
 Food Starch Market | 2026-2036
Food Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Food Starch Market Analysis
Ingredient customization revenue is rewriting profit distribution across the food starch value chain. Cargill, Incorporated leverages its global agricultural sourcing network to secure consistent raw material supply. Roquette Frères anchors its position through pea and potato starch specialization in European markets. Ingredion Inc. competes by extending its clean-label ingredient portfolio for reformulation projects.
Food starch comprises carbohydrate polymers extracted from botanical sources such as corn, wheat, potato, tapioca, and rice, typically containing 20-25% amylose and 75-80% amylopectin by weight, with gelatinization temperatures ranging from 55°C to 70°C depending on botanical origin; manufacturers modify these starches through physical, chemical, or enzymatic treatments to control viscosity, stability, and freeze-thaw performance for industrial food processing. Modified starch commands the dominant margin pool due to its functional superiority in dairy products and sauces, while native starch growth concentrates among organic and clean-label product lines targeting health-conscious consumers. Specialty starch applications in confectionery represent the fastest-expanding segment as confectioners seek texture optimization without synthetic additives.
Food starch producers navigate FDA food additive regulations alongside EFSA purity criteria and ISO 22000 certification requirements for international market access. The EU Green Deal's sustainable sourcing mandates are reshaping procurement criteria for European food manufacturers. China's GB standards and SAMR oversight govern import specifications for modified starch entering Asian processing channels. Stakeholders must monitor evolving clean-label certification thresholds and regional carbon accounting rules to maintain formulation competitiveness.
Market Dynamics
The EU Green Deal's sustainable sourcing mandates are compressing formulation timelines for European food manufacturers while simultaneously opening procurement windows for certified clean-label suppliers. Native starch adoption is accelerating as snack makers reformulate to meet retailer certification thresholds.
Growth Catalysts
- Clean-label certification thresholds:Retailer mandates for simplified ingredient panels are pulling native starch into organic snack and bakery lines. SAMR oversight of modified starch imports is redirecting Chinese processors toward domestically certified clean-label alternatives.
- EU Green Deal procurement criteria:European manufacturers must demonstrate carbon-accounted supply chains by 2030, favoring regional pea and potato starch over transatlantic corn derivatives. This is reshaping supplier qualification protocols.
- Texture optimization in confectionery:Confectioners are replacing synthetic hydrocolloids with specialty starches to achieve clean-label status without sacrificing mouthfeel. This application segment is expanding fastest among all food starch categories.
Market Restraints
- Corn price volatility:Input cost swings for the dominant North American feedstock compress margin stability for unhedged processors. Drought cycles in the US Corn Belt amplify quarterly earnings unpredictability.
- Modified starch technical ceilings:Freeze-thaw stability gaps persist in high-moisture dairy applications, limiting full substitution for synthetic stabilizers. Enzymatic treatment costs for performance-grade variants remain prohibitive for mid-tier processors.
- EFSA purity criteria friction:Residual chemical limits in acetylated and oxidized starches create batch rejection risk for exporters serving European markets. Testing protocol harmonization between FDA and EFSA remains incomplete.
Strategic Opportunities
- Pea starch underpenetration in Southeast Asia:Thailand and Vietnam processed food hubs currently rely on tapioca and rice derivatives. European pea specialists can capture share as clean-label demand crosses from premium into mass-market segments.
- Dual carbon goals alignment in China:GB standards evolution is creating certified pathways for low-carbon modified starch. Domestic producers securing MEE environmental compliance ratings will access preferential procurement from state-owned food conglomerates.
- Enzymatic modification convergence:Combining precision fermentation with conventional wet-milling is reducing chemical treatment intensity. This hybrid process opens premium positioning for starch meeting both organic and performance specifications.
Industry Challenges
- ISO 22000 certification timelines:Small and mid-cap mills face 18-24 month compliance windows to access international buyer approved vendor lists. Audit backlog at accredited bodies is extending market entry schedules.
- Legacy ERP integration with carbon accounting modules:Real-time supply chain traceability requirements demand IT infrastructure upgrades that strain capital allocation for family-owned processing operations.
- Specialized food polymer chemist scarcity:Formulation science expertise spanning both native functionality and modification chemistry concentrates at a handful of technical universities. Talent competition intensifies as clean-label R&D budgets expand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Starch Market |
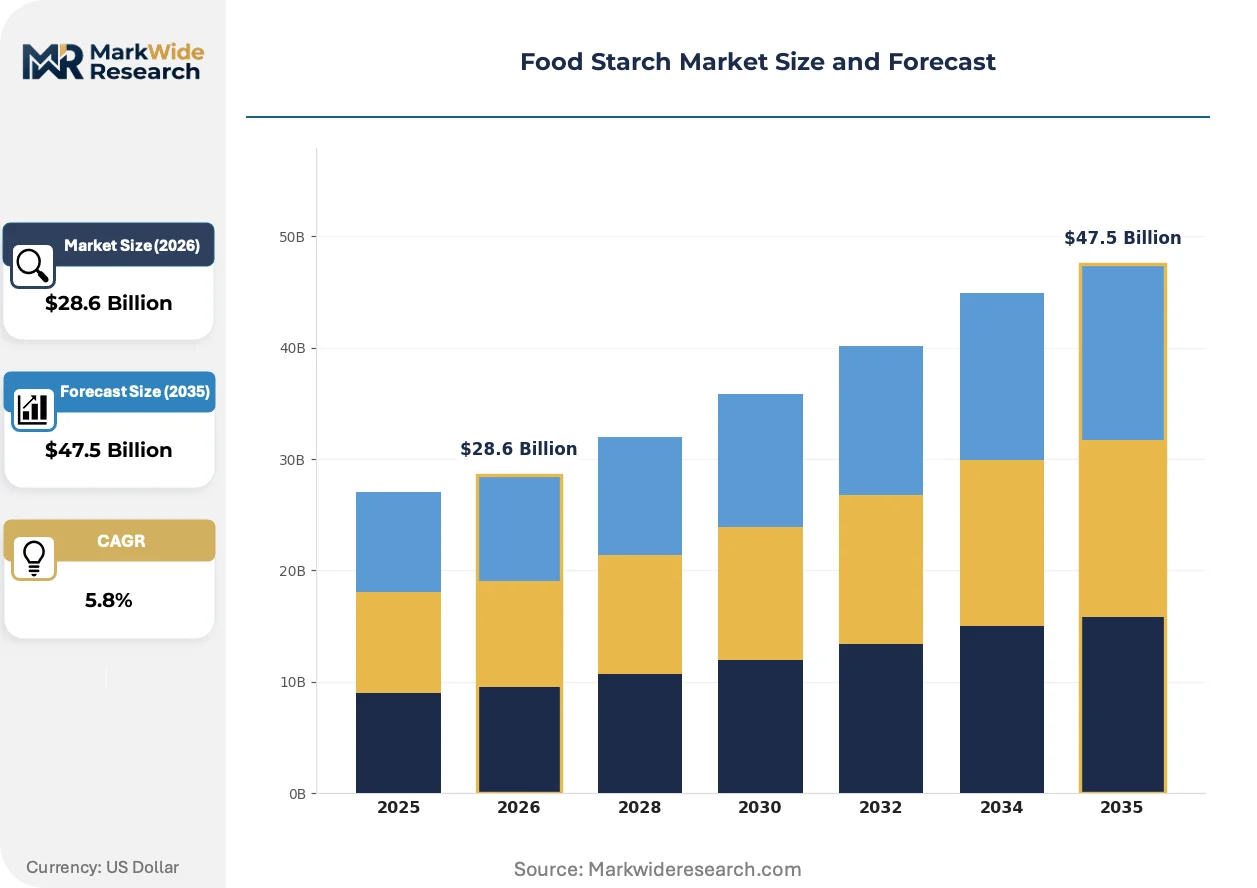
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Organic Starch, Specialty Starch Application: Baking, Dairy Products, Confectionery, Sauces End User: Food Manufacturers, Beverage Producers, Snack Makers, Confectioners Form: Powder, Granule, Liquid, Gel |
| Companies Covered | Roquette Frères, AGRANA Beteiligungs-AG, Cargill, Incorporated, Grain Processing Corporation, Tereos, Ingredion Inc., Tate & Lyle Plc, Emsland Group, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Starch Market Emerging Trajectories
Physical modification techniques are overtaking chemical processes as the preferred pathway to clean-label starch performance. This shift is compressing capital requirements for entry-level producers while fragmenting the technology supplier base.
High-pressure processing and annealing methods are achieving viscosity and stability profiles previously requiring chemical cross-linking. Mid-sized European bakery ingredient suppliers are adopting these systems at accelerating pace. Thermal-physical modification is rendering obsolete the cost and regulatory burden of acetylation and phosphorylation for mid-performance applications.
REACH authorization requirements for residual acetic anhydride are tightening batch documentation burdens for chemically modified starch entering European dairy and sauce channels. Food manufacturers are pre-emptively reformulating to avoid supply interruption from authorization sunset dates. The infant nutrition segment is responding fastest, with several major brands already completing transitions to physically processed alternatives.
Direct sourcing contracts between snack manufacturers and regional starch mills are displacing traditional ingredient distributor networks. Large branded snack producers in the US and Germany are building approved supplier lists that bypass national distributors entirely. This channel compression is most visible in organic and non-GMO product lines where traceability documentation requirements exceed distributor capabilities.
Food Starch Market Segmentation
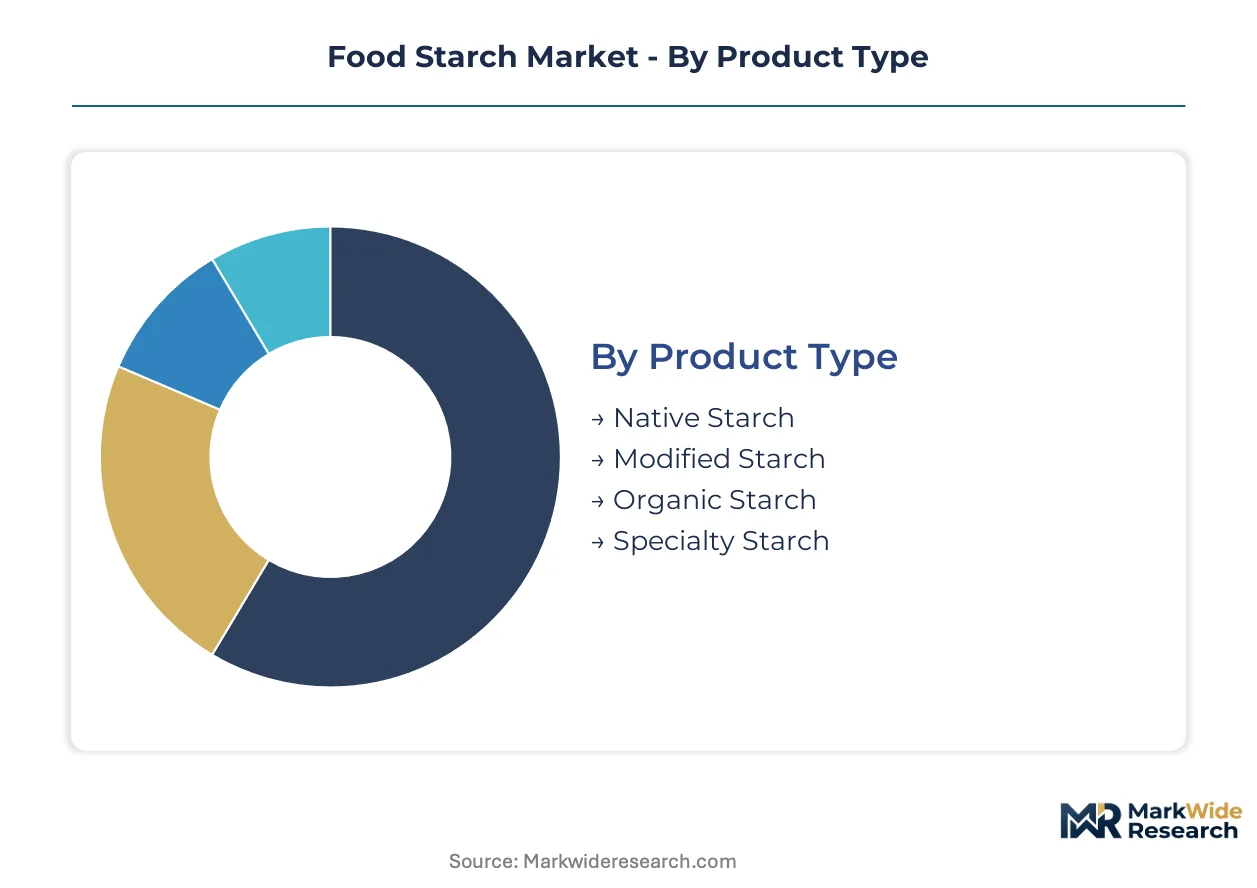
Food starch segmentation reflects divergent technical requirements across processing applications and certification tiers. Manufacturers configure product portfolios around functional performance, clean-label compliance, and supply chain traceability demands.
Product Type:
Cost tier determines margin structure and capital intensity across starch processing categories.
- Native Starch:Extracted through wet-milling without chemical alteration, retaining natural amylose-amylopectin ratios. Snack makers in Germany and the US are pulling native starch into organic lines to meet retailer certification thresholds.
- Modified Starch:Physically, chemically, or enzymatically treated to control viscosity, freeze-thaw stability, and gelatinization profiles. Dairy processors in Southeast Asia concentrate demand here for sauce and dessert applications requiring thermal stability.
- Organic Starch:Certified organic variants sourced from non-GMO botanicals with full farm-to-facility traceability. European baby food manufacturers specify these for infant nutrition formulations.
- Specialty Starch:High-performance grades including pregelatinized and cold-water-swelling variants for instant applications. Confectioners leverage these for texture optimization without synthetic hydrocolloids.
Modified starch commands the established base. The steepest expansion runs through specialty starch.
Application:
Volume concentration varies sharply by processing temperature requirements and shelf-life demands.
- Baking:Starch functions as crumb softener, moisture retainer, and anti-staling agent in bread and pastry systems. Industrial bakeries in France and Italy specify native and modified wheat derivatives for clean-label positioning.
- Dairy Products:Yogurt, cream, and processed cheese applications demand freeze-thaw stable starches with shear resistance. High-moisture dairy segments in China face technical substitution ceilings where synthetic stabilizers retain performance advantages.
- Confectionery:Gelling, glazing, and texture-modifying functions in candies and chewing gum. Japanese and Swiss confectioners are expanding specialty starch trials for clean-label reformulations.
- Sauces:Viscosity control and emulsion stability in dressings, gravies, and ready-meal components. US and UK sauce manufacturers prioritize modified starch with acid stability for refrigerated and shelf-stable lines.
Baking anchors volume demand. Confectionery is climbing the fastest as clean-label pressure intensifies.
End User:
Customer type shapes procurement scale, technical service requirements, and certification documentation intensity.
- Food Manufacturers:Large-scale processors of prepared meals, meat alternatives, and bakery goods. These buyers negotiate direct sourcing contracts bypassing traditional distributor networks for organic and non-GMO lines.
- Beverage Producers:Starch functions as clouding agent, mouthfeel modifier, and stabilizer in juice, dairy alternatives, and functional drinks. Brazilian and Thai beverage processors drive demand for cold-water-soluble variants.
- Snack Makers:Extruded and sheeted snack applications require specific expansion and crunch profiles. Clean-label certification thresholds are accelerating native starch adoption among US and German branded snack producers.
- Confectioners:Specialized texture and shelf-life requirements distinguish this segment. European confectioners are completing transitions to physically processed starches ahead of REACH authorization sunset dates.
Food manufacturers represent the deepest volume base. Snack makers are gaining share fastest on clean-label momentum.
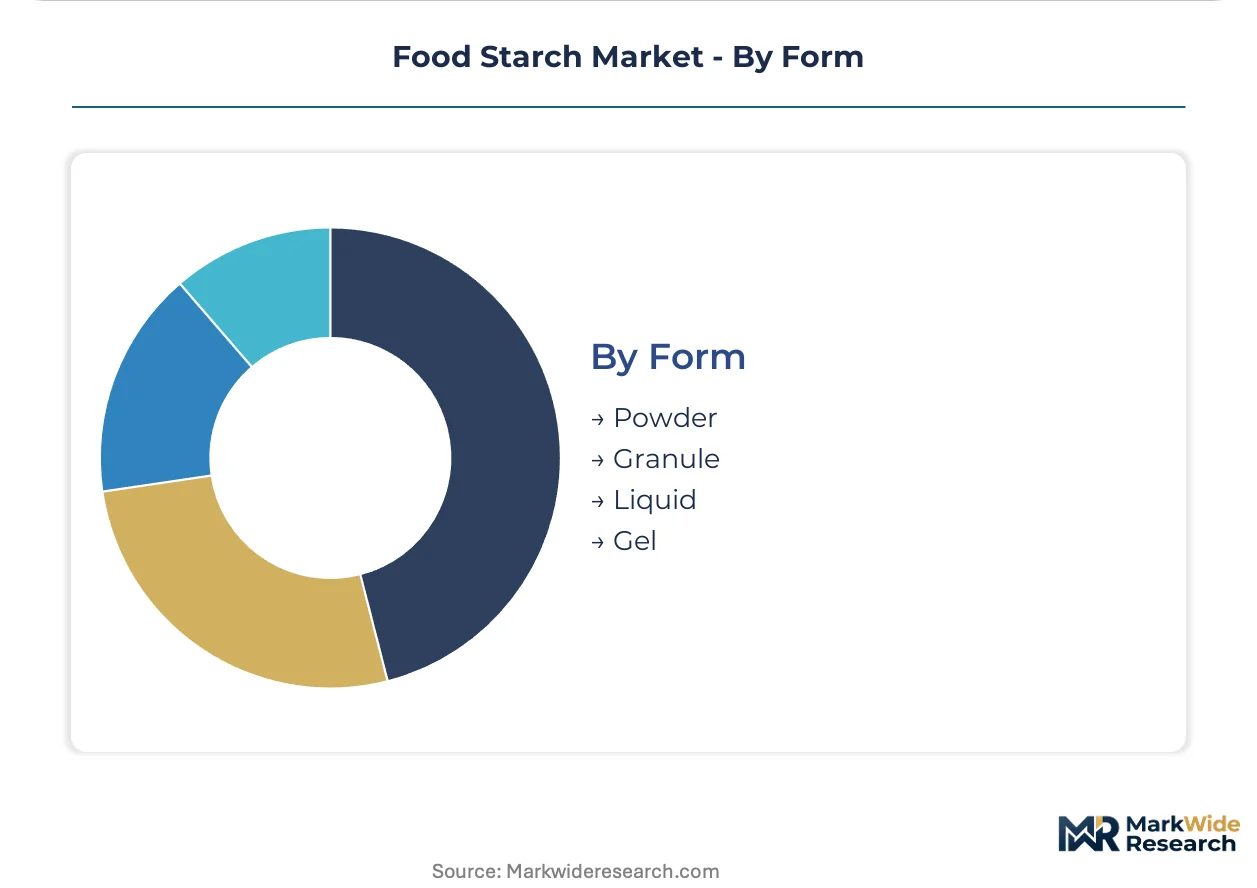
Form:
Supply concentration and logistics economics vary by physical state and handling requirements.
- Powder:Standard milled starch with bulk density optimized for pneumatic conveying and dry blending. Powder dominates high-volume baking and sauce applications where dusting and flowability are critical.
- Granule:Agglomerated or coarse-milled variants reducing dust generation and improving dispersibility. Beverage producers in Japan and South Korea specify granule forms for clean dissolving in cold liquids.
- Liquid:Pre-hydrated starch suspensions eliminating hydration steps in continuous processing. US and Mexican sauce manufacturers adopt liquid starch for reduced batch cycle times.
- Gel:Fully gelatinized and cooled starch systems for instant functionality. Ready-meal processors in the UK and Netherlands leverage gel forms for microwaveable product consistency.
Powder retains the volume anchor. Liquid is expanding most quickly on continuous processing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across food starch demand centers. German and French buyers absorb premium clean-label premiums with minimal volume contraction. Southeast Asian processors remain acutely sensitive to tapioca and rice starch price swings.
United States
Snack manufacturers in Chicago and Minneapolis drive native starch procurement for organic product lines. FDA food additive regulations govern modified starch specifications for dairy and sauce applications. The Corn Belt concentration in Iowa and Illinois supplies wet-milling feedstock, though drought cycles amplify input cost volatility for unhedged processors.
Germany
Industrial bakeries in Munich and Stuttgart specify wheat-derived native starches for clean-label positioning. The EU Green Deal's sustainable sourcing mandates compress formulation timelines while favoring regional pea and potato starch over transatlantic corn derivatives. The Emsland region anchors potato starch specialization with integrated processing clusters.
China
Domestic sauce and dairy processors in Shandong and Jiangsu provinces drive modified starch demand for high-moisture applications. SAMR oversight and evolving GB standards create certified pathways for low-carbon modified starch with MEE environmental compliance ratings. State-owned food conglomerates increasingly specify domestic clean-label alternatives over imports.
Thailand
Processed food hubs in Bangkok and surrounding provinces concentrate tapioca starch demand for confectionery and beverage applications. Clean-label certification thresholds are crossing from premium into mass-market segments, opening procurement windows for European pea starch specialists. The country's tapioca wet-milling infrastructure faces margin pressure from European sustainability audits.
Brazil
Beverage producers in São Paulo and Minas Gerais specify cold-water-soluble starch variants for juice and dairy alternative applications. ANVISA import specifications govern modified starch quality thresholds for industrial processing channels. The country's cassava starch sector competes with Asian tapioca on cost while lagging on clean-label certification infrastructure.
Food Starch Market Vendor Landscape
Agribusiness conglomerates and botanical specialists split the market into distinct capability territories. Consolidation pressure runs highest in North American corn starch, while European pea and potato segments retain specialist fragmentation. Three archetypes dominate: integrated agribusinesses with captive raw material supply, regional botanical specialists with crop-specific expertise, and diversified ingredient platforms with reformulation service capabilities. Capacity expansion in enzymatic modification and backward integration into specialty crop contracting represent the dominant competitive vectors.
Among integrated agribusinesses, Cargill, Incorporated and Archer Daniels Midland Company anchor the North American corn starch complex with upstream control over agricultural supply networks. Roquette Frères exemplifies the European botanical specialist archetype, occupying a position centered on pea and potato starch crop expertise. Ingredion Inc. sits within the diversified ingredient platform tier, representing the service-intensive model built around clean-label reformulation partnerships with food manufacturers.
| Leading Market Players |
|---|
| Roquette Frères |
| AGRANA Beteiligungs-AG |
| Cargill, Incorporated |
| Grain Processing Corporation |
| Tereos |
| Ingredion Inc. |
| Tate & Lyle Plc |
| Emsland Group |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp barge corridor shapes European starch economics, with freight cost swings amplifying margin pressure for processors dependent on Black Sea corn or Southeast Asian tapioca. This logistics chokepoint concentrates pricing power among integrated agribusinesses with captive port terminal access while forcing smaller mills toward regional botanical alternatives.
Pricing Analysis
After-sales technical service contracts drive lifetime value for specialty starch suppliers serving reformulation-intensive confectioners and dairy processors. Three-tier pricing structure across premium clean-label, standard modified, and economy native grades reflects certification intensity and functional performance rather than raw material cost alone. Price differentiation hinges on EU organic certification and ISO 22000 compliance tier. Pricing pressure stems from corn price volatility in the US Corn Belt compressing unhedged processor margins. Beverage producers in Brazil and Thailand exhibit highest price sensitivity, while German industrial bakeries absorb premium clean-label premiums with minimal volume contraction.
Supply Chain Analysis
Contract manufacturing concentration sits with integrated wet-millers in Iowa and Illinois, Emsland Group facilities in Germany, and Thai tapioca processors in Bangkok provinces. Geographic supply concentrates in the United States, Germany, and Thailand for corn, potato, and tapioca derivatives respectively. Raw material dependencies rest on corn from the Corn Belt, cassava from Mekong Delta plantations, and peas from European contract farming networks. Single-source vulnerability runs through drought-exposed US corn supply. Distribution runs through direct sourcing contracts displacing traditional ingredient distributors for organic and non-GMO lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized food polymer chemists capable of bridging native functionality and enzymatic modification chemistry remain scarce across technical universities, constraining clean-label R&D velocity for mid-cap processors. This talent bottleneck favors incumbents with captive formulation science teams.
For Market Incumbents: Build certification moats around EU Green Deal carbon-accounted supply chains and REACH-compliant physical modification capabilities. Defensive moves center on backward integration into specialty crop contracting in the Emsland region and capacity addition in enzymatic modification to preempt substitution by synthetic stabilizers. The threat of precision fermentation-derived alternatives intensifies as precision fermentation costs decline. For New Entrants and Emerging Players: Southeast Asian pea starch underpenetration offers white-space capture as Thai and Vietnamese processed food hubs transition clean-label demand from premium to mass-market segments. Target confectionery texture optimization applications where specialty starch trials are expanding fastest among Japanese and Swiss manufacturers. A go-to-market angle anchored in MEE environmental compliance ratings unlocks preferential procurement from Chinese state-owned food conglomerates. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates divesting non-core starch assets to refocus on protein and oilseed platforms. Long-term viability across the analysis window favors botanical specialists with crop-specific expertise over diversified commodity processors. The acquisition archetype is European pea and potato starch specialists with integrated processing clusters. The signal to watch is REACH authorization sunset dates accelerating reformulation timelines for chemically modified starch in infant nutrition.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Capacity Expansion | Hybrid physical-enzymatic processes reduce chemical treatment intensity for organic-performance convergence. |
| Backward Integration into Specialty Crop Contracting | Captive pea and potato supply secures EU Green Deal carbon-accounting compliance for European manufacturers. |
| Clean-Label Certification Investment | Organic and non-GMO credentials unlock direct sourcing contracts bypassing traditional distributor networks. |
| Regional Production Footprint in Southeast Asia | Thailand and Vietnam proximity captures clean-label demand crossing from premium into mass-market segments. |
| Technical Service Partnership with Confectioners | Texture optimization expertise without synthetic hydrocolloids drives fastest-expanding specialty starch applications. |
Methodological Framework
Two parallel data streams informed the analysis: primary engagement with starch procurement managers at European bakery and dairy processors, technical directors at enzymatic modification facilities, and sustainability officers at agribusiness conglomerates; and secondary validation through EFSA purity criteria documentation, SAMR GB standards filings, EU Green Deal procurement guidelines, and trade flow data from corn and tapioca customs records. Bottom-up volume modeling from application-level demand and top-down value reconciliation from producer revenue disclosures enabled triangulation.
Forecast inputs considered product type segmentation across native, modified, organic, and specialty grades; application intensity across baking, dairy, confectionery, and sauces; and end-user procurement scale from food manufacturers through snack makers. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Industry-specific inputs included clean-label certification threshold evolution and REACH authorization timeline impacts on chemically modified starch substitution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation startups or accelerated EU carbon border adjustments would shift outcomes. Quarterly review of corn futures volatility, REACH authorization sunset progress, and clean-label certification adoption rates at major retailers is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Acetylated Distarch Phosphate Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
Food Grade Butyric Acid Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market
Food Additives and Ingredients
Cetyl Palmitate Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Natural Food Preservatives Market