
 Asia Pacific Food Acidulants Market | 2026-2036
Asia Pacific Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Food Acidulants Market Outlook
Food acidulant distribution through regional chemical traders is fragmenting as direct procurement contracts between manufacturers and beverage multinationals multiply. Weifang Ensign Industry Co., Ltd dominates citric acid supply chains across coastal China through captive fermentation capacity. Jungbunzlauer Suisse AG differentiates via bio-based acidulant platforms that sustain premium positioning in clean-label formulations. Cargill, Incorporated leverages its bulk logistics network to control cost-competitive lactic acid flows into Southeast Asian dairy processors.
Food acidulants comprise organic and inorganic compounds—principally citric, lactic, malic, and phosphoric acids—introduced to lower pH, enhance microbial stability, and modify flavor profiles in processed foods, typically dosed between 0.1% and 1.5% by weight. Citric acid remains the volume anchor due to its versatility across beverages and confectionery, though malic acid captures expanding share in sour confectionery and sports drinks where prolonged tartness delivers sensory differentiation. Application demand in beverages leads absolute consumption, while bakery products present concentrated margin pools for acidulant blends that replace chemical preservatives in extended-shelf-life goods.
China's SAMR enforces GB 1886 food additive standards that mandate heavy metal limits and impurity thresholds for acidulants sold domestically, effectively filtering smaller exporters from compliance-intensive segments. India's FSSAI parallelly requires additive labeling disclosures that push food manufacturers toward certified acidulant grades traceable through supply chain documentation. Australia's TGA-aligned import inspection protocols for food chemicals add another compliance layer for acidulants entering Oceania. Stakeholders must monitor regulatory divergence between national standards regimes and pre-empt certification investments before bilateral trade agreements reshape market access conditions.
Market Dynamics
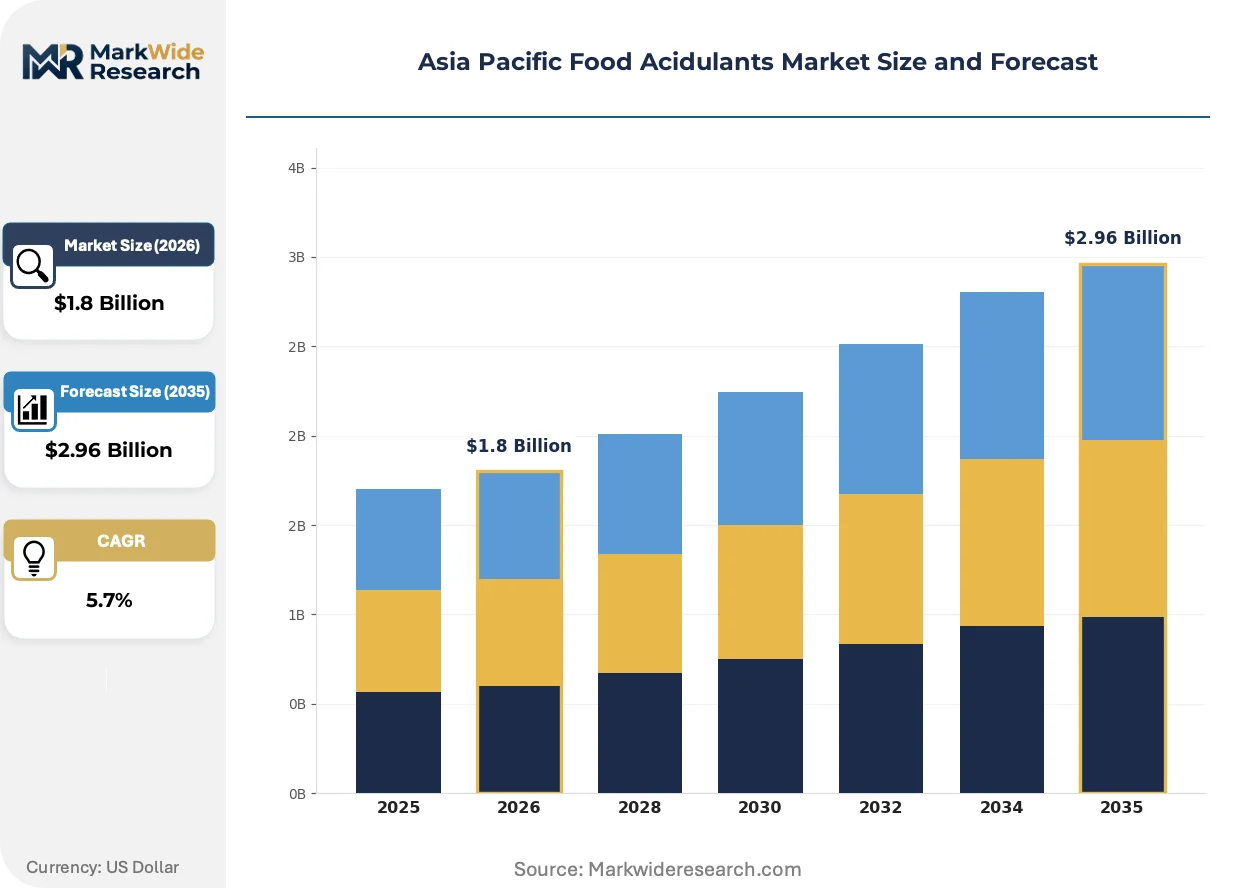
Direct procurement contracts between beverage multinationals and acidulant manufacturers are fragmenting traditional chemical trader networks across Southeast Asia. China's SAMR enforcement of GB 1886 standards and India's FSSAI labeling mandates are simultaneously raising compliance barriers while filtering sub-scale suppliers from premium segments.
Growth Catalysts
- Clean-label formulation mandates:India's FSSAI disclosure requirements push food manufacturers toward certified acidulant grades with full supply chain traceability, accelerating demand for bio-based platforms.
- Functional beverage expansion:Sports drink producers across Thailand and Vietnam are expanding malic acid procurement for prolonged tartness profiles that differentiate sour confectionery and hydration products.
- Dual carbon policy alignment:China's MEE enforcement of dual carbon goals drives fermentation capacity upgrades toward lower-carbon citric acid production methods.
Market Restraints
- Feedstock cost volatility:Molasses and corn starch price swings directly compress fermentation margins for citric and lactic acid producers operating across coastal China.
- Supply concentration risk:Captive fermentation capacity controlled by dominant coastal Chinese manufacturers creates procurement vulnerability for Southeast Asian dairy processors dependent on bulk lactic acid flows.
- Regulatory friction:Australia's TGA-aligned import inspection protocols add compliance layers and inspection delays for acidulants entering Oceania markets.
Strategic Opportunities
- Underpenetrated processed food corridors:Maharashtra and Gujarat in India present concentrated demand pools for acidulant blends replacing chemical preservatives in extended-shelf-life bakery goods.
- Regulatory tailwind from PLI schemes:India's PLI scheme for food processing incentivizes domestic acidulant manufacturing investments that reduce import dependency.
- Distribution disintermediation:Direct manufacturer-to-beverage-procurement contracts bypass regional chemical traders, capturing margin compression as channel efficiency gains.
Industry Challenges
- Certification timeline compression:GB 1886 heavy metal limit compliance and FSSAI additive documentation requirements demand accelerated laboratory validation cycles that strain mid-scale exporters.
- Legacy system integration:Supply chain documentation systems for traceable acidulant grades must interface with existing ERP platforms at Indian and Southeast Asian food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Food Acidulants Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Malic Acid, Phosphoric Acid Application: Beverages, Dairy Products, Bakery Products, Confectionery End User: Food Manufacturers, Beverage Producers, Restaurants, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Weifang Ensign Industry Co., Ltd, Cargill, Incorporated, Tate & Lyle, Archer Daniels Midland Company, Jungbunzlauer Suisse AG, Corbion, Brenntag, Bartek Ingredients Inc., Hawkins Watts Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Food Acidulants Market Strategic Shifts
Bio-based acidulant platforms and precision fermentation technologies are compressing traditional chemical synthesis pathways while regulatory disclosure mandates reshape procurement specifications across Asia Pacific beverage and processed food sectors.
Fermentation-derived acidulant production is migrating from conventional batch processing toward continuous bioreactor systems that reduce energy intensity and water consumption. Southeast Asian dairy processors and functional drink manufacturers are adopting these platforms at moderate pace as carbon accounting pressures intensify. This technology migration from chemical synthesis is enabling premium positioning for suppliers that can document bio-based content through supply chain certification.
China's SAMR enforcement of GB 1886 food additive standards mandates specific heavy metal limits and impurity thresholds that filter smaller exporters from compliance-intensive market segments. Industrial consequence includes accelerated consolidation toward manufacturers with captive analytical laboratories and regulatory affairs capabilities. Premium beverage and infant nutrition segments across China and Southeast Asia are responding by locking in multi-year supply contracts with certified-grade suppliers.
Direct procurement contracts between acidulant manufacturers and beverage multinationals are displacing traditional regional chemical trader networks across Southeast Asia. Regional chemical distributors in Thailand and Indonesia face margin compression as procurement teams at multinational beverage headquarters negotiate volume commitments directly with fermentation plant operators. This channel shift is most visible in Vietnam and the Philippines where greenfield beverage production facilities are being commissioned with integrated supplier qualification programs.
Asia Pacific Food Acidulants Market Segmentation
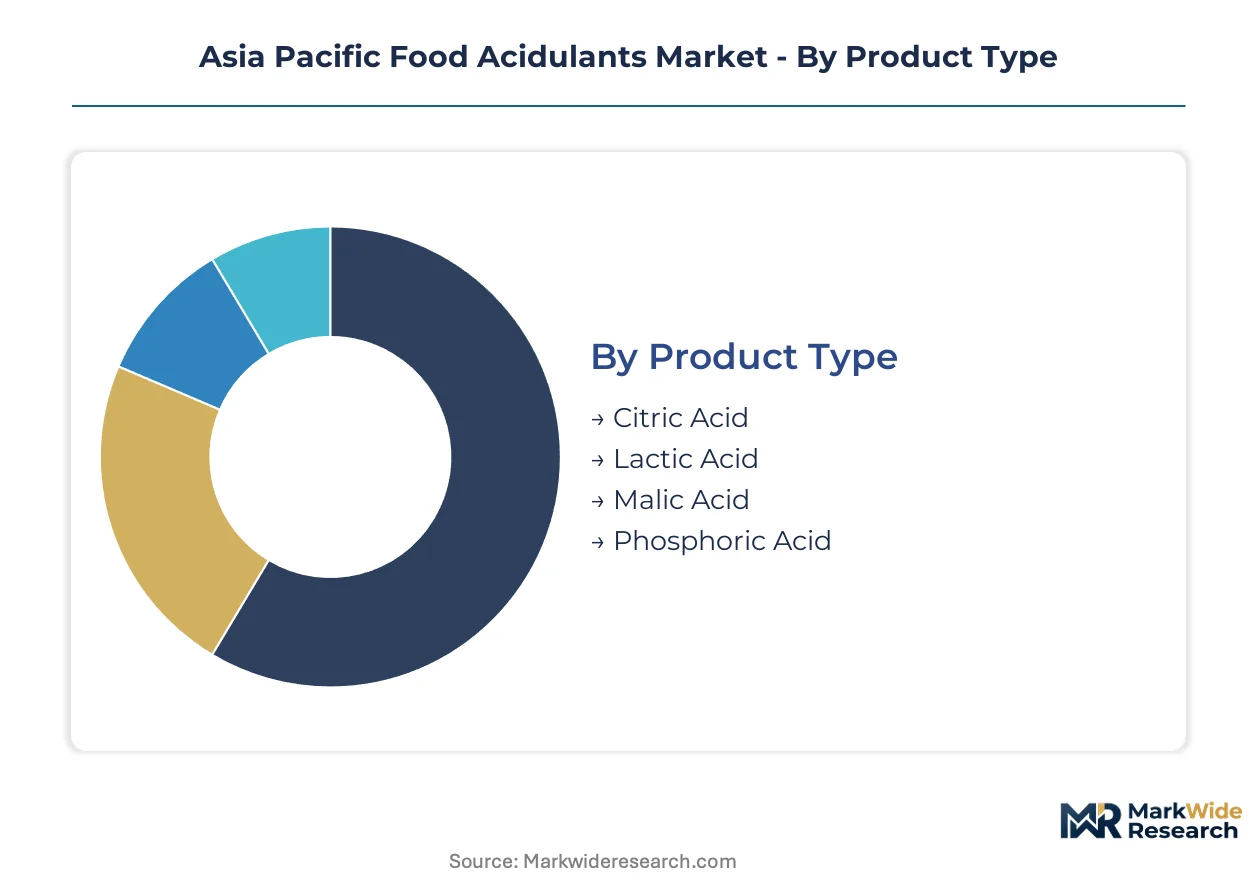
Acidulant procurement patterns diverge sharply across product chemistry, application requirements, and channel economics. Segmentation reveals where fermentation-scale advantages translate into pricing power versus where formulation flexibility commands premium positioning.
Product Type:
Mature fermentation platforms anchor volume supply while emerging bio-based alternatives reshape premium tier procurement specifications across Asia Pacific beverage and dairy sectors.
- Citric Acid:Derived from Aspergillus niger fermentation of molasses or corn starch, this tricarboxylic acid delivers pH reduction alongside chelating functionality for metal ion control. Demand concentrates in China's coastal manufacturing clusters where Weifang Ensign Industry Co., Ltd operates captive fermentation capacity serving Coca-Cola and PepsiCo bottling networks; GB 1886 heavy metal compliance filters smaller exporters from infant nutrition and premium beverage segments.
- Lactic Acid:Produced through bacterial fermentation of carbohydrates, this alpha-hydroxy acid provides milder acidity with antimicrobial properties suited for dairy preservation. Cargill's bulk logistics network controls cost-competitive flows into Southeast Asian yogurt and cheese processors; dual carbon policy enforcement in China's MEE framework drives fermentation upgrades toward lower-carbon production methods.
- Malic Acid:Synthesized via hydration of maleic anhydride or fermentation-derived, this dicarboxylic acid delivers prolonged tartness profiles. Sports drink manufacturers across Thailand and Vietnam expand procurement for sensory differentiation in sour confectionery.
- Phosphoric Acid:Inorganic acid produced through wet process or thermal routes, delivering strong acidity at lower dosage rates. Cola-type beverage producers in Indonesia and Philippines maintain concentrated demand for this cost-efficient pH modifier.
Citric acid retains volume leadership across Asia Pacific procurement; malic acid holds the steepest expansion curve driven by functional beverage differentiation requirements.
Application:
Cost tier stratification separates commodity-scale beverage dosing from margin-rich bakery preservation where acidulant blends displace chemical alternatives.
- Beverages:Carbonated soft drinks, fruit juices, and functional hydration products represent the dominant acidulant consumption endpoint. China's SAMR-enforced GB standards and India's FSSAI labeling mandates simultaneously elevate compliance barriers while concentrating procurement toward certified-grade suppliers with full supply chain traceability.
- Bakery Products:Extended-shelf-life bread, cakes, and pastries utilize acidulant blends to replace calcium propionate and other chemical preservatives. Maharashtra and Gujarat processed food corridors present concentrated demand pools as PLI scheme incentives accelerate domestic manufacturing investment.
- Dairy Products:Yogurt, cheese, and fermented milk applications leverage lactic acid for pH control and microbial stability. Southeast Asian processors face procurement vulnerability from supply concentration in coastal Chinese fermentation capacity.
- Confectionery:Sour candies and gummies employ malic acid for prolonged tartness intensity. Clean-label formulation mandates across India's FSSAI jurisdiction push manufacturers toward bio-based acidulant platforms with documented supply chain certification.
Beverage applications dominate absolute acidulant consumption; bakery products present the most rapid margin expansion opportunity as preservative replacement accelerates.
End User:
Customer type fragmentation creates distinct procurement specifications between multinational scale and fragmented foodservice demand.
- Food Manufacturers:Integrated processed food producers operating extended-shelf-life production lines. Direct procurement contracts with acidulant manufacturers are displacing traditional regional chemical trader networks across Southeast Asia.
- Beverage Producers:Multinational bottlers and regional functional drink specialists. Procurement teams at headquarters negotiate volume commitments directly with fermentation plant operators, bypassing Indonesian and Thai chemical distributors.
- Restaurants:Commercial foodservice operations utilizing acidulants for marinade, sauce, and preservation applications. Fragmented demand aggregates through specialty store and online retail channels.
- Households:Consumer-packaged acidulants for home food preservation and cooking. Online retail penetration expands fastest in India's tier-2 cities where specialty store access remains limited.
Food manufacturers anchor volume contracting; beverage producers drive the fastest channel restructuring through direct manufacturer relationships.
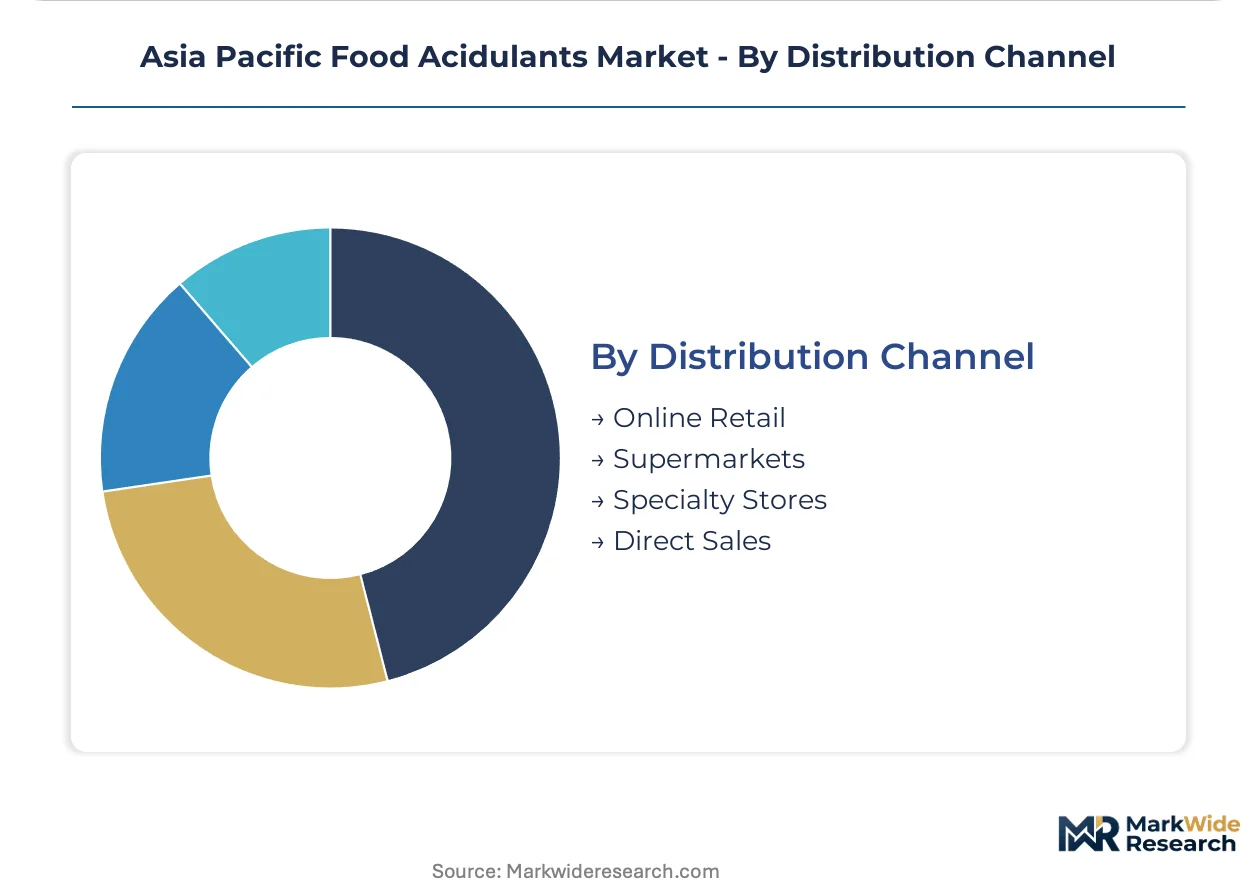
Distribution Channel:
Supply concentration in coastal Chinese manufacturing clusters dictates logistics economics across channel alternatives.
- Direct Sales:Volume contracts between fermentation plant operators and multinational beverage or dairy processors. Vietnam and Philippines greenfield beverage facilities commission with integrated supplier qualification programs that lock in multi-year supply commitments.
- Online Retail:E-commerce platforms serving small-scale food manufacturers and household consumers. India's digital marketplace infrastructure expands access to certified acidulant grades in Gujarat and Maharashtra industrial zones.
- Supermarkets:Mass retail distribution for consumer-packaged acidulants and small-batch food processor procurement. Australia's TGA-aligned import inspection protocols add compliance layers affecting shelf-stock reliability.
- Specialty Stores:Chemical supply houses and food ingredient distributors serving mid-scale manufacturers. Regional chemical traders in Thailand and Indonesia face margin compression as direct procurement multiplies.
Direct sales capture the dominant value flow; online retail climbs fastest as small-producer digital procurement accelerates across India and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for food processing and China's dual carbon policy enforcement are redirecting capital toward domestic acidulant manufacturing capacity across the region.
China
Weifang Ensign Industry Co., Ltd operates captive fermentation capacity serving Coca-Cola and PepsiCo bottling networks along coastal manufacturing clusters. SAMR enforcement of GB 1886 standards mandates heavy metal limits and impurity thresholds that filter smaller exporters from infant nutrition segments. Yangtze River Delta fermentation plants are upgrading toward continuous bioreactor systems that reduce energy intensity under MEE dual carbon compliance.
India
Maharashtra and Gujarat processed food corridors present concentrated demand pools for acidulant blends replacing chemical preservatives in extended-shelf-life bakery goods. FSSAI labeling disclosure requirements push food manufacturers toward certified acidulant grades with full supply chain traceability. PLI scheme incentives are accelerating domestic manufacturing investments that reduce import dependency for lactic and citric acid procurement.
Thailand
Sports drink producers are expanding malic acid procurement for prolonged tartness profiles that differentiate sour confectionery and functional hydration products. The country's national food additive regulator maintains alignment with ASEAN harmonized standards while enforcing import inspection protocols. Bangkok-based beverage manufacturing clusters are commissioning greenfield facilities with integrated supplier qualification programs that lock in multi-year supply commitments.
Vietnam
Greenfield beverage production facilities are being commissioned with direct procurement contracts that bypass traditional regional chemical trader networks. The government's food safety authority is tightening additive documentation requirements that elevate compliance barriers for uncertified imports. Ho Chi Minh City industrial zones are attracting fermentation plant operators seeking proximity to Southeast Asian dairy processors.
Australia
TGA-aligned import inspection protocols for food chemicals add compliance layers and inspection delays affecting acidulant shelf-stock reliability in supermarket channels. Clean-label formulation mandates from major retailers are pushing food manufacturers toward bio-based acidulant platforms with documented supply chain certification. Sydney and Melbourne food manufacturing hubs are consolidating procurement toward certified-grade suppliers with captive analytical laboratory capabilities.
Asia Pacific Food Acidulants Market Competitive Environment
On the supply side, the industry is consolidating around fermentation-scale advantages and captive regulatory affairs capabilities that filter sub-scale participants from premium segments. Coastal Chinese manufacturers control volume supply through molasses and corn starch fermentation platforms, while European specialists occupy premium positioning via bio-based certification. Three archetypes dominate: scale-driven fermentation operators, bio-based platform specialists, and bulk logistics integrators. Capacity expansion and direct procurement contracting represent the dominant competitive moves reshaping channel economics.
Within the scale-driven tier, Weifang Ensign Industry Co., Ltd anchors citric acid supply chains through Chinese coastal manufacturing presence. Jungbunzlauer Suisse AG exemplifies the bio-based specialist archetype with Swiss-registered positioning that supports premium-tier procurement specifications. Cargill, Incorporated represents bulk logistics integration, leveraging North American-originated corporate structure to control cost-competitive acidulant flows into Southeast Asian dairy processing corridors.
| Leading Market Players |
|---|
| Weifang Ensign Industry Co., Ltd |
| Cargill, Incorporated |
| Tate & Lyle |
| Archer Daniels Midland Company |
| Jungbunzlauer Suisse AG |
| Corbion |
| Brenntag |
| Bartek Ingredients Inc. |
| Hawkins Watts Limited |
| Others |
Value Chain & Pricing Dynamics
Feedstock cost volatility in molasses and corn starch markets compresses fermentation margins while simultaneously widening spreads between certified-grade and commodity-tier acidulant pricing across Asia Pacific procurement channels. China's SAMR enforcement of GB 1886 heavy metal limits and India's FSSAI labeling mandates create dual regulatory chokepoints that filter sub-scale suppliers from premium segments while concentrating pricing power among coastal Chinese manufacturers with captive analytical capabilities.
Pricing Analysis
Certification level creates the primary spread between premium GB 1886-compliant grades and economy-tier imports across Asia Pacific acidulant procurement. Three-tier pricing structure across premium certified, standard industrial, and economy unbranded levels reflects compliance investment differentials rather than chemical specification alone. Pricing pressure stems from feedstock volatility in corn starch and molasses markets that compresses fermentation margins for citric and lactic acid producers. Food manufacturers in Maharashtra and Gujarat industrial corridors exhibit highest price sensitivity due to PLI scheme margin pressures, while infant nutrition segment buyers absorb premium certification costs without volume reduction.
Supply Chain Analysis
Molasses and corn starch feedstock dependencies anchor supply concentration in China's coastal fermentation clusters, particularly Weifang and Yangtze River Delta manufacturing zones. Raw material sourcing draws from domestic Chinese corn processing networks and imported Southeast Asian molasses flows, with energy inputs tethered to regional grid carbon intensity under MEE dual carbon enforcement. Single-source vulnerability concentrates in coastal Chinese citric acid capacity controlled by dominant fermentation operators serving Coca-Cola and PepsiCo bottling networks. Distribution runs through direct manufacturer-to-beverage-procurement contracts that displace traditional Thai and Indonesian chemical trader networks, with bulk logistics integration controlling lactic acid flows into Southeast Asian dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific food acidulant markets sit in early-cycle expansion as clean-label formulation mandates across India's FSSAI jurisdiction and China's dual carbon policy enforcement simultaneously accelerate bio-based platform adoption and filter legacy chemical synthesis suppliers from premium segments.
For Market Incumbents: Insulate certification-grade positioning through captive analytical laboratory investments that preempt GB 1886 heavy metal compliance audits and FSSAI documentation requirements. Deepen backward integration into molasses and corn starch sourcing to offset feedstock volatility compressing fermentation margins, while locking multi-year direct procurement contracts with Vietnam and Philippines greenfield beverage facilities before regional chemical traders consolidate remaining channel share. For New Entrants and Emerging Players: Build out bio-based acidulant platforms targeting Maharashtra and Gujarat bakery preservation segments where acidulant blends displace calcium propionate in extended-shelf-life goods. India's PLI scheme incentives create penetrable white space for domestic manufacturing investments that reduce import dependency, with go-to-market positioning anchored through FSSAI-certified supply chain traceability documentation that mid-scale incumbents lack resources to replicate. For Investors and Strategic Acquirers: India's PLI scheme implementation reshapes the acquisition landscape toward domestic fermentation capacity with regulatory pre-certification. Five-to-ten year viability favors operators with existing GB 1886 compliance infrastructure and direct procurement relationships with multinational beverage headquarters rather than regional distributor-dependent models. Signal to monitor: FSSAI disclosure requirement expansion into confectionery and dairy segments that would accelerate demand for certified-grade traceability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn starch and molasses sourcing control insulates fermentation margins from commodity volatility in coastal China. |
| Continuous Bioreactor Technology Migration | Energy intensity reduction under MEE dual carbon compliance enables premium positioning in carbon-accounting procurement. |
| Direct Procurement Contract Expansion | Bypassing Thai and Indonesian chemical traders captures margin compression as channel efficiency gains accelerate. |
| Certified-Grade Supply Chain Documentation | FSSAI traceability requirements push food manufacturers toward bio-based platforms with full chain-of-custody records. |
| Greenfield Fermentation Capacity in India | PLI scheme incentives reduce import dependency while positioning for Maharashtra and Gujarat processed food corridor demand. |
Study Parameters
Cross-validation between primary interviews with fermentation plant operators, FSSAI regulatory affairs leads, beverage procurement directors, and specialty chemical distributors anchors the qualitative findings in operational reality. Secondary validation draws from SAMR GB standard filings, India customs import data, ACC industry reports, and SEC 10-K disclosures from listed suppliers. Bottom-up acidulant consumption modeling across beverage, bakery, dairy, and confectionery applications triangulates against top-down market sizing from production capacity declarations.
Calibration against historical CAGRs from adjacent fermentation-derived ingredient categories informs growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include acidulant chemistry type, application end-use, certification grade tier, and regional production hub concentration. Forecast inputs incorporate molasses and corn starch price elasticity, MEE dual carbon enforcement timelines, and PLI scheme incentive uptake rates among Indian food processors.
Sensitivities concentrate around feedstock cost volatility, regulatory timeline acceleration for FSSAI disclosure expansion, and bilateral trade agreement reshaping of market access conditions. Cross-checking against India customs acidulant import volume trends and China fermentation capacity utilization disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
United Kingdom Anti Caking Market
Food Additives and Ingredients
Inosinic Acid Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
Sunset Yellow FCF Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Filling Fat Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Sugar Reduction Technology Market
Food Additives and Ingredients
Banana Powder Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Meat Tenderizing Agents Market