
 Keyhole Orthopaedic Surgery Market | 2026-2036
Keyhole Orthopaedic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Keyhole Orthopaedic Surgery Market Foresight
Multi-source procurement of visualization systems and electrosurgical devices is consolidating around fewer OEM partners with full-stack capabilities. Stryker Corporation leverages its endoscopy portfolio to anchor hospital supply agreements across North America. Zimmer Biomet Holdings, Inc. competes through specialized arthroscopic instrument lines that dominate sports medicine accounts. Smith & Nephew Plc differentiates via advanced wound closure sutures that sustain premium positioning in ambulatory settings.
Keyhole orthopaedic surgery encompasses minimally invasive procedures performed through portals under 10mm diameter using arthroscopes, motorized shavers, and radiofrequency probes to visualize and manipulate joint structures without open arthrotomy. Visualization systems lead product type revenue due to recurring camera and light-source replacement cycles, while electrosurgical devices represent the fastest-growing segment as bipolar radiofrequency adoption expands in soft tissue management. Joint repair applications command the largest volume share among procedure categories, though ligament reconstruction generates superior per-case instrument revenue through disposable anchor systems.
FDA 510(k) clearance pathways govern arthroscopic device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa and IIb instruments entering European markets. Japan's PMDA enforces unique QMS standards that extend registration timelines for foreign visualization system manufacturers. Stakeholders must monitor evolving reimbursement parity between inpatient and outpatient settings as procedural site migration reshapes capital equipment purchasing authority.
Market Dynamics
CMS reimbursement parity between inpatient and outpatient settings is redistributing purchasing authority from hospital capital committees to ambulatory surgical center administrators, compressing equipment procurement cycles and favoring modular visualization platforms over fixed-suite installations.
Growth Catalysts
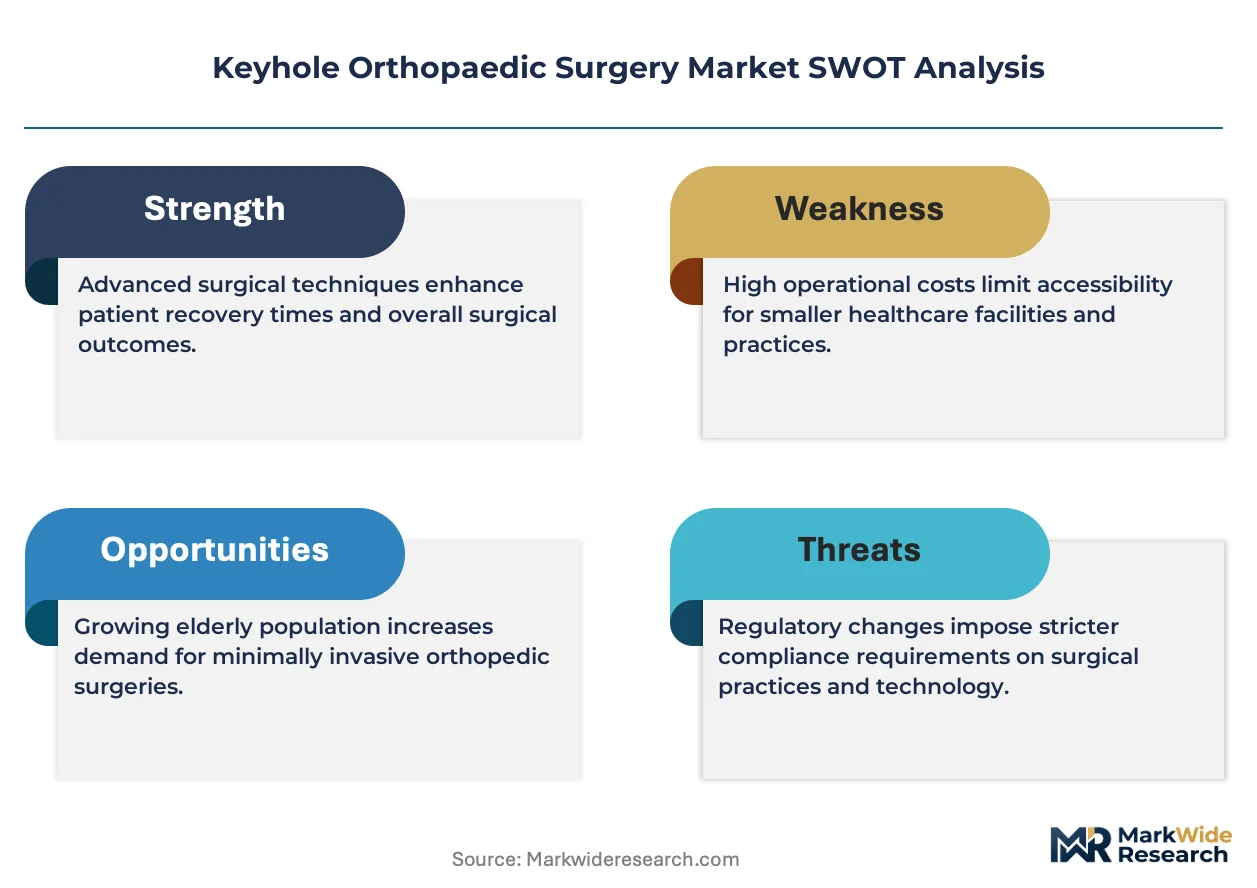
- Outpatient procedure migration:CMS expanded eligibility for same-day discharge joint procedures, accelerating demand for compact arthroscopic towers in freestanding surgical facilities across the United States.
- Radiofrequency soft tissue management:Bipolar electrosurgical devices now replace mechanical shavers in ligament debridement, shortening operative time and reducing instrument turnover for high-volume sports medicine practices.
- German hospital procurement pooling:Regional purchasing consortiums prioritize minimally invasive suite standardization, concentrating demand for full-stack visualization and navigation platforms in Bavaria and North Rhine-Westphalia.
Market Restraints
- Visualization component cost volatility:Sapphire camera lenses and LED light-source chips face supply concentration among Taiwanese and South Korean foundries, creating input price instability for OEMs.
- EU MDR clinical evidence requirements:Class IIb arthroscopic instruments now require prospective clinical data for CE marking, extending registration timelines and freezing new product introductions in European markets.
- Open arthrotomy persistence:Complex revision procedures and severe osteoarthritis cases still require traditional surgical access, limiting addressable procedure volume for portal-based techniques.
Strategic Opportunities
- Japanese ASC expansion:METI deregulation permits independent surgical facilities to perform knee arthroscopy outside hospital licensing, opening ambulatory channels previously blocked by institutional gatekeeping.
- Wearable navigation convergence:Integration of haptic feedback gloves with augmented reality headsets enables remote proctoring and trainee supervision without physical presence in the operating theater.
- Disposable anchor system penetration:Suture anchor pull-out strength improvements now match permanent implants, creating single-use revenue streams in ligament reconstruction previously captured by reusable hardware.
Industry Challenges
- Surgeon learning curve compression:Fellowship programs reduce arthroscopic case exposure as open procedure volumes decline, narrowing the pipeline of independently practicing specialists.
- Interoperability certification delays:Visualization systems must achieve IEC 62304 software lifecycle compliance for robotic platform integration, extending development timelines for legacy equipment retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keyhole Orthopaedic Surgery Market |
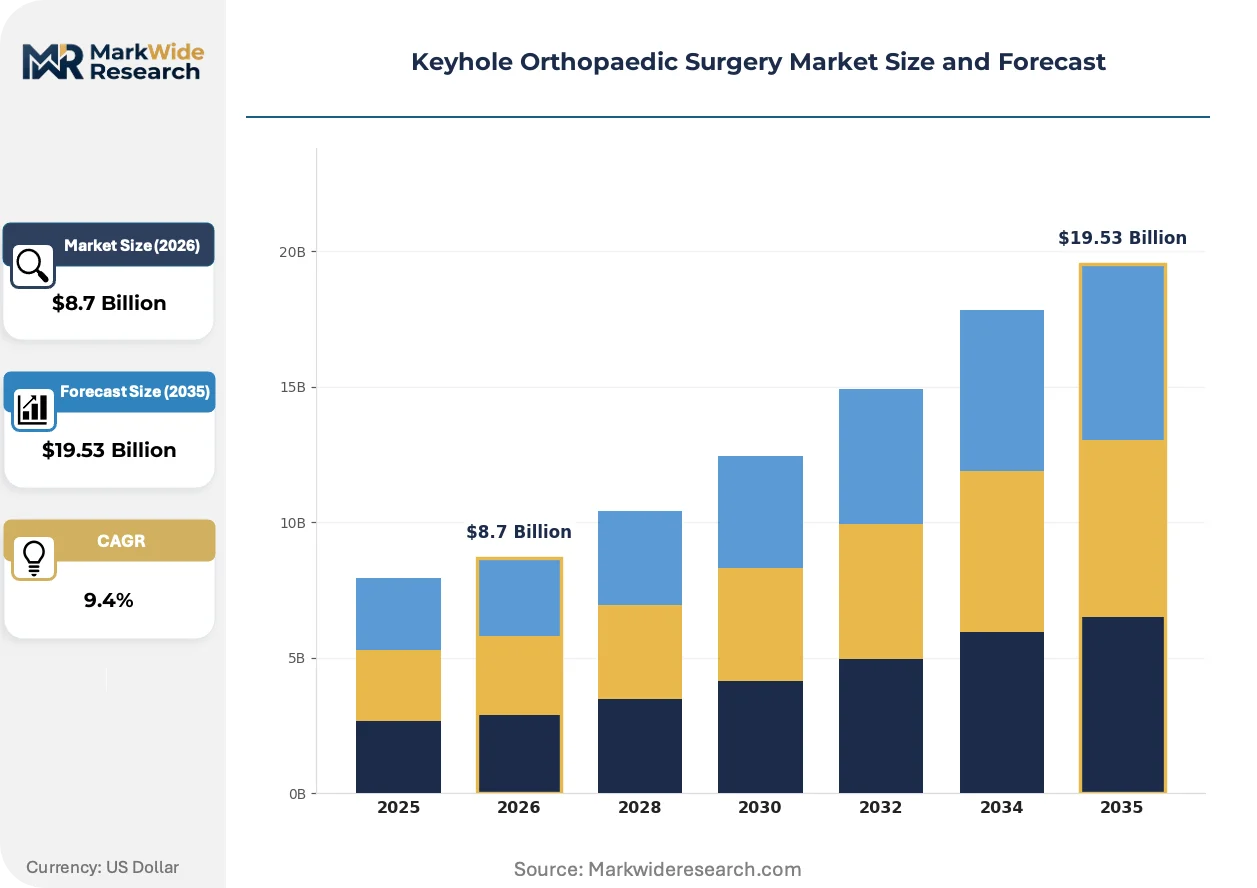
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arthroscopic Instruments, Visualization Systems, Sutures, Electrosurgical Devices Application: Joint Repair, Ligament Reconstruction, Cartilage Repair, Soft Tissue Management End User: Hospitals, Ambulatory Surgical Centers, Clinics, Rehabilitation Centers Delivery Mode: In-Hospital, At-Home, Outpatient, Virtual Consultation |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings, Inc., Smith & Nephew Plc, Johnson & Johnson, NuVasive, Inc., Globus Medical, Inc., Medtronic Limited, Arthrex Inc, Integra LifeSciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keyhole Orthopaedic Surgery Market Shifts & Advancements
Arthroscopic technology convergence is collapsing the distinction between diagnostic visualization and therapeutic intervention, enabling single-portal procedures that previously required multiple instrument exchanges and extended operative time.
4K fluorescence-guided imaging is unifying soft tissue visualization with perfusion assessment in a single camera head. Orthopaedic surgeons in high-volume German and Japanese hospitals are adopting these systems for meniscal repair and rotator cuff procedures. The technology is unifying previously separate capital equipment purchases into integrated platform decisions, pressuring standalone camera manufacturers without fluorescence capability.
The EU Medical Device Regulation now mandates post-market clinical follow-up for Class IIa arthroscopic shavers and radiofrequency probes, imposing surveillance obligations that smaller instrument manufacturers lack infrastructure to satisfy. German notified bodies have extended review timelines, causing product launch delays. Sports medicine distributors are consolidating supplier relationships toward OEMs with established European regulatory affairs departments.
Hospital supply agreements now bundle visualization system maintenance with disposable instrument commitments, displacing transactional purchasing. Ambulatory surgical centers in the United States are negotiating all-inclusive per-procedure fees that wrap capital depreciation into consumable pricing. This restructuring concentrates vendor selection authority with materials management rather than surgeon preference cards.
Keyhole Orthopaedic Surgery Market Segmentation
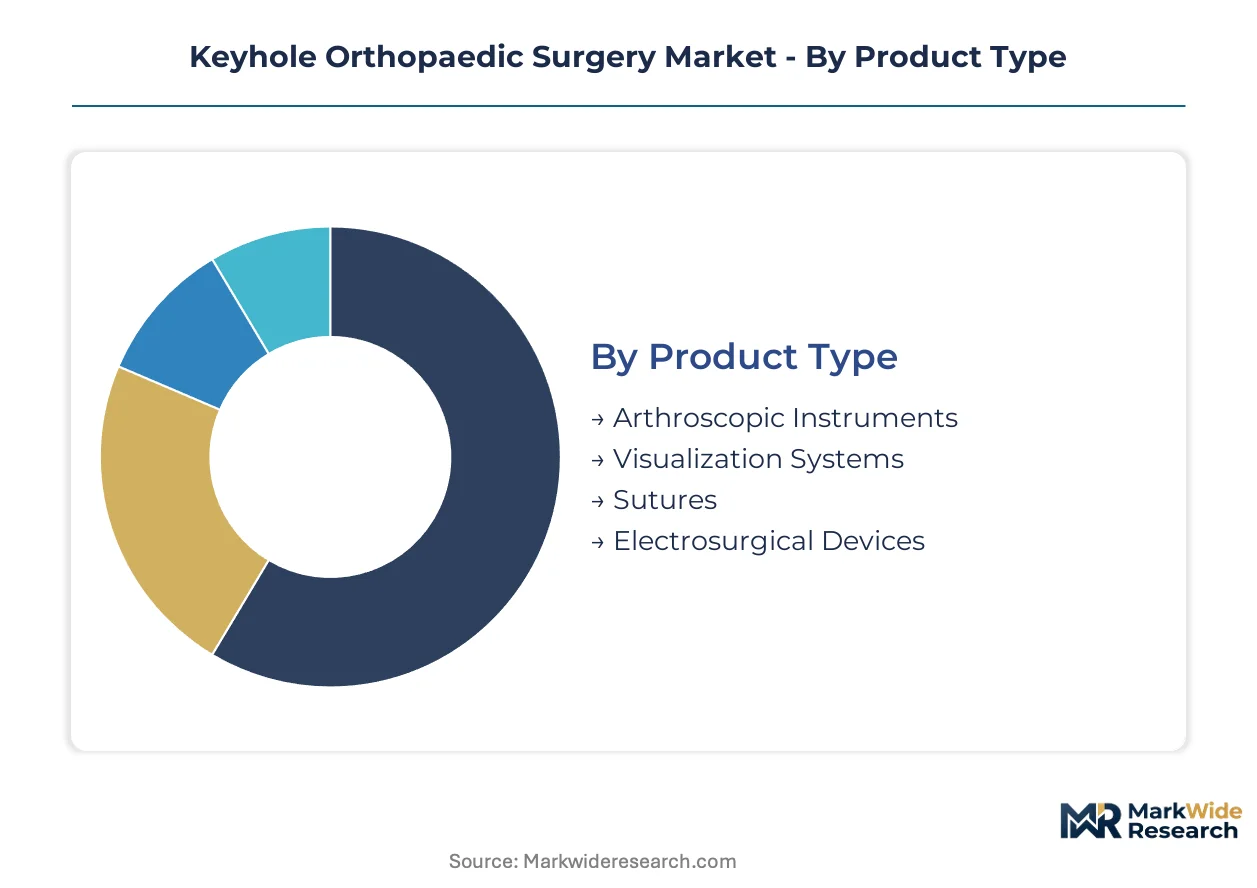
Keyhole orthopaedic surgery markets segment across product, application, and delivery dimensions that reshape procurement authority and regulatory exposure. Each category concentrates distinct margin profiles and certification burdens that determine vendor positioning and customer switching costs.
Product Type:
FDA 510(k) clearance governs arthroscopic instruments and electrosurgical devices, while EU MDR Class IIb designation imposes prospective clinical data requirements on visualization systems and advanced energy platforms.
- Visualization Systems:4K camera heads with integrated fluorescence capability unify diagnostic and therapeutic functions in single units. German hospital procurement pools in Bavaria concentrate demand for these platforms as regional standardization mandates accelerate replacement cycles.
- Electrosurgical Devices:Bipolar radiofrequency probes with tissue impedance feedback replace mechanical shavers in ligament debridement. Ambulatory surgical centers in the United States drive fastest uptake as operative time compression justifies premium pricing against reusable alternatives.
- Arthroscopic Instruments:Motorized shavers and hand-held graspers with disposable blade attachments.
- Sutures:Advanced wound closure systems including barbed and knotless configurations for portal-site management.
Leading the category by volume: Visualization Systems. Growing fastest: Electrosurgical Devices.
Application:
Procedure complexity determines instrument revenue per case, with multi-ligament reconstructions requiring anchor system bundles that exceed single-portal diagnostic arthroscopy economics by an order of magnitude.
- Joint Repair:Meniscal suturing and chondroplasty procedures performed through standard anteromedial and anterolateral portals. Japanese ASC expansion under METI deregulation opens ambulatory channels for knee repairs previously restricted to hospital licensing.
- Ligament Reconstruction:ACL and rotator cuff repairs utilizing suture anchor systems with pull-out strength matching permanent implants. Sports medicine accounts in North America generate superior per-case instrument revenue through disposable anchor consumption.
- Cartilage Repair:Microfracture and autologous chondrocyte implantation procedures requiring specialized delivery instruments.
- Soft Tissue Management:Synovectomy and capsular release procedures employing radiofrequency thermal modulation.
Joint Repair captures the highest procedure volume. Ligament Reconstruction commands the steepest expansion trajectory in revenue per intervention.
End User:
Site-of-care migration redistributes purchasing authority from hospital capital committees to ASC administrators, compressing equipment procurement cycles and favoring modular platforms over fixed-suite installations.
- Hospitals:Academic medical centers and community hospitals with dedicated orthopaedic suites. CMS reimbursement parity rules erode inpatient joint procedure volumes as same-day discharge eligibility expands.
- Ambulatory Surgical Centers:Freestanding facilities performing outpatient arthroscopy under expanded CMS procedural codes. United States ASC administrators now control visualization system procurement through bundled per-procedure fee structures.
- Clinics:Orthopaedic practice offices with limited procedure capabilities.
- Rehabilitation Centers:Post-operative recovery facilities without operative intervention authority.
Volume concentrates with Ambulatory Surgical Centers. Fastest transition occurs in hospital outpatient departments converting to independent ASC status.
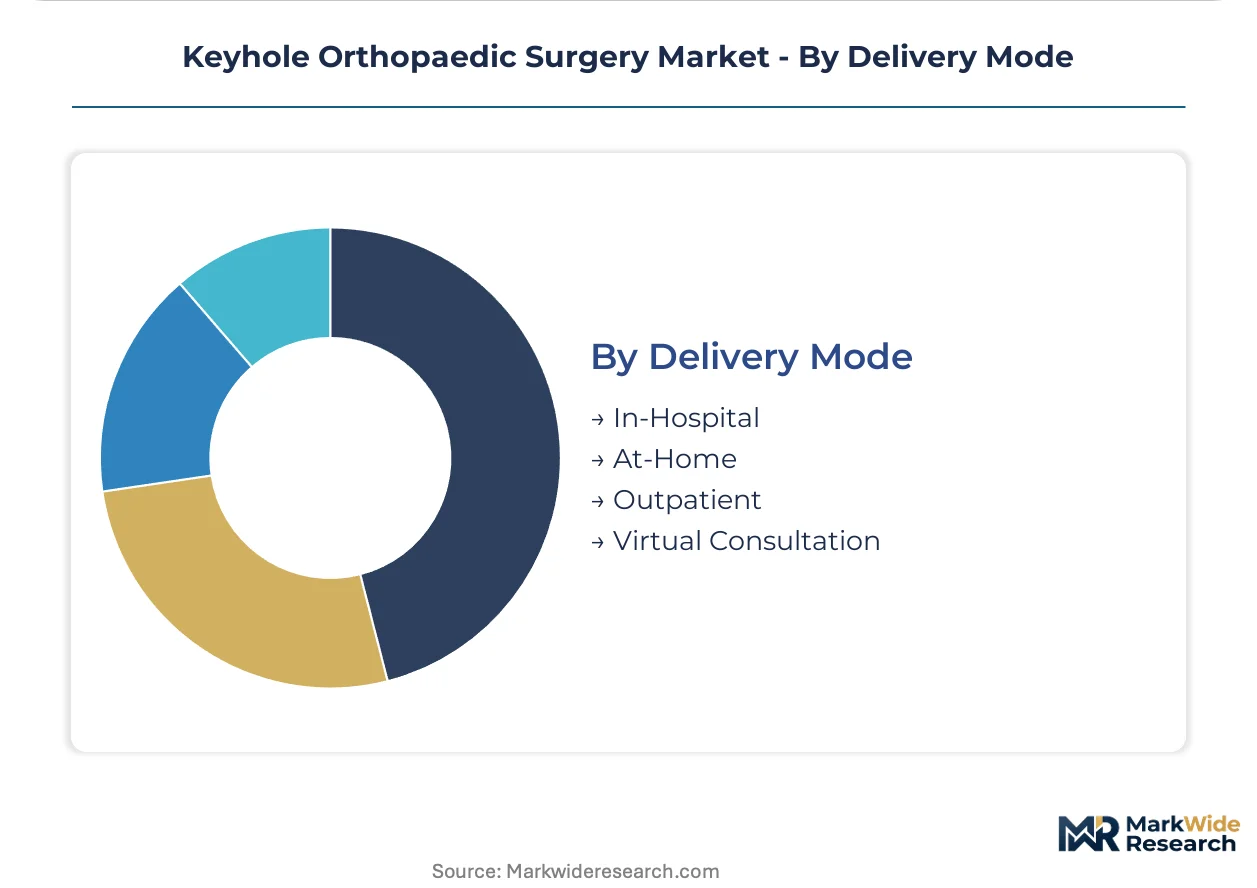
Delivery Mode:
Virtual consultation and remote proctoring capabilities now influence capital equipment specifications as wearable navigation converges with augmented reality platforms.
- Outpatient:Same-day discharge procedures in dedicated surgical facilities. German regional purchasing consortiums standardize minimally invasive suite configurations across North Rhine-Westphalia hospital networks.
- In-Hospital:Traditional inpatient admissions with overnight stays. Complex revision procedures and severe osteoarthritis cases maintain this channel despite site-of-care migration pressure.
- At-Home:Post-operative monitoring and rehabilitation protocols.
- Virtual Consultation:Pre-operative assessment and remote surgical planning utilizing haptic feedback gloves with AR headset integration.
Outpatient delivery leads procedure volume. Virtual Consultation exhibits the most rapid capability expansion as remote proctoring reduces training travel requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sapphire camera lenses and LED chips from Taiwanese and South Korean foundries anchor supply-side geography for visualization systems, while demand concentrates in hospital procurement pools across Germany, ambulatory surgical centers in the United States, and deregulated Japanese facilities.
United States
Ambulatory surgical centers drive visualization system demand as CMS reimbursement parity expands same-day discharge eligibility for joint procedures. FDA 510(k) clearance pathways govern arthroscopic device commercialization with streamlined timelines for Class II instruments. Texas and Florida ASC administrators now control procurement through bundled per-procedure fee structures that wrap capital depreciation into consumable pricing.
Germany
Regional hospital procurement consortiums in Bavaria and North Rhine-Westphalia concentrate demand for full-stack minimally invasive suites. EU MDR Class IIb designation imposes prospective clinical data requirements on advanced energy platforms entering European markets. Munich and Düsseldorf hospital networks prioritize visualization platform standardization across affiliated facilities, accelerating replacement cycles for 4K fluorescence-capable systems.
Japan
METI deregulation permits independent surgical facilities to perform knee arthroscopy outside hospital licensing, opening ambulatory channels previously blocked by institutional gatekeeping. PMDA enforces unique QMS standards that extend registration timelines for foreign visualization system manufacturers. Tokyo and Osaka academic medical centers anchor adoption of wearable navigation convergence with augmented reality headsets for remote proctoring.
United Kingdom
NHS supply agreements bundle visualization system maintenance with disposable instrument commitments, displacing transactional purchasing toward integrated vendor relationships. MHRA operates under retained EU MDR alignment for device registration, preserving clinical evidence requirements for Class IIa arthroscopic shavers. London and Manchester orthopaedic networks consolidate procurement authority through regional purchasing collaboratives.
South Korea
LED light-source chip foundries in Gyeonggi Province supply critical components for visualization systems facing input price volatility. MFDS maintains harmonized standards with FDA and PMDA for streamlined multinational registration. Seoul Capital Area hospitals drive adoption of bipolar radiofrequency probes with tissue impedance feedback for ligament debridement procedures.
Keyhole Orthopaedic Surgery Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent orthopaedic conglomerates anchor hospital supply agreements through bundled visualization and instrument offerings. The market structure concentrates around full-stack OEMs with endoscopy portfolios, electrosurgical device specialists, and sports medicine-focused instrument manufacturers. Three archetypes define competitive positioning: integrated platform providers leveraging maintenance contracts, disposable anchor system innovators capturing ligament reconstruction revenue, and modular tower suppliers serving ASC price sensitivity. M&A activity and strategic partnerships represent the dominant competitive moves as mid-cap specialists seek regulatory infrastructure and geographic reach.
Among North American-based conglomerates, Stryker Corporation and Zimmer Biomet Holdings, Inc. occupy positions as integrated platform anchors, while Smith & Nephew Plc exemplifies the specialized wound closure and sports medicine archetype. These three entities represent the tier of vendors capable of satisfying EU MDR surveillance obligations and German procurement consortium technical specifications. Their collective positioning illustrates how regulatory compliance infrastructure and regional purchasing authority concentration favor established players with dedicated European regulatory affairs departments over smaller instrument manufacturers lacking post-market clinical follow-up capabilities.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Smith & Nephew Plc |
| Johnson & Johnson |
| NuVasive, Inc. |
| Globus Medical, Inc. |
| Medtronic Limited |
| Arthrex Inc |
| Integra LifeSciences Corporation |
| Others |
Supply & Pricing Matrix
German hospital procurement pools in Bavaria and North Rhine-Westphalia now mandate 4K fluorescence-capable visualization suites as regional standardization requirements, forcing OEMs to absorb sapphire lens and LED chip cost volatility while compressing service-bundling margins into multi-year maintenance contracts.
Pricing Analysis
Extended warranty and preventive maintenance bundling now separates premium-tier full-stack providers from economy-tier modular tower suppliers in ambulatory surgical center negotiations. Price differentiation hinges on CE marking tier under EU MDR Class IIb designation and volume-scale disposable instrument commitments. Cost compression in standard visualization platforms is intensifying as Taiwanese foundry input prices fluctuate. Ambulatory surgical center administrators exhibit highest price sensitivity; academic medical centers with dedicated orthopaedic suites demonstrate lowest.
Supply Chain Analysis
Specialized optical engineering talent scarcity in Gyeonggi Province and Taichung constrains LED light-source chip and sapphire camera lens production expansion for visualization system OEMs. Manufacturing concentrates in Taiwan, South Korea, and Germany. Critical inputs include sapphire substrates, CMOS sensors, and radiofrequency generator components. Single-source vulnerability in Taiwanese foundry capacity for high-purity sapphire represents the dominant structural risk. Distribution runs through hospital procurement consortiums in Germany and GPO-negotiated contracts in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The keyhole orthopaedic surgery market sits in a technology-transition phase as bipolar radiofrequency probes with tissue impedance feedback displace mechanical shavers in ligament debridement, collapsing operative time economics and reshaping instrument procurement patterns.
For Market Incumbents: Deploy post-market clinical follow-up infrastructure as the priority lever to satisfy EU MDR surveillance obligations for Class IIb arthroscopic instruments. Consolidate supplier relationships toward OEMs with established European regulatory affairs departments. Deepen backward integration into sapphire lens supply through captive partnerships with Taiwanese foundries to defend against input price volatility from emerging modular tower competitors.
For New Entrants and Emerging Players: The premium-to-economy tier price gap in visualization systems creates entry space for modular tower suppliers targeting United States ambulatory surgical centers with per-procedure fee structures. Focus white-space capture on Japanese independent surgical facilities newly authorized under METI deregulation for knee arthroscopy outside hospital licensing. Pursue software companion development for wearable navigation convergence with augmented reality headsets as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with disposable anchor system innovators given suture anchor pull-out strength improvements now matching permanent implants, opening single-use revenue streams in ligament reconstruction. Long-term viability over the next decade favors mid-cap specialists with EU MDR compliance infrastructure and established German procurement consortium relationships. Monitor CMS reimbursement parity expansion for outpatient joint procedures as the critical inflection signal for ambulatory surgical center equipment procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Infrastructure Buildout | CE marking timelines for Class IIb instruments now require prospective clinical data and post-market surveillance capabilities. |
| Fluorescence-Guided Imaging Platform Launch | 4K camera heads with integrated perfusion assessment unify diagnostic and therapeutic functions in German hospital networks. |
| Disposable Anchor System Portfolio Expansion | Single-use suture anchors with permanent-implant-equivalent pull-out strength capture ligament reconstruction revenue from reusable hardware. |
| Ambulatory Surgical Center Partnership Program | Bundled per-procedure fee structures in Texas and Florida wrap capital depreciation into consumable pricing for modular tower suppliers. |
| Wearable Navigation Convergence Development | Haptic feedback glove integration with augmented reality headsets enables remote proctoring in Tokyo and Osaka academic medical centers. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR notified body guidance documents, and CMS reimbursement rulemaking records, complemented by interviews with hospital purchasing committee chairs, ambulatory surgical center administrators, biomedical engineers, GPO contracts managers, and orthopaedic surgeons across the United States, Germany, and Japan. Secondary validation drew from hospital procurement databases, GPO contract disclosures, and PMDA registration filings. Bottom-up procedure volume estimates and top-down equipment replacement cycle analysis were triangulated against manufacturer shipment data.
Historical visualization system replacement patterns were cross-referenced against expert panel input from German hospital procurement consortium directors and Japanese METI deregulation implementation officers. Segmentation modeling across product type, application, end user, and delivery mode dimensions incorporated procedure site migration trends, regulatory framework clusters, and regional purchasing authority concentration patterns. CAGRs were derived from equipment installed base growth and disposable instrument consumption trajectories, with specific weighting for radiofrequency probe adoption curves and fluorescence-capable camera head upgrade cycles.
Inputs from PMDA QMS standard auditors and German notified body review officers were available through the study window; gaps in real-time ambulatory surgical center conversion data from hospital outpatient departments introduce uncertainty bands around United States volume projections. Forecasts embed assumptions regarding CMS reimbursement parity expansion velocity and EU MDR clinical evidence requirement enforcement consistency. Material deviation in Taiwanese foundry capacity allocation or METI deregulation implementation scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Medical Traction Devices Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Global Orthopedic Bone Cement Market