
 Global Personalized 3D Printed Orthopedic Implants Market | 2026-2036
Global Personalized 3D Printed Orthopedic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personalized 3D Printed Orthopedic Implants Market Foresight
A shortage of trained biomedical design engineers is redrawing competitive boundaries in personalized implant production. Stryker leverages its captive metal printing capacity to control lead times for complex hip reconstructions. Materialise anchors European hospital networks with software-to-implant workflows that bridge scan data and selective laser melting output. EOS GmbH dominates industrial-grade titanium powder bed fusion systems installed at contract manufacturers serving orthopedic OEMs.
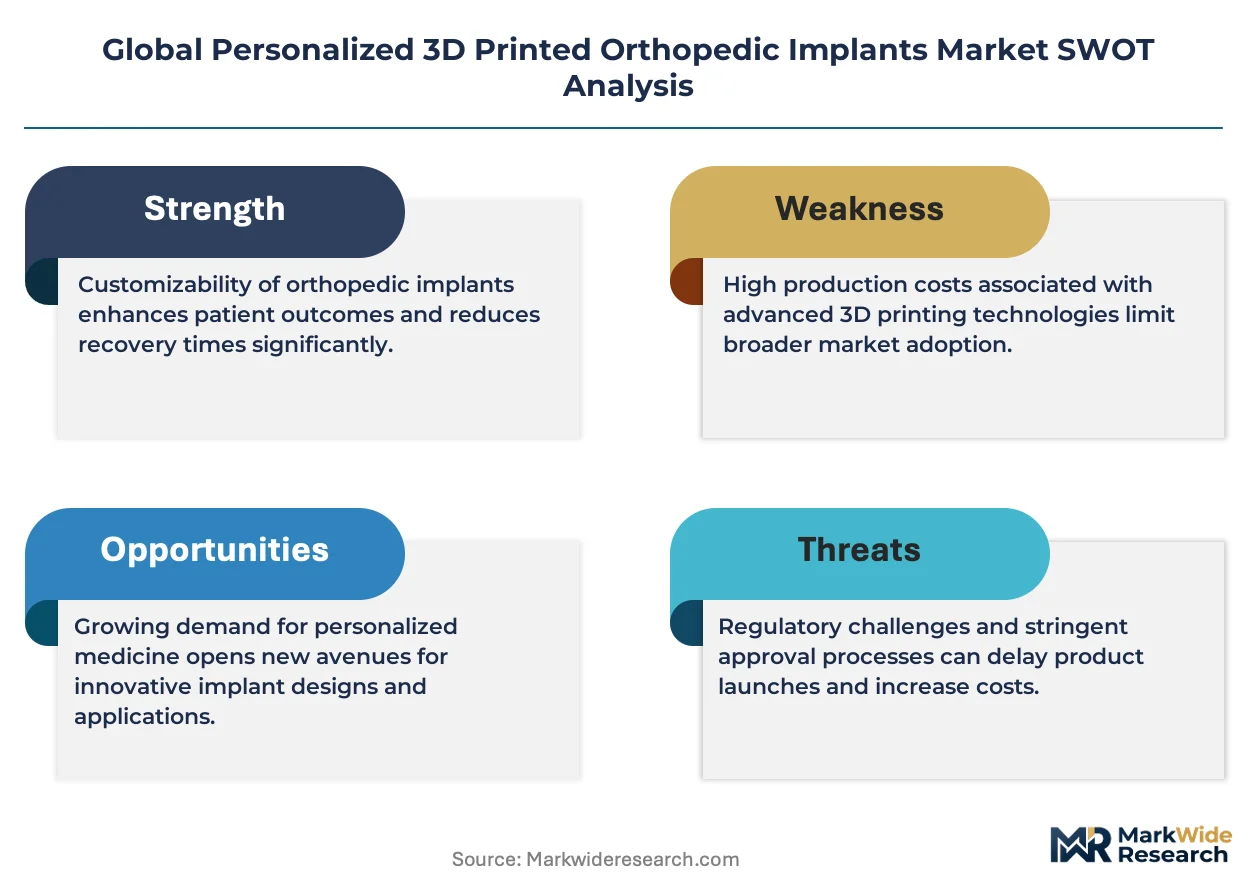
Personalized 3D printed orthopedic implants are patient-matched devices fabricated through additive manufacturing of biocompatible materials such as titanium alloys and PEEK, with pore architectures engineered between 100-500 microns to promote osseointegration. These implants replace or reinforce damaged skeletal structures when off-the-shelf geometries cannot restore biomechanical function. Joint implants lead current revenue contribution as knee and hip arthroplasty volumes strain standard inventory models. Titanium material demand outpaces polymer alternatives in load-bearing applications where fatigue resistance governs clinical acceptance. Selective laser sintering occupies the fastest-expanding manufacturing technique category as powder bed fusion achieves pore precision that fused deposition modeling cannot replicate.
FDA 510(k) premarket notification and EU MDR technical documentation requirements enforce biocompatibility validation and process repeatability that filter out undercapitalized entrants. ISO 13485 quality management systems and ASTM F3091 standards for additively manufactured implants further tighten compliance burdens for cross-border suppliers. Stakeholders must monitor how national reimbursement decisions for custom-device add-on payments reshape hospital willingness to adopt patient-specific workflows over standard catalog implants.
Market Dynamics
Hospital procurement teams are consolidating vendor relationships around additive manufacturing platforms that compress pre-surgical planning cycles from weeks to days. This concentration of buying power is forcing implant manufacturers to embed design software and printing capacity into integrated service contracts rather than discrete hardware sales.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's premarket notification framework for patient-matched devices accelerates titanium lattice implant approvals, reducing regulatory uncertainty for hospital adoption committees.
- PEEK polymer osseointegration advances:Porous polyetheretherketone structures engineered through selective laser sintering now achieve bone ingrowth rates comparable to titanium in spinal fusion applications.
- German university hospital networks:Academic medical centers in Berlin, Munich, and Heidelberg integrate scan-to-implant workflows that demonstrate measurable reductions in revision surgery rates.
Market Restraints
- Titanium powder supply concentration:Spherical Ti-6Al-4V powder production concentrates among three European chemical suppliers, exposing orthopedic OEMs to input cost volatility and allocation risk.
- EU MDR technical documentation burden:The Medical Device Regulation's clinical evidence requirements for additively manufactured implants impose multi-year compliance timelines that filter out mid-tier competitors.
- Standard implant catalog substitution:Off-the-shelf cobalt-chromium and polyethylene components retain cost advantages for routine arthroplasty cases, limiting patient-specific hardware to complex anatomical reconstructions.
Strategic Opportunities
- China NMPA regulatory harmonization:China's National Medical Products Administration is aligning custom-device pathways with international standards, opening procurement channels for European and American implant designers.
- Trauma and craniomaxillofacial expansion:Facial reconstruction and pelvic fracture fixation represent underpenetrated applications where patient-matched geometries deliver functional outcomes impossible with standard plates.
- Software-as-a-service distribution models:Cloud-based surgical planning platforms enable remote design collaboration between hospital radiology departments and distributed printing facilities.
Industry Challenges
- Biomedical design engineer scarcity:The intersection of computational topology optimization, biocompatibility validation, and additive process engineering creates a talent bottleneck that extends implant development cycles.
- ISO 13485 certification timeline compression:Quality management system audits for multi-site manufacturing networks strain smaller contract manufacturers attempting to serve multiple orthopedic OEMs simultaneously.
- Legacy hospital IT integration:DICOM-to-implant data pipelines require middleware development that many medical centers lack internal capability to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personalized 3D Printed Orthopedic Implants Market |
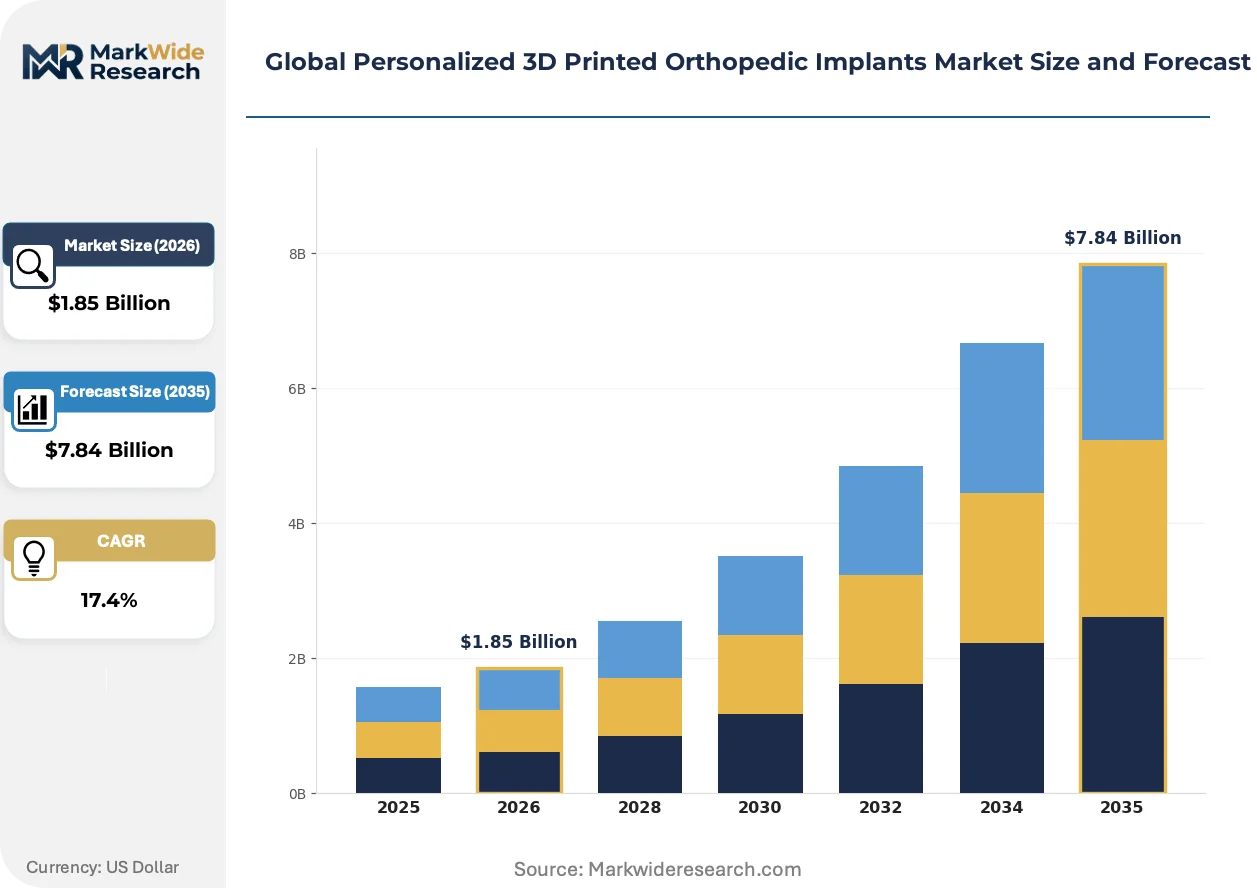
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Implants, Joint Implants, Spine Implants, Dental Implants Material: Titanium, PEEK, Polymers, Ceramics Manufacturing Technique: Fused Deposition Modeling, Selective Laser Sintering, Stereolithography, Binder Jetting End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Research Laboratories |
| Companies Covered | Stratasys, 3D Systems, Materialise, Stryker, Zimmer Biomet, EnvisionTEC, SLM Solutions, EOS GmbH, Formlabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personalized 3D Printed Orthopedic Implants Market Shifts & Advancements
Selective laser melting is displacing electron beam melting as the dominant powder bed fusion modality for orthopedic titanium lattices. This technology rotation reflects hospital demands for surface finish precision and pore architecture control that enable faster osseointegration.
Electron beam melting's coarse surface roughness and limited material portfolio are supplanting its historical dominance in aerospace-adjacent medical applications. Academic medical centers in the United States and Germany now specify laser-based systems for hip and knee reconstruction hardware. The shift is compressing equipment procurement cycles for hospital-based additive manufacturing labs and redirecting R&D investment toward laser parameter optimization for fatigue-resistant lattice structures.
The EU MDR's enhanced post-market surveillance requirements are mandating implant-specific clinical follow-up registries that track patient outcomes for ten to fifteen years. This regulatory architecture forces manufacturers to invest in traceability infrastructure that links individual printed devices to patient records. Joint reconstruction segments face the steepest compliance burden, as high-volume hip and knee applications generate the largest data aggregation requirements.
Hospital value analysis committees are consolidating implant procurement around vendors who bundle pre-operative planning software with physical device production. This purchasing pattern is displacing traditional distributor relationships that separated hardware catalog sales from surgical support services. The behavioral shift is most visible in United States academic medical centers, where orthopedic departments negotiate enterprise contracts that span design software licenses, printing capacity allocation, and implant supply.
Global Personalized 3D Printed Orthopedic Implants Market Segmentation
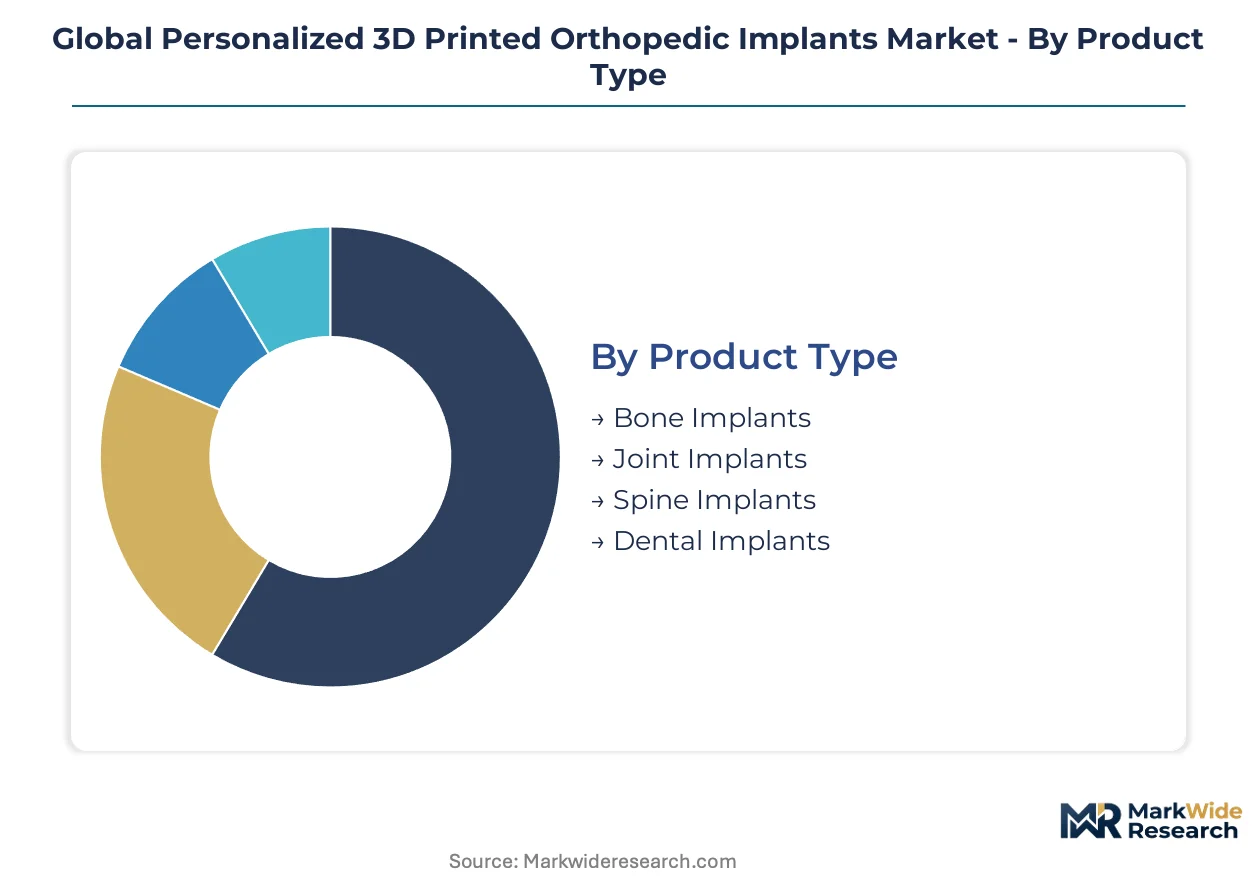
Patient-matched orthopedic hardware demands granular segmentation because implant geometry, material selection, and manufacturing modality directly determine osseointegration timelines and revision surgery risk. Procurement teams evaluate each dimension separately when qualifying vendors for complex reconstructions.
Product Type:
Domestic hospital networks in Germany and the United States drive demand for joint and spine implants, while export-led growth concentrates in trauma and craniomaxillofacial applications shipped to Middle Eastern and Southeast Asian medical centers.
- Joint Implants:Patient-specific hip and knee components fabricated from titanium alloys with lattice porosities between 300-500 microns optimize load distribution across compromised bone stock. United States academic medical centers in Boston and New York now specify these for complex revision arthroplasty cases where standard stems fail to achieve fixation.
- Spine Implants:Custom interbody fusion cages match individual vertebral endplate topography, reducing subsidence rates in multilevel procedures. German university hospitals in Munich and Heidelberg report measurable reductions in adjacent segment degeneration when deploying patient-matched geometries versus off-the-shelf PEEK spacers.
- Bone Implants:Cranial plates and pelvic reconstruction hardware address trauma defects where standard titanium mesh cannot restore anatomical continuity.
- Dental Implants:Patient-specific abutments and guided surgery templates concentrate in European aesthetic dentistry practices seeking soft tissue emergence profile control.
Joint implants hold the largest share; momentum sits with spine implants as lumbar fusion volumes strain standard inventory models.
Material:
Cost stratification separates premium titanium alloys from mid-tier PEEK polymers and economy ceramic alternatives, with fatigue resistance governing clinical acceptance in load-bearing applications.
- Titanium:Ti-6Al-4V ELI and Ti-6Al-7Nb alloys dominate hip and knee reconstructions where cyclic loading exceeds 10 million cycles annually. United States FDA 510(k) clearances for titanium lattice structures outpace polymer approvals, reinforcing hospital confidence in long-term implant survival.
- PEEK:Radiolucent polyetheretherketone enables post-operative CT assessment without metal artifact, particularly valued in spinal fusion where fusion mass evaluation determines return-to-activity timelines. European hospitals in Switzerland and the Netherlands lead adoption as EU MDR technical documentation requirements for titanium powder sourcing create temporary supply uncertainty.
- Polymers:Resorbable polylactic acid scaffolds for pediatric applications degrade as native bone regenerates, eliminating secondary removal surgeries.
- Ceramics:Alumina and zirconia components serve niche dental and finger joint applications where wear resistance outweighs toughness requirements.
Titanium commands the dominant revenue position; PEEK is climbing the fastest as porous SLS processing achieves bone ingrowth parity with metal.
Manufacturing Technique:
Volume concentration favors powder bed fusion installations at contract manufacturers serving multiple orthopedic OEMs, while lower-throughput stereolithography and binder jetting systems cluster at hospital-based point-of-care facilities.
- Selective Laser Sintering:Laser-based powder bed fusion achieves pore precision of ±50 microns, enabling engineered surface roughness that accelerates osteoblast attachment. German equipment suppliers dominate industrial system installations at contract manufacturers in Bavaria and Baden-Württemberg serving European hospital networks.
- Fused Deposition Modeling:Extrusion-based polymer printing serves surgical planning models and provisional guides rather than permanent implants, with United States hospitals deploying desktop systems for same-day pre-operative visualization.
- Stereolithography:Vat photopolymerization produces investment casting patterns for cobalt-chromium dental frameworks with surface finishes unattainable through machining.
- Binder Jetting:Powder bed inkjet systems with secondary sintering offer throughput advantages for stainless steel trauma plates where geometric complexity exceeds milling capability.
Selective laser sintering holds the largest installed base; binder jetting is gaining share fastest as throughput economics improve for high-volume trauma applications.
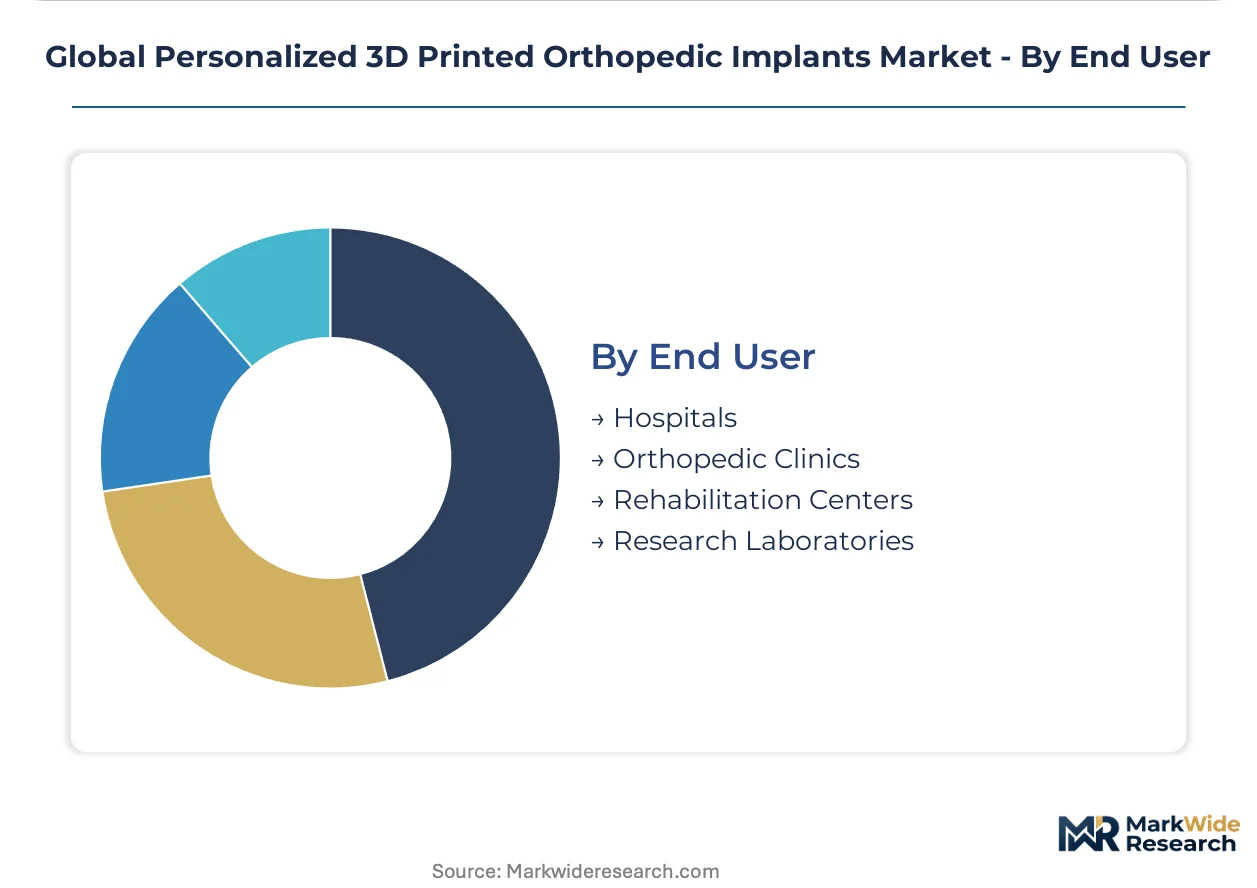
End User:
Customer type determines service model configuration, with enterprise hospitals demanding integrated software-to-implant workflows while orthopedic clinics and rehabilitation centers purchase through distributor networks with extended lead times.
- Hospitals:Academic medical centers in the United States, Germany, and China operate captive additive manufacturing labs or contracted production capacity with 48-hour turnaround commitments for emergency trauma cases. These institutions negotiate enterprise licenses spanning DICOM segmentation software, printing capacity allocation, and implant supply under single vendor relationships.
- Orthopedic Clinics:Ambulatory surgery centers concentrate in elective joint replacement corridors of Florida and Texas, relying on remote design services and regional printing hubs to access patient-specific hardware without capital equipment investment.
- Rehabilitation Centers:Post-acute facilities in Japan and South Korea deploy custom orthotic and prosthetic interfaces fabricated through distributed manufacturing networks.
- Research Laboratories:University engineering departments and hospital-affiliated innovation centers drive materials development for next-generation resorbable scaffolds and functionally graded composites.
Hospitals command the dominant procurement volume; orthopedic clinics represent the steepest expansion trajectory as same-day surgery volumes shift site of service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor United States demand for patient-matched titanium lattice implants. Academic medical centers in Boston, New York, and California integrate additive manufacturing into pre-surgical planning workflows. Procurement teams consolidate vendor relationships around software-to-implant service contracts.
United States
Hospital value analysis committees in Boston and New York negotiate enterprise contracts spanning DICOM segmentation software and printing capacity. FDA premarket notification requirements enforce biocompatibility validation that filters undercapitalized entrants. The Mayo Clinic and Cleveland Clinic anchor Midwest adoption of scan-to-implant workflows for complex revision arthroplasty.
Germany
University hospital networks in Berlin, Munich, and Heidelberg demonstrate measurable reductions in revision surgery rates using patient-specific geometries. EU MDR technical documentation requirements impose multi-year compliance timelines for additively manufactured implants. Bavaria and Baden-Württemberg concentrate industrial-grade powder bed fusion installations serving European orthopedic OEMs.
China
Academic medical centers in Beijing and Shanghai expand adoption of titanium lattice structures for trauma and joint reconstruction. NMPA regulatory harmonization with international standards opens procurement channels for European and American implant designers. The Yangtze River Delta clusters contract manufacturers serving domestic hospital networks.
Switzerland
Swissmedic oversight of custom-device pathways accelerates quality benchmarks for spinal fusion applications. Hospitals in Zurich and Geneva lead PEEK polymer adoption where radiolucency enables post-operative CT assessment without metal artifact. The Basel region anchors materials development for next-generation resorbable scaffolds.
Japan
PMDA regulatory frameworks govern patient-matched device approvals for hip and knee reconstruction hardware. Academic medical centers in Tokyo and Osaka integrate selective laser melting into pre-surgical planning for complex anatomical cases. The Kansai region concentrates rehabilitation centers deploying custom orthotic interfaces through distributed manufacturing networks.
Global Personalized 3D Printed Orthopedic Implants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that concentrates on software-to-implant workflows or captive metal printing capacity. The upper tier controls lead times through backward integration into powder bed fusion systems. Mid-tier players compete on DICOM segmentation expertise and regulatory submission support. Dominant competitive moves include strategic partnerships between equipment suppliers and hospital networks, plus capacity expansion at contract manufacturers serving multiple orthopedic OEMs.
Among European fabricators, Materialise and EOS GmbH exemplify distinct archetypes within the integrated tier. Materialise anchors hospital networks with software-to-implant workflows bridging scan data and selective laser melting output. EOS GmbH occupies a position supplying industrial-grade titanium powder bed fusion systems installed at contract manufacturers. Stryker represents the captive-capability model, leveraging in-house metal printing to control lead times for complex reconstructions.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| Materialise |
| Stryker |
| Zimmer Biomet |
| EnvisionTEC |
| SLM Solutions |
| EOS GmbH |
| Formlabs |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts between German powder bed fusion equipment suppliers and United States hospital networks lock in titanium powder allocation and implant production pricing visibility across multi-year procurement cycles. These arrangements insulate academic medical centers from spot-market volatility in spherical Ti-6Al-4V feedstock while binding contract manufacturers to fixed-volume output commitments.
Pricing Analysis
Price spreads between titanium lattice implants sourced from Bavarian contract manufacturers versus Chinese production facilities reflect EU MDR certification premiums and powder traceability documentation costs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared titanium alloys from PEEK polymers and provisional surgical guides. Pricing pressure stems from hospital value analysis committees consolidating vendor relationships around bundled software-to-implant service contracts. Orthopedic clinics in ambulatory settings exhibit the highest price sensitivity due to capital constraints and extended lead-time tolerance, while academic medical centers prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Inbound logistics costs for spherical titanium powder shipments from Hamburg and Antwerp ports to Bavarian additive manufacturing facilities have intensified allocation risk as container availability fluctuates on Asia-Europe trade lanes. Supply concentrates in Germany, China, and Belgium for industrial-grade powder bed fusion systems and spherical Ti-6Al-4V feedstock. Raw material dependencies center on titanium sponge from Ukraine and Kazakhstan, argon gas for inert atmosphere processing, and polymer feedstocks for PEEK sintering. Single-source vulnerability pervades the three European chemical suppliers dominating spherical powder production. Distribution runs through hospital-based captive printing labs and contracted production capacity at regional manufacturing hubs serving multiple orthopedic OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as hospital procurement teams disaggregate traditional distributor relationships into specialized software, printing capacity, and implant supply contracts. This unbundling creates niches for point-solution vendors in DICOM segmentation, regulatory submission support, and regional powder bed fusion services.
For Market Incumbents: Shield market position by deepening backward integration into titanium powder sourcing and expanding captive printing capacity in the Yangtze River Delta to serve Chinese hospital networks. Acquire regulatory submission expertise to compress EU MDR technical documentation timelines as compliance burdens filter mid-tier competitors. Prioritize ISO 13485 certification investments across multi-site manufacturing networks to defend against contract manufacturer consolidation. For New Entrants and Emerging Players: Anchor in trauma and craniomaxillofacial applications where patient-matched geometries deliver functional outcomes impossible with standard plates and revision surgery rates remain unaddressed by incumbent catalogs. Target orthopedic clinics in Florida and Texas corridors through cloud-based surgical planning platforms that eliminate capital equipment requirements. Pursue software-as-a-service distribution models enabling remote design collaboration between radiology departments and distributed printing facilities. For Investors and Strategic Acquirers: Capital is best deployed toward biomedical design engineering specialists possessing computational topology optimization capabilities and established FDA 510(k) submission track records. Long-term viability hinges on regulatory moats widening as EU MDR post-market surveillance requirements extend to fifteen-year clinical follow-up registries. Monitor NMPA regulatory harmonization progress as the signal indicating procurement channel opening for European and American implant designers in Chinese academic medical centers.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise contracts spanning DICOM software and printing capacity consolidate procurement at Mayo Clinic and Cleveland Clinic networks. |
| CE Marking Pathway | EU MDR technical documentation compliance enables market access across German university hospital networks in Berlin and Munich. |
| Backward Integration into Powder Supply | Captive spherical Ti-6Al-4V sourcing insulates Stryker from European chemical supplier allocation constraints. |
| Software Companion Development | Cloud-based surgical planning platforms enable Materialise to bridge scan data and selective laser melting output remotely. |
| Reimbursement Strategy | Custom-device add-on payment approvals determine hospital willingness to adopt patient-specific workflows over standard implants. |
Research Methodology
The analysis maps joint implants, spine implants, trauma hardware, and dental applications, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at orthopedic OEMs. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up demand modeling and top-down supply capacity assessments triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation dimensions including implant geometry complexity, material certification tier, manufacturing modality precision, and end-user service model configuration. CAGRs derive from implant volume forecasts weighted by procedural complexity indices and material cost curves. Industry-specific inputs incorporate titanium powder price trajectories and hospital additive manufacturing lab installation rates.
Material uncertainties — titanium powder supply disruptions, EU MDR audit timeline extensions, and NMPA harmonization delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory pathway stability and hospital capital expenditure continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Orthopedic Bone Cement Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Total Wrist Prosthesis Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Global Patient Positioning Devices Market