
 Femoral Head Prostheses Market | 2026-2036
Femoral Head Prostheses Market Size, Share, and Industry Trends Forecast 2026-2036
Femoral Head Prostheses Market Intelligence
Customer concentration within large hospital purchasing groups and orthopedic clinic networks is hardening supplier selection criteria, favoring established vendors. Zimmer Biomet Holdings leverages its extensive product portfolio and deep surgeon relationships to maintain a dominant market position. Stryker competes through its Mako robotic-assisted surgery platform, which integrates with the company's implant offerings. Smith & Nephew differentiates with advanced material sciences, including its OXINIUM oxidized zirconium for improved implant longevity.
A femoral head prosthesis is an orthopedic implant that replaces the natural femoral head in hip arthroplasty procedures. These components are engineered with specific head diameters and neck taper geometries to ensure stable articulation within an acetabular cup. Ceramic materials are gaining share over cobalt chromium due to superior wear resistance and biocompatibility, especially in younger, active patients. Modular designs provide surgeons greater intraoperative flexibility for adjusting fit compared to monoblock types, driving their use in complex cases.
Regulatory oversight from bodies like the U.S. FDA, Europe's EMA under the MDR, and China's NMPA mandates stringent clinical data and post-market surveillance. These requirements directly influence material selection, manufacturing processes, and the cost of market entry for new devices. Manufacturers must now decide whether to invest in next-generation smart implants with embedded sensors or focus on cost optimization for value-based healthcare models.
Market Dynamics
The market's central dynamic is the tension between the clinical demand for advanced, durable materials like ceramics for younger patients and the economic pressure from value-based healthcare models, which scrutinizes the cost-effectiveness of every component choice.
Growth Catalysts
- Advanced Materials:The development of third-generation ceramic composites with enhanced fracture toughness and wear resistance is expanding their application in active patient populations, driving a segment of premium-priced device adoption.
- Aging Demographics:An increasing prevalence of osteoarthritis and hip fractures in the aging populations of developed nations, particularly in countries like Germany and Japan, provides a consistent volume of primary hip arthroplasty procedures.
- Ambulatory Surgical Centers:A procedural shift towards outpatient settings, enabled by minimally invasive surgical techniques and favorable reimbursement policies, is expanding the addressable market for femoral head prostheses outside of traditional hospital environments.
Market Restraints
- Regulatory Scrutiny:The European Union's Medical Device Regulation (MDR) imposes stringent requirements for clinical evidence and post-market surveillance, increasing the time and cost for manufacturers to bring new materials or designs to market.
- Price Pressurization:Large hospital purchasing groups and integrated delivery networks leverage their volume to negotiate lower prices, compressing margins for manufacturers, especially for standard cobalt-chromium and stainless steel components.
- Surgeon Training and Inertia:The successful adoption of novel implant systems, especially those paired with robotic platforms, requires significant investment in surgeon training, creating a barrier to rapid displacement of established techniques and products.
Strategic Opportunities
- Smart Implants:Integrating microsensors into femoral heads to monitor implant stability, joint loading, and infection risk post-surgery presents a significant opportunity to improve patient outcomes and provide valuable data for clinicians.
- Emerging Market Penetration:Expanding access to hip arthroplasty in large, underserved markets such as Brazil and India through the introduction of cost-effective, reliable implant systems offers substantial volume growth potential.
- Revision Procedure Specialization:Developing modular femoral head and neck systems specifically designed for complex revision arthroplasty addresses a growing clinical need as the population of patients with primary implants ages.
Industry Challenges
- Material Supply Chain:Securing a stable, high-purity supply of raw materials for advanced ceramics, such as zirconia and alumina, presents a challenge due to a concentrated supplier base and high qualification costs.
- Interoperability Standards:A lack of standardization for taper geometries between femoral stems and heads from different manufacturers complicates inventory management for hospitals and limits surgeon choice during revision procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Femoral Head Prostheses Market |
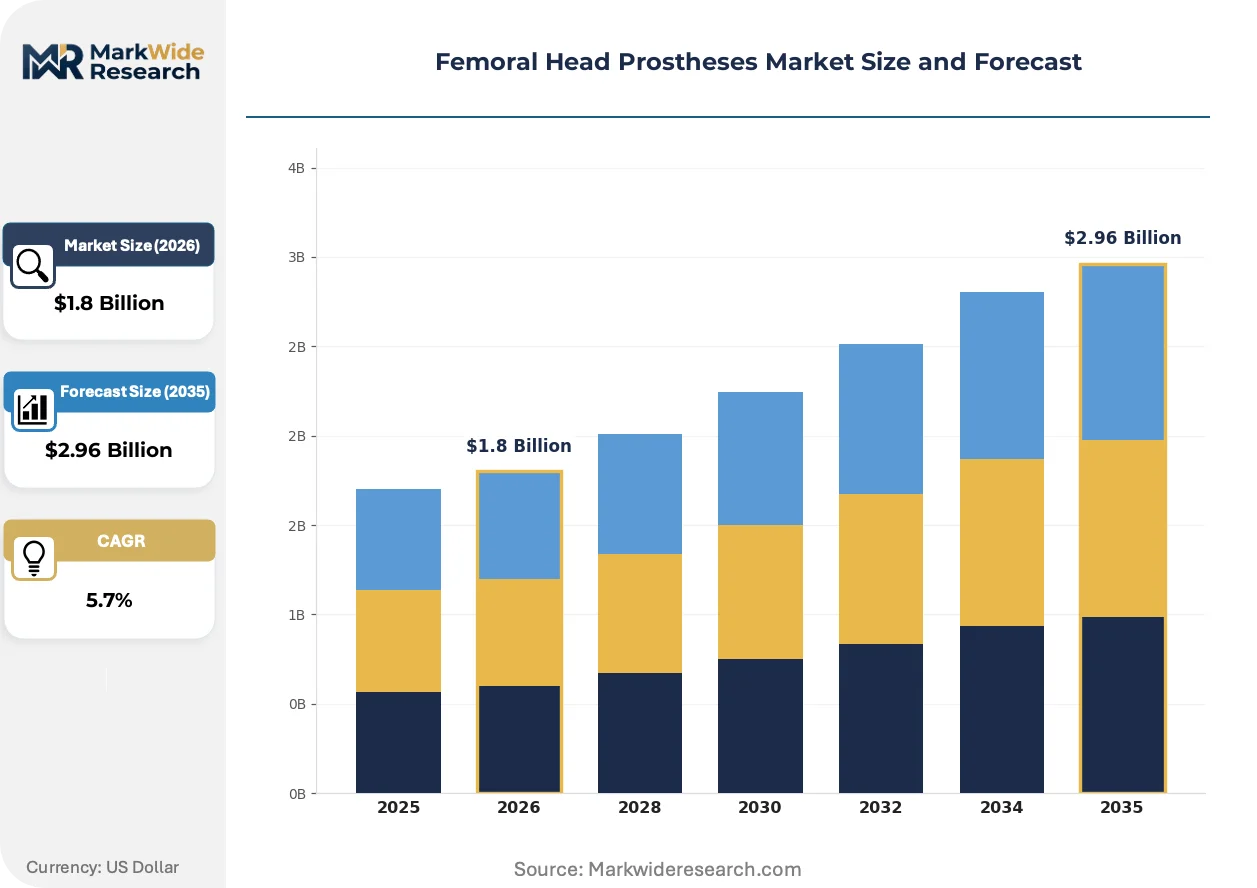
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Ceramic, Cobalt Chromium, Stainless Steel, Titanium Alloy Design Type: Monoblock, Modular, Bipolar, Unipolar Application: Osteoarthritis Treatment, Rheumatoid Arthritis Care, Hip Fracture Repair, Bone Tumor Reconstruction End User: Orthopedic Clinics, Rehabilitation Centers, Specialty Surgical Hospitals, Ambulatory Surgical Centers |
| Companies Covered | Zimmer Biomet Holdings, Stryker, Johnson & Johnson, Smith & Nephew, Corin Group, Medacta International, Exactech, DePuy Synthes, Amplitude SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Femoral Head Prostheses Market Strategic Shifts & Innovations
Material science advancements are intersecting with data-driven surgical planning and stricter regulatory oversight. This convergence is forcing manufacturers to innovate not just on the implant itself but also on the clinical evidence and procedural integration supporting it.
Additive manufacturing enables the creation of implants with porous structures that encourage bone ingrowth for improved fixation. Orthopedic surgeons in specialized centers are adopting these 3D-printed components for complex primary and revision hip arthroplasty. This personalized manufacturing approach is converging with advanced material science, allowing for the creation of functionally graded materials within a single component.
The U.S. FDA's focus on real-world evidence (RWE) is influencing device development and post-market requirements. This regulatory expectation compels manufacturers to systematically collect and analyze data from patient registries and electronic health records to support device performance claims. The segment most affected is next-generation implants, which must now be designed with a clear strategy for data collection from the outset.
Buying patterns within large hospital networks are shifting from component-level purchasing to a focus on procedural episodes. This change concentrates decision-making power with hospital administrators who evaluate implants based on their contribution to reducing revision rates and overall episode-of-care costs. This value-based procurement is most visible in the United States' integrated delivery networks, where it directly impacts vendor selection.
Femoral Head Prostheses Market Segmentation
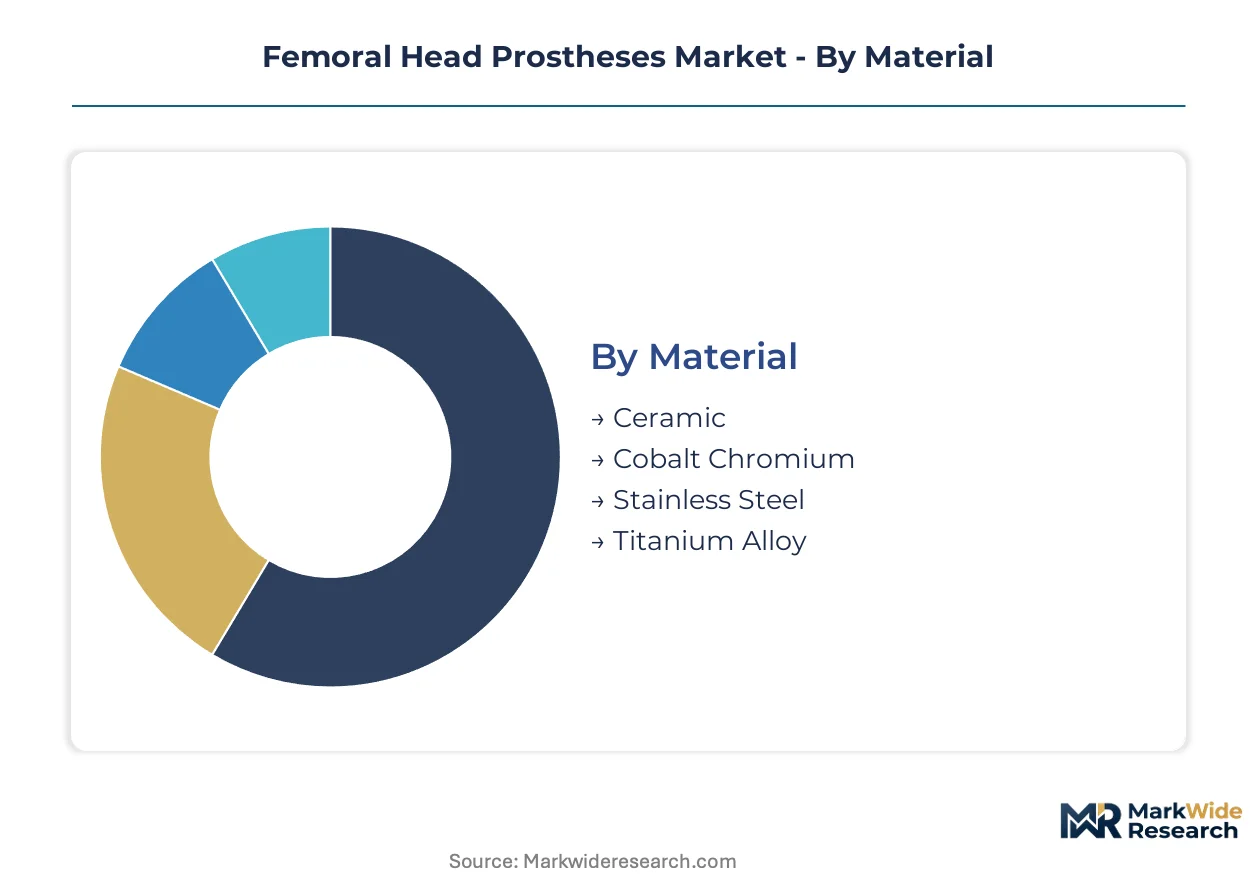
Segmentation reveals the diverse needs driving femoral head prostheses adoption, from material preferences to end-user settings. Understanding these distinct market components helps manufacturers tailor product development and distribution strategies. It also highlights areas of concentrated demand and emerging growth opportunities for stakeholders.
Material:
Supply chain dynamics significantly influence material choices for femoral head prostheses, impacting both cost and performance characteristics.
- Ceramic:These prostheses utilize advanced alumina and zirconia, offering superior wear resistance and biocompatibility. Demand concentrates in Germany and Japan, driven by younger, active patients seeking long-term implant longevity.
- Cobalt Chromium:This traditional alloy provides strength and durability, commonly used in total hip arthroplasty due to its established clinical history. Procurement is concentrated in large hospital groups, where cost-effectiveness remains a primary driver.
- Stainless Steel:These implants offer a cost-effective solution for hip replacement, primarily utilized in regions with budget constraints or for less active patient populations.
- Titanium Alloy:Titanium alloys provide excellent biocompatibility and osseointegration, often used with porous coatings for enhanced bone ingrowth and fixation.
Cobalt Chromium absorbs the bulk of installed capacity; Ceramic is expanding most quickly.
Design Type:
Surgical requirements and patient-specific needs dictate selection among various femoral head prosthesis design types.
- Modular:These designs feature separate head and neck components, allowing surgeons to adjust leg length and offset intraoperatively for optimal fit. Orthopedic clinics increasingly adopt modular systems for complex primary and revision cases.
- Monoblock:Comprising a single, integrated head and neck unit, monoblock prostheses offer a straightforward implantation process and reduced taper corrosion risk. These are chosen for primary hip arthroplasty prioritizing surgical simplicity and cost-efficiency.
- Bipolar:Bipolar designs incorporate two articulating surfaces for greater range of motion, primarily used in hemiarthroplasty for hip fractures in elderly patients.
- Unipolar:Unipolar femoral heads feature a single articulating surface, typically used in hemiarthroplasty procedures for specific patient demographics and fracture patterns.
Clinical preference for enhanced intraoperative flexibility drives modular design adoption, while monoblock types maintain relevance for simplicity.
Application:
The volume of surgical procedures for femoral head prostheses varies significantly across different clinical applications, reflecting distinct patient demographics.
- Osteoarthritis Treatment:This application addresses degenerative joint disease, the most common reason for total hip replacement, especially in aging populations. Demand is consistently high across developed nations, including the United States, where long-term durability is paramount.
- Hip Fracture Repair:Femoral head prostheses are critical for restoring mobility after severe hip fractures, particularly in elderly patients. Ambulatory surgical centers and specialty hospitals frequently perform these procedures, focusing on rapid recovery.
- Rheumatoid Arthritis Care:This application involves replacing damaged femoral heads in patients with inflammatory autoimmune conditions, often requiring specialized implant designs.
- Bone Tumor Reconstruction:Femoral head prostheses are used in oncological surgery to replace bone resected due to tumors, demanding customized implant solutions.
Osteoarthritis treatment represents the largest clinical burden for hip arthroplasty, with hip fracture repair also contributing substantial procedural volumes.
End User:
The evolving healthcare delivery landscape shapes procurement patterns and procedural volumes for femoral head prostheses across various end-user facilities.
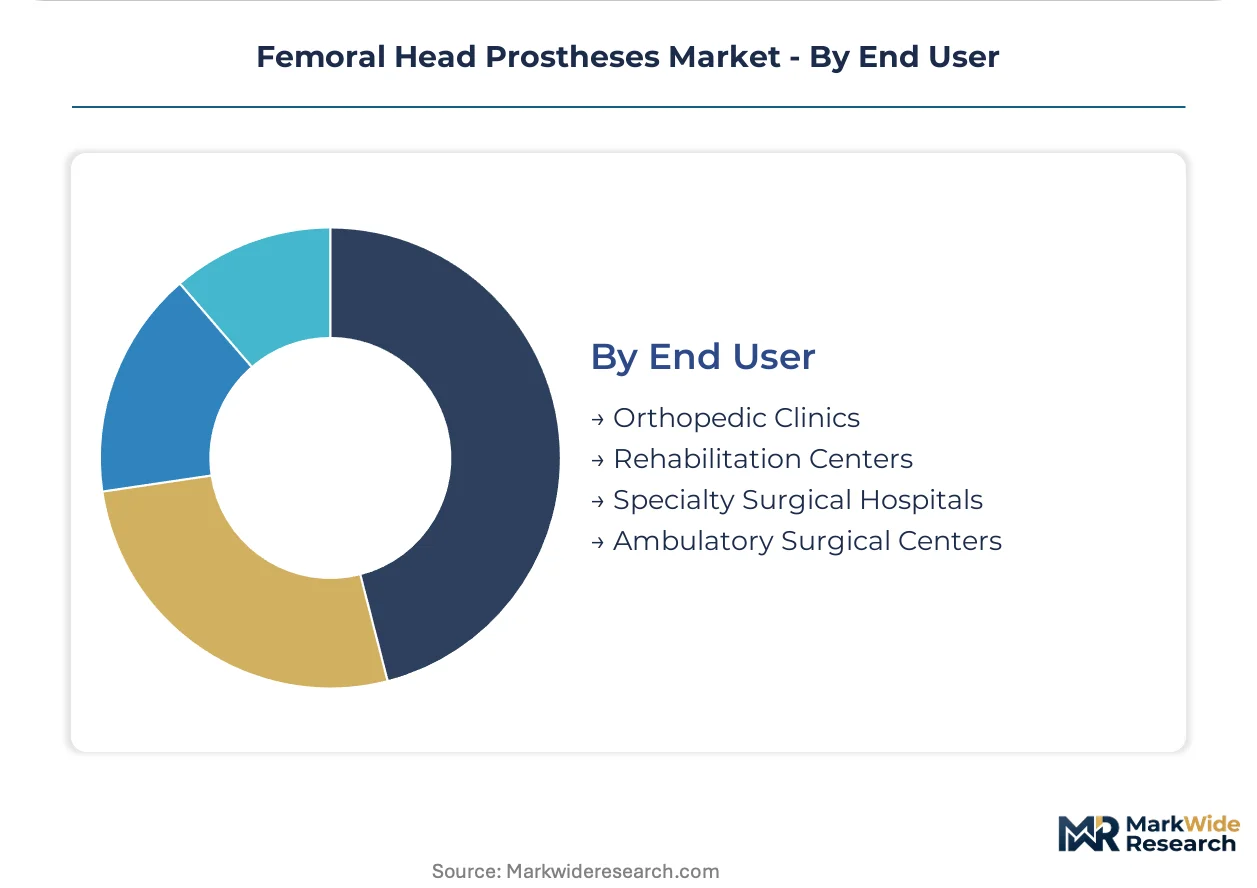
- Specialty Surgical Hospitals:These facilities specialize in orthopedic procedures, performing high volumes of complex primary and revision hip arthroplasties. They prioritize premium implant systems offering superior patient outcomes.
- Ambulatory Surgical Centers:ASCs increasingly perform outpatient hip replacement procedures, driven by cost-effectiveness and favorable reimbursement. The shift towards ASCs in the United States expands the market for efficient prostheses.
- Orthopedic Clinics:These clinics primarily focus on diagnosis and non-surgical treatment, referring patients for hip arthroplasty and influencing implant selection through surgeon preference.
- Rehabilitation Centers:These centers focus on post-operative care and physical therapy, playing a crucial role in patient recovery but not directly purchasing femoral head prostheses.
Specialty Surgical Hospitals remain core to complex arthroplasty, while Ambulatory Surgical Centers are experiencing the steepest expansion trajectory for routine procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for femoral head prostheses is particularly pronounced in developed economies with aging populations. These regions face a high incidence of osteoarthritis and hip fractures, driving consistent procedural volumes. Healthcare infrastructure and reimbursement policies also significantly influence market dynamics across various geographies.
Germany
Germany exhibits strong demand for femoral head prostheses, driven by its aging population and high healthcare spending. The EU's Medical Device Regulation (MDR) imposes rigorous standards, influencing material selection. Bavaria's medical technology cluster actively develops advanced ceramic materials, fostering innovation in implant design.
Japan
Japan's rapidly aging demographics contribute to consistent hip arthroplasty volumes, particularly for osteoarthritis treatment. The PMDA ensures strict oversight of implant approvals, emphasizing safety and long-term efficacy. Tokyo's medical device industry drives innovation in modular designs and ceramic materials.
United States
The United States represents a substantial market for femoral head prostheses, fueled by a large patient pool requiring osteoarthritis treatment. U.S. FDA regulations mandate stringent clinical data, impacting device development. Indiana, a prominent orthopedic device manufacturing hub, focuses on advanced material research and robotic surgery integration.
China
China offers significant growth potential as healthcare infrastructure expands and access to advanced medical treatments improves for its vast population. The NMPA enforces strict approval processes, shaping local manufacturing standards. The Yangtze River Delta region is home to a burgeoning medical device industry, developing cost-effective and reliable implant systems.
India
India presents an emerging market for femoral head prostheses, driven by increasing healthcare investment and a large, underserved patient base. The CDSCO regulates medical device approvals, ensuring quality and affordability for domestic patients. Gujarat's medical device manufacturing sector is expanding, focusing on cost-effective solutions for local markets.
Femoral Head Prostheses Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue advanced material innovation and digital integration within the femoral head prostheses market. The market exhibits a tiered structure, with a few large, diversified players dominating the premium segment and numerous smaller firms specializing in cost-effective or niche solutions. Strategic archetypes include global orthopedic giants, specialized material science innovators, and regional manufacturers focusing on value-based care. Companies primarily engage in strategic acquisitions to expand product portfolios and form partnerships to integrate robotic surgical platforms.
Global orthopedic giants like Zimmer Biomet Holdings and Stryker exemplify comprehensive market coverage, leveraging extensive product portfolios and integrated surgical solutions. Smith & Nephew occupies a position as a material science innovator, focusing on advanced surface technologies for improved implant longevity. These entities anchor the market's premium and mid-tier segments, influencing product development trajectories and setting industry benchmarks. Their presence underscores the importance of established clinical relationships and continuous R&D investment in maintaining market relevance.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings |
| Stryker |
| Johnson & Johnson |
| Smith & Nephew |
| Corin Group |
| Medacta International |
| Exactech |
| DePuy Synthes |
| Amplitude SAS |
| Others |
Cost & Logistics Intelligence
The alumina price index, a critical input for advanced ceramics, cascades through the femoral head prostheses supply chain, influencing the premium pricing of ceramic components versus traditional alloy tiers.
Pricing Analysis
The femoral head prostheses market exhibits a clear volume-driven versus margin-focused split, with standard alloy components competing on cost and advanced ceramics commanding premium prices. Pricing stratifies across premium, standard, and economy levels based on material quality and advanced design features. Price differentiation stems from material science advancements like OXINIUM oxidized zirconium and integration with robotic platforms. Pricing pressure intensifies for commodity components due to large hospital purchasing groups. Specialty surgical hospitals are less price-sensitive for premium implants, while Ambulatory Surgical Centers prioritize cost-efficiency for routine procedures.
Supply Chain Analysis
Domestic content mandates, such as those encouraged by China's NMPA, are reshaping sourcing strategies for femoral head prostheses, pushing for localized manufacturing of cost-effective implant systems. Supply primarily draws from China and India for cost-effective solutions, while Germany and Japan focus on advanced ceramic production. Raw material dependencies include high-purity alumina and zirconia, alongside cobalt chromium. Single-source vulnerability for specialized ceramic powders presents a structural risk. Distribution runs through established channels like large hospital groups and orthopedic clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The femoral head prostheses market operates as a cost-of-compliance story, where the stringent requirements of the EU Medical Device Regulation (MDR) create a significant barrier to entry for non-compliant manufacturers.
For Market Incumbents: Deepen investment in advanced material R&D, particularly in ceramic composites, to counter potential displacement by novel materials. Strengthen surgeon relationships through comprehensive training on new robotic-assisted platforms. This strategy mitigates margin pressure from large purchasing groups for standard components. Focus R&D on smart implants with embedded sensors to maintain a competitive edge.
For New Entrants and Emerging Players: Enter via underserved emerging markets like India, focusing on cost-effective yet reliable implant systems for primary hip arthroplasty. Target niche applications such as bone tumor reconstruction requiring customized implant solutions. A go-to-market angle involves strategic partnerships with local healthcare providers and distributors. This approach allows penetration where established players have less presence or cost-sensitivity is higher.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized material science innovators in Europe, particularly those navigating complex regulatory pathways for next-generation ceramics. The long-term viability of this market remains strong, driven by persistent demand from aging populations globally. Target acquisition archetypes include companies developing additive manufacturing capabilities for personalized implants. A key signal to watch is an uptick in M&A activity for firms specializing in digital integration with surgical planning software.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material Development | Enhances implant longevity and biocompatibility, crucial for younger, active patients in Germany. |
| Robotic-Assisted Surgery Integration | Improves surgical precision and outcomes, attracting orthopedic clinics and specialty hospitals in the United States. |
| Emerging Market Localized Production | Expands access to cost-effective solutions for large, underserved patient bases in countries like India. |
| Smart Implant Sensor Integration | Provides post-operative data on stability and loading, improving patient monitoring and clinical decision-making. |
| Modular Revision System Design | Addresses complex clinical needs in revision arthroplasty, offering surgeons greater intraoperative flexibility. |
Research Approach
Independent corroboration across U.S. FDA public databases, EMA post-market surveillance reports, and NMPA approval registries underwrites the qualitative findings of this market analysis. This approach combines primary interviews with industry stakeholders and secondary validation. Stakeholders included orthopedic surgeons, hospital procurement managers, R&D directors at major manufacturers, and regulatory affairs specialists. Bottom-up and top-down triangulation ensured data integrity and comprehensive market understanding.
Anchoring the forecast window to comparable historical periods provided a robust foundation for projecting market trajectories across the modeling period. The analytical framework modeled segmentation dimensions including material type, design type, application, end-user, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected market dynamics. Key forecast inputs included orthopedic procedure volumes and advanced ceramic material adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory shifts or significant material supply chain disruptions. Forecasts reflect assumptions regarding technological advancements and healthcare expenditure trends. Unforeseen global economic downturns or shifts in reimbursement policies could revise these projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market
Orthopedic Devices
Polyethylene Orthopaedic Insert Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
3D Orthopedic Scanning System Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Computer-Assisted Orthopedic Surgery Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
North America Knee Cartilage Repair Market