
 Hip Reconstruction Devices Market | 2026-2036
Hip Reconstruction Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Hip Reconstruction Devices Market Outlook
Market Context
Ceramic-on-polyethylene bearing surfaces is hardening as the default construct for primary total hip arthroplasty, displacing metal-on-metal configurations that faced elevated revision rates. Zimmer Biomet leverages its comprehensive portfolio spanning cementless stems and patient-specific instrumentation to sustain share in academic medical centers. Stryker Corporation anchors its position through proprietary additive manufacturing capabilities for porous titanium acetabular shells. Smith & Nephew competes via its polished double-taper stem design and direct anterior surgical approach specialization.
Technical Definition and Segment Structure
Hip reconstruction devices comprise implantable prosthetic systems—femoral stems, acetabular cups, bearing liners, and modular heads—fabricated from cobalt-chrome alloys, alumina ceramic, ultra-high molecular weight polyethylene, or oxidized zirconium, designed to restore biomechanical function following degenerative joint disease or fracture. Total hip replacement generates the dominant revenue pool, while revision hip surgery commands premium pricing due to operative complexity and specialized implant geometries. Cementless implant technology leads volume in primary procedures, though hybrid constructs retain significant share in osteoporotic patient populations where initial mechanical stability remains uncertain.
Regulatory Framework and Outlook
The FDA's 510(k) clearance pathway and subsequent post-market surveillance through the MAUDE database govern product entry and long-term safety monitoring, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class III implantable devices. The BIS certification mandate and CDSCO registration timeline shape market access dynamics for multinational manufacturers seeking Indian commercialization. Stakeholders must monitor evolving payer policies on outpatient total joint replacement bundled payments and the trajectory of robotic-assisted surgical platform integration.
Market Dynamics
The migration toward same-day discharge protocols is compressing implant selection criteria toward constructs with demonstrated early stability and reduced complication profiles, reshaping how manufacturers prioritize bearing surface validation and surgical technique support.
Growth Catalysts
- Outpatient Procedure Coverage:Commercial payers in the United States are expanding bundled payment authorization for ambulatory surgical centers, accelerating volume shifts away from inpatient settings.
- Ceramic Bearing Adoption:Alumina and oxidized zirconium bearing surfaces are displacing metal-on-metal configurations following elevated revision rate documentation in FDA post-market surveillance.
- Aging Demographics:Osteoarthritis prevalence among populations over sixty-five is concentrating procedure demand in markets with established reimbursement infrastructure.
Market Restraints
- Cobalt-Chrome Supply Concentration:Foundry capacity for medical-grade alloys concentrates in a limited supplier base, exposing manufacturers to input cost volatility and allocation risk.
- EU MDR Compliance Burden:The Medical Device Regulation imposes extended clinical evidence requirements for Class III implantable devices, lengthening registration timelines and elevating regulatory expenditure.
- Bone Cement Substitution Pressure:Cementless fixation technology is capturing share in primary procedures, compressing demand for polymethyl methacrylate bone cement in younger patient cohorts.
Strategic Opportunities
- Robotic-Assisted Platform Integration:Computer-navigated implant positioning is converging with patient-specific instrumentation to enable ambulatory surgical center penetration.
- Indian Market Access:BIS certification and CDSCO registration pathways, once navigated, open access to a volume market with underpenetrated joint replacement utilization relative to disease burden.
- Direct Anterior Approach Specialization:Surgical technique training and instrument configuration for muscle-sparing approaches represent differentiable service layers beyond implant hardware.
Industry Challenges
- Revision Surgery Technical Complexity:Bone loss management and implant extraction in secondary procedures demands specialized stem geometries and augments, complicating inventory and surgeon training.
- Cross-Border Regulatory Divergence:Reconciliation of FDA 510(k) clearance data with EU MDR clinical evidence requirements creates redundant study expenditure and timeline misalignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hip Reconstruction Devices Market |
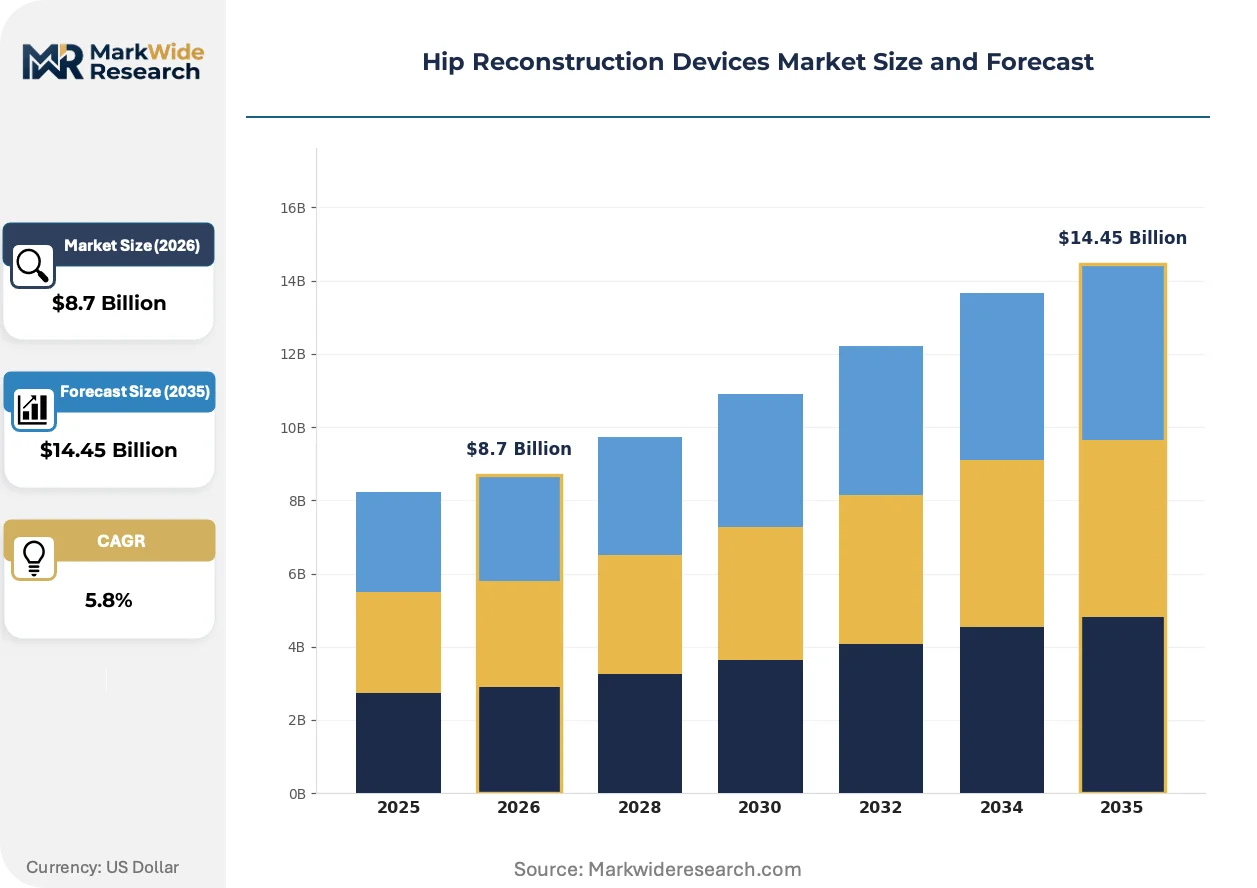
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Total Hip Replacement, Partial Hip Replacement, Hip Resurfacing, Revision Hip Surgery Material: Metal, Ceramic, Polymer, Composite End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Ambulatory Surgical Centers Technology: Cemented Implants, Cementless Implants, Hybrid Implants, Patient-Specific Implants |
| Companies Covered | Zimmer Biomet, Stryker Corporation, Johnson & Johnson (DePuy Synthes), Smith & Nephew, B. Braun Melsungen AG, Exactech, Microport Scientific Corporation, Corin, Medacta International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hip Reconstruction Devices Market Strategic Shifts
Additive manufacturing is reshaping acetabular component production, enabling porous titanium architectures that were previously unmachinable. This shift is compressing lead times for patient-matched implants while altering competitive positioning around proprietary fabrication capabilities.
Three-dimensional printing of porous titanium acetabular shells is integrating with preoperative planning software to produce anatomically conforming implants without conventional machining constraints. Academic medical centers with established orthopedic research programs are adopting these constructs for complex primary and revision cases. The technology is integrating surgical workflow efficiency with biomechanical customization, compressing the advantage of standardized implant inventories.
The EU Medical Device Regulation is mandating post-market clinical follow-up studies for hip arthroplasty systems, elevating evidence generation obligations beyond premarket submission requirements. Manufacturers must now maintain active surveillance registries and periodic safety update reports across their European device portfolios. Revision hip systems and novel bearing couples face the steepest compliance burden, driving consolidation of product lines toward proven construct configurations.
Hospital purchasing coalitions are consolidating implant procurement decisions through value-analysis committees, displacing individual surgeon preference as the dominant selection criterion. Integrated delivery networks in the United States are negotiating single-source contracts for total joint episodes, compressing vendor access to operating room access. This concentration is most visible in metropolitan markets where health system consolidation has produced dominant regional purchasers with substantial volume leverage.
Hip Reconstruction Devices Market Segmentation
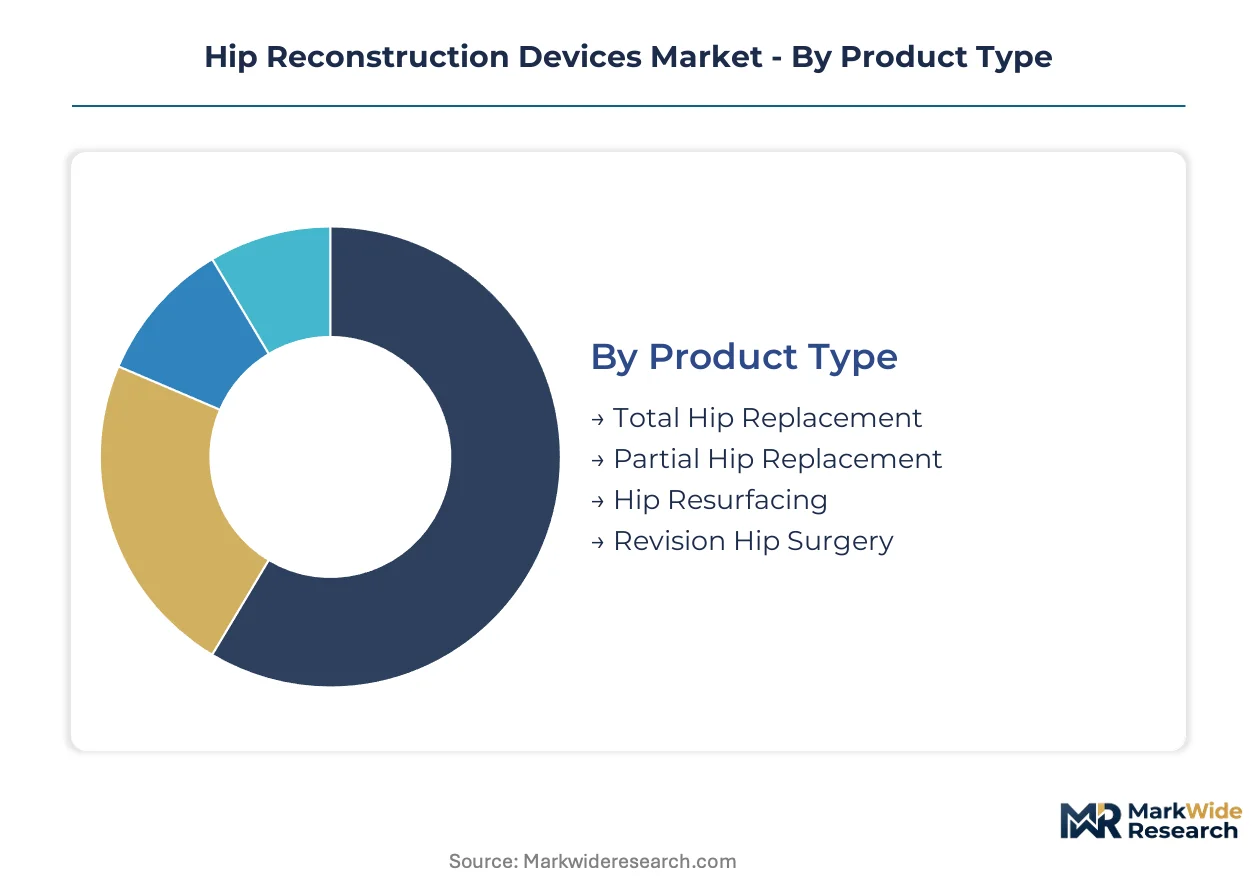
Segmentation in hip reconstruction devices reveals how clinical requirements, patient demographics, and surgical settings fragment demand across incompatible technical specifications. Manufacturers must align portfolio depth with the specific stability, bearing surface, and fixation demands of each procedure type and care environment.
Product Type:
Ceramic-on-polyethylene bearing surfaces and modular stem geometries define competitive differentiation across procedure categories.
- Total Hip Replacement:Complete femoral and acetabular reconstruction using cementless stems with porous titanium coatings and cross-linked polyethylene liners. Demand concentrates in the United States within ambulatory surgical centers where same-day discharge protocols favor demonstrated early stability.
- Revision Hip Surgery:Complex secondary procedures requiring specialized tapered stems, augments, and allograft bone for managing bone loss and implant extraction. Academic medical centers in Germany and the United States generate volume where fellowship-trained surgeons handle operative complexity.
- Partial Hip Replacement:Femoral head replacement preserving native acetabulum, typically for displaced femoral neck fractures in elderly patients.
- Hip Resurfacing:Bone-conserving femoral head capping with metal-on-metal or ceramic bearings, limited to younger active males with adequate bone stock.
Mature deployment sits with Total Hip Replacement. Newer deployment is concentrated in Revision Hip Surgery.
Material:
Material selection traces directly to FDA post-market surveillance outcomes and EU MDR biocompatibility documentation requirements.
- Ceramic:Alumina and oxidized zirconium bearing surfaces deliver superior wear characteristics and reduced osteolysis risk compared to metal alternatives. German and Japanese orthopedic centers drive adoption where long-term implant survival data supports premium positioning.
- Polymer:Cross-linked ultra-high molecular weight polyethylene liners dominate bearing surface volume due to cost accessibility and established clinical track records. United States hospital purchasing coalitions favor this construct for standard primary procedures.
- Metal:Cobalt-chrome alloys remain essential for femoral heads and stems despite bearing surface displacement, constrained by foundry supply concentration.
- Composite:Carbon fiber-reinforced PEEK and bioactive glass composites occupy niche applications in tumor prostheses and custom implants.
Volume leadership belongs to Polymer. Steepest expansion trajectory is Ceramic.
End User:
Site-of-care economics and reimbursement authorization reshape procurement authority and implant selection criteria.
- Hospitals:Inpatient joint replacement programs retain complex primary and revision case volume where extended recovery monitoring is required. United States integrated delivery networks concentrate purchasing decisions through value-analysis committees.
- Ambulatory Surgical Centers:Same-day discharge protocols demand constructs with demonstrated early stability and reduced complication profiles. Commercial payer bundled payment expansion in the United States accelerates volume migration to this setting.
- Orthopedic Clinics:Preoperative planning and postoperative rehabilitation services without implant provision.
- Rehabilitation Centers:Post-acute recovery and physical therapy following hospital or ASC discharge.
Procurement authority is consolidating in Hospitals. Fastest volume shift is Ambulatory Surgical Centers.
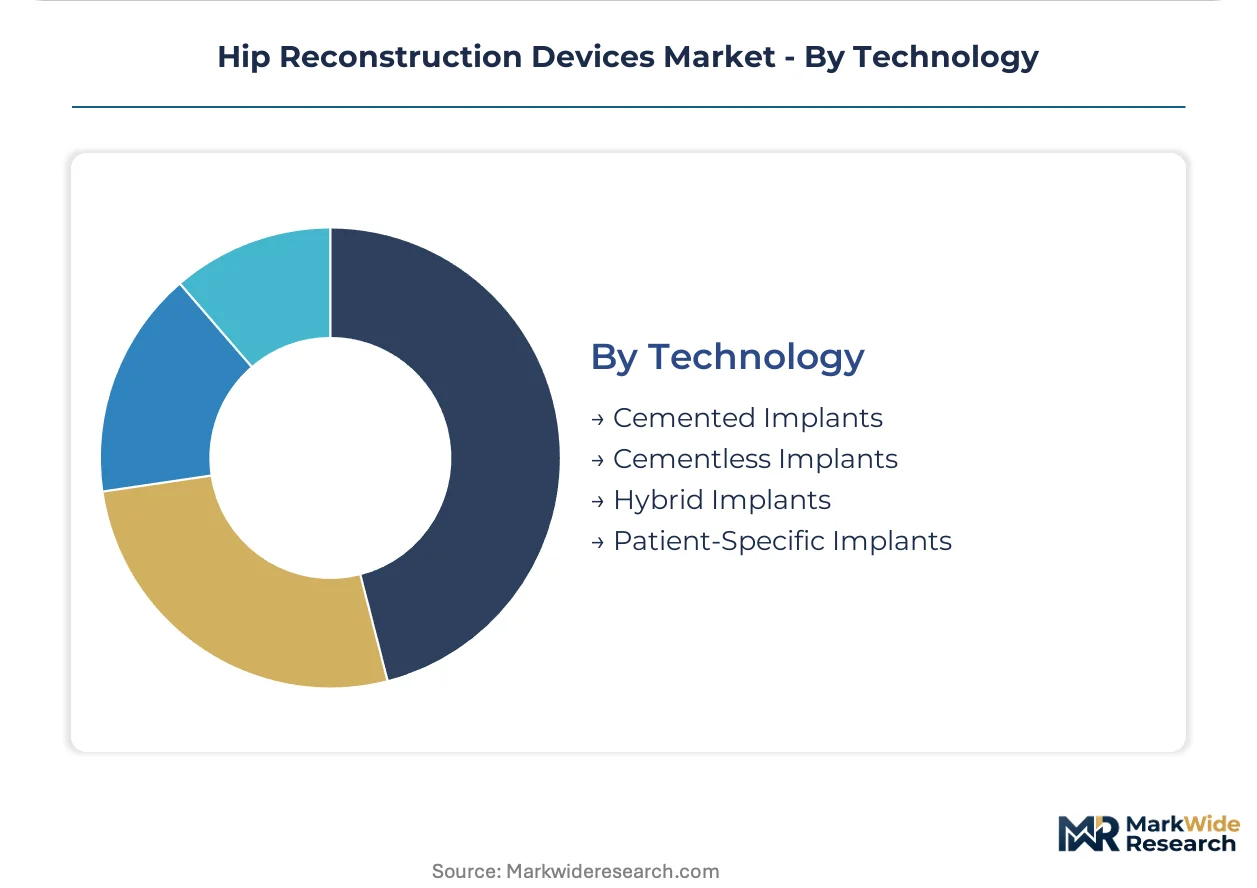
Technology:
Fixation philosophy and manufacturing method determine inventory requirements and surgeon training investment.
- Cementless Implants:Porous titanium or cobalt-chrome surfaces enable biological osseointegration without polymethyl methacrylate bone cement. Younger patient cohorts in Australia and South Korea favor this technology for anticipated longer implant survival.
- Patient-Specific Implants:Additive-manufactured acetabular shells and cutting guides derived from preoperative CT planning. Academic medical centers in the Netherlands and Switzerland adopt these for complex primary and revision anatomies.
- Cemented Implants:Polymethyl methacrylate fixation for osteoporotic bone where initial mechanical stability is uncertain.
- Hybrid Implants:Cementless acetabular components with cemented femoral stems, balancing biological fixation with immediate stability.
Standard practice centers on Cementless Implants. Technical innovation is concentrating in Patient-Specific Implants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device manufacturing concentrates in tax-advantaged zones near major orthopedic research clusters. United States-based production leverages FDA premarket approval pathways and proximity to academic medical centers. European operations navigate EU MDR compliance through established notified body relationships. Asian expansion targets volume markets with localized registration strategies.
United States
Ambulatory surgical centers drive demand concentration through same-day discharge protocols. FDA 510(k) clearance pathways and MAUDE post-market surveillance govern product entry. Warsaw, Indiana anchors domestic manufacturing with dense supplier networks for cobalt-chrome alloys and porous titanium coatings.
Germany
Academic medical centers in Berlin and Munich generate revision surgery volume requiring specialized implant geometries. EU MDR Class III device requirements impose extended clinical evidence obligations. The Rhine-Ruhr industrial corridor hosts precision foundry capacity for medical-grade alloys serving European OEMs.
Switzerland
Swissmedic registration timelines and premium reimbursement structures attract high-value implant innovation. Patient-specific instrumentation development concentrates near Lake Geneva research institutes. The Basel-Zurich corridor integrates additive manufacturing with orthopedic biomechanics research.
India
CDSCO registration and BIS certification shape market access for multinational manufacturers. Government PLI scheme incentives localize production for cost-sensitive segments. Mumbai-Pune and Delhi-NCR clusters develop domestic foundry capacity for cobalt-chrome medical alloys.
Australia
TGA approval pathways and public hospital procurement frameworks concentrate demand. Cementless fixation technology adoption runs ahead of global averages in Sydney and Melbourne orthopedic centers. The Therapeutic Goods Administration's post-market vigilance system generates long-term implant survival data.
Hip Reconstruction Devices Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates around integrated orthopedic portfolios and specialized revision component suppliers. Three archetypes dominate: diversified medical technology conglomerates with comprehensive hip portfolios, mid-cap specialists with single-procedure focus, and Asian manufacturers with cost-optimized primary implant lines. Competitive moves center on robotic-assisted surgical platform partnerships and additive manufacturing capacity expansion.
Among diversified orthopedic conglomerates, Zimmer Biomet and Stryker Corporation occupy positions reflecting comprehensive hip reconstruction portfolios spanning cementless stems, acetabular systems, and bearing surface technologies. Smith & Nephew represents the specialist archetype with focused expertise in surgical approach-specific instrumentation. These three entities exemplify distinct strategic vectors: scale-driven manufacturing integration, proprietary fabrication technology ownership, and muscle-sparing surgical technique specialization.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker Corporation |
| Johnson & Johnson (DePuy Synthes) |
| Smith & Nephew |
| B. Braun Melsungen AG |
| Exactech |
| Microport Scientific Corporation |
| Corin |
| Medacta International |
| Others |
Value Chain & Pricing Dynamics
Orthopedic biomechanical engineers concentrated in Warsaw, Indiana and the Rhine-Ruhr corridor command wage premiums that translate directly into spreads between premium ceramic-bearing constructs and economy-tier metal-on-polyethylene alternatives. Labor-cost differentials between these specialized manufacturing clusters and emerging production hubs in India widen pricing-tier dispersion as manufacturers balance FDA-validated quality systems against cost-sensitive market entry.
Pricing Analysis
Volume concentrates in standard primary total hip constructs while margins accrue to revision systems and patient-specific implants. Three-tier pricing structure across premium ceramic-bearing, standard cross-linked polyethylene, and economy metal-on-metal levels reflects certification-grade differentiation and surgical complexity. Pricing pressure stems from hospital purchasing coalition consolidation in United States metropolitan markets. Ambulatory surgical centers exhibit highest price sensitivity due to bundled payment constraints, while academic medical centers prioritize demonstrated implant survival data over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand while specialized distributors serve ambulatory surgical centers and independent orthopedic practices. Manufacturing concentrates in United States, Germany, and Switzerland for precision-machined components, with India developing domestic foundry capacity under PLI scheme incentives. Supply chains draw from cobalt-chrome alloy feedstock, alumina ceramic blanks, and porous titanium powder. Single-source vulnerability concentrates in medical-grade cobalt-chrome foundry capacity. Distribution runs through GPO-negotiated contracts and direct OEM relationships with health system value-analysis committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU MDR Class III device requirements erect substantial barrier-to-entry moats favoring manufacturers with established clinical evidence registries and notified body relationships.
For Market Incumbents: Anchor market position through backward integration into additive manufacturing capacity for porous titanium acetabular shells, securing proprietary fabrication capabilities that emerging competitors cannot replicate without capital-intensive equipment investment. Defend against robotic-assisted surgical platform disruption by embedding implant portfolios within computer-navigated workflow ecosystems. Prioritize EU MDR post-market clinical follow-up registry maintenance as competitive differentiation.
For New Entrants and Emerging Players: Launch via direct anterior approach specialization and muscle-sparing surgical technique training programs, accessing differentiated service layers beyond commodity implant hardware. Target Indian market access through CDSCO registration and BIS certification pathways, leveraging government PLI scheme production incentives for cost-competitive primary implant manufacturing. Pursue white-space in patient-specific instrumentation for complex revision anatomies where established players maintain premium positioning.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing ceramic-bearing surface expertise and established EU MDR technical documentation given regulatory compliance scarcity. Long-term viability across the analysis window favors manufacturers with diversified geographic revenue exposure and ambulatory surgical center channel penetration. Monitor FDA MAUDE database revision rate trajectories for bearing surface technologies as inflection indicator for portfolio construct shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class III compliance unlocks European market access for novel bearing couples. |
| Hospital System Partnership | Integrated delivery network contracts secure operating room access and volume commitments. |
| Additive Manufacturing Scale-Up | Proprietary porous titanium production compresses lead times for patient-matched implants. |
| Reimbursement Strategy | CMS and commercial payer outpatient bundled payment alignment accelerates ASC migration. |
| Software Companion Development | Preoperative planning integration with robotic-assisted platforms differentiates surgical workflow. |
Study Parameters
Multi-period observation of FDA 510(k) clearance trajectories, MAUDE adverse event reporting patterns, and EU MDR registration timelines anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers at academic medical centers, and GPO contracts managers. Secondary validation drew from FDA device databases, EUDAMED registration records, hospital procurement databases, and CMS Medicare claims data. Bottom-up implant volume modeling triangulated against top-down market sizing through manufacturer revenue disclosure analysis.
Input-output matrices mapped procedure volume, bearing surface adoption rates, and site-of-care migration patterns across segmentation dimensions including fixation technology, material composition, end-user setting, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves for ceramic-bearing adoption and outpatient procedure penetration, stress-tested against demographic osteoarthritis prevalence projections and reimbursement policy trajectories. Forecast inputs incorporated EU MDR compliance cost burdens and ambulatory surgical center capital expenditure cycles.
The model assumes a particular technology adoption path for ceramic-on-polyethylene constructs; alternative pathways for oxidized zirconium or novel composite bearings would alter the outlook for material segment shares. Forecasts reflect base-case assumptions regarding FDA post-market surveillance stringency and commercial payer outpatient authorization expansion. Periodic stress-testing of base assumptions against regulatory delay scenarios and supply chain disruption events is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Limb Salvage Systems Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Global Orthopedic Bone Cement Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
Medical Traction Devices Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
India Orthopedic Braces and Supports Market