
 Cranial Orthoses Market | 2026-2036
Cranial Orthoses Market Size, Share, and Industry Trends Forecast 2026-2036
Cranial Orthoses Market Analysis
Specialty clinic networks is reconfiguring how cranial orthoses reach families, shifting volume away from hospital outpatient departments toward independent pediatric orthotic practices. Cranial Technologies leverages proprietary digital scanning systems to control patient intake workflows across multiple metropolitan markets. Boston Orthotics & Prosthetics anchors its position through embedded partnerships with major children's hospital systems. Orthomerica Products competes via broad distributor coverage that extends into secondary and tertiary care markets.
Cranial orthoses are custom-fabricated medical devices, typically vacuum-formed from copolymer thermoplastics over a positive mold generated from 3D surface scans, designed to redirect cranial growth in infants with positional plagiocephaly or craniosynostosis. Their primary purpose is to apply定向 corrective pressure across specific cranial quadrants during the high-growth window of infancy. Helmets dominate product type revenue due to reimbursement alignment and clinical protocol standardization, while bands represent a faster-growing configuration driven by parent preference for lighter, more ventilated designs. Thermoplastics capture the majority of material value, though composite materials are gaining traction where durability and precision molding justify premium positioning.
FDA 510(k) requirements govern device clearance in the United States, while the EU MDR framework imposes stricter clinical evidence and post-market surveillance obligations on European manufacturers. ISO 13485 certification serves as the baseline quality management threshold for export-oriented suppliers across both jurisdictions. Stakeholders must monitor reimbursement policy shifts in Medicaid programs, as coverage variability between states directly determines addressable patient populations and provider willingness to invest in scanning and fabrication infrastructure.
Market Dynamics
Pediatric orthotic specialists are consolidating fabrication workflows through captive digital scanning infrastructure, compressing patient intake cycles and reducing reliance on centralized hospital outpatient departments for mold acquisition.
Growth Catalysts
- Medicaid Expansion:State-level coverage standardization for cranial remolding therapy in the United States is expanding addressable infant populations and incentivizing provider network development.
- ISO 13485 Certification:Quality management system adoption among mid-sized fabricators is unlocking export pathways into EU MDR jurisdictions and accelerating market access timelines.
- Copolymer Thermoplastic Advances:Material science improvements in vacuum-forming substrates are reducing helmet weight and improving ventilation without sacrificing corrective pressure precision.
Market Restraints
- Copolymer Resin Volatility:Petrochemical feedstock price swings directly compress fabrication margins for vacuum-formed orthoses and strain working capital cycles.
- Specialist Concentration:Board-certified pediatric orthotists cluster in major metropolitan corridors, leaving secondary markets underserved and elongating referral travel burdens.
- FDA 510(k) Friction:Premarket notification requirements for design modifications extend product iteration timelines and elevate compliance overhead for custom device manufacturers.
Strategic Opportunities
- Telehealth Integration:Remote scanning protocol adoption creates white space for rural patient capture without physical clinic presence.
- Composite Material Premiumization:Carbon fiber and advanced polymer hybrids enable durability positioning in athletic and active pediatric segments.
- EU MDR Harmonization:Stricter European clinical evidence requirements favor incumbent suppliers with established post-market surveillance infrastructure.
Industry Challenges
- Orthotist Training Pipeline:Accredited residency slots for cranial specialization remain scarce, constraining workforce expansion and patient throughput capacity.
- Legacy CAD/CAM Migration:Small fabrication shops face capital intensity barriers when transitioning from plaster casting to 3D surface scanning systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cranial Orthoses Market |
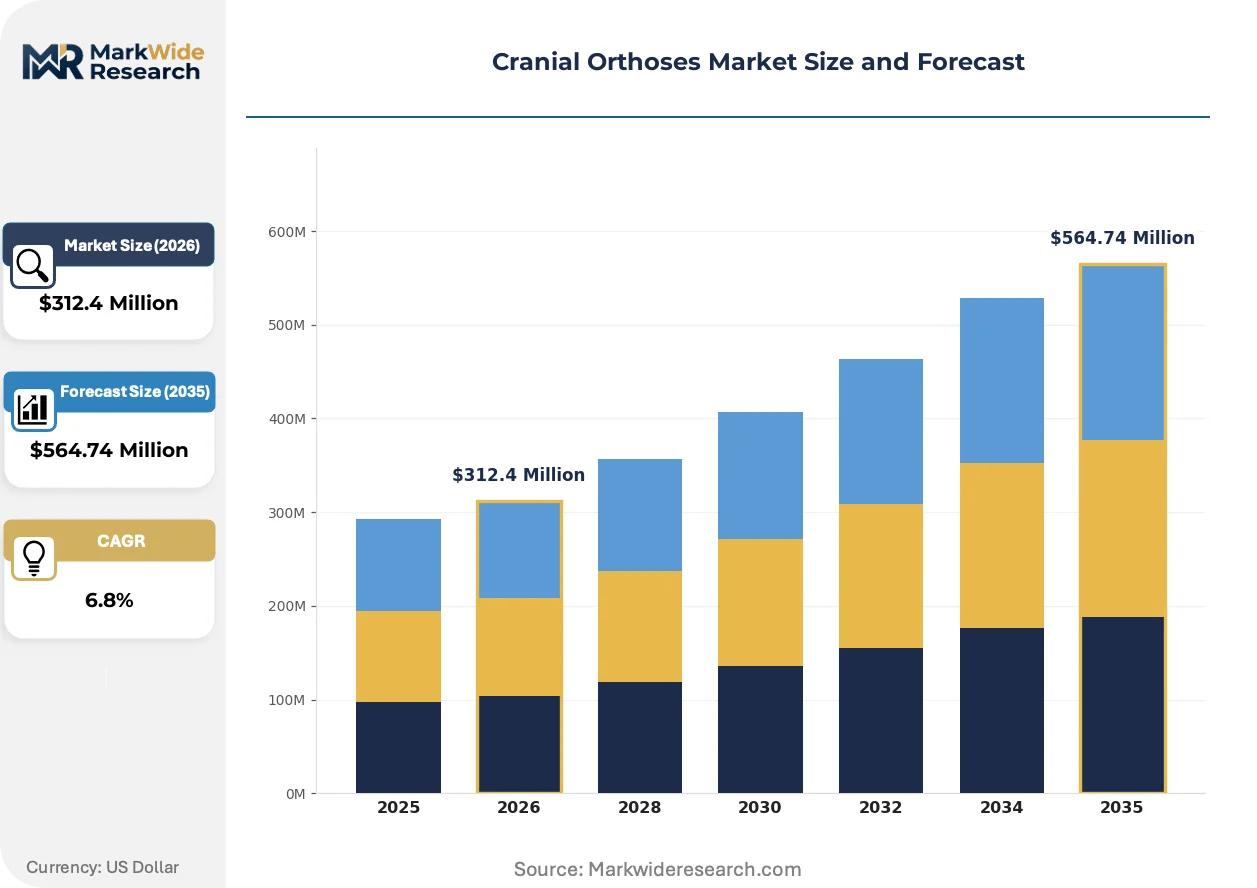
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Caps, Bands, Supports End User: Pediatric Hospitals, Rehabilitation Centers, Home Healthcare, Specialty Clinics Material: Thermoplastics, Foam, Fabric, Composite Materials Distribution Channel: Direct Sales, Online Retail, Distributors, Medical Supply Stores |
| Companies Covered | Boston Orthotics & Prosthetics, Level Four Orthotics & Prosthetics, Cranial Technologies, Ballert Orthopedic, Northern Care, Orthomerica Products, Hanger, Scheck and Siress, Becker Orthopedic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cranial Orthoses Market Emerging Trajectories
Digital capture and additive fabrication methods are displacing traditional plaster-based workflows across pediatric orthotic practices. Three concurrent developments are compressing device production timelines and reshaping competitive positioning.
Structured light scanning is virtualizing the patient intake process for cranial orthoses. Independent pediatric practices deploy handheld 3D capture devices to generate positive molds without physical contact. This compression eliminates shipping delays and plaster storage requirements while enabling same-day fabrication initiation.
EU MDR post-market surveillance obligations are elevating clinical evidence requirements for cranial device manufacturers. European notified bodies now mandate extended follow-up data for pediatric populations. Suppliers with established patient registries and longitudinal tracking infrastructure capture disproportionate share in continental markets.
Parental preference is shifting toward ventilated band configurations over traditional helmet designs. Lighter polymer formulations and open-crown architectures address thermal comfort concerns during extended wear periods. This rotation is most pronounced in United States coastal markets where consumer education levels and specialist density enable informed product selection.
Cranial Orthoses Market Segmentation
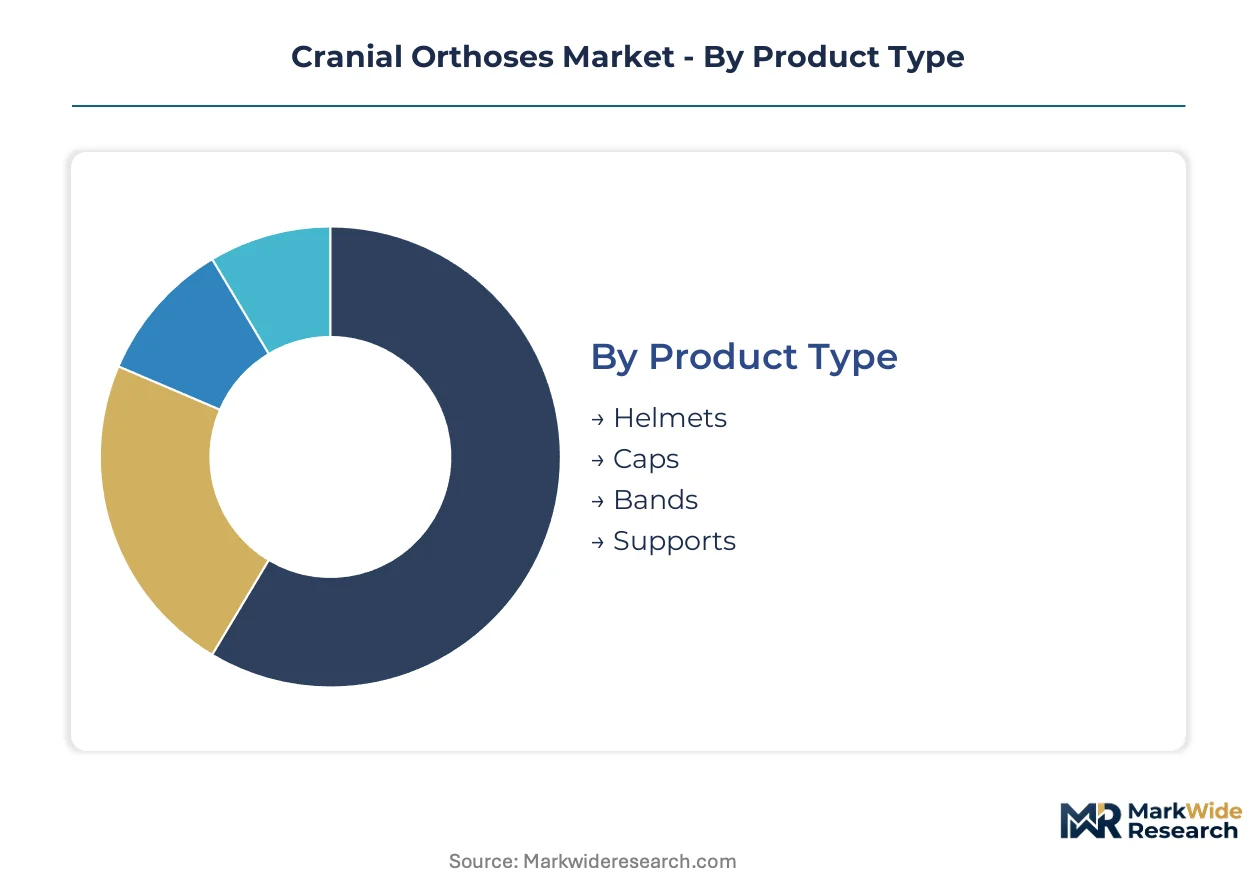
Cranial orthoses serve distinct clinical and consumer workflows across four fundamental dimensions. Product configuration determines reimbursement pathways and fabrication complexity. Material selection governs weight, ventilation, and premium positioning. Distribution channel and end-user access shape patient capture economics and geographic reach.
Product Type:
Configuration determines therapeutic intensity, wear compliance, and parent acceptance across the infant treatment window.
- Helmets:Vacuum-formed copolymer shells deliver circumferential corrective pressure across multiple cranial quadrants. Demand concentrates in United States metropolitan corridors where Medicaid coverage standardization and pediatric orthotist density enable full-capture protocols.
- Bands:Open-crown polymer configurations prioritize thermal comfort and reduced weight for mild-to-moderate positional plagiocephaly. Coastal United States markets show preference acceleration driven by parent education levels and specialist availability enabling informed selection.
- Caps:Soft fabric-based positioning aids for preventive use in neonatal intensive care settings.
- Supports:Supplementary stabilization accessories for post-surgical craniosynostosis management.
Helmets command the established base. The steepest expansion runs through bands.
End User:
Site of care dictates referral pathway complexity, reimbursement velocity, and patient throughput capacity.
- Specialty Clinics:Independent pediatric orthotic practices with captive digital scanning infrastructure compress intake-to-fabrication cycles. United States suburban corridors concentrate demand where embedded specialist networks reduce hospital outpatient dependency.
- Pediatric Hospitals:Academic medical centers anchor complex craniosynostosis cases requiring multidisciplinary surgical coordination. Major United States children's hospital systems drive volume through early intervention screening programs.
- Rehabilitation Centers:Post-acute facilities managing neuromotor comorbidities affecting head positioning.
- Home Healthcare:Direct-to-family delivery models emerging in rural United States markets with telehealth scan integration.
Pediatric hospitals anchor complex case volume. Specialty clinics are expanding most quickly.
Material:
Substrate selection governs fabrication margins, device longevity, and thermal performance during extended infant wear.
- Thermoplastics:Copolymer vacuum-forming substrates dominate fabrication economics through established supplier networks and predictable molding behavior. United States Medicaid reimbursement alignment sustains volume concentration despite petrochemical feedstock volatility.
- Composite Materials:Carbon fiber and advanced polymer hybrids enable durability positioning for active pediatric segments. Premium United States coastal markets absorb higher unit costs where parent willingness-to-pay exceeds standard copolymer thresholds.
- Foam:Lightweight cushioning layers for interface pressure management.
- Fabric:Breathable textile components for cap and band constructions.
Thermoplastics retain volume leadership. Composite materials gain share fastest.
Distribution Channel:
Channel structure determines geographic penetration depth and working capital intensity for fabricators.
- Direct Sales:Captive patient intake through proprietary clinic networks enables margin retention and workflow control. Cranial Technologies deploys this model across multiple United States metropolitan markets.
- Distributors:Third-party logistics networks extend reach into secondary United States care markets without capital-intensive clinic infrastructure. Orthomerica Products leverages broad distributor coverage for tertiary hospital access.
- Online Retail:Emerging direct-to-consumer pathways for supplemental positioning products.
- Medical Supply Stores:Limited retail presence for post-treatment accessories and replacement components.
Distributors anchor rural and secondary market access. Direct sales models are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American distribution for copolymer thermoplastic feedstocks, enabling just-in-time fabrication cycles across West Coast pediatric orthotic networks.
United States
Medicaid expansion across 40 states now covers cranial remolding therapy, expanding addressable infant populations beyond traditional academic medical center catchments. FDA 510(k) clearance pathways govern custom helmet commercialization timelines. Texas Medical Center in Houston anchors one of the nation's largest early intervention screening programs, driving referral volume into surrounding suburban specialty clinic networks.
Germany
University hospital systems in Bavaria and North Rhine-Westphalia coordinate multidisciplinary craniosynostosis care, generating complex case demand for post-surgical orthotic support. EU MDR post-market surveillance obligations elevate clinical evidence requirements for pediatric device manufacturers. The Medical Valley cluster around Erlangen concentrates digital health infrastructure that supports remote scanning protocol development.
United Kingdom
NHS England's specialized commissioning frameworks determine access to cranial remolding services, creating regional variation in treatment availability. MHRA conformity assessment procedures align with EU MDR transition timelines for market access. Great Ormond Street Hospital in London anchors national referral pathways for syndromic craniosynostosis cases requiring integrated orthotic management.
Japan
PMDA marketing authorization requirements for custom medical devices shape product development cycles for domestic and imported cranial orthoses. METI industrial policy supports advanced manufacturing adoption in medical device supply chains. The Keiyō Industrial Zone east of Tokyo concentrates precision molding capabilities that serve pediatric orthotic fabricators.
Australia
TGA inclusion in the Australian Register of Therapeutic Goods enables Medicare reimbursement for cranial remolding devices, expanding private practice service provision. State-based early childhood intervention programs vary in orthotic coverage scope. Melbourne's Parkville biomedical precinct integrates Royal Children's Hospital surgical services with adjacent orthotic fabrication capacity.
Cranial Orthoses Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated fabricators that control digital scanning infrastructure and captive patient intake workflows. Mid-sized regional orthotics groups compete through embedded hospital partnerships and specialist referral network density. Two strategic archetypes dominate: metropolitan direct-to-family clinic operators and distributor-anchored national coverage platforms. Competitive moves concentrate on M&A of independent pediatric orthotic practices and geographic expansion of proprietary scanning networks.
Among United States-based fabricators, Cranial Technologies exemplifies the metropolitan direct-to-family model through proprietary digital scanning deployment, while Boston Orthotics & Prosthetics anchors the hospital-embedded partnership archetype. Orthomerica Products represents distributor-anchored national coverage, extending reach into secondary care markets without capital-intensive clinic infrastructure.
| Leading Market Players |
|---|
| Boston Orthotics & Prosthetics |
| Level Four Orthotics & Prosthetics |
| Cranial Technologies |
| Ballert Orthopedic |
| Northern Care |
| Orthomerica Products |
| Hanger |
| Scheck and Siress |
| Becker Orthopedic |
| Others |
Supply Flow & Price Mechanics
Copolymer thermoplastic feedstock suppliers in the United States Gulf Coast petrochemical corridor anchor fabrication economics, concentrating margin capture upstream while vacuum-forming fabricators downstream absorb resin price volatility through fixed Medicaid reimbursement schedules.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs cranial orthoses, with composite carbon fiber configurations commanding premium positioning against copolymer helmet baselines. Price differentiation hinges on certification grade—FDA 510(k) cleared devices versus non-cleared positioning aids—and customization depth from digital scan protocols. Pricing pressure stems from Medicaid rate compression in state-level fee schedules, squeezing fabrication margins on standard copolymer units. Pediatric hospitals demonstrate lowest price sensitivity due to bundled reimbursement, while independent specialty clinics face acute margin pressure from fixed procedural payments.
Supply Chain Analysis
Extended payment terms from distributor-anchored fabricators to thermoplastic resin suppliers compress working capital cycles across the fabrication tier. Raw material sourcing draws from United States petrochemical producers, German precision molding equipment manufacturers, and East Asian ventilation component suppliers. Single-source vulnerability concentrates in specialized copolymer formulations qualified for medical device biocompatibility. Distribution runs through proprietary clinic networks for metropolitan capture and third-party logistics partnerships for secondary market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of board-certified pediatric orthotists trained in cranial specialization constrains patient throughput capacity, making digital scanning infrastructure and specialist workforce development the decisive competitive assets.
For Market Incumbents: Entrench market position through captive acquisition of independent pediatric orthotic practices in underserved secondary corridors, consolidating referral network density against emerging telehealth-enabled competitors. Backward integration into in-house copolymer sheet extrusion buffers margin erosion from petrochemical feedstock volatility. ISO 13485 certification investment creates regulatory moat as EU MDR clinical evidence requirements escalate. For New Entrants and Emerging Players: Build out remote scanning protocol capabilities targeting rural United States markets where specialist travel burdens elongate treatment initiation timelines. Home healthcare delivery models with telehealth integration represent the most penetrable channel, bypassing capital-intensive clinic infrastructure requirements. Partner with Medicaid managed care organizations for direct-to-family reimbursement pathway development. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional orthotics groups holding embedded hospital partnerships but lacking digital workflow modernization. Five-to-ten year viability hinges on successful CAD/CAM migration and proprietary scanning network density. Watch FDA 510(k) clearance velocity for novel band configurations as inflection indicator for premium segment competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Scanning Network Expansion | Proprietary 3D capture infrastructure compresses intake-to-fabrication cycles and locks patient flow. |
| Medicaid Reimbursement Strategy | State-level coverage standardization in Texas and California unlocks addressable infant populations. |
| EU MDR Certification Pathway | Post-market surveillance infrastructure captures disproportionate share in continental European markets. |
| Composite Material Product Line | Carbon fiber hybrids enable premium positioning in active pediatric segments with higher willingness-to-pay. |
| Telehealth Integration Development | Remote protocols extend geographic reach without capital-intensive physical clinic presence. |
Methodological Framework
Cross-validation between primary interviews with pediatric orthotists, hospital purchasing committee members, and Medicaid program administrators and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, and state-level Medicaid fee schedules anchors the qualitative findings. Bottom-up patient volume modeling by metropolitan statistical area triangulates against top-down market sizing from fabrication equipment installed base and copolymer resin consumption patterns.
Calibration against historical Medicaid expansion trajectories and FDA clearance velocity informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, material substrate, end-user site of care, and distribution channel structure. CAGRs derive from regression analysis of procedure volume growth against orthotist workforce expansion rates and digital scanning adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by telehealth-enabled direct-to-consumer entrants would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Biological Microscope Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Global Disability Devices Market
Medical Devices
Global Spirometers Market
Medical Devices
Aneurysm Coiling & Embolization Devices Market