
 Veterinary Prosthetics and Orthotics Market | 2026-2036
Veterinary Prosthetics and Orthotics Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Prosthetics and Orthotics Market Intelligence
Subscription-based leasing models for high-cost orthotic fabrication equipment are reshaping which veterinary practices can enter the prosthetics market without capital-intensive lab investments. OrthoPets LLC leverages its vertically integrated design-to-delivery workflow to sustain premium positioning across North American specialty clinics. Animal Ortho Care competes through rapid turnaround on custom thermoplastic braces, while Bionic Pets specializes in carbon fiber prosthetic limbs for athletic and working dog recovery protocols.
Veterinary prosthetics and orthotics encompass custom-fabricated external devices engineered from biocompatible thermoplastics, carbon fiber composites, and medical-grade foam to restore locomotor function in animals following amputation, ligament injury, or degenerative joint disease. These devices require precise anthropometric measurement, CAD-modeled socket interfaces, and iterative gait analysis to achieve weight-bearing tolerance and range-of-motion targets comparable to pre-injury biomechanics. Prosthetic limbs dominate current revenue contribution due to high per-unit pricing and surgical referral dependency, while orthotic devices represent the fastest-expanding category as conservative management protocols gain preference among companion animal owners. Custom supports anchored in 3D-scanning workflows capture concentrated margin pools by reducing remake rates and improving clinical outcomes.
The FDA Center for Veterinary Medicine regulates device materials and claims for animal health applications, while ISO 10993 biocompatibility standards govern material selection for prolonged skin contact. State veterinary medical boards in California, Texas, and New York additionally restrict device dispensing to licensed practitioners, shaping channel structure and training requirements. Stakeholders must monitor evolving reimbursement codes from pet insurance underwriters and specialty credentialing pathways for veterinary rehabilitation therapists as these determine addressable clinic penetration and pricing authority.
Market Dynamics
Specialty veterinary clinics in the United States are consolidating rehabilitation service capabilities, creating referral bottlenecks that concentrate prosthetic fabrication demand among a shrinking pool of certified practitioners with CAD-CAM workflows and gait analysis laboratories.
Growth Catalysts
- Pet insurance reimbursement expansion:Underwriters in the United States are adding advanced orthopedic procedure codes, reducing out-of-pocket costs for carbon fiber limb prosthetics.
- ISO 10993 material certification:Standardized biocompatibility testing accelerates regulatory clearance for thermoplastic socket interfaces across state veterinary boards.
- Working dog rehabilitation protocols:Military and police K-9 units in Texas and California mandate prosthetic return-to-duty standards, institutionalizing procurement budgets.
Market Restraints
- Carbon fiber composite supply concentration:Aerospace-grade prepreg manufacturers prioritize aviation contracts, creating 12-16 week lead times for veterinary-grade weaves.
- State dispensing restrictions:California, Texas, and New York veterinary medical boards limit device fitting to licensed practitioners, constraining paraprofessional technician pools.
- Biomechanical measurement standardization gaps:Absence of unified anthropometric protocols forces redundant socket remakes, elevating per-case labor hours.
Strategic Opportunities
- Midwestern specialty clinic deserts:Ohio, Michigan, and Illinois show concentrated small-animal populations with sparse certified rehabilitation therapists.
- 3D scanning plus generative design convergence:Cloud-based socket topology optimization reduces fabrication iteration cycles from three to one.
- Subscription equipment leasing:Orthotic fabrication systems shift from capital purchase to monthly fee structures, lowering clinic entry barriers.
Industry Challenges
- Veterinary rehabilitation therapist certification backlog:University of Tennessee and Colorado State credentialing programs graduate fewer than 150 certified practitioners annually.
- CAD-CAM laboratory capex requirements:Five-axis milling machines and thermal vacuum forming stations demand $180,000-$340,000 initial investment per facility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Prosthetics and Orthotics Market |
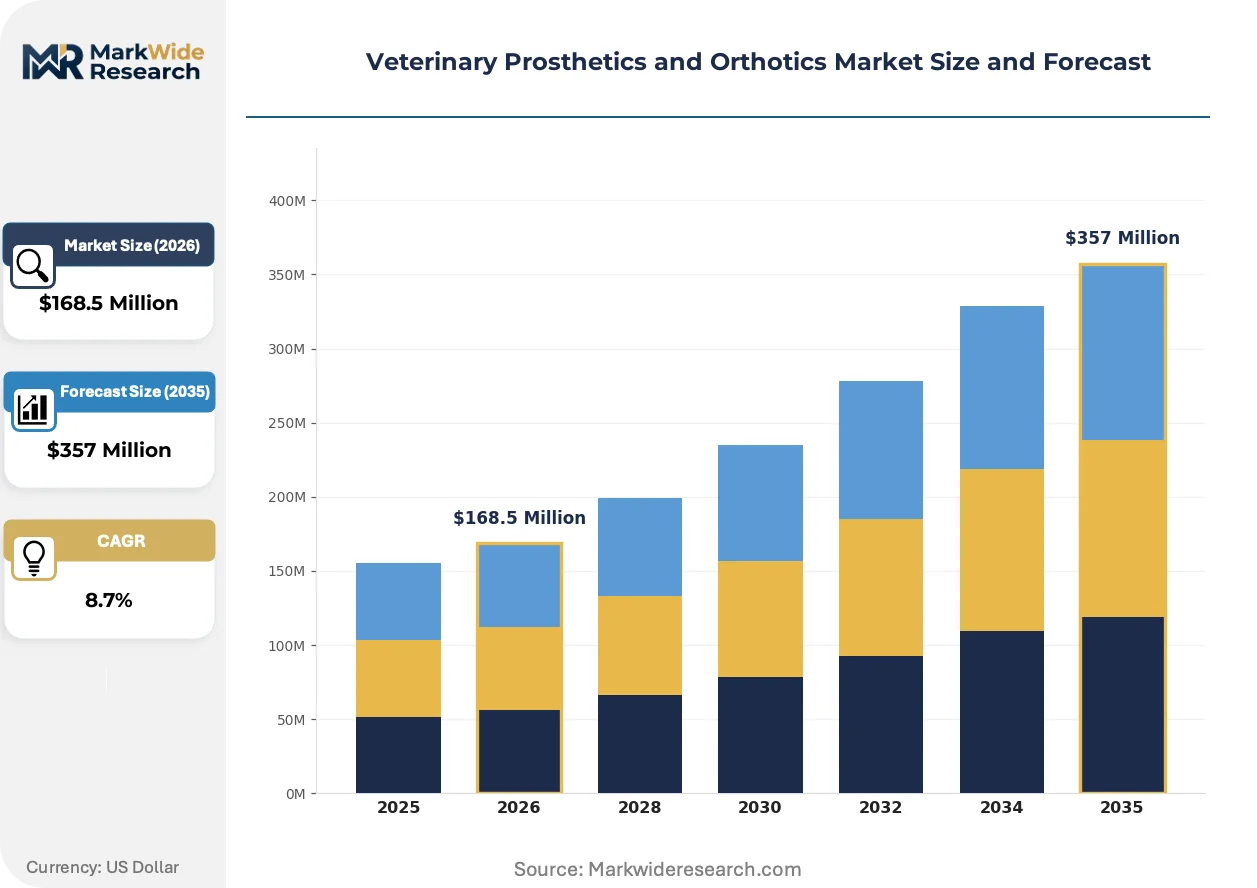
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $357 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prosthetic Limbs, Orthotic Devices, Custom Supports, Animal Braces Animal Type: Dogs, Cats, Horses, Exotic Animals Material: Thermoplastics, Carbon Fiber, Foam, Metal Alloys Application: Rehabilitation, Surgery Support, Injury Recovery, Mobility Enhancement |
| Companies Covered | OrthoPets LLC, Animal Ortho Care, K-9 Orthotics & Prosthetics Inc., Bionic Pets, Paw Prosper, OrthoVet LLC, Petsthetics, Walkin' Pets By HandicappedPets, My Pet's Brace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Prosthetics and Orthotics Market Strategic Shifts & Innovations
Digital fabrication workflows are compressing the interval between injury assessment and device delivery, while regulatory clarity on biocompatibility claims is separating credentialed fabricators from uncertified competitors.
Additive manufacturing with selective laser sintering of nylon-12 powders is hybridizing with traditional carbon fiber lamination to produce hybrid socket interfaces that combine osseointegration mapping precision with impact-resistant exoskeletal structures. University veterinary teaching hospitals in California and North Carolina are piloting these workflows for athletic dog limb salvage cases. The hybridizing fabrication approach is collapsing the distinction between prototype iteration and final production, enabling same-week delivery for urgent trauma cases.
The FDA Center for Veterinary Medicine issued draft guidance clarifying device material claims for prolonged skin contact applications in 2023. Fabricators must now submit ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization test data for novel thermoplastic formulations. Small fabrication shops lacking in-house biocompatibility testing partnerships face extended pre-market consultation timelines, advantaging vertically integrated design-to-delivery operations with captive laboratory relationships.
Pet owners in metropolitan United States markets are compressing their veterinarian selection cycles, prioritizing clinics with in-house rehabilitation certification and same-day orthotic fitting capabilities. This behavioral shift is disintermediating traditional referral chains from general practice veterinarians to distant specialty centers. Urban corridor practices in Denver, Austin, and Seattle are responding by embedding certified rehabilitation therapists within primary care facilities, capturing cases before external referral becomes necessary.
Veterinary Prosthetics and Orthotics Market Segmentation
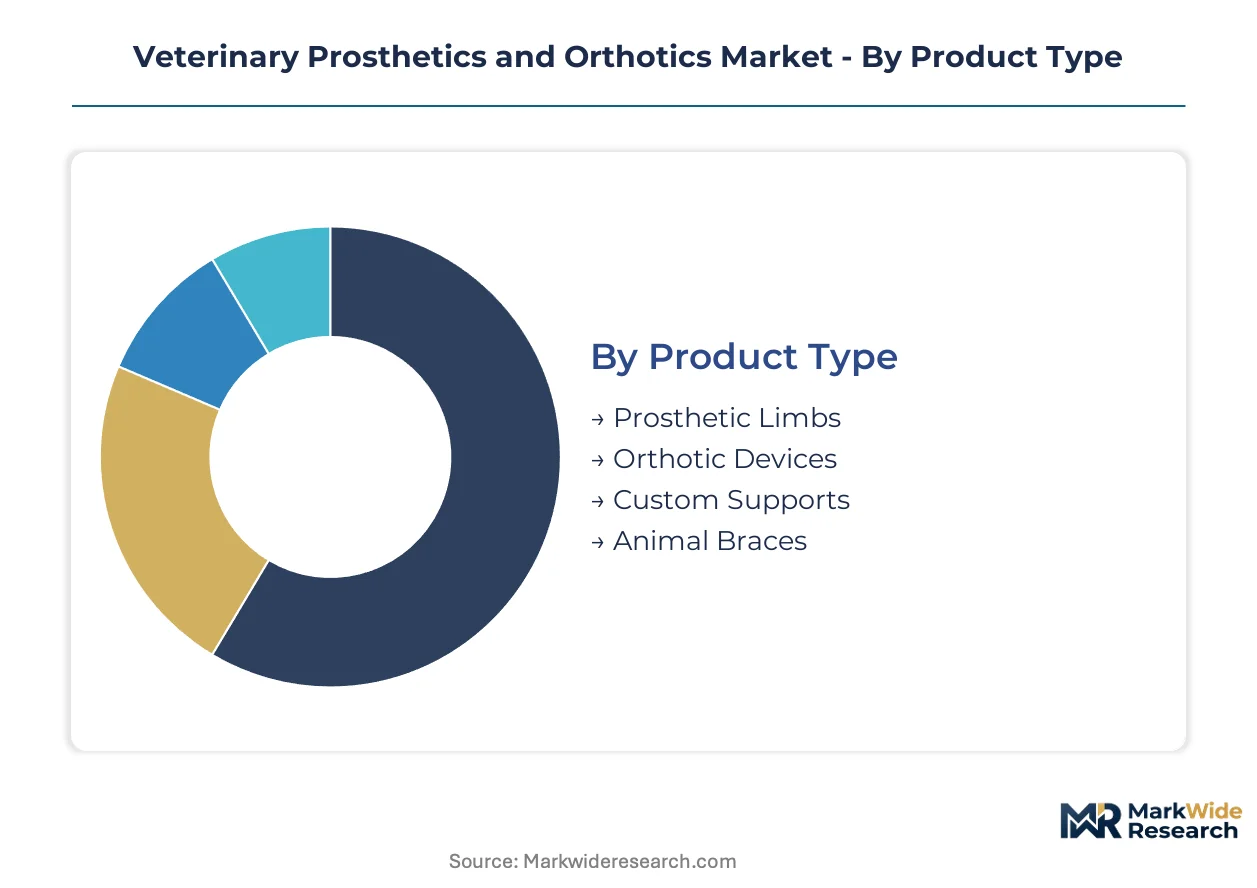
Segmentation in veterinary prosthetics and orthotics reveals distinct manufacturing requirements, pricing tiers, and clinical workflows across product categories. Material selection and animal biomechanics drive specialized fabrication approaches that separate premium custom solutions from standardized supports.
Product Type:
Mature prosthetic categories coexist with emerging orthotic technologies as conservative management protocols reshape clinical preferences.
- Prosthetic Limbs:Carbon fiber composite exoskeletons with CAD-modeled socket interfaces restore weight-bearing function following amputation. Military and police K-9 units in Texas and California institutionalize procurement budgets for return-to-duty limb systems, though aerospace-grade prepreg supply concentration creates 12-16 week lead times.
- Orthotic Devices:External brace systems stabilize ligament injuries and degenerative joint conditions without surgical intervention. Pet insurance underwriters in the United States are adding advanced orthopedic procedure codes, reducing out-of-pocket costs and accelerating category expansion beyond traditional prosthetic demand.
- Custom Supports:3D-scanned thermoplastic interfaces tailored to individual anatomical measurements.
- Animal Braces:Prefabricated and semi-custom stabilizers for acute injury immobilization.
Prosthetic Limbs retain volume leadership; Orthotic Devices holds the steepest expansion curve.
Animal Type:
Volume concentration in companion species contrasts with premium pricing dynamics in large-animal and exotic applications.
- Dogs:Canine patients dominate procedure volume across rehabilitation clinics, with athletic and working dog protocols driving carbon fiber limb adoption. The University of Tennessee and Colorado State credentialing programs graduate fewer than 150 certified veterinary rehabilitation therapists annually, creating referral bottlenecks that concentrate demand among certified practitioners.
- Cats:Feline orthotic applications concentrate on conservative fracture management and degenerative joint disease, with smaller anatomical dimensions requiring specialized thermoplastic molding workflows and reduced fabrication tolerances.
- Horses:Equine prosthetics command premium pricing for catastrophic limb injury salvage, with university veterinary teaching hospitals in California and North Carolina piloting hybrid additive manufacturing approaches.
- Exotic Animals:Avian, reptilian, and wildlife rehabilitation cases require species-specific biomechanical adaptation and limited fabricator expertise.
Dogs command absolute procedure volume; Horses capture the highest per-case revenue realization.
Material:
Biocompatibility certification requirements separate ISO 10993-compliant suppliers from uncertified competitors in material selection.
- Thermoplastics:Medical-grade polypropylene and polyethylene formulations enable rapid thermoforming of socket interfaces and adjustable brace components. The FDA Center for Veterinary Medicine now mandates ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization test data for novel formulations, advantaging fabricators with captive laboratory partnerships.
- Carbon Fiber:Aerospace-grade prepreg weaves deliver strength-to-weight ratios essential for athletic and working dog limb prosthetics, though supply concentration in aviation contracts constrains veterinary-grade availability.
- Foam:Medical-grade cushioning materials for interface padding and pressure distribution.
- Metal Alloys:Titanium and aluminum structural elements for high-load equine and large-breed applications.
Thermoplastics anchor fabrication volume across all product categories; Carbon Fiber claims the margin concentration in premium limb systems.
Application:
Clinical setting determines reimbursement pathways and device specification requirements across the care continuum.
- Rehabilitation:Post-surgical and post-injury therapeutic protocols emphasize gait analysis and iterative device adjustment. Urban corridor practices in Denver, Austin, and Seattle are embedding certified rehabilitation therapists within primary care facilities, capturing cases before external referral becomes necessary.
- Surgery Support:Pre- and post-operative stabilization devices protect surgical repair sites during healing windows.
- Injury Recovery:Conservative management of ligament tears, fractures, and soft tissue trauma without surgical intervention.
- Mobility Enhancement:Quality-of-life interventions for geriatric and degenerative conditions in companion animals.
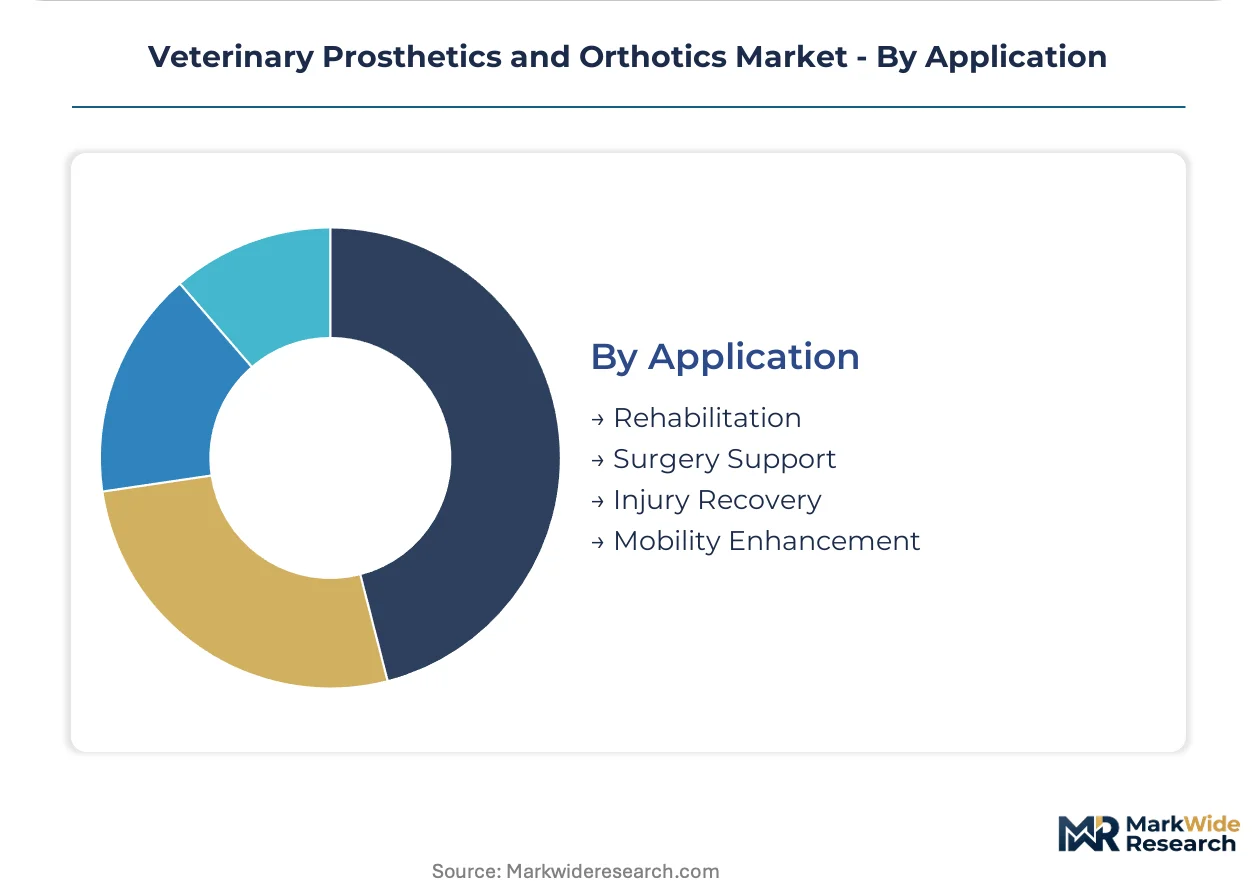
Rehabilitation absorbs the largest certified practitioner capacity; Mobility Enhancement is climbing fastest as pet owner willingness-to-pay for geriatric care expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty veterinary clinics with certified rehabilitation therapists concentrate demand in affluent metropolitan corridors where pet insurance penetration and disposable income for advanced orthopedic procedures align. Urban corridor practices embed prosthetic fitting capabilities to capture cases before external referral chains activate.
United States
Pet insurance underwriters add advanced orthopedic procedure codes, reducing out-of-pocket costs for carbon fiber limb prosthetics. The FDA Center for Veterinary Medicine oversees device material claims for prolonged skin contact applications. Denver, Austin, and Seattle urban corridors embed certified rehabilitation therapists within primary care facilities, disintermediating traditional referral chains.
Germany
Equine catastrophic limb injury salvage commands premium pricing from specialized university veterinary teaching hospitals. EMA-aligned regulatory frameworks govern biocompatibility certification for novel thermoplastic formulations. Bavaria and North Rhine-Westphalia concentrate fabrication expertise alongside automotive-grade carbon fiber supply chain access.
United Kingdom
Companion animal owners compress veterinarian selection cycles, prioritizing in-house rehabilitation certification. The Veterinary Medicines Directorate aligns with ISO 10993 standards for device material safety. London and Southeast England cluster specialty clinics with CAD-CAM workflows and gait analysis laboratories.
Japan
Working dog rehabilitation protocols for police and military K-9 units institutionalize procurement budgets for return-to-duty limb systems. METI and PMDA frameworks guide medical device material selection for animal health applications. Kanto and Kansai metropolitan areas concentrate small-animal populations with sparse certified rehabilitation therapist coverage.
Australia
Veterinary teaching hospitals pilot hybrid additive manufacturing workflows for athletic dog limb salvage cases. TGA biocompatibility requirements shape material selection for prolonged skin contact devices. New South Wales and Victoria anchor fabrication demand alongside concentrated small-animal populations in Sydney and Melbourne corridors.
Veterinary Prosthetics and Orthotics Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure that concentrates certified fabrication capacity among vertically integrated design-to-delivery operations and rapid-turnout thermoplastic specialists. The vendor base separates into three strategic archetypes: premium custom limb fabricators with captive laboratory relationships, mid-market orthotic brace specialists with subscription equipment leasing models, and standardized support manufacturers serving price-sensitive segments. Dominant competitive moves include backward integration into biocompatibility testing partnerships and geographic embedding of certified rehabilitation therapists within primary care facilities to capture pre-referral cases.
Within the premium custom limb tier, OrthoPets LLC and Bionic Pets exemplify vertically integrated operations with design-to-delivery workflows. Among mid-market orthotic specialists, Animal Ortho Care occupies a position emphasizing rapid turnaround capabilities. These three anchors represent the competitive spectrum from aerospace-grade carbon fiber limb systems through thermoplastic brace fabrication to subscription-enabled clinic service models.
| Leading Market Players |
|---|
| OrthoPets LLC |
| Animal Ortho Care |
| K-9 Orthotics & Prosthetics Inc. |
| Bionic Pets |
| Paw Prosper |
| OrthoVet LLC |
| Petsthetics |
| Walkin' Pets By HandicappedPets |
| My Pet's Brace |
| Others |
Cost & Logistics Intelligence
Aerospace-grade prepreg export controls from US and German suppliers determine both the three-tier pricing spread across carbon fiber limb systems and the geographic clustering of fabrication capacity around aviation-contract manufacturers. Veterinary-grade carbon fiber weaves face 12-16 week allocation delays when defense and commercial aviation orders surge, forcing fabricators to either absorb margin compression or pass through index-linked surcharges to specialty clinics.
Pricing Analysis
Cost-plus contracts with aerospace-grade carbon fiber suppliers indexed to aviation spot markets dominate procurement for premium limb fabricators. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified custom sockets from rapid-turnout thermoplastic braces and prefabricated supports. Pricing pressure stems from pet insurance reimbursement rate compression as underwriters negotiate bundled procedure codes. General practice veterinarians exhibit highest price sensitivity, while military K-9 procurement units accept premium positioning for return-to-duty specifications.
Supply Chain Analysis
US and German export-control restrictions on aerospace-grade carbon fiber prepreg constrain flows to veterinary device manufacturers below aviation and defense contract priority. Raw material dependencies center on Japanese Toray weaves, German thermoplastic resin formulations, and US-sourced medical-grade foam substrates. Single-source vulnerability concentrates in aerospace-grade carbon fiber allocation slots. Distribution runs through certified rehabilitation therapist networks with state veterinary board dispensing restrictions limiting paraprofessional channel expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
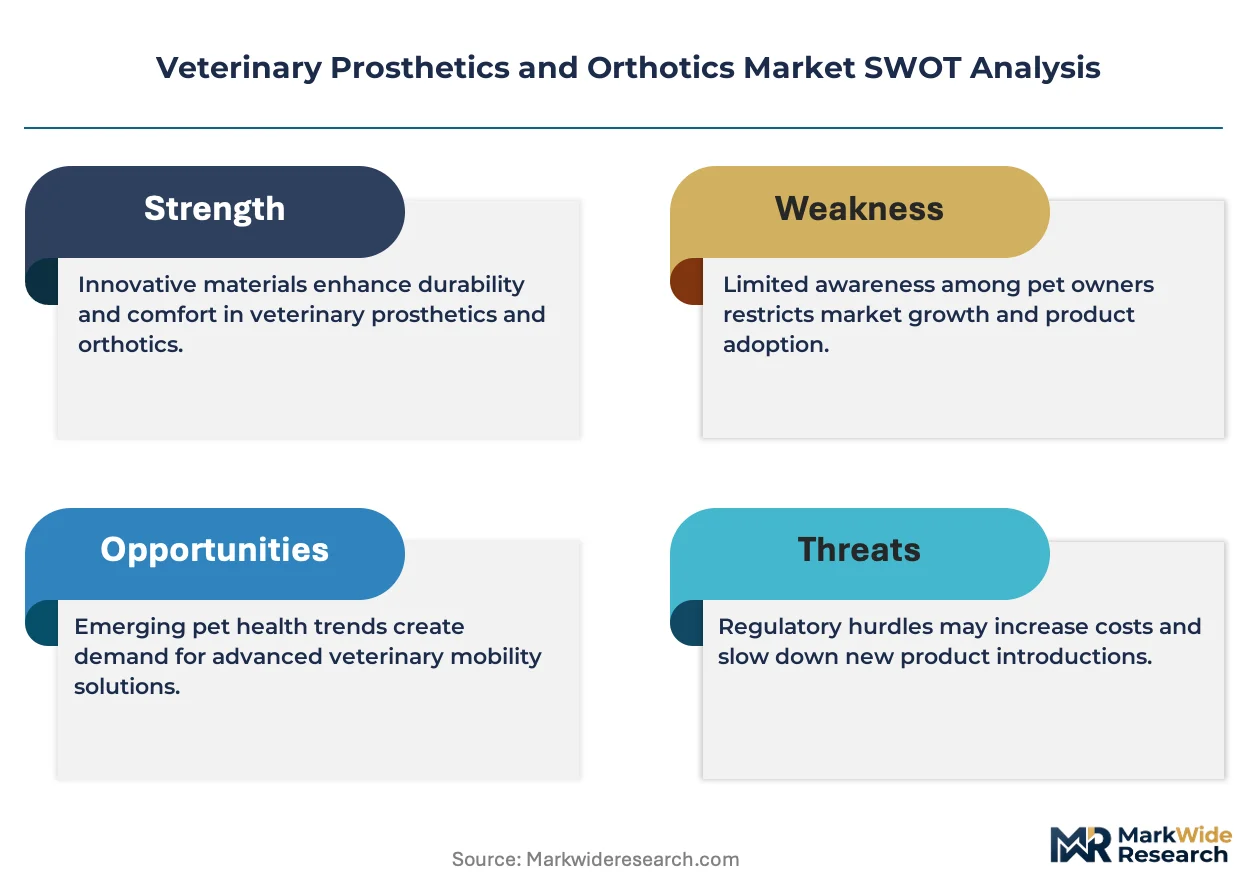
Veterinary prosthetics and orthotics sits in early-cycle expansion as pet insurance reimbursement codes for advanced orthopedic procedures penetrate beyond coastal metropolitan markets into interior states.
For Market Incumbents: Harden biocompatibility testing partnerships against FDA Center for Veterinary Medicine pre-market consultation timelines that disadvantage smaller fabrication shops without captive laboratory relationships. Secure multi-year carbon fiber allocation agreements with aerospace prepreg manufacturers before defense contract renewal cycles tighten supply. Add certified rehabilitation therapist capacity in Ohio, Michigan, and Illinois clinic deserts to preempt referral chain disintermediation by urban corridor competitors. For New Entrants and Emerging Players: Establish a beachhead in subscription-based orthotic fabrication equipment leasing to capture general practice veterinarians priced out of capital-intensive CAD-CAM laboratory investments. Target midwestern states with concentrated small-animal populations and sparse certified rehabilitation therapist coverage. Lead with rapid-turnout thermoplastic brace capabilities rather than carbon fiber limb systems requiring 12-16 week material lead times. For Investors and Strategic Acquirers: Design-to-delivery operations with vertical integration into biocompatibility testing and gait analysis laboratories represent the priority acquisition archetype. Long-term viability hinges on consolidation of fragmented fabrication capacity among fewer than 150 annual rehabilitation therapy program graduates. Watch pet insurance underwriter orthopedic procedure code expansion velocity as the inflection signal for addressable market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatibility Testing Partnership | FDA Center for Veterinary Medicine pre-market timelines compress for ISO 10993-5 and ISO 10993-10 data holders. |
| Carbon Fiber Allocation Agreement | Aerospace prepreg manufacturers prioritize long-term contracts over spot veterinary-grade purchases during defense surges. |
| Certified Therapist Embedding | Urban corridor primary care facilities in Denver and Austin capture cases before external specialty referral chains activate. |
| Subscription Equipment Leasing | General practice veterinarians enter orthotic fabrication without $180,000-$340,000 five-axis milling capital requirements. |
| Midwestern Clinic Expansion | Ohio and Illinois small-animal populations face certified rehabilitation therapist deserts with concentrated unmet demand. |
Research Approach
Cross-validation between primary interviews with veterinary rehabilitation therapists, specialty clinic owners, and pet insurance underwriters anchors the qualitative findings against secondary validation from FDA Center for Veterinary Medicine guidance documents, ISO 10993 biocompatibility standards, and state veterinary medical board dispensing regulations. Bottom-up fabrication capacity modeling triangulates against top-down pet insurance reimbursement code penetration estimates.
Calibration against historical prosthetic limb and orthotic device shipment patterns informs volume projections across the analysis window. Segmentation dimensions include product type, animal species, material certification tier, and clinical application setting. CAGRs derive from iterative convergence of demand-side insurance penetration curves and supply-side certified practitioner graduation rates from University of Tennessee and Colorado State programs.
Stress conditions across carbon fiber supply allocation volatility, pet insurance reimbursement rate compression, and state veterinary board regulatory tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about rehabilitation therapist certification program expansion and aerospace prepreg manufacturer capacity allocation priorities. Material shifts in FDA biocompatibility testing requirements or ISO 10993 standard revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
Medical Traction Devices Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Japan Spinal Surgery Devices Market
Orthopedic Devices
Europe Orthopedic Braces and Support Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
North America Kyphoplasty Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Wrist Replacement Orthopedic Devices Market