
 Europe Dental Implants and Prosthetics Market | 2026-2036
Europe Dental Implants and Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dental Implants and Prosthetics Market Insights
Shortages of specialized oral surgeons and prosthodontic technicians across Southern and Eastern Europe is redrawing competitive dynamics, forcing manufacturers to invest in simplified surgical protocols and training ecosystems. Institut Straumann AG leverages its education infrastructure to sustain loyalty among implantologists in premium segments. Dentsply Sirona competes through integrated digital workflow platforms that connect chairside scanning with laboratory production. BEGO GmbH & Co. KG anchors its position in the German-speaking region through deep specialization in cobalt-chrome and precious metal frameworks.
Dental implants and prosthetics encompass endosseous fixtures, abutments, and superstructures fabricated from titanium, zirconia, or cobalt-chrome alloys, typically achieving osseointegration over 12-16 weeks before final prosthetic loading; these systems restore masticatory function and aesthetic continuity for edentulous or partially dentulous patients. Endosseous implants dominate volume due to their versatility across bone densities and established long-term clinical documentation, while zirconia-based solutions command premium positioning in aesthetic zones where soft tissue response and metal-free biocompatibility drive patient preference. CAD/CAM technology is displacing conventional casting workflows in prosthetic fabrication, compressing turnaround times from weeks to days and enabling same-day implant restoration protocols that reshape practice economics.
The EU Medical Device Regulation and CE marking framework impose heightened clinical evidence requirements and post-market surveillance obligations on implant manufacturers, extending product development timelines and favoring entities with substantial regulatory affairs capabilities. EMA coordination with notified bodies shapes harmonized standards for biocompatibility testing and surface modification validation across member states. National health technology assessment bodies in France, Germany, and Italy determine reimbursement levels for implant procedures, directly influencing patient access and manufacturer pricing power. Stakeholders must monitor evolving HTA methodologies and procurement centralization trends that threaten to commoditize standard implant systems while preserving premium tiers for differentiated digital and biological offerings.
Market Dynamics
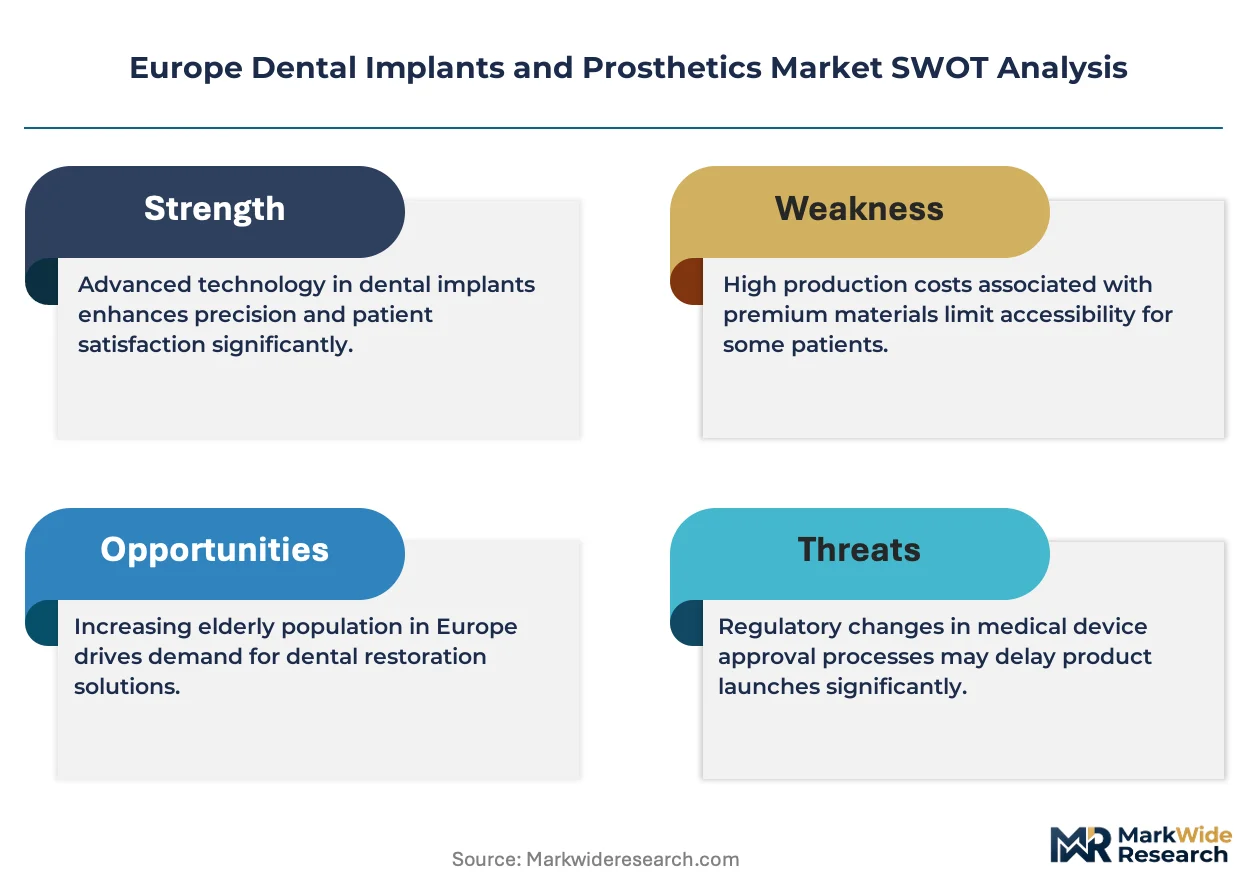
EU Medical Device Regulation (MDR) implementation is compressing product development timelines and elevating clinical evidence thresholds, forcing implant manufacturers to restructure regulatory affairs capabilities or exit premium segments entirely.
Growth Catalysts
- Digital workflow integration:CAD/CAM technology enables same-day implant restoration protocols in private dental clinic chains across Southern Europe, compressing turnaround from weeks to days.
- CE marking framework harmonization:EMA coordination with notified bodies standardizes biocompatibility testing requirements, reducing cross-border registration friction for multi-market manufacturers.
- Aging demographics in Germany and Spain:Expanding edentulous and partially dentulous patient pools are enlarging the addressable market for restorative dentistry procedures.
Market Restraints
- Titanium supply concentration:Raw material sourcing depends on a limited supplier base, exposing manufacturers to input cost volatility and geopolitical supply disruptions.
- Specialized labor scarcity:Shortages of oral surgeons and prosthodontic technicians across Southern and Eastern Europe constrain service delivery capacity and procedure volume expansion.
- MDR compliance costs:Elevated post-market surveillance obligations and clinical documentation requirements extend product development cycles and favor larger entities with dedicated regulatory infrastructure.
Strategic Opportunities
- Eastern Europe penetration:Underdeveloped private dental infrastructure in Poland and Romania presents first-mover advantages for clinic chain partnerships and training ecosystem investments.
- Zirconia aesthetic applications:Metal-free biocompatibility and superior soft tissue response are opening premium positioning in anterior zone restorations where patient-driven aesthetics dominate.
- Health technology assessment alignment:Proactive engagement with French HAS, German IQWiG, and Italian AIFA bodies can secure favorable reimbursement tiers before procurement centralization accelerates.
Industry Challenges
- Prosthodontic technician pipeline collapse:Vocational training program deficits across Italy and Spain are creating bottlenecks in laboratory fabrication capacity.
- Legacy system integration friction:Digital intraoral scanners and chairside milling units require substantial capital deployment and staff retraining in established practices.
- CE marking timeline extension:Notified body capacity constraints under MDR are delaying product launches and compressing commercialization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dental Implants and Prosthetics Market |
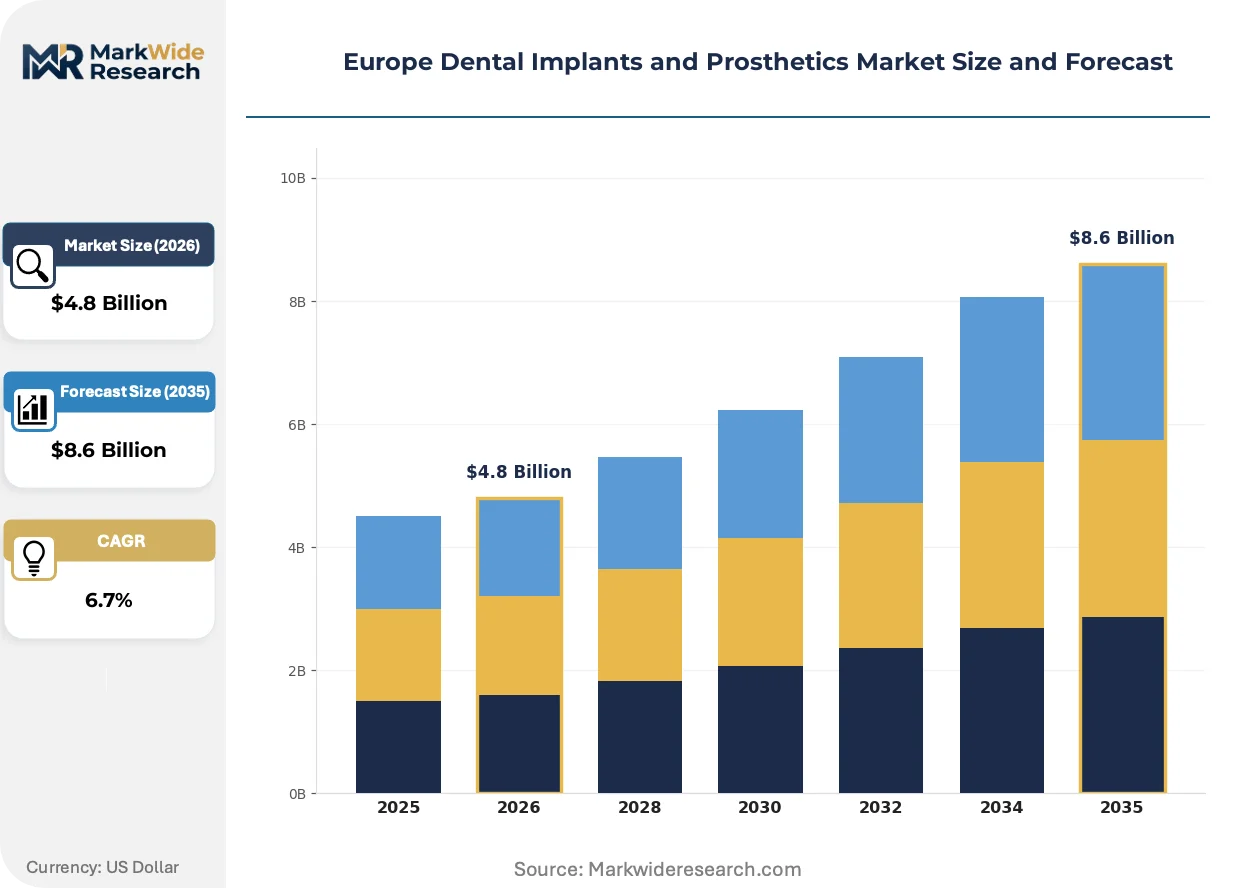
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endosseous Implants, Subperiosteal Implants, Transosteal Implants, Mini Implants Material: Titanium, Zirconia, Stainless Steel, Polymer Technology: Laser Sintering, CAD/CAM, 3D Printing, Surface Treatment Application: Restorative Dentistry, Prosthodontics, Implantology, Oral Surgery |
| Companies Covered | Envista Holdings Corporation, OSSTEM Implant, Institut Straumann AG, Ivoclar Vivadent AG, BEGO GmbH & Co. KG, Dentsply Sirona, Nobel Biocare, Neoss Limited, Zimmer Biomet Holdings, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dental Implants and Prosthetics Market Trends and Innovations
Digital fabrication protocols and biological surface engineering are converging to compress treatment timelines and elevate clinical outcomes, reshaping competitive differentiation beyond hardware specifications toward integrated service ecosystems.
CAD/CAM-produced zirconia abutments and monolithic crowns deliver precise marginal fit and aesthetic translucency for anterior restorations. Private clinic chains in Spain and Italy are adopting these workflows at accelerating pace to differentiate against public-sector alternatives. Chairside milling is supplanting conventional laboratory casting, collapsing the prosthetic production cycle from multi-week intervals to single-visit completion.
EU MDR Article 10 and Annex XIV impose heightened clinical evaluation requirements and systematic post-market clinical follow-up obligations on implantable devices. Manufacturers must maintain updated clinical evaluation reports and periodic safety update reports throughout product lifecycles. Premium titanium implant systems face the steepest compliance burden, prompting portfolio rationalization toward platforms with robust long-term documentation.
Patient-driven channel preferences are fragmenting traditional dentist-laboratory relationships. Direct-to-clinic digital file transmission and centralized milling center networks are displacing local technician dependencies in high-volume markets. France and Germany exhibit the strongest momentum for this disintermediation, where procurement consolidation among dental clinic chains favors standardized, scalable production models over bespoke artisanal fabrication.
Europe Dental Implants and Prosthetics Market Segmentation
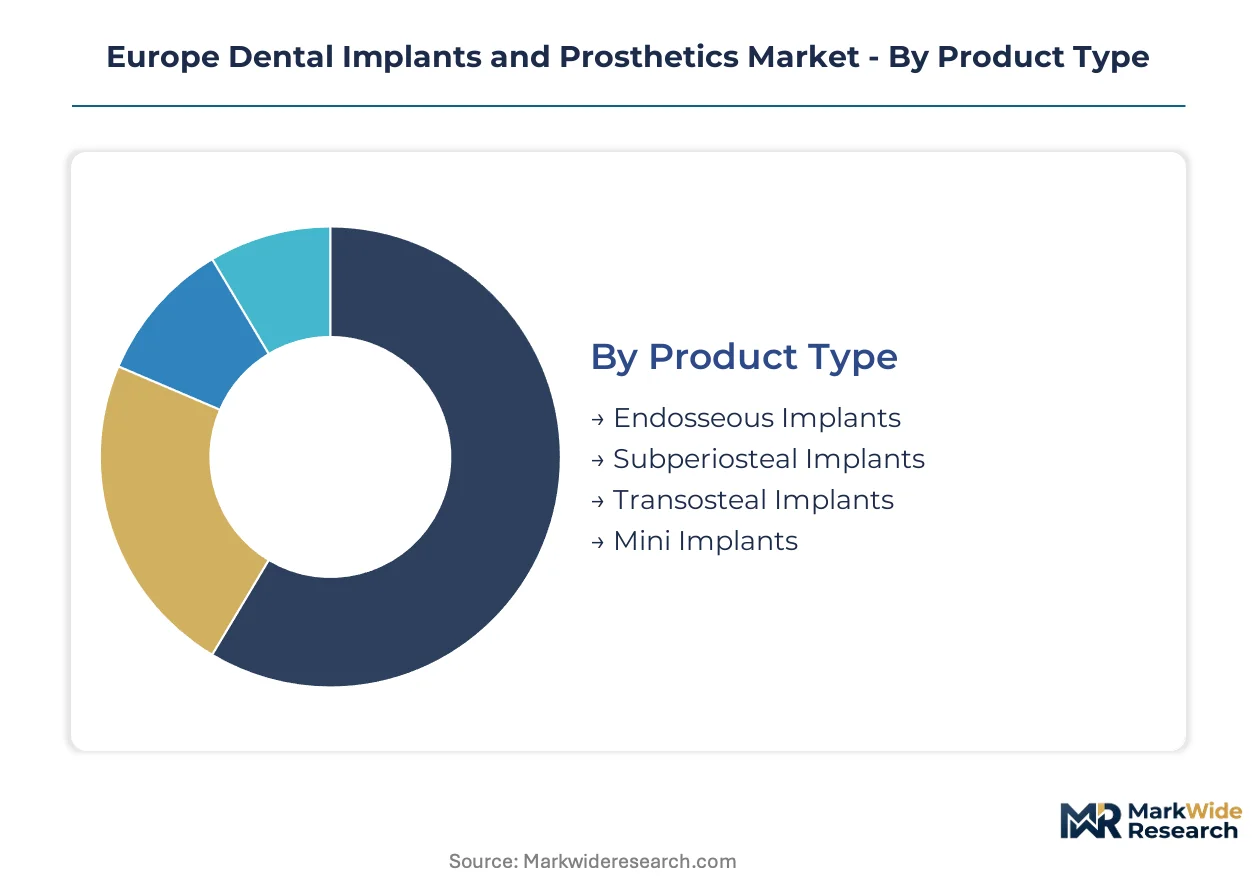
Segmentation in the Europe Dental Implants and Prosthetics Market reveals how product specifications, material choices, and fabrication technologies align with distinct clinical workflows and reimbursement environments across EU member states. Manufacturers configure their portfolios around these divisions to match regulatory pathways and channel economics.
Product Type:
Endosseous fixtures flow through specialist implantology clinics and hospital dental departments, while alternative configurations serve niche anatomical constraints through oral surgery centers.
- Endosseous Implants:Threaded titanium or zirconia fixtures inserted directly into alveolar bone, available in tapered or parallel-walled designs for varying density classifications. German and Spanish private clinic chains concentrate procurement here, driven by established osseointegration protocols and CE marking documentation depth.
- Subperiosteal Implants:Custom-cast frameworks resting atop the jawbone beneath periosteal tissue, fabricated from cobalt-chrome alloys via traditional casting or emerging CAD/CAM methods. Italian oral surgery units in Lombardy and Emilia-Romagna generate concentrated demand where residual bone height precludes endosseous placement.
- Transosteal Implants:Penetrating fixtures anchored through the mandible with transcutaneous abutments, reserved for severe atrophy cases requiring maxillofacial intervention.
- Mini Implants:Reduced-diameter temporary anchorage devices for orthodontic stabilization and provisional prosthetic support, gaining traction in French orthodontic practices seeking lower-invasion alternatives.
By volume, Endosseous Implants lead. By growth pace, Mini Implants are climbing the fastest as orthodontic applications expand.
Material:
Material selection stratifies across cost tiers and aesthetic requirements, with premium biocompatibility commanding distinct pricing bands in Southern European private markets.
- Titanium:Commercially pure grades 1-4 and Ti-6Al-4V ELI alloys dominate load-bearing posterior applications, with sandblasted and acid-etched surface modifications enhancing bone apposition. German statutory health insurance reimbursement frameworks favor titanium for standard care, constraining zirconia penetration in cost-sensitive segments.
- Zirconia:Yttria-stabilized tetragonal polycrystalline ceramics offering metal-free biocompatibility and soft tissue aesthetic integration. Spanish and Italian anterior zone restorations concentrate demand here, where patient-driven aesthetics override reimbursement limitations.
- Stainless Steel:Austenitic grades for temporary abutments and provisional frameworks in budget-tier service lines.
- Polymer:PEEK and PMMA provisional materials for immediate-load temporization and surgical guide fabrication.
Titanium captures the largest volume share. Zirconia demonstrates the steepest expansion trajectory as metal-free protocols gain clinical acceptance.
Technology:
Technology segments map to customer maturity levels, with digital-native clinic chains adopting integrated workflows faster than established practices with legacy equipment.
- Laser Sintering:Selective laser melting of titanium and cobalt-chrome powders enables complex lattice structures and patient-specific implant geometries. German milling centers in Baden-Württemberg and Bavaria concentrate capacity here, serving pan-European laboratory networks.
- CAD/CAM:Computer-aided design and subtractive milling of zirconia abutments and monolithic crowns, compressing fabrication from weeks to hours. Italian private clinic chains in Milan and Rome deploy chairside systems for same-day restoration protocols.
- 3D Printing:Vat photopolymerization and material extrusion for surgical guides and provisional prosthetics.
- Surface Treatment:Plasma spraying, anodization, and biomimetic coating processes modifying implant surface energy and topography.
CAD/CAM leads by installed base volume. Laser Sintering is gaining share fastest as metal additive manufacturing achieves medical-grade certification consistency.
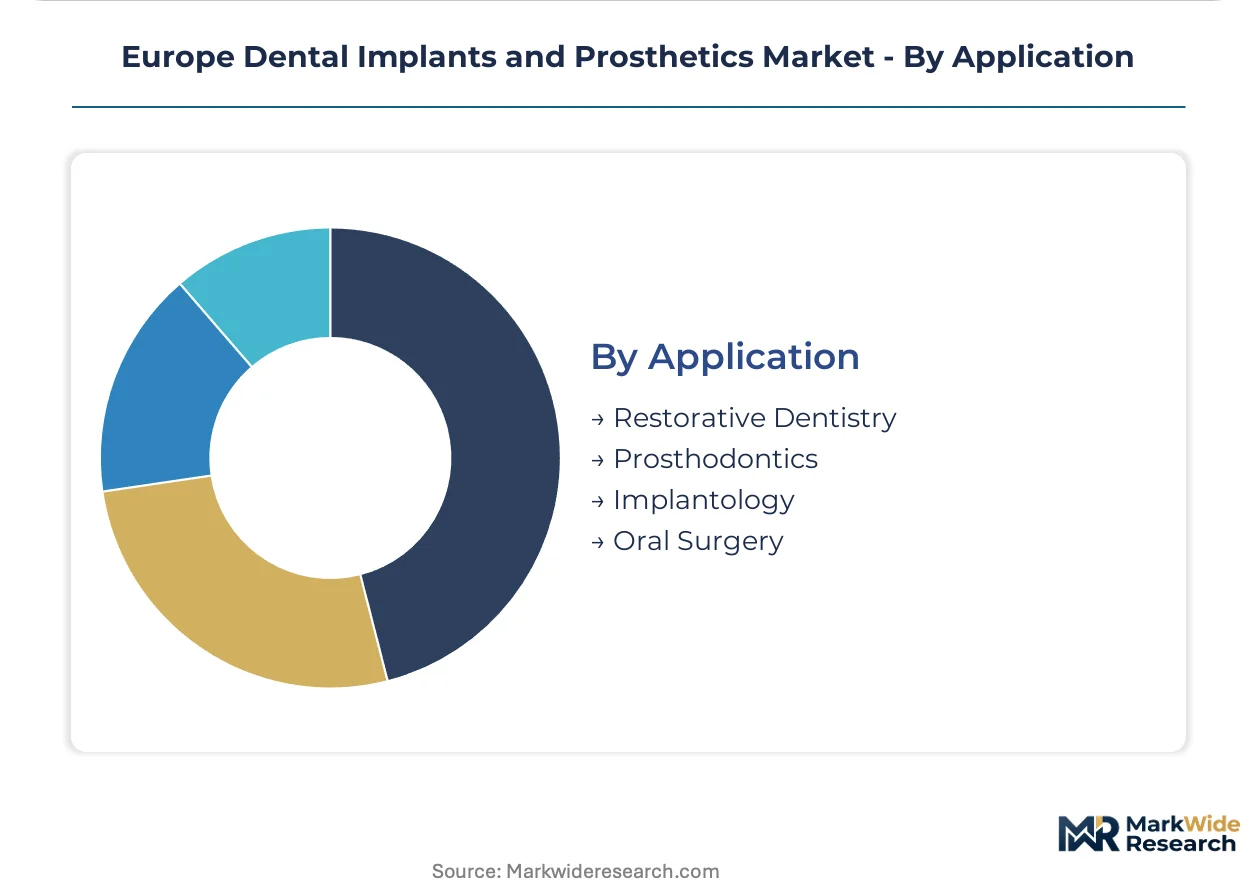
Application:
Application segments align with practitioner specialization and reimbursement category boundaries, determining which stakeholders control purchasing decisions.
- Restorative Dentistry:Crown, bridge, and full-arch prosthetic rehabilitation on implant foundations, spanning single-tooth to edentulous reconstructions. French and German general dental practices with implantology qualifications drive volume, constrained by HTA-determined reimbursement ceilings.
- Prosthodontics:Complex rehabilitation requiring maxillofacial prosthodontist involvement, including obturators and craniofacial implants. Belgian and Dutch academic medical centers concentrate specialized demand here.
- Implantology:Surgical placement and immediate loading protocols performed by specialist oral surgeons.
- Oral Surgery:Trauma, oncologic, and congenital defect reconstruction requiring hospital-based intervention.
Restorative Dentistry dominates procedure volume. Implantology is expanding most quickly as simplified surgical protocols enable general practitioner participation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German implantology runs substantially ahead of Italian and Spanish markets, where reimbursement compression and private clinic competition compress margins for standard titanium systems.
Germany
Statutory health insurance frameworks favor titanium fixtures for standard care, constraining zirconia penetration in cost-sensitive segments. IQWiG assessments determine procedure reimbursement ceilings, directly influencing manufacturer pricing negotiations. The Baden-Württemberg and Bavaria corridor hosts concentrated milling center capacity serving pan-European laboratory networks.
Spain
Private dental clinic chains in Madrid and Barcelona are modernizing implantology service lines with same-day restoration protocols. Regional health authorities maintain fragmented reimbursement policies across autonomous communities, creating pricing arbitrage opportunities. Catalonia's Barcelona cluster drives adoption of CAD/CAM chairside systems for aesthetic zone applications.
Italy
AIFA reimbursement determinations lag behind private market expansion in Lombardy and Emilia-Romagna. Vocational training deficits for prosthodontic technicians create laboratory fabrication bottlenecks. Milan's private clinic concentration anchors premium zirconia demand for anterior restorations where patient-driven aesthetics dominate purchasing decisions.
France
HAS health technology assessments shape implant procedure coverage under national health insurance, constraining volume in public-sector dentistry. Procurement consolidation among dental clinic chains favors standardized production models over bespoke fabrication. The Paris-Sud cluster exhibits strongest momentum for direct-to-clinic digital file transmission displacing local technician dependencies.
Poland
Underdeveloped private dental infrastructure presents first-mover advantages for clinic chain partnerships and training ecosystem investments. National reimbursement frameworks remain limited, driving out-of-pocket payment dynamics. Warsaw and Krakow emerging as hubs for simplified surgical protocol adoption enabling general practitioner participation in implant placement.
Europe Dental Implants and Prosthetics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with premium-tier specialists commanding margins through education infrastructure while integrated platform vendors compete on workflow efficiency. The vendor base stratifies across three tiers: premium implantology specialists with deep clinical documentation, mid-market integrated dental equipment providers, and regional metal-framework fabricators with cobalt-chrome specialization. Consolidation pressures favor entities with dedicated regulatory affairs capabilities under MDR compliance burdens. Dominant competitive moves include portfolio rationalization toward platforms with robust long-term clinical evidence and strategic training ecosystem investments to secure implantologist loyalty.
Among Swiss-headquartered specialists, Institut Straumann AG exemplifies the premium-tier archetype through sustained education infrastructure deployment. Dentsply Sirona occupies a position within the integrated platform segment, representing workflow-centric competition that connects digital scanning with laboratory production. BEGO GmbH & Co. KG anchors the regional fabrication specialist tier, with its German GmbH & Co. KG structure reflecting deep specialization in metal-framework production for the German-speaking market.
| Leading Market Players |
|---|
| Envista Holdings Corporation |
| OSSTEM Implant |
| Institut Straumann AG |
| Ivoclar Vivadent AG |
| BEGO GmbH & Co. KG |
| Dentsply Sirona |
| Nobel Biocare |
| Neoss Limited |
| Zimmer Biomet Holdings |
| Others |
Pricing and Supply Chain Analysis
CAD/CAM-produced zirconia components displacing conventional cobalt-chrome casting are redrawing procurement geography toward Southern European milling centers while compressing price premiums for metal-free restorations. This substitution dynamic concentrates value capture with digital workflow integrators and fragments traditional laboratory networks.
Pricing Analysis
The customization-premium spread between patient-specific CAD/CAM abutments and standard titanium fixtures spans roughly three-to-one in German private practices, with CE marking tier and surface modification protocol serving as primary differentiation drivers. Pricing pressure stems from procurement consolidation among Spanish and Italian clinic chains favoring standardized implant platforms. Public-sector reimbursement frameworks in France and Germany exhibit highest price sensitivity, while Southern European private aesthetic dentistry demonstrates lowest sensitivity due to out-of-pocket payment dominance.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific titanium sponge suppliers through Rotterdam and Hamburg ports expose European fabricators to container availability volatility and customs processing delays. Raw material sourcing draws from Chinese titanium sponge producers, German precision milling equipment manufacturers, and Italian zirconia blank suppliers. Single-source vulnerability concentrates in yttria-stabilized zirconia powder supply. Distribution runs through specialist dental distributors in Germany, direct-to-clinic digital networks in France, and integrated clinic chain procurement in Spain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Dental Implants and Prosthetics Market sits at a regulatory-inflection disruption where EU MDR compliance timelines are eliminating subscale competitors and concentrating share with documentation-heavy incumbents.
For Market Incumbents: Consolidate regulatory affairs capabilities through dedicated MDR infrastructure investments or targeted acquisition of notified-body-certified product lines. Vertical integration into laser-sintering capacity in Baden-Württemberg and Bavaria secures supply continuity against titanium sourcing volatility from Chinese sponge producers. For New Entrants and Emerging Players: Training ecosystem gaps in Poland and Romania where simplified surgical protocols enable general practitioner participation present first-mover white-space opportunities. Target Eastern European clinic chain partnerships with bundled education-and-supply offerings that bypass established distributor relationships in mature markets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale specialists with robust clinical documentation over diversified dental equipment conglomerates. Acquisition targets should demonstrate CE marking depth under MDR Annex XIV and established post-market surveillance systems. Monitor notified body capacity constraints as the signal indicating commercialization timeline compression and portfolio rationalization urgency.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Infrastructure Buildout | CE marking depth under EU MDR Annex XIV determines market access survival for implant manufacturers. |
| Digital Workflow Platform Integration | Chairside CAD/CAM connectivity with centralized milling networks displaces traditional laboratory dependencies in France. |
| Eastern European Training Ecosystem Investment | Poland and Romania's underdeveloped private dental infrastructure rewards first-mover clinic chain partnerships. |
| Zirconia Supply Chain Backward Integration | Yttria-stabilized powder sourcing control mitigates single-source vulnerability for metal-free restoration producers. |
| Health Technology Assessment Alignment | Proactive HAS, IQWiG, and AIFA engagement secures favorable reimbursement tiers before procurement centralization accelerates. |
Research Methodology
A standing panel of implantology clinic directors, prosthodontic laboratory managers, regulatory affairs specialists at notified bodies, and dental distributor procurement heads provided ongoing calibration across primary interview cycles. Secondary validation drew from EMA MDR guidance documents, CE marking databases, hospital procurement registries, and IQWiG assessment reports. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, material grade, fabrication technology, application specialty, and national reimbursement cluster. CAGRs were derived from fitted growth curves incorporating aging demographic projections, regulatory timeline assumptions, and digital adoption rate parameters specific to dental practice economics.
Forecasts assume regulatory continuity in EU MDR implementation and national HTA methodologies; material policy shifts in CE marking requirements or reimbursement centralization would require re-modeling. Practitioners should keep alternative scenarios live as notified body capacity constraints and titanium supply chain disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Global Orthodontic Product Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Dental Curing Lights Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Dental Healing Caps Market
Dental Devices
Dental Air Polishers Market
Dental Devices
United States Dental Implants Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Dental Regeneration Market
Dental Devices
Dental Microsurgery Market
Dental Devices
North America Aligner Sheet Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Intraoral Dental Scanner Market