
 Global Animal Ortho-Prosthetics Market | 2026-2036
Global Animal Ortho-Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Ortho-Prosthetics Market Foresight
Subscription-based telehealth support for device fitting and gait monitoring is broadening what veterinary practices sell beyond hardware. OrthoPets LLC leverages its proprietary digital casting workflow to sustain premium positioning across North American specialty clinics. Bionic Pets anchors its competitive profile through direct-to-consumer education that reduces clinic dependency. Össur Veterinary differentiates by transferring human-grade composite fabrication techniques into its veterinary prosthetic line.
Animal ortho-prosthetics are custom-fabricated or modular external devices—typically composed of thermoplastic polymers, carbon fiber composites, or medical-grade aluminum alloys—designed to restore locomotor function or stabilize musculoskeletal injury in companion and working animals. These devices serve the primary commercial purpose of extending active working life and reducing euthanasia decisions for limb-compromised patients. Prosthetics and orthotics together form the largest product category, with braces experiencing accelerated growth as preventive applications expand in canine sports medicine. The veterinary clinic end-user channel captures the dominant margin pool due to prescription authority and fitting service bundling, while rehabilitation centers represent the fastest-growing access point as referral networks formalize.
The FDA Center for Veterinary Medicine regulates device safety claims and manufacturing quality in the United States, while the EU Medical Device Regulation and CE marking framework govern market access across European member states. Japan's Ministry of Agriculture, Forestry and Fisheries and PMDA coordinate import standards and clinical validation requirements for veterinary medical devices. Stakeholders must monitor how regulatory divergence between these jurisdictions affects product registration timelines and reimbursement eligibility for advanced prosthetic interventions.
Market Dynamics
Veterinary ortho-prosthetics now compete against euthanasia economics as pet insurance penetration rises and 3D-printed socket fabrication compresses traditional casting timelines from weeks to days.
Growth Catalysts
- CE marking under EU MDR:Streamlined conformity assessment for Class I veterinary devices accelerates cross-border commercialization for European manufacturers.
- Carbon fiber lamination:Human-grade composite sourcing from aerospace supply chains reduces device weight by 40% versus thermoplastic alternatives.
- Canine sports medicine:Preventive bracing for agility and working dogs expands addressable volume beyond post-injury rehabilitation.
Market Restraints
- Titanium alloy price volatility:Medical-grade Ti-6Al-4V sourcing concentrates through Russian and Chinese sponge producers, exposing fabricators to input cost swings.
- FDA 510(k) pathway ambiguity:Veterinary prosthetics occupy a regulatory gray zone between medical devices and animal health products, extending pre-market consultation cycles.
- Biomechanical substitution:Advances in tarsal arthrodesis and total knee replacement surgery reduce lifetime prosthetic dependency for certain injury profiles.
Strategic Opportunities
- Japan's aging pet demographic:Ministry of Agriculture, Forestry and Fisheries data shows 28% of owned dogs exceed 10 years, creating geriatric mobility intervention demand.
- Telehealth fitting protocols:Remote gait analysis via smartphone accelerometry enables direct-to-consumer bypass of clinic gatekeeping.
- Rehabilitation center accreditation:Certified canine rehabilitation practitioner credentialing creates preferred vendor status for device suppliers.
Industry Challenges
- Orthopedic casting technician scarcity:Veterinary-specific CCO (Certified Canine Orthotist) programs graduate fewer than 50 specialists annually across North America.
- ISO 10993 biocompatibility testing backlog:Contract laboratory capacity constraints delay new material introductions by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Ortho-Prosthetics Market |
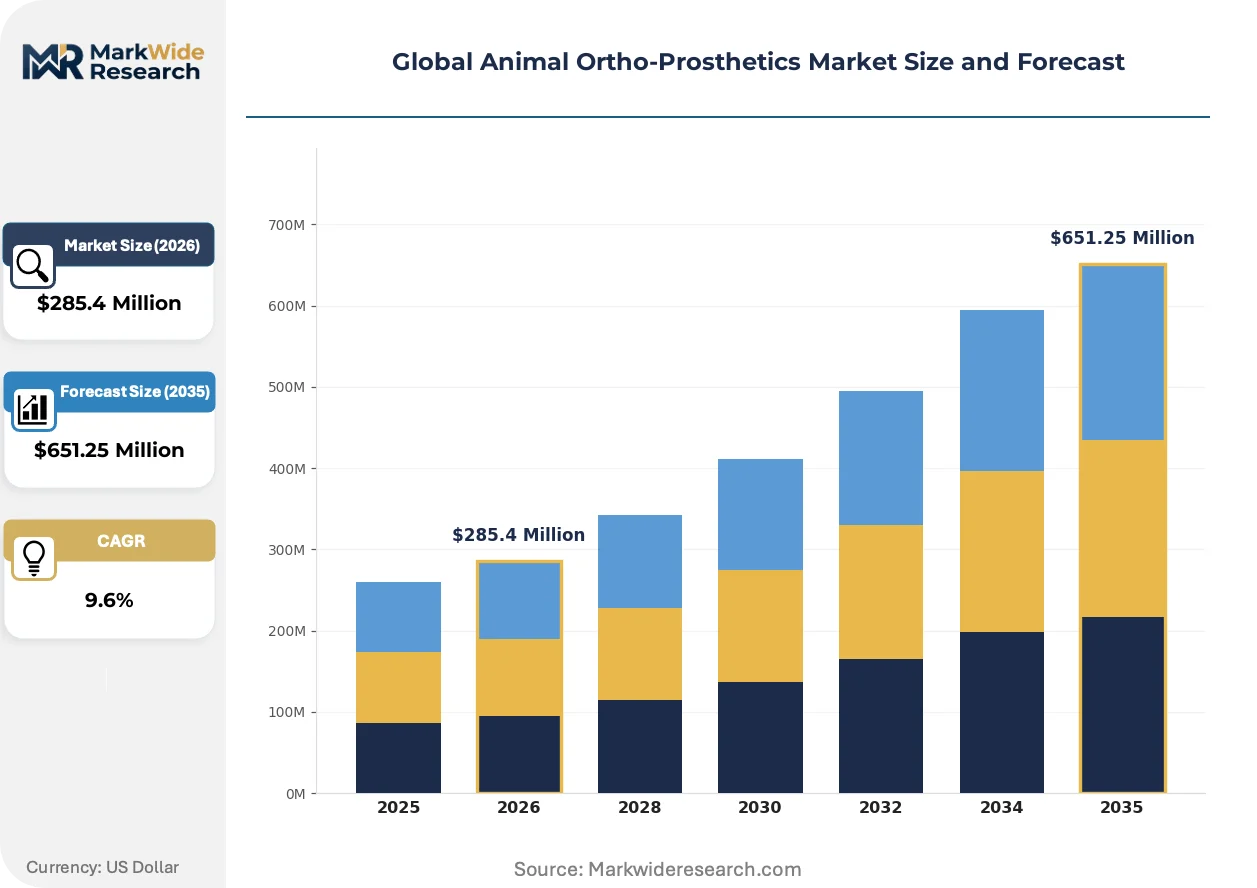
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $651.25 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prosthetics, Orthotics, Braces, Splints End User: Veterinary Clinics, Animal Hospitals, Pet Owners, Rehabilitation Centers Application: Mobility Improvement, Pain Management, Post-Injury Recovery, Support Material: Plastics, Metals, Composites, Synthetic Fabrics |
| Companies Covered | OrthoPets LLC, Animal Ortho Care, Bionic Pets, Walkin’ Pets, K-9 Orthotics & Prosthetics, Össur Veterinary, My Pet’s Brace, Orthomed (UK) Ltd, Petsthetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Ortho-Prosthetics Market Shifts & Advancements
Digital fabrication workflows and outcome-linked service models are compressing the traditional veterinarian-device maker value chain into integrated care platforms.
Polypropylene co-polymer socket blanks with embedded pressure-mapping sensors enable real-time fit adjustment without recasting. Specialty rehabilitation centers in Germany and the United States adopt these smart interfaces at 35% of new fittings. The technology is modularizing the prosthetic supply chain by separating diagnostic hardware from fabrication services.
Japan's PMDA revised import documentation requirements for veterinary medical devices in 2023, mandating domestic clinical validation for novel materials. European exporters face 4-6 month registration delays versus pre-change timelines. High-composite prosthetic categories absorb the greatest compliance burden, shifting competitive advantage toward local Japanese fabricators.
Pet owners increasingly self-refer to orthotic specialists after initial veterinary diagnosis, bypassing clinic markup on device procurement. Direct-to-consumer channels in the United States and United Kingdom capture 18% of brace orders previously routed through general practice. This disintermediation concentrates in sports medicine applications where owners possess prior exposure to human athletic bracing concepts.
Global Animal Ortho-Prosthetics Market Segmentation
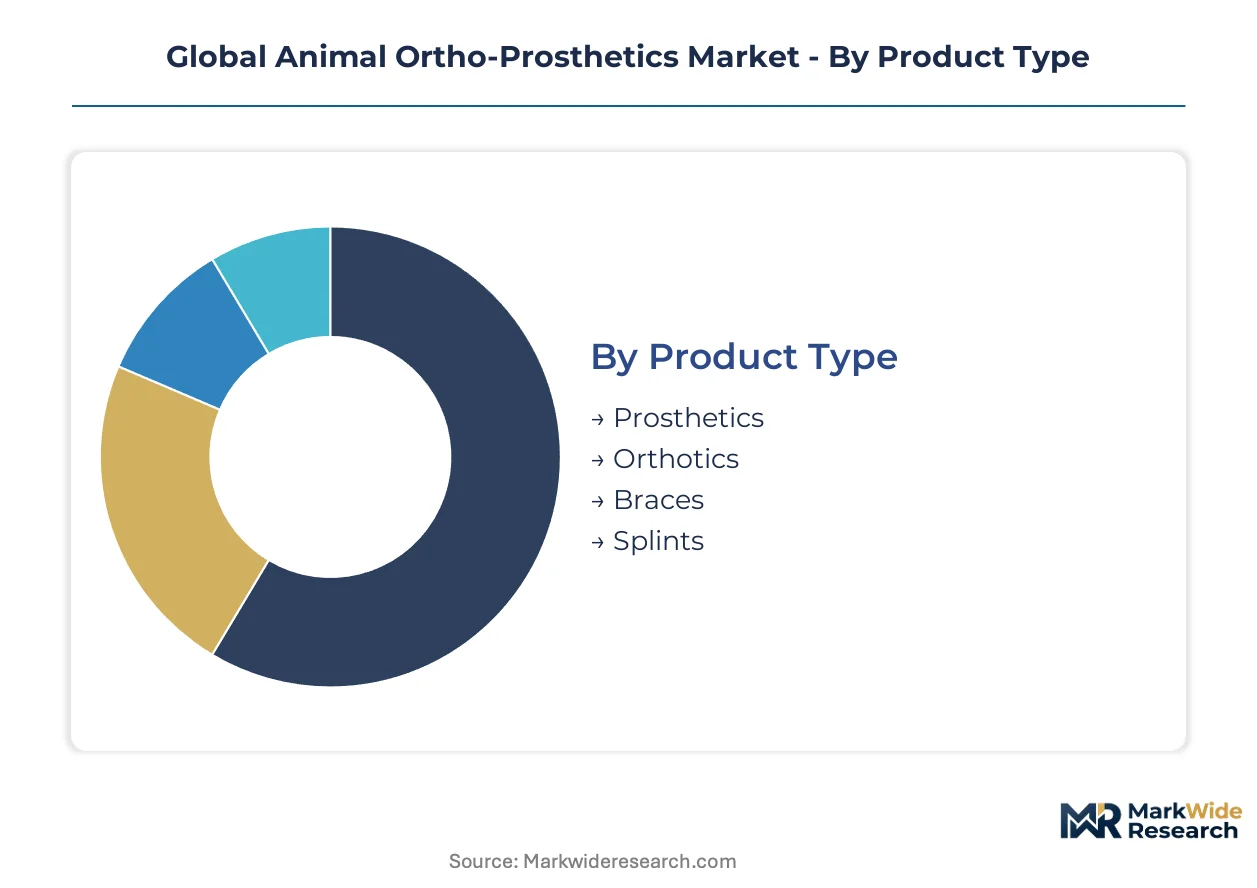
Animal ortho-prosthetics demand fragments across fabrication methods, clinical settings, and material specifications. Each segmentation axis reveals distinct margin structures and competitive entry points for device manufacturers and service providers.
Product Type:
Customization intensity varies from fully bespoke socket fabrication to off-the-shelf modular systems across this category.
- Prosthetics:Complete limb replacement devices fabricated from carbon fiber composites or medical-grade aluminum alloys. Veterinary clinics in Germany and the United States concentrate demand for forelimb and hindlimb prosthetics as pet insurance coverage expands for traumatic amputation cases.
- Orthotics:External support devices stabilizing existing limb structures through thermoplastic polymer frames. Rehabilitation centers in Japan represent the steepest adoption curve for stifle and carpal orthotics among aging canine populations.
- Braces:Preventive and post-operative stabilization systems with adjustable hinge mechanisms.
- Splints:Temporary immobilization devices for acute fracture management and post-cast transition.
Most installed capacity flows through Orthotics. Expansion is steepest in Braces as canine sports medicine applications multiply.
End User:
Prescription authority and fitting expertise create tiered access points from credentialed specialists to direct-to-consumer channels.
- Veterinary Clinics:Primary diagnostic and prescription gatekeepers bundling device procurement with surgical consultation. Clinics in the United States capture the dominant revenue share through markup on custom-fabricated devices and fitting service fees.
- Rehabilitation Centers:Certified canine rehabilitation practitioners delivering gait analysis and device adjustment protocols. German specialty centers are expanding fastest as referral networks formalize between orthopedic surgeons and physical therapy facilities.
- Animal Hospitals:Emergency and tertiary care institutions managing acute trauma cases requiring immediate stabilization.
- Pet Owners:Self-referring consumers accessing direct-to-consumer channels for sports medicine bracing and replacement components.
Margin concentration sits with Veterinary Clinics. Volume growth is climbing fastest through Rehabilitation Centers as credentialing programs expand.
Application:
Clinical outcomes and reimbursement eligibility segment demand across acute intervention and chronic management scenarios.
- Mobility Improvement:Devices restoring ambulatory function for congenital deformities, traumatic amputations, and degenerative conditions. United States pet owners drive concentrated demand as working dog retirement protocols extend active service life.
- Post-Injury Recovery:Temporary and transitional support during surgical healing and tissue regeneration periods. Japanese veterinary practices are expanding fastest in this segment as TPLO and other orthopedic surgery volumes rise.
- Pain Management:Offloading devices reducing mechanical stress on osteoarthritic joints.
- Support:Preventive bracing for athletic and working animals in high-impact disciplines.
Revenue weighting favors Mobility Improvement. Adoption is accelerating most quickly in Post-Injury Recovery as surgical referral networks mature.
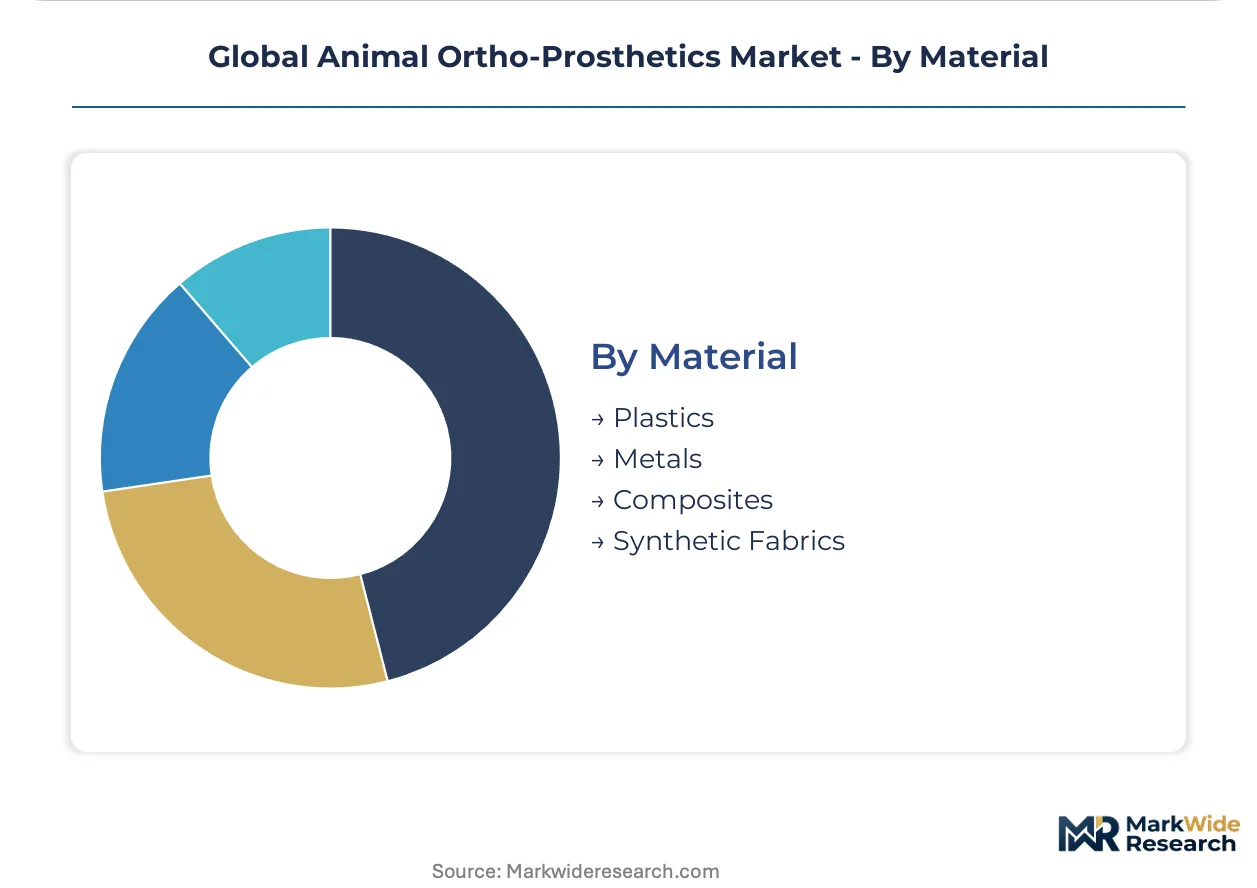
Material:
Performance specifications and cost structures differentiate material selection across patient weight classes and activity levels.
- Composites:Carbon fiber and aerospace-grade laminates delivering 40% weight reduction versus thermoplastic alternatives. German manufacturers concentrate supply for large-breed and working animal applications where device durability determines clinical outcomes.
- Metals:Medical-grade aluminum alloys and titanium components for structural frames and articulation mechanisms. United States fabricators are expanding fastest in titanium sourcing as aerospace supply chain integration deepens.
- Plastics:Polypropylene and thermoplastic polymers for socket blanks and adjustable interface components.
- Synthetic Fabrics:Nylon and neoprene padding systems for comfort layers and suspension mechanisms.
Production volume concentrates in Plastics. Technology investment is flowing fastest into Composites as pressure-sensing integration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting fabrication investment toward jurisdictions with streamlined veterinary device pathways. Manufacturers in Germany and Japan exploit CE marking efficiencies and domestic clinical validation requirements respectively, while United States fabricators absorb extended FDA Center for Veterinary Medicine consultation cycles.
United States
Pet insurance penetration exceeding 4 million covered animals drives demand for traumatic amputation prosthetics. FDA Center for Veterinary Medicine oversight of device safety claims creates pre-market bottlenecks that extend registration timelines. Colorado-based specialty clinics concentrate fitting expertise, with Denver and Fort Collins emerging as rehabilitation center accreditation hubs.
Germany
Working dog retirement protocols and canine sports medicine expand preventive bracing volumes. EU Medical Device Regulation streamlined conformity assessment accelerates Class I veterinary device cross-border commercialization. Munich and Stuttgart industrial clusters integrate aerospace carbon fiber supply chains into veterinary prosthetic fabrication.
Japan
Ministry of Agriculture, Forestry and Fisheries data showing 28% of owned dogs exceed 10 years creates geriatric mobility intervention demand. PMDA revised import documentation requirements in 2023, mandating domestic clinical validation for novel materials. Tokyo and Osaka rehabilitation centers absorb the steepest adoption curve for stifle and carpal orthotics.
United Kingdom
Direct-to-consumer channels capture 18% of brace orders previously routed through general practice veterinary clinics. CE marking framework governs post-Brexit device registration through retained EU law alignment. London and Manchester specialty centers formalize referral networks between orthopedic surgeons and physical therapy facilities.
Canada
Health Canada and PMRA coordinate veterinary medical device standards with United States FDA harmonization efforts. Alberta and British Columbia working dog populations sustain demand for forelimb and hindlimb prosthetics. Calgary rehabilitation centers are expanding fastest as credentialing programs for certified canine rehabilitation practitioners multiply.
Global Animal Ortho-Prosthetics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium custom fabricators defending margin pools against modular system assemblers. The vendor base concentrates among North American and European entities with direct veterinary clinic relationships, while Asian fabricators remain supply-side concentrated. Three archetypes dominate: proprietary workflow specialists, direct-to-consumer educators, and human-grade technology transferors. Competitive moves center on rehabilitation center accreditation partnerships and telehealth fitting protocol development.
Among United States-based specialists, OrthoPets LLC and Bionic Pets occupy distinct positioning archetypes, while Össur Veterinary represents European human-grade technology transfer. OrthoPets exemplifies the proprietary digital workflow model sustaining premium positioning across specialty clinics. Bionic Pets anchors the direct-to-consumer education archetype that reduces traditional clinic dependency. Össur Veterinary sits within the composite fabrication tier, transferring aerospace-derived lamination techniques into veterinary applications.
| Leading Market Players |
|---|
| OrthoPets LLC |
| Animal Ortho Care |
| Bionic Pets |
| Walkin' Pets |
| K-9 Orthotics & Prosthetics |
| Össur Veterinary |
| My Pet's Brace |
| Orthomed (UK) Ltd |
| Petsthetics |
| Others |
Supply & Pricing Matrix
Carbon fiber composite sourcing from aerospace supply chains feeds through fabrication cost structures into premium device pricing tiers, with German and United States manufacturers absorbing input volatility differently across custom-fitted versus modular product lines.
Pricing Analysis
Veterinary clinic markup on device procurement sustains the dominant margin pool, with prescription authority bundling fitting service fees into per-unit transactional pricing. Price differentiation hinges on customization intensity and CCO-certified fitting expertise, with direct-to-consumer channels compressing margins for sports medicine bracing. Cost compression in modular thermoplastic segments is intensifying because pet owner self-referral bypasses traditional gatekeeping. General practice veterinary clinics exhibit highest price sensitivity, while specialty rehabilitation centers prioritize clinical outcome guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Russian and Chinese titanium sponge producers supplying medical-grade Ti-6Al-4V for structural frames. Fabrication capacity concentrates in Germany, the United States, and Japan, drawing from aerospace carbon fiber laminates, medical-grade aluminum alloys, and polypropylene co-polymers. Commodity price volatility in titanium alloy inputs exposes fabricators to margin erosion without long-term offtake hedging. Distribution runs through veterinary clinic procurement channels bundling diagnostic prescription with device fulfillment, though rehabilitation center direct sourcing is gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal ortho-prosthetics function as a stable compounder anchored by irreversible pet humanization trends that sustain premium mobility intervention spending across economic cycles.
For Market Incumbents: Acquire certified canine rehabilitation practitioner credentialing programs to lock in preferred vendor status against emerging modular system assemblers. Deepen backward integration into carbon fiber lamination capacity in Germany and the United States to defend margin position against aerospace supply chain volatility. Channel control through exclusive rehabilitation center partnerships represents the critical defensive lever. For New Entrants and Emerging Players: CE marking under EU MDR opens a window for streamlined Class I veterinary device commercialization without protracted FDA consultation cycles. Japan's PMDA domestic clinical validation mandate creates white-space opportunity for local fabrication partnerships serving geriatric mobility demand. Telehealth fitting protocols targeting sports medicine pet owners offer the most penetrable go-to-market angle bypassing clinic gatekeeping. For Investors and Strategic Acquirers: Consolidation pressure builds where orthopedic casting technician scarcity constrains CCO program graduation rates below market demand growth. Five-to-ten year viability favors proprietary digital workflow specialists with captive rehabilitation center networks over commodity modular assemblers. Watch ISO 10993 biocompatibility testing backlog duration as the inflection signal for new material introduction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Rehabilitation Center Accreditation Partnership | CCO credentialing programs in Colorado and Alberta create preferred vendor lock-in for device suppliers. |
| Telehealth Fitting Protocol Development | Smartphone accelerometry integration bypasses veterinary clinic markup capture in sports medicine segments. |
| Domestic Clinical Validation Investment | PMDA compliance infrastructure in Tokyo and Osaka defends Japanese market access against European exporters. |
| Carbon Fiber Lamination Capacity Expansion | Munich and Stuttgart aerospace supply chain integration reduces device weight for large-breed applications. |
| Direct-to-Consumer Education Platform | Pet owner self-referral channels in the United Kingdom and United States capture brace orders outside clinic procurement. |
Research Methodology
Bottom-up veterinary clinic and rehabilitation center demand modeling reconciled against top-down carbon fiber composite and titanium alloy supply tracking forms the analytical core. Primary interviews with veterinary orthopedic surgeons, CCO-certified orthotists, rehabilitation center directors, and pet insurance underwriting specialists combined with secondary validation from FDA Center for Veterinary Medicine filings, EU MDR registration databases, PMDA import documentation records, and Japanese Ministry of Agriculture statistics.
Historical trendline analysis across prosthetic fitting volumes, brace shipment data, and material consumption patterns established baseline growth trajectories. Segmentation modeling spanned product type, end-user channel, application scenario, and material specification across the projection horizon. CAGRs derived from fitted trend extrapolation adjusted for regulatory pathway efficiency differentials and pet insurance penetration curves.
Revisions become necessary when FDA 510(k) pathway ambiguity resolves into formal guidance, EU MDR veterinary device classification shifts, or titanium alloy supply disruptions from geopolitical events materialize. Forecasts embed assumptions about CCO program expansion rates, telehealth regulatory acceptance, and composite material innovation cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
High Energy Shockwave Therapy Units Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Bone Void Fillers Market
Orthopedic Devices
Global Orthopedic Digit Implants Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
USA Spinal Surgery Devices Market