
 Global Shoulder Replacement Market | 2026-2036
Global Shoulder Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shoulder Replacement Market Outlook
Orthopedic surgeon training capacity is redrawing competitive boundaries in shoulder arthroplasty. Stryker Corporation leverages its proprietary navigation platforms to anchor premium positioning in computer-assisted implantation. Zimmer Biomet sustains manufacturing scale across four continents, while Smith & Nephew differentiates through specialized shoulder portfolios in sports medicine channels.
Shoulder replacement encompasses prosthetic reconstruction of the glenohumeral joint using cobalt-chromium or titanium alloy humeral components mated to ultra-high molecular weight polyethylene glenoid inserts, restoring rotational mobility in patients with end-stage osteoarthritis or rotator cuff arthropathy. Reverse shoulder systems lead volume due to expanded indications for cuff-deficient patients, while cementless fixation technology captures fastest-growing adoption as osseointegration surfaces improve. Ambulatory surgical centers represent the most concentrated margin pool as procedural migration accelerates.
FDA premarket notification pathways and EU MDR conformity assessments shape implant approval timelines and clinical evidence requirements for manufacturers seeking transatlantic market access. Japan's PMDA and South Korea's MFDS impose distinct biocompatibility testing protocols that fragment regulatory strategy. Stakeholders must monitor CMS reimbursement determinations and EU Green Deal material sourcing mandates as dual vectors reshaping procurement criteria.
Market Dynamics
Procedural migration toward ambulatory surgical centers is compressing hospital revenue per case while forcing implant manufacturers to reconfigure logistics for same-day discharge protocols across Germany, the United States, and Japan.
Growth Catalysts
- Japan's PMDA pathway streamlining:Accelerated approval timelines for reverse shoulder systems are concentrating new product launches in Tokyo-Osaka hospital networks serving the super-aged population.
- Cementless fixation surfaces:Porous titanium coatings with enhanced osseointegration properties are displacing cemented humeral stems in academic medical centers prioritizing long-term survivorship data.
- South Korea's MFDS reimbursement expansion:National health insurance coverage for reverse shoulder arthroplasty in cuff-deficient patients is driving procedural volume in Seoul metropolitan clusters.
Market Restraints
- Cobalt-chromium supply concentration:Primary smelting capacity for orthopedic-grade alloys clusters in a limited number of European and Chinese suppliers, exposing manufacturers to input volatility.
- EU MDR clinical evidence requirements:Extended post-market surveillance obligations and notified body backlogs are stretching conformity assessment timelines for legacy implant portfolios.
- Polyethylene insert degradation:Oxidative wear in retrieved glenoid components continues to limit implant longevity claims, constraining marketing differentiation among competing bearing surfaces.
Strategic Opportunities
- India's CDSCO orthopedic device notification pathway:Streamlined import licensing for FDA-cleared implants is opening private hospital networks in Mumbai, Delhi, and Bangalore to premium shoulder systems.
- Computer-assisted navigation convergence:Integration of preoperative planning software with intraoperative robotic guidance is creating new service revenue streams in high-volume arthroplasty centers.
- EU Green Deal material sourcing mandates:Recycled titanium and conflict-free cobalt certification requirements are favoring suppliers with vertically controlled supply chains and documented provenance systems.
Industry Challenges
- Shoulder arthroplasty fellowship capacity:Limited accredited training positions in the United States and Germany are constraining surgeon supply expansion needed for procedural volume growth.
- Legacy hospital EHR integration:Implant tracking systems and surgical workflow software require costly interoperability upgrades to meet FDA Unique Device Identification mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shoulder Replacement Market |
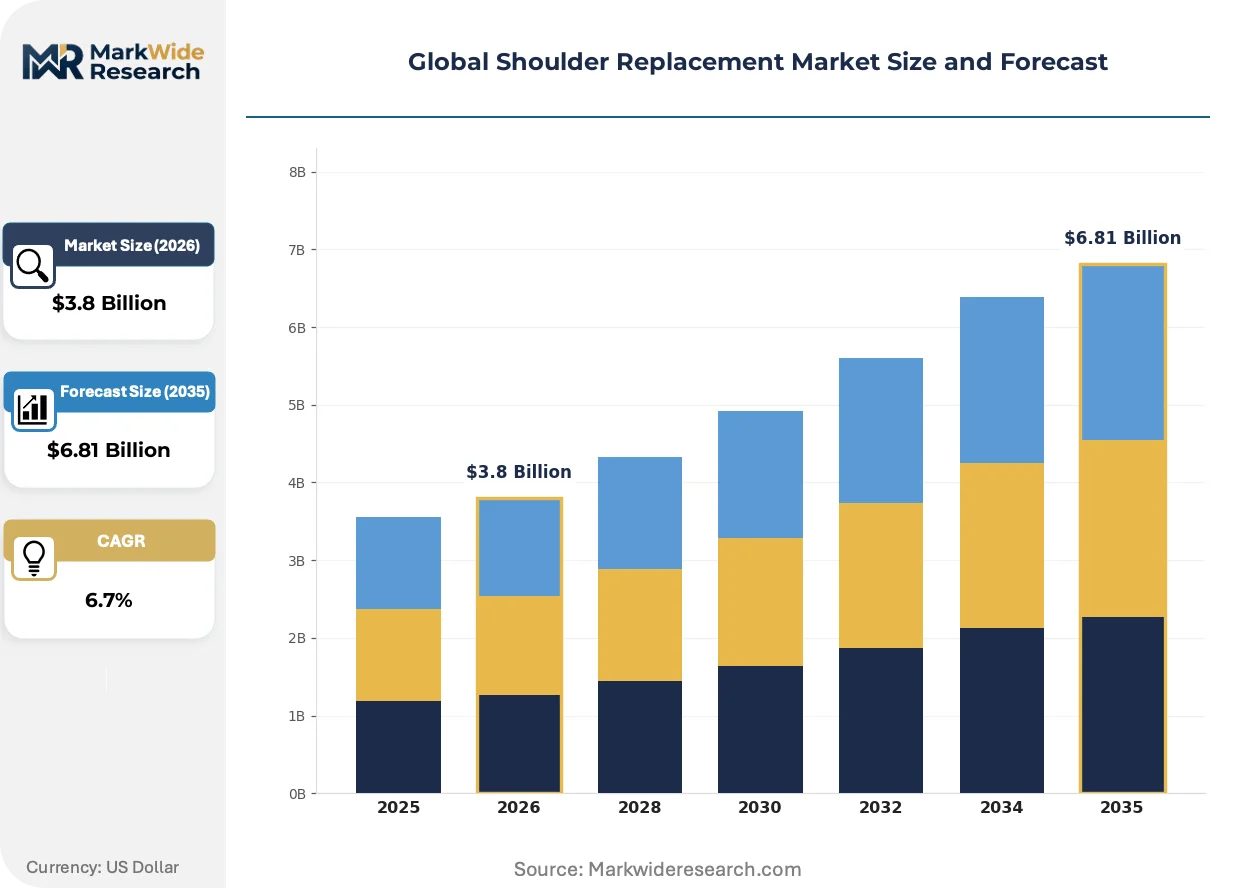
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse, Anatomic, Stemless, Partial End User: Hospitals, Orthopedic Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Technology: Cemented, Cementless, Hybrid, Computer-Assisted Material: Metal, Polyethylene, Ceramic, Composite |
| Companies Covered | Zimmer Biomet, Stryker Corporation, DePuy Synthes, Arthrex, Johnson & Johnson, Smith & Nephew, Wright Medical Group, Integra LifeSciences, Exactech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shoulder Replacement Market Strategic Shifts
Patient-specific instrumentation and additive manufacturing are collapsing the gap between preoperative planning and intraoperative execution, while regulatory pressure on material traceability is forcing supply chain visibility investments.
Patient-specific 3D-printed glenoid guides are miniaturizing preoperative planning into disposable sterilized instruments matched to individual anatomy. High-volume shoulder centers in Germany and the United States are adopting these guides for complex revision cases with significant bone loss. The technology is miniaturizing the traditional navigation tower into single-use disposable components that eliminate capital equipment amortization while preserving accuracy.
EU MDR Article 10 post-market clinical follow-up requirements are mandating systematic retrieval analysis and patient registry participation for all shoulder implant manufacturers. The regulation is compressing product lifecycle management timelines and forcing earlier portfolio rationalization decisions. Small-to-mid-sized orthopedic firms without dedicated clinical affairs infrastructure are outsourcing registry maintenance to specialized contract research organizations.
Same-day discharge protocols are restructuring procurement relationships between implant vendors and ambulatory surgical centers. Bundled payment models in United States Medicare Advantage plans are displacing traditional fee-for-service implant purchasing with all-inclusive procedural contracts. This shift concentrates negotiating leverage in multi-site ASC chains operating across Florida, Texas, and Arizona metropolitan markets.
Global Shoulder Replacement Market Segmentation
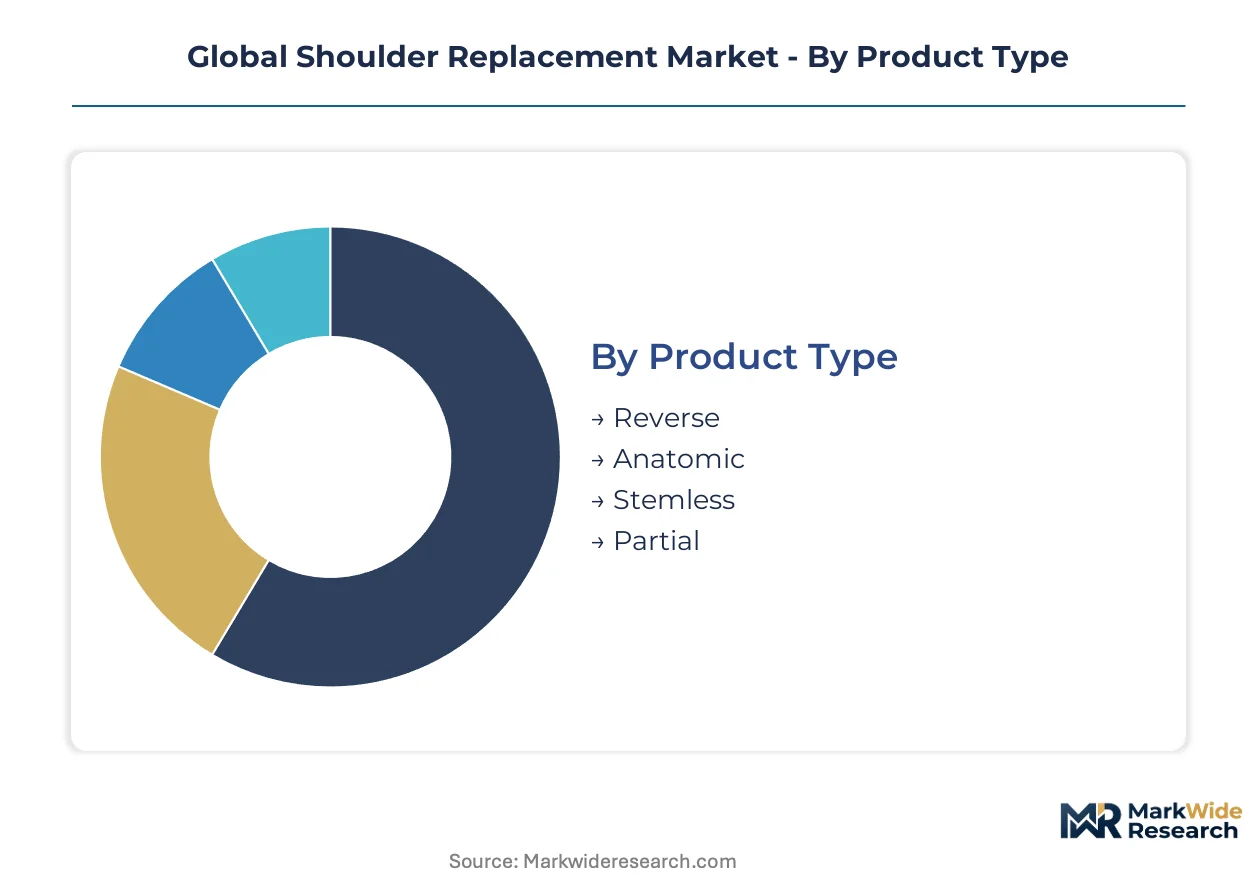
Segmentation in shoulder arthroplasty reveals how regulatory pathways, reimbursement structures, and surgical venue economics partition demand across implant configurations and delivery settings. Understanding these divisions exposes where procurement leverage concentrates and where technology premiums command pricing power.
Product Type:
FDA 510(k) clearance timelines and EU MDR clinical evidence requirements create divergent approval burdens across implant architectures, reshaping which configurations reach market first.
- Reverse:Glenosphere-mounted on glenoid and socket on humerus inverts native anatomy to deltoid-compensate for rotator cuff deficiency. Demand clusters in academic medical centers across Germany and the United States where cuff-deficient elderly patients present for complex reconstruction.
- Anatomic:Preserves native ball-and-socket orientation using humeral head resurfacing against polyethylene glenoid. Volume concentrates in Japanese metropolitan hospitals serving osteoarthritis patients with intact rotator cuffs under PMDA reimbursement pathways.
- Stemless:Humeral component anchors in metaphyseal bone without diaphyseal stem intrusion, preserving bone stock for future revision. Bone-preserving design attracts younger patient cohorts in private European clinics.
- Partial:Hemiarthroplasty replaces humeral head alone, retaining native glenoid. Limited to trauma and select osteonecrosis cases in South Korean emergency hospital networks.
Reverse systems handle the majority of throughput; stemless configurations are gaining share fastest as bone-preservation protocols expand.
End User:
Reimbursement rate differentials between facility types drive implant procurement behavior and vendor contract structures.
- Hospitals:Inpatient admission infrastructure supports complex revision arthroplasty and comorbid patient management. German university hospitals and Tokyo tertiary centers anchor volume for high-acuity cases requiring overnight monitoring.
- Orthopedic Clinics:Specialized surgical focus enables high-throughput primary arthroplasty with dedicated shoulder fellowship-trained surgeons. Munich and Hamburg clinic networks are expanding same-day programs under statutory health insurance frameworks.
- Ambulatory Surgical Centers:Bundled payment models in United States Medicare Advantage concentrate negotiating leverage in multi-site Florida and Texas chains seeking all-inclusive implant contracts.
- Rehabilitation Centers:Post-acute facilities manage functional recovery protocols but do not perform implantation; procurement limited to consumables and physical therapy equipment.
Hospitals retain the highest absolute case volume; ambulatory surgical centers are expanding most quickly as procedural migration accelerates under cost-containment pressures.
Technology:
Fixation method and intraoperative assistance technologies stratify by patient age, bone quality, and surgeon training infrastructure.
- Cemented:Polymethylmethacrylate fixation provides immediate stability in osteoporotic bone. Dominates elderly patient segments in National Health Service England facilities where bone mineral density screening guides selection.
- Cementless:Porous titanium surfaces achieve biological osseointegration without cement. Fastest-growing configuration in German and United States academic centers tracking long-term survivorship data for younger, active patients.
- Hybrid:Cemented glenoid with cementless humeral stem combines immediate fixation with bone preservation. Selective adoption in revision cases with glenoid bone loss.
- Computer-Assisted:Navigation platforms and robotic guidance systems improve component positioning accuracy. Premium pricing concentrates in high-volume United States centers with capital equipment amortization capacity.
Cemented technology maintains installed base dominance; cementless fixation is climbing the fastest as osseointegration surface engineering improves.
Material:
Biocompatibility testing protocols under Japan's PMDA and EU MDR material traceability mandates fragment supplier qualification requirements.
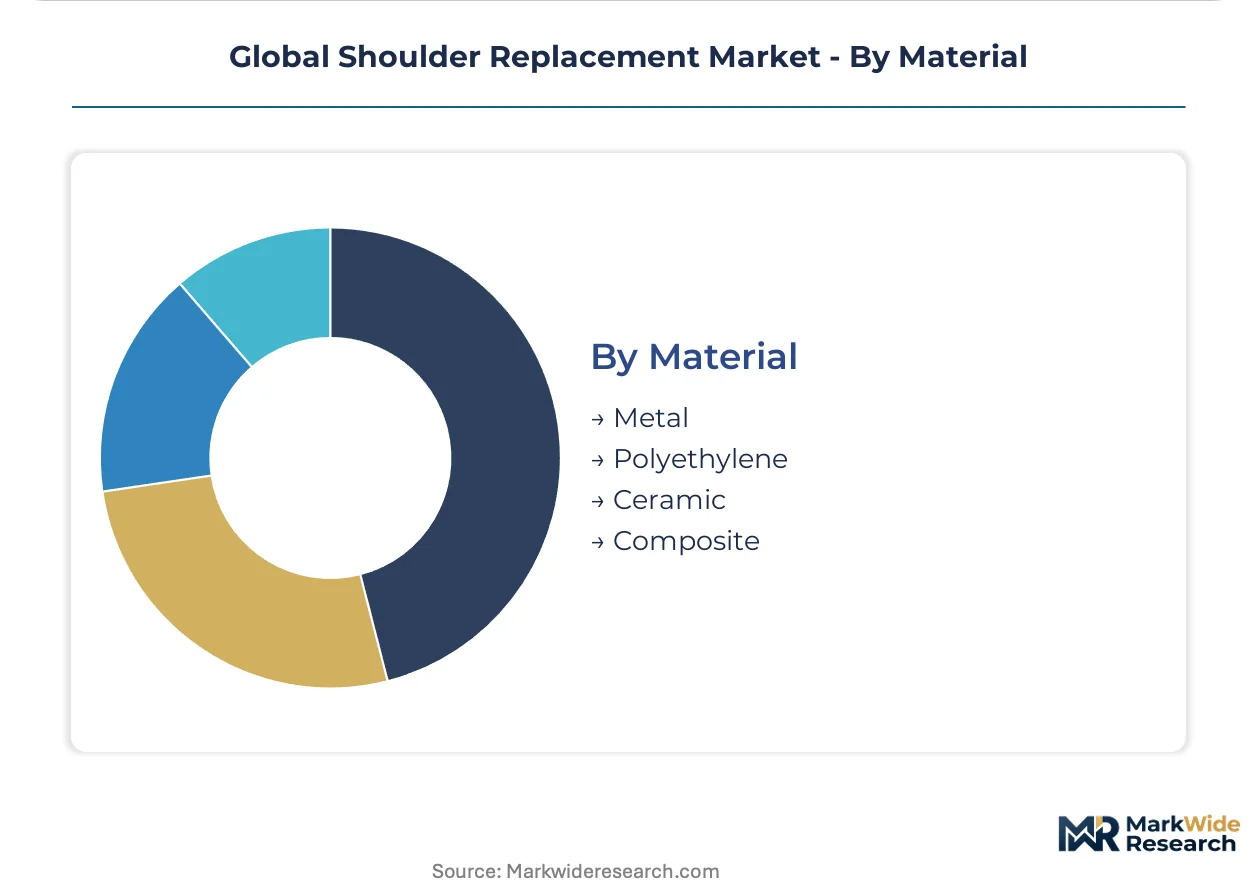
- Metal:Cobalt-chromium and titanium alloys form humeral stems and glenospheres. Supply concentration in European and Chinese smelters exposes manufacturers to input volatility under EU Green Deal sourcing mandates.
- Polyethylene:Ultra-high molecular weight polyethylene inserts provide articulating bearing surfaces. Oxidative wear limitations in retrieved components constrain longevity marketing claims across all major vendors.
- Ceramic:Alumina and zirconia composites offer reduced wear debris in young, active patients. Limited adoption due to fracture risk and premium pricing in Japanese private hospital segments.
- Composite:Carbon fiber-reinforced polymers and PEEK components address specific load-bearing requirements. Niche applications in sports medicine channels for glenoid augmentation.
Metal alloys handle the majority of structural load-bearing; ceramic components are expanding most quickly in premium private-pay segments despite cost barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States consume shoulder replacement systems through ambulatory channels at substantially higher rates than Japan, where inpatient monitoring protocols dominate reimbursement structures.
United States
Medicare Advantage bundled payment models are concentrating procurement leverage in multi-site ASC chains across Florida, Texas, and Arizona. FDA 510(k) clearance pathways enable rapid reverse shoulder system launches. Hospital networks in the Dallas-Fort Worth metroplex are expanding same-day discharge protocols for primary arthroplasty.
Germany
Statutory health insurance frameworks are reimbursing orthopedic clinic-based shoulder arthroplasty at rates competitive with hospital settings. EU MDR notified body backlogs are stretching conformity timelines for legacy implant portfolios. Munich and Hamburg clinic networks are scaling same-day programs with dedicated shoulder fellowship-trained surgeons.
Japan
PMDA accelerated approval pathways for reverse shoulder systems are concentrating new product launches in Tokyo-Osaka hospital corridors. National reimbursement policies favor inpatient admission for elderly patients with comorbidities. Tertiary centers in the Kanto region are tracking long-term survivorship data for cementless fixation surfaces.
South Korea
MFDS national health insurance expansion for reverse shoulder arthroplasty in cuff-deficient patients is driving procedural volume. Biocompatibility testing protocols distinct from FDA and EU standards fragment regulatory strategy. Seoul metropolitan hospital clusters are absorbing the majority of new case volume.
India
CDSCO streamlined import licensing for FDA-cleared implants is opening private hospital networks to premium shoulder systems. Out-of-pocket payment dominance in orthopedic surgery creates three-tier pricing stratification across premium, standard, and economy implant levels. Mumbai, Delhi, and Bangalore hospital groups are building dedicated shoulder arthroplasty units.
Global Shoulder Replacement Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated in multi-continental manufacturing footprints and navigation platform ecosystems. The vendor base separates into three archetypes: diversified orthopedic conglomerates with full joint reconstruction portfolios, shoulder-dedicated specialists with sports medicine channel access, and emerging navigation-anchored platform players. Competitive moves center on M&A for cementless surface technology and strategic partnerships with ASC chains for bundled contract capture.
Within the diversified orthopedic tier, Zimmer Biomet and Stryker Corporation exemplify scale-driven positioning across four-continent manufacturing footprints. Smith & Nephew occupies a specialist position with concentrated shoulder portfolio depth. These three entities anchor the premium tier where computer-assisted navigation convergence creates service revenue differentiation in high-volume arthroplasty centers.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Stryker Corporation |
| DePuy Synthes |
| Arthrex |
| Johnson & Johnson |
| Smith & Nephew |
| Wright Medical Group |
| Integra LifeSciences |
| Exactech |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for cobalt-chromium feedstock expose implant manufacturers to both spot-price volatility and concentrated supplier leverage across European and Chinese smelters. This lead-time exposure concentrates pricing power with alloy processors while forcing arthroplasty vendors into long-term offtake commitments to secure orthopedic-grade material certification under EU Green Deal traceability mandates.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between implant vendors and ambulatory surgical center chains, displacing spot purchasing as bundled payment models expand. Price differentiation rests on FDA clearance tier and surgeon training certification level, with premium navigation-enabled systems commanding substantial markups over standard configurations. Cost compression in economy-tier cemented stems is intensifying as Indian private hospital networks drive volume procurement. Multi-site ASC chains in Florida and Texas exhibit the highest price sensitivity, while German university hospitals prioritize longevity data over unit cost.
Supply Chain Analysis
Strait of Malacca transit routes for titanium sponge feedstock underpin supply security for porous coating manufacturers serving cementless fixation demand. Primary smelting capacity clusters in Germany, China, and Austria, with secondary processing concentrated in South Korea and Japan for PMDA-compliant surface finishing. Raw material dependencies center on cobalt-chromium alloy, titanium sponge, and ultra-high molecular weight polyethylene resin. Single-source vulnerability in European orthopedic-grade alloy production creates tariff exposure under evolving EU-China trade frameworks. Distribution runs through authorized distributor networks with surgeon training bundling, though direct-to-hospital contracts are expanding in high-volume metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the shoulder arthroplasty vendor base creates entry niches as procedural migration toward ambulatory settings fragments procurement authority away from centralized hospital purchasing committees.
For Market Incumbents: Secure cementless surface technology through targeted acquisition of specialized coating firms, as osseointegration performance becomes the primary surgeon selection criterion. Lock in multi-year exclusive supply agreements with ASC chains in Florida, Texas, and Arizona before bundled payment models fully mature, defending against emerging platform players with navigation-anchored offerings. For New Entrants and Emerging Players: Differentiate on patient-specific instrumentation for complex revision cases with significant bone loss, where established vendors lack dedicated portfolio depth. Target India's CDSCO notification pathway for FDA-cleared implants, as Mumbai and Delhi private hospital networks build dedicated shoulder arthroplasty units with limited incumbent loyalty. Pursue sports medicine channel partnerships as the primary go-to-market angle, leveraging orthopedic clinic relationships outside traditional hospital procurement structures. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because reimbursement compression and EU MDR compliance costs will force portfolio rationalization among sub-scale specialists. Acquisition targets should prioritize firms with proprietary cementless surface technology or established ASC chain contracts. Watch MFDS reimbursement expansion velocity in South Korea as the signal indicating whether East Asian regulatory pathways will accelerate or constrain volume growth.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body backlogs stretch conformity timelines, favoring firms with dedicated clinical affairs infrastructure. |
| Hospital System Partnership | Exclusive vendor status in German orthopedic clinic networks secures same-day procedure volume under statutory health insurance. |
| Software Companion Development | Preoperative planning integration with intraoperative navigation creates service revenue streams in high-volume arthroplasty centers. |
| Reimbursement Strategy | Medicare Advantage bundled payment capture in Florida and Texas ASC chains concentrates negotiating leverage for implant vendors. |
| FDA Submission | 510(k) clearance for reverse shoulder systems enables rapid launch in United States academic medical centers tracking cuff-deficient patient outcomes. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up implant volume estimates triangulated against top-down market sizing from trade customs data and manufacturer revenue disclosures.
Across the analysis window, the forecasting framework modeled demand by product configuration, fixation technology, end-user facility type, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, reimbursement rate evolution, and implant price elasticity assumptions. Specific inputs included Japan's PMDA approval timeline data, MFDS reimbursement expansion schedules, and EU Green Deal material sourcing compliance cost estimates.
The analysis sits within stated boundaries; outcomes outside current FDA, EU MDR, PMDA, and MFDS regulatory trajectories would require recalibration. Forecasts reflect assumptions about surgeon training capacity expansion, ASC migration velocity, and cobalt-chromium supply stability. Practitioners should keep alternative scenarios live as CMS reimbursement determinations and EU-China trade framework evolution reshape procurement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Total Ankle Replacement Market
Orthopedic Devices
Orthopedic Support Systems Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Global Orthopedic Bone Cement Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Orthopedic Splints and Casts Market
Orthopedic Devices
Middle East and Africa Knee Cartilage Repair Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
India Spinal Surgery Devices Market
Orthopedic Devices
Spine Devices Market