
 Global Patient Lateral Transfer Devices Market | 2026-2036
Global Patient Lateral Transfer Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient Lateral Transfer Devices Market Foresight
Aftermarket service revenue is tilting toward predictive maintenance contracts for powered lateral transfer systems. Stryker leverages its installed base of hospital beds to bundle transfer device servicing with capital equipment contracts. HoverTech International specializes in single-use disposable slide sheets, competing against reusable alternatives on infection control metrics.
Patient lateral transfer devices are mechanical or powered systems designed to move immobile patients horizontally between surfaces such as beds, stretchers, and imaging tables, typically employing low-friction materials or air-assisted cushions to reduce shear forces below 25 pounds of pull force for caregiver safety. Their primary purpose is eliminating manual lifting injuries among nursing staff while maintaining patient skin integrity during repositioning. Transfer sheets fabricated from ultra-low-friction fabrics dominate unit volume due to universal compatibility with existing hospital beds, while powered air-assisted systems command premium positioning in bariatric and critical care applications where single-caregiver operation is mandatory. The end-user landscape fragments across hospitals, which anchor capital purchases, and home care, where lightweight disposable slide pads are gaining traction as discharge planning extends patient mobility support into residential settings.
The FDA regulates powered lateral transfer devices as Class II medical devices under 21 CFR 880.5500, requiring 510(k) clearance for air-assisted and motorized systems, while the EU Medical Device Regulation mandates clinical evaluation and post-market surveillance under CE marking obligations. ISO 10535 standards for patient hoists and transfer devices establish international benchmarks for sling integrity and safe working loads that manufacturers must meet for market access across jurisdictions. Stakeholders must monitor how reimbursement coding for safe patient handling programs evolves, as bundled payment models increasingly reward hospitals that demonstrate measurable reductions in caregiver musculoskeletal injuries through engineered transfer protocols.
Market Dynamics
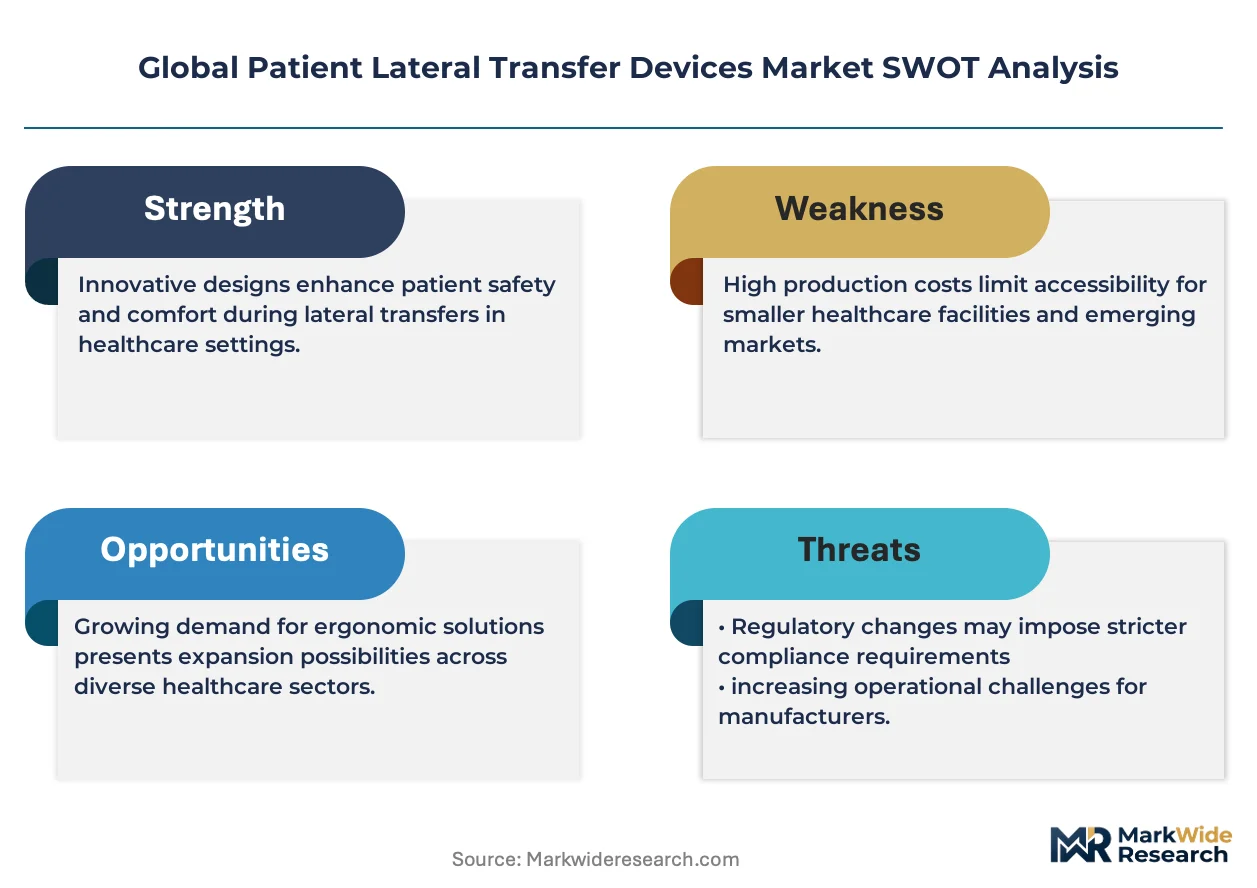
Powered air-assisted transfer systems are compressing manual lift protocols in acute care, as hospital procurement departments bundle these devices with safe patient handling mandates to reduce nursing staff injury claims and insurance premiums.
Growth Catalysts
- OSHA safe patient handling directives:US hospitals face escalating workers compensation costs from caregiver musculoskeletal injuries, accelerating capital allocation toward engineered transfer solutions that demonstrably reduce pull forces below injury thresholds.
- Bariatric patient volume expansion:Rising obesity prevalence in critical care units creates mandatory demand for single-caregiver transfer capabilities that manual methods cannot safely address.
- EU MDR biocompatibility tightening:Stricter electrical safety and material testing requirements for powered transfer equipment are filtering out marginal suppliers and consolidating procurement toward certified system integrators.
Market Restraints
- Medical-grade polymer input volatility:Specialized low-friction fabric substrates depend on petroleum-derived feedstocks subject to energy market fluctuations, compressing margins for disposable slide sheet manufacturers.
- Capital equipment replacement cycles:Hospital budget constraints extend depreciation schedules for existing manual transfer aids, delaying conversion to powered systems even where total cost of ownership favors upgrade.
- Reusable textile competition:Autoclave-compatible transfer sheets with validated infection control protocols challenge single-use disposables on per-procedure economics in cost-conscious long-term care settings.
Strategic Opportunities
- Home care discharge extension:Lightweight disposable slide pads are penetrating residential settings as hospitals expand post-acute mobility support into patient homes, creating channel expansion beyond traditional institutional procurement.
- ISO 10535 convergence with digital load monitoring:Integration of wireless force sensors into transfer sling systems enables real-time compliance documentation for injury prevention protocols.
- India hospital infrastructure buildout:Greenfield medical facility construction under national health expansion programs creates first-mover positioning for air-assisted system suppliers establishing service networks.
Industry Challenges
- Biomedical technician specialization gaps:Powered air-assisted systems require pneumatic and electrical troubleshooting competencies that exceed standard hospital maintenance training, creating service dependency on manufacturer field engineers.
- Legacy bed fleet interoperability:Transfer device compatibility with heterogeneous hospital bed architectures from multiple suppliers demands costly adapter development and validation testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient Lateral Transfer Devices Market |
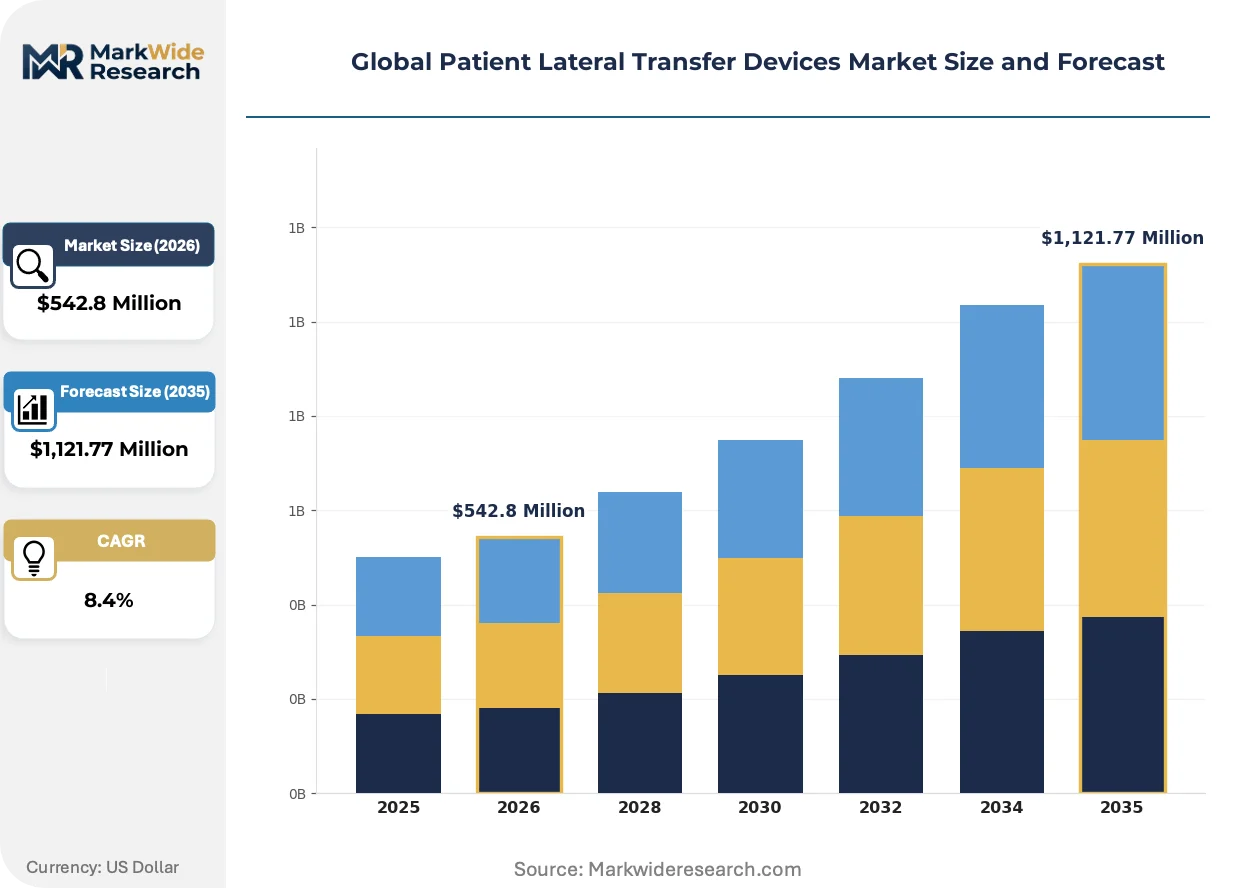
| Market Size in 2026 | $542.8 Million |
| Market Size in 2035 | $1,121.77 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transfer Sheets, Transfer Boards, Slings, Slide Pads End User: Hospitals, Nursing Homes, Rehabilitation Centers, Home Care Material: Fabric, Foam, Plastic, Metal Application: Patient Mobility, Safety Transfer, Assisting Care, Emergency Response |
| Companies Covered | Hill-Rom Holdings, Inc., AliMed, Arjo, EZ Way Inc., McAuley Medical, Stryker, HoverTech International, Patient Positioning Systems, LLC., Medline Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient Lateral Transfer Devices Market Shifts & Advancements
Active sensor integration and predictive maintenance architectures are redefining how transfer device performance is monitored and monetized, shifting vendor revenue from episodic replacement toward continuous service relationships.
Air-assisted cushion technology is migrating from high-friction mechanical surfaces to fully suspended patient interfaces that eliminate shear forces during lateral movement. Intensive care units in tertiary hospitals are adopting these systems fastest, converting capital budgets from manual lift aids to powered platforms. The technology is migrating from bariatric specialty applications toward standard critical care protocols, compressing addressable market segmentation between premium and economy tiers.
EU Medical Device Regulation post-market surveillance obligations now require clinical evaluation documentation for powered transfer systems seeking CE marking renewal. Manufacturers must maintain vigilance databases tracking adverse events across installed bases, adding compliance overhead that favors larger suppliers with dedicated regulatory affairs functions. German hospital procurement associations are consolidating supplier qualification around MDR-certified portfolios, marginalizing non-compliant competitors.
Aftermarket service contracts are unbundling from capital equipment sales as distinct revenue streams with separate P&L ownership. Hospital supply chain directors now negotiate predictive maintenance subscriptions independent of device acquisition, with payment tied to uptime guarantees rather than parts replacement. This behavioral shift is most visible in United States integrated delivery networks consolidating vendor management under centralized procurement offices.
Global Patient Lateral Transfer Devices Market Segmentation
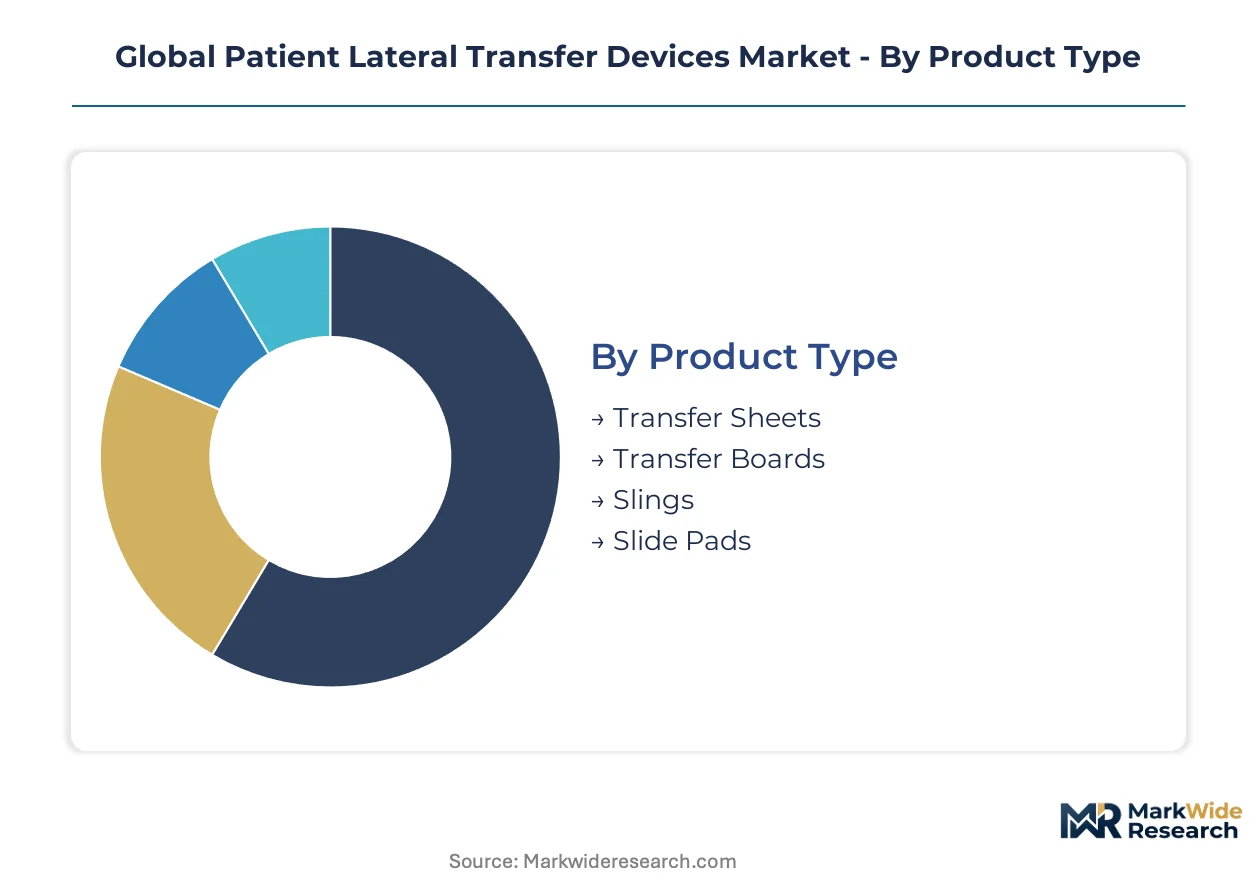
Patient lateral transfer devices fragment across four distinct classification axes, each governing different procurement rhythms and margin profiles. Cycle times vary dramatically: disposable fabric sheets turn over monthly while powered air-assisted systems depreciate over seven to ten years.
Product Type:
Replacement cycles diverge sharply across this category, with single-use disposables refreshing continuously versus capital equipment enduring multi-year depreciation schedules.
- Transfer Sheets:Ultra-low-friction woven or non-woven fabrics, often disposable, designed for horizontal patient movement between surfaces. Demand clusters in United States acute care units where OSHA safe patient handling mandates drive bulk purchasing of single-use variants to eliminate laundering logistics and infection control variables.
- Slide Pads:Thin polymer-based disposable sheets optimized for emergency department throughput and bariatric protocols where rapid turnover is mandatory. German hospital procurement associations are standardizing on MDR-certified slide pad specifications, filtering out uncertified suppliers from tender processes.
- Transfer Boards:Rigid low-friction polymer or composite platforms bridging gaps between beds and stretchers. Long-term care facilities in Japan specify JIS-standard load ratings for reusable board inventory.
- Slings:Fabric or mesh patient support interfaces integrated with powered lift systems. Rehabilitation centers in Australia require TGA-registered sling configurations for funded mobility programs.
Transfer Sheets anchor the volume base while Slide Pads gain share at the steepest rate.
End User:
Procurement authority and budget structures create tiered pricing outcomes across institutional versus residential settings.
- Hospitals:Capital-intensive purchasers with centralized supply chain offices negotiating enterprise contracts for powered air-assisted systems and bulk disposable inventories. United States integrated delivery networks bundle transfer device procurement with safe patient handling insurance premium reductions.
- Home Care:Lightweight disposable slide pads dominate as discharge planning extends hospital mobility protocols into residential settings. India's national health expansion programs are subsidizing home care transfer aids for post-surgical recovery.
- Nursing Homes:Cost-conscious operators balancing reusable textile economics against infection control mandates, often lagging hospitals in powered system adoption.
- Rehabilitation Centers:Specialized sling and board configurations for repetitive mobility training under physiotherapist supervision.
Hospitals command the premium tier while Home Care expands most quickly as post-acute care decentralizes.
Material:
Input cost volatility and sterilization compatibility determine sourcing strategies and margin compression exposure.
- Fabric:Woven polyester or nylon substrates with silicone or PTFE coatings for friction reduction. Autoclave-compatible versions challenge disposables in French long-term care settings where ANSM infection protocols favor validated reusable textiles.
- Foam:Open-cell or closed-cell cushioning integrated into air-assisted mattress overlays for pressure redistribution during transfer. Critical care units in Canada specify Health Canada-registered foam densities for bariatric applications.
- Plastic:Injection-molded polymer boards and slide pad substrates derived from petroleum feedstocks subject to energy market fluctuations.
- Metal:Aluminum or stainless steel structural components in powered transfer frame architectures requiring electrical safety certification under EU MDR and FDA 510(k) pathways.
Fabric supplies the volume foundation while Foam climbs the fastest on pressure injury prevention integration.
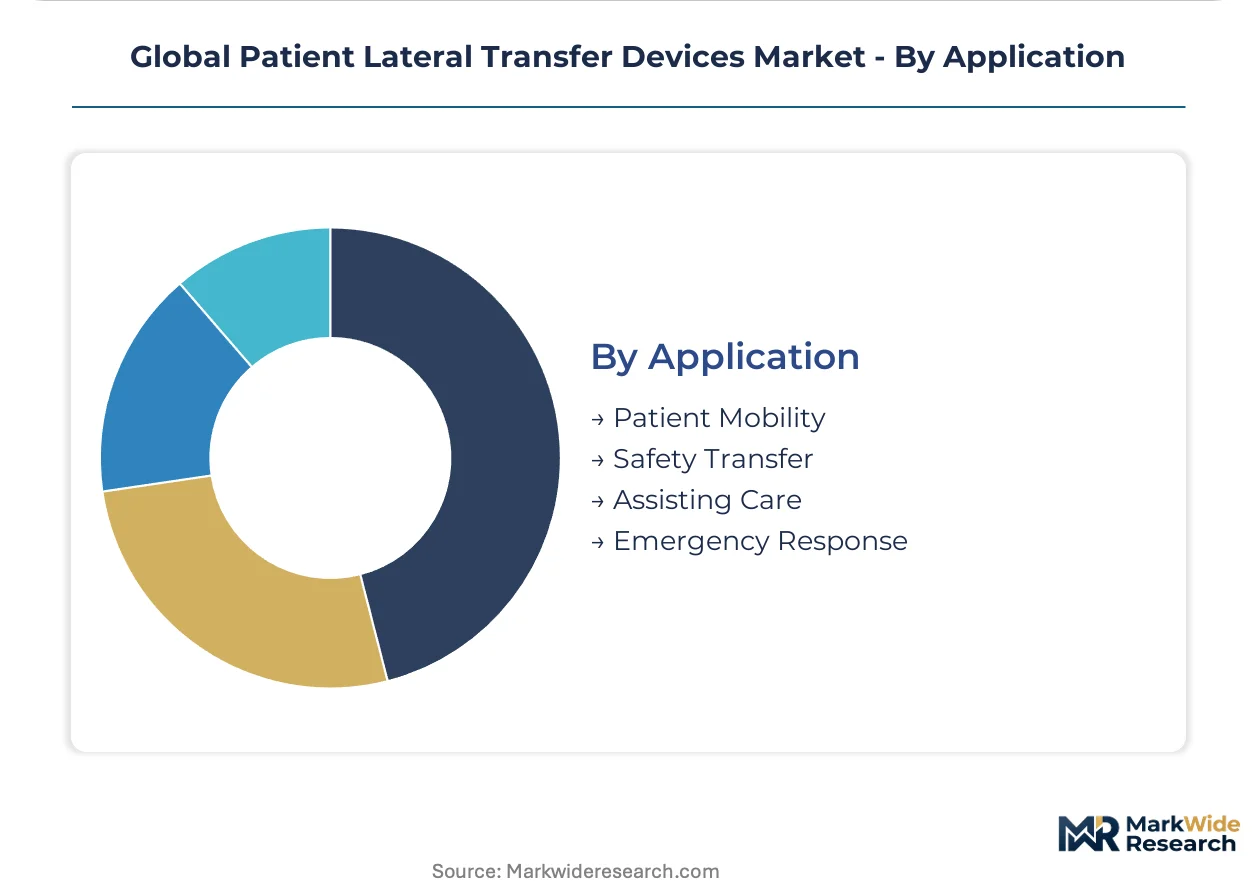
Application:
Clinical use case intensity shapes performance specifications and regulatory scrutiny levels.
- Patient Mobility:Routine repositioning and lateral movement in general medical-surgical units, representing the baseline functional requirement for all transfer device categories.
- Safety Transfer:Engineered protocols eliminating manual lifting injuries through mechanical or powered assistance, the primary compliance driver for OSHA-directed United States hospital procurement.
- Assisting Care:Single-caregiver operation mandates in home care and understaffed long-term care settings where staff-to-patient ratios preclude manual lift teams.
- Emergency Response:Rapid extraction and lateral movement in trauma bays and ambulance loading scenarios requiring validated load capacity under dynamic conditions.
Safety Transfer anchors institutional budgets while Assisting Care gains traction fastest on home care discharge expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals deploy powered air-assisted systems at the highest per-bed density globally, while German acute care facilities favor reusable textile protocols under stricter MDR compliance timelines. Japanese nursing homes lag in capital conversion, retaining manual transfer methods longer than Western counterparts. Indian greenfield hospital construction is absorbing first-generation air-assisted platforms as infrastructure buildouts outpace staff training programs.
United States
OSHA safe patient handling directives and escalating workers compensation premiums are accelerating replacement of manual lift aids in acute care settings. FDA 510(k) clearance pathways dominate regulatory timelines for powered system introductions. Integrated delivery networks in the Midwest and Southeast are consolidating vendor contracts under centralized procurement offices that bundle transfer devices with insurance premium reduction programs.
Germany
Hospital procurement associations are filtering supplier qualification through EU MDR biocompatibility and electrical safety certification requirements. ANSM-aligned infection control protocols in neighboring France are influencing cross-border tender specifications for reusable textile systems. The Ruhr industrial corridor hosts validation testing facilities where adapter development for heterogeneous bed fleet interoperability is concentrated.
Japan
JIS-standard load ratings govern reusable board inventory specifications in long-term care facilities facing severe staff-to-patient ratio constraints. METI industrial policy is subsidizing domestic manufacturing of low-friction fabric substrates to reduce petroleum-derived import dependency. Osaka-based rehabilitation centers are pioneering sling configuration standardization for funded mobility programs under national long-term care insurance.
India
National health expansion programs are subsidizing home care transfer aids for post-surgical recovery as discharge planning extends hospital protocols into residential settings. CDSCO medical device registration requirements are tightening for powered air-assisted systems entering through greenfield hospital construction. Maharashtra and Karnataka state health infrastructure buildouts are creating first-mover positioning for suppliers establishing pneumatic maintenance service networks.
Australia
TGA-registered sling configurations are mandatory for rehabilitation center funding under national disability insurance schemes. Health Canada-registered foam density specifications are influencing cross-reference standards for bariatric pressure redistribution overlays in critical care units. Sydney and Melbourne tertiary hospitals are piloting wireless force sensor integration for real-time compliance documentation in injury prevention protocols.
Global Patient Lateral Transfer Devices Market Competitive Landscape
Capability concentration sits with established hospital bed manufacturers possessing integrated service networks; scale advantage sits with disposable textile specialists optimizing per-unit production economics. The vendor base stratifies across three tiers: capital equipment integrators bundling powered systems with maintenance contracts, single-use disposable fabricators competing on infection control metrics, and regional reusable textile suppliers serving cost-conscious long-term care operators. Dominant competitive moves include strategic partnerships between bed manufacturers and transfer device specialists, plus backward integration into low-friction fabric coating technologies.
Within the capital equipment integrator tier, Stryker and Hill-Rom Holdings, Inc. occupy positions anchored by installed bed fleet relationships that enable bundled servicing contracts. HoverTech International exemplifies the disposable specialization archetype, competing against reusable alternatives on per-procedure infection control economics. Arjo represents European-based system integration, navigating EU MDR compliance timelines that filter marginal competitors from tender processes.
| Leading Market Players |
|---|
| Hill-Rom Holdings, Inc. |
| AliMed |
| Arjo |
| EZ Way Inc. |
| McAuley Medical |
| Stryker |
| HoverTech International |
| Patient Positioning Systems, LLC. |
| Medline Industries, Inc. |
| Others |
Supply & Pricing Matrix
Ruhr industrial corridor validation facilities concentrate adapter development for heterogeneous bed fleet interoperability, concentrating pricing power with certified system integrators who control MDR-compliant manufacturing access. German procurement associations leverage this concentration to consolidate supplier qualification, filtering tender participation toward vendors with captive pneumatic engineering capabilities and established service networks.
Pricing Analysis
Long-term predictive maintenance subscriptions are displacing episodic capital equipment sales as the dominant contract structure, with payment terms tied to uptime guarantees rather than device acquisition. Three-tier pricing structure across premium air-assisted systems, standard reusable textiles, and economy disposable slide sheets differentiates on certification grade and after-sales bundling. Cost compression in disposable polymer substrates is intensifying because petroleum-derived feedstock volatility squeezes margin structures for single-use manufacturers. Long-term care operators exhibit highest price sensitivity, while United States integrated delivery networks prioritize total cost of ownership over per-unit expenditure.
Supply Chain Analysis
Contract manufacturing for low-friction fabric coatings concentrates in German technical textile clusters and Chinese polymer processing zones, with pneumatic system assembly anchored in United States Midwest industrial corridors. Medical-grade silicone and PTFE coatings draw from specialty chemical suppliers in Belgium and Japan, while aluminum structural components source from domestic foundries in India and Germany. Single-source vulnerability in certified biocompatible substrate supply creates exposure to EU MDR testing backlog delays. Distribution runs through hospital GPO contracts in North America and procurement association frameworks in German-speaking Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manual lift protocols face substitution pressure from powered air-assisted systems as OSHA compliance mandates harden injury prevention thresholds, forcing incumbents to defend installed base relationships against engineered transfer technology displacement.
For Market Incumbents: Build switching-cost moats through predictive maintenance contract bundling that embeds field engineering dependencies into hospital procurement workflows. Incumbents should secure backward integration into low-friction fabric coating technologies to control input cost volatility and filter competitor access to certified substrate supply. The threat of disposable specialists capturing infection-control-driven replacement cycles demands channel control through GPO contract consolidation. For New Entrants and Emerging Players: Establish a beachhead in Indian greenfield hospital construction where infrastructure buildouts outpace established service network coverage, creating first-mover positioning before pneumatic maintenance competencies mature locally. Target home care discharge extension segments where lightweight slide pad demand is expanding fastest and incumbent capital equipment relationships hold weakest sway. A go-to-market angle anchored to national health expansion program subsidies bypasses traditional hospital procurement gatekeepers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among powered system integrators with predictive maintenance contract penetration above fifty percent of installed base, signaling durable cash flow quality across the analysis window. Acquisition targets should display EU MDR certification completion and established pneumatic field service networks rather than pure manufacturing scale. The signal to watch is CDSCO registration timeline acceleration for air-assisted platforms entering Indian greenfield facilities as an inflection indicator for geographic demand shift.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance completion filters tender participation in German procurement association frameworks. |
| Hospital System Partnership | Integrated delivery network bundling secures predictive maintenance contract attachment rates above capital equipment sales. |
| Software Companion Development | Wireless force sensor integration enables real-time OSHA compliance documentation for injury prevention protocols. |
| Reimbursement Strategy | Safe patient handling program coding alignment captures bundled payment rewards for measurable caregiver injury reduction. |
| Backward Integration | Captive low-friction fabric coating production insulates margin structures from petroleum-derived substrate volatility. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR vigilance repositories, and hospital GPO contract disclosures preceded structured interviews with biomedical engineering directors, hospital purchasing committee chairs, pneumatic system field service technicians, and safe patient handling program coordinators. Primary intelligence combined with secondary validation against ISO 10535 standard documentation, OSHA injury reporting statistics, and customs trade data for medical-grade polymer substrates. Bottom-up facility-level demand assessment triangulated against top-down procurement spend analysis.
Assumptions held fixed include EU MDR certification timeline completion rates and OSHA safe patient handling directive enforcement intensity, while variables included petroleum feedstock price trajectories and Indian hospital infrastructure buildout acceleration. Segmentation modeling spanned product type, end-user setting, material substrate, and clinical application intensity across the projection horizon. CAGRs derived from installed base replacement cycle analysis and penetration rate modeling for powered versus manual transfer protocols, with bariatric patient volume expansion and nurse injury claim cost inflation as key demand inputs.
Stress conditions across medical-grade polymer input cost bands, EU MDR testing capacity constraints, and Indian pneumatic technician training program scale were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and would require revision upon material shifts in safe patient handling mandate enforcement or greenfield hospital construction subsidy suspension. Quarterly review of CDSCO registration approval velocity and German procurement association tender participation thresholds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Global Joint Replacement Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Patient Lifts Market