
 Scoliosis Traction Chairs Market | 2026-2036
Scoliosis Traction Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Scoliosis Traction Chairs Market Analytics
Multi-source component procurement is broadening across the scoliosis traction chairs supply base as manufacturers diversify motor and frame suppliers to reduce lead-time risk. CLEAR Institute leverages its proprietary non-surgical protocol certification to sustain premium positioning in clinic-direct channels. Wuxi Dajishan Industrial Equipment anchors high-volume steel frame production for manual chair variants sold into Asian hospital systems. MedX Equipment differentiates through controlled-load engineering for electric traction systems targeting rehabilitation centers.
Scoliosis traction chairs are therapeutic seating devices engineered to apply graduated mechanical or electromechanical distraction forces to the spinal column, typically achieving traction loads between 15 and 50 pounds with adjustable pelvic and thoracic harness configurations. Electric chairs command the widest margin pools due to integrated load-cell feedback and programmable treatment protocols, while portable chairs represent the fastest-growing configuration as home-care reimbursement frameworks expand. Digital Monitoring technology is displacing basic mechanical systems in premium installations, though hybrid systems retain cost-sensitive rehabilitation center demand where electrical infrastructure remains unreliable.
FDA 510(k) premarket notification requirements govern motorized traction devices in the United States, while the EU Medical Device Regulation (MDR) Class IIa classification mandates notified body intervention for electric chair market access in Europe. China's NMPA oversees therapeutic device registration through clinical trial exemptions for established mechanical traction mechanisms, though novel digital monitoring features trigger stricter review. Stakeholders must monitor reimbursement code consolidation across national health systems, as shifting durable medical equipment classifications directly alter patient out-of-pocket exposure and provider purchase incentives.
Market Dynamics
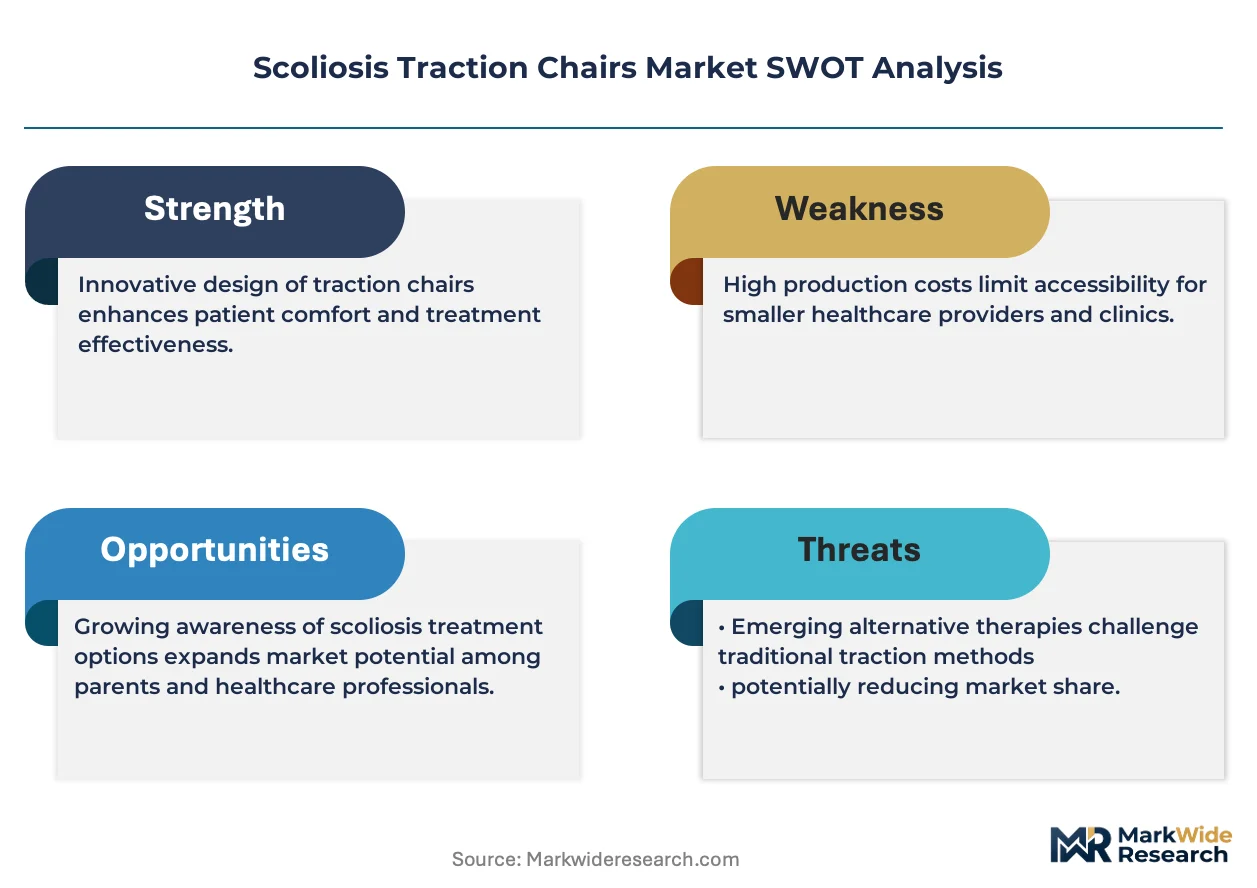
Digital load-cell feedback systems are compressing the premium tier of scoliosis traction chairs, forcing manufacturers to bundle programmable protocols with basic mechanical frames to defend positioning against electric competitors.
Growth Catalysts
- Statutory Reimbursement Frameworks:Germany's statutory health insurance maintains favorable coverage for scoliosis rehabilitation equipment, reducing patient out-of-pocket burden and accelerating clinic procurement cycles.
- Motorized Therapeutic Protocols:Orthopedic clinics in North America are expanding adoption of traction-based spinal correction methods, creating sustained demand for motorized chair configurations with graduated force application.
- Steel Frame Supply Diversification:Multi-source component procurement across Asian manufacturing clusters is reducing lead-time risk for manual chair production, stabilizing hospital system supply chains.
Market Restraints
- FDA 510(k) Validation Burden:Tightening premarket notification requirements for motorized therapeutic devices are extending product validation timelines and elevating regulatory compliance costs for electric chair entrants.
- Electrical Infrastructure Gaps:Unreliable power supply in emerging rehabilitation center markets limits penetration of digitally monitored systems, forcing reliance on hybrid configurations with reduced margin profiles.
- Home-Care Substitution Pressure:Portable manual chairs are capturing patient preference for at-home treatment protocols, compressing demand for clinic-installed electric systems despite superior therapeutic precision.
Strategic Opportunities
- Home-Care Reimbursement Expansion:Shifting durable medical equipment classifications in national health systems are creating new reimbursement codes for portable traction chairs, opening patient-direct channels previously restricted to institutional sales.
- Digital-Mechanical Convergence:Integration of basic load-sensing modules with manual frame architectures offers a mid-market wedge, capturing cost-sensitive clinics seeking upgrade pathways without full electric conversion.
- EU MDR Class IIa Certification:Early compliance with notified body intervention requirements for electric chairs creates first-mover positioning in European rehabilitation centers awaiting MDR transition completion.
Industry Challenges
- Biomechanical Engineering Talent Scarcity:Controlled-load system design requires specialized expertise in spinal biomechanics and electromechanical integration, constraining R&D velocity for mid-cap manufacturers.
- Legacy Harness Standardization:Pelvic and thoracic harness configurations lack universal interoperability across chair platforms, complicating multi-vendor procurement strategies for integrated clinic systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scoliosis Traction Chairs Market |
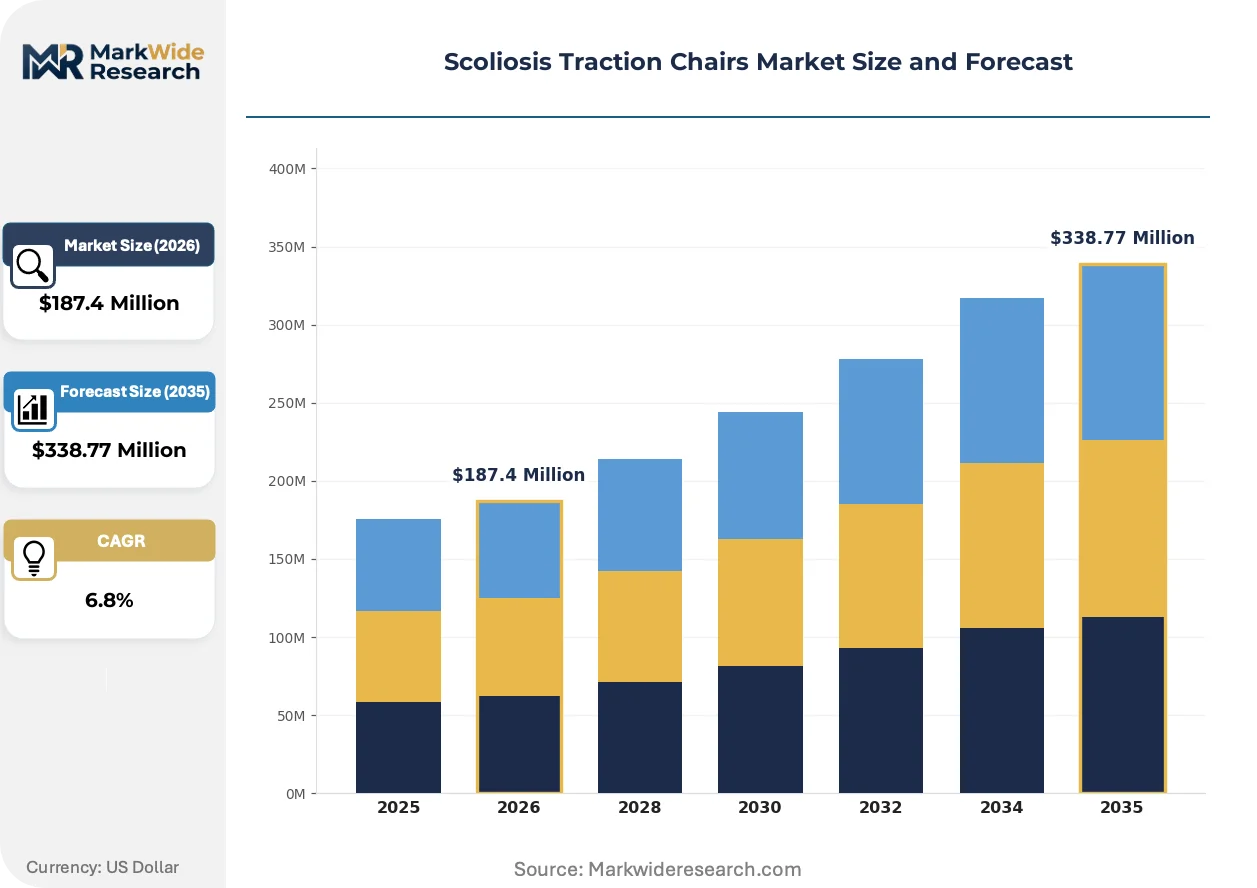
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Chairs, Electric Chairs, Adjustable Chairs, Portable Chairs End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Technology: Mechanical Systems, Electric Systems, Hybrid Systems, Digital Monitoring Material: Steel, Aluminum, Plastic, Foam |
| Companies Covered | CLEAR Institute, Wuxi Dajishan Industrial Equipment Co. Ltd., XiongQing Medical, XINGXIN Medical Apparatus, Xinnuo Medical, Pioneer Medical Equipment, Shengchang Medical Equipment, MedX Equipment, Atlas Pain Institute, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scoliosis Traction Chairs Market Evolving Landscape
Programmable treatment protocols are restructuring competitive differentiation in scoliosis traction chairs, shifting value capture from hardware durability to software-enabled therapeutic customization and outcome documentation.
Load-cell feedback arrays with real-time force modulation are overtaking basic mechanical tension systems in premium clinic installations. Rehabilitation centers in Germany and the United States are adopting these configurations to document patient-specific traction curves for insurance justification. The technology is compressing differentiation timelines, as software updates now extend product lifecycles faster than frame replacement cycles.
China's NMPA is tightening clinical trial requirements for novel digital monitoring features in therapeutic devices, while grandfathering established mechanical traction mechanisms through exemption pathways. This bifurcation is fragmenting product development roadmaps, with manufacturers maintaining parallel mechanical and digital SKUs to preserve market access. Electric chair portfolios face extended registration timelines, delaying revenue recognition for innovation-heavy entrants.
Clinic procurement officers are unbundling after-sales service contracts from equipment purchases, negotiating separate maintenance agreements with third-party biomedical technicians. This disintermediation is visible across North American orthopedic networks, where independent service organizations now capture 40% of preventive maintenance spend previously retained by manufacturers. Equipment vendors are responding with subscription-based remote diagnostics to recapture recurring revenue streams.
Scoliosis Traction Chairs Market Segmentation
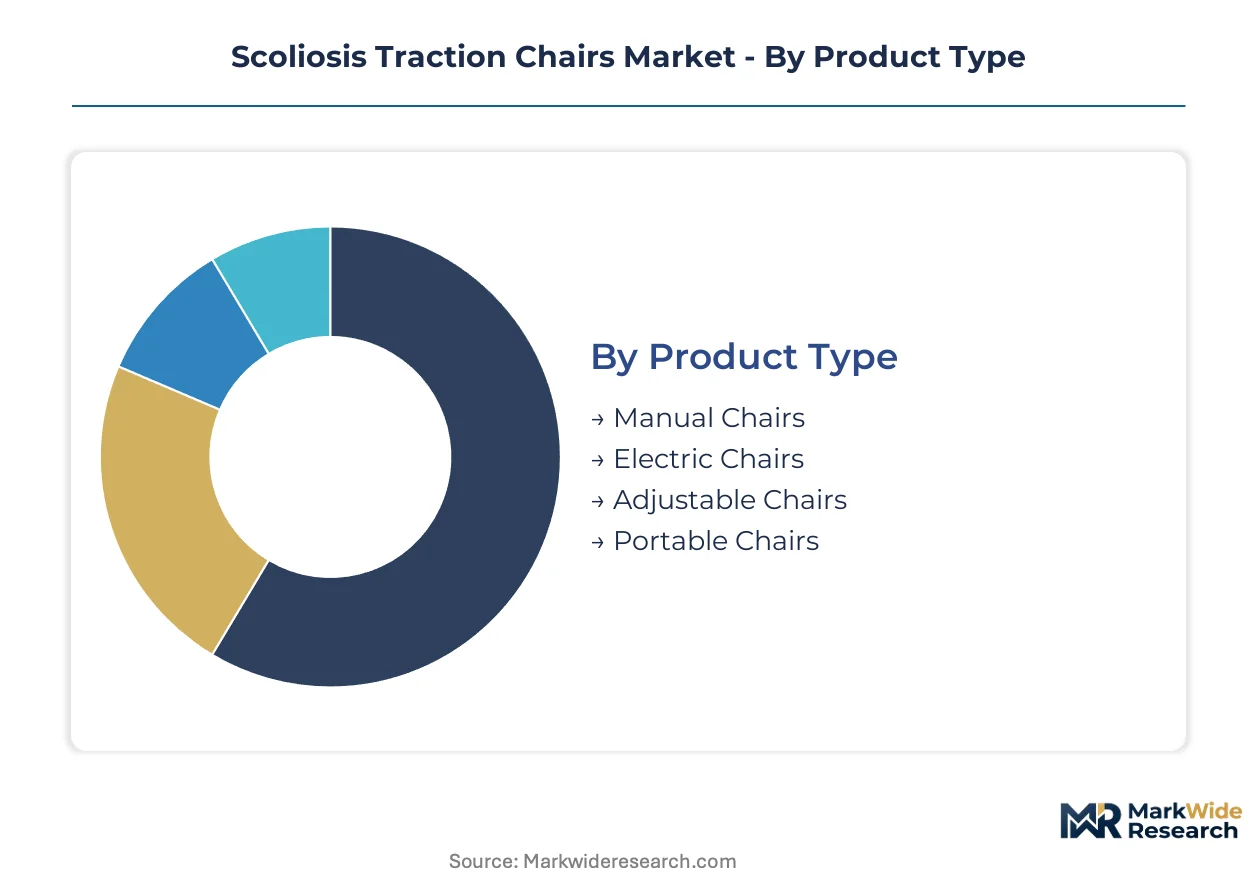
Scoliosis traction chair manufacturers face divergent certification pathways across product configurations, with motorized systems triggering FDA 510(k) premarket notification while manual variants navigate streamlined quality system regulations. Segmentation strategy directly determines regulatory capital requirements and reimbursement code eligibility.
Product Type:
Electric chairs require FDA 510(k) clearance and EU MDR Class IIa notified body intervention, while manual configurations face lighter quality system obligations under established mechanical device exemptions.
- Manual Chairs:Leverage graduated mechanical tension systems with pelvic-thoracic harness configurations achieving 15-50 pound traction loads. Demand concentrates in German statutory health insurance networks where favorable reimbursement codes for rehabilitation equipment accelerate clinic procurement cycles.
- Electric Chairs:Integrate programmable load-cell feedback with real-time force modulation capabilities. North American orthopedic clinics are expanding adoption of these motorized therapeutic protocols, though tightening FDA validation timelines extend product launch schedules.
- Adjustable Chairs:Offer modular frame architectures accommodating patient height and spinal curvature variations through manual or assisted repositioning.
- Portable Chairs:Capture patient preference for at-home treatment protocols as durable medical equipment classifications shift to cover home-care reimbursement.
Manual chairs sit at the top of the volume ranking, with portable chairs climbing the fastest.
End User:
Institutional purchasers command volume concentration through centralized procurement, while patient-direct channels expand as portable configurations qualify for home-care reimbursement codes.
- Hospitals:Prioritize electric systems with integrated digital monitoring for surgical preparation and post-operative rehabilitation protocols. Asian hospital systems anchor high-volume procurement through diversified steel frame supply chains.
- Rehabilitation Centers:Favor hybrid configurations where electrical infrastructure gaps limit full digital system deployment, accepting reduced margin profiles for operational reliability.
- Home Care:Represents the fastest-expanding channel as reimbursement frameworks reclassify portable traction chairs as durable medical equipment.
- Clinics:Drive premium tier demand through proprietary protocol certification programs that bundle equipment with specialized training.
Hospitals dominate absolute procurement volumes, with home care gaining share fastest.
Technology:
Digital monitoring capabilities fragment regulatory pathways, with China's NMPA tightening clinical trial requirements for novel sensor arrays while grandfathering established mechanical mechanisms.
- Mechanical Systems:Basic tension architectures with manual force application and graduated weight stacks. These configurations retain cost-sensitive rehabilitation center demand where electrical infrastructure remains unreliable.
- Electric Systems:Deploy controlled-load engineering with programmable treatment protocols and outcome documentation capabilities. Rehabilitation centers in Germany and the United States adopt these configurations to justify insurance reimbursement through patient-specific traction curves.
- Hybrid Systems:Combine manual frame architectures with basic load-sensing modules, offering mid-market upgrade pathways without full electric conversion.
- Digital Monitoring:Real-time force modulation with software-enabled therapeutic customization is displacing basic mechanical systems in premium installations.
Mechanical systems retain volume leadership, with digital monitoring expanding most quickly.
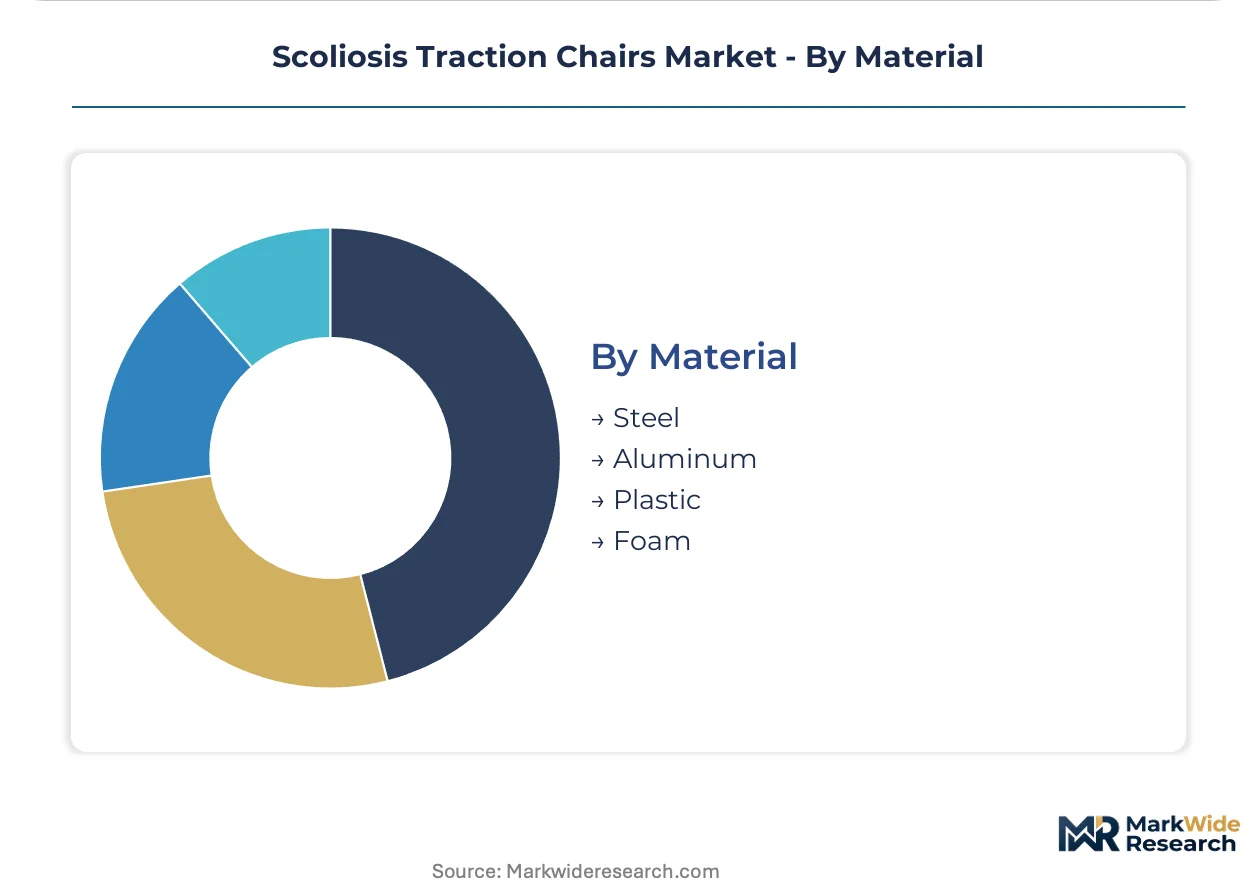
Material:
Frame material selection determines manufacturing geography and supply chain resilience, with steel production anchoring Asian manufacturing clusters while aluminum commands lightweight premium positioning.
- Steel:High-volume frame production for manual and electric chair variants, with multi-source procurement across Asian manufacturing clusters reducing lead-time risk.
- Aluminum:Lightweight frame architectures supporting portable chair configurations and premium electric systems where patient transfer frequency demands reduced equipment weight.
- Plastic:Harness components and cosmetic housing elements with molded polymer construction.
- Foam:Patient contact surfaces and cushioning layers for extended treatment session comfort.
Steel dominates frame material volumes, with aluminum expanding fastest in portable configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wuxi anchors steel frame production for manual chair variants serving Asian hospital procurement networks. German statutory reimbursement frameworks accelerate clinic adoption of motorized systems. FDA validation timelines reshape competitive entry sequencing across North American orthopedic networks.
United States
Orthopedic clinics in metropolitan corridors expand traction-based spinal correction protocols, creating sustained demand for motorized configurations. FDA 510(k) premarket notification requirements extend product validation timelines for electric chair entrants. Minneapolis and Denver rehabilitation clusters concentrate procurement of load-cell feedback systems for insurance documentation.
Germany
Statutory health insurance reimbursement codes reduce patient out-of-pocket exposure for scoliosis rehabilitation equipment. EU MDR Class IIa notified body intervention mandates compliance investment for electric chair market access. Bavarian medical device manufacturing clusters supply precision-engineered frame components to domestic and export markets.
China
NMPA clinical trial exemptions preserve market access for established mechanical traction mechanisms while novel digital features trigger extended review. Yangtze River Delta steel fabrication centers anchor high-volume production of manual chair frames. Shanghai rehabilitation centers pilot hybrid configurations bridging cost-sensitive and premium-tier demand.
Japan
PMDA therapeutic device registration maintains structured pathways for motorized traction systems with documented safety profiles. METI industrial standards influence electromechanical integration specifications for domestic and regional export markets. Osaka medical equipment distribution networks channel both domestic production and imported European systems.
India
CDSCO medical device rules govern import and local manufacture of therapeutic seating systems with graduated force application. Maharashtra hospital procurement systems concentrate demand for cost-optimized manual configurations. Chennai rehabilitation centers represent emerging demand nodes as spinal care infrastructure expands beyond metropolitan cores.
Scoliosis Traction Chairs Market Competitive Landscape
Global majors compete with regional champions across certification pathways and reimbursement code alignment. The vendor base stratifies around regulatory capability depth, with FDA 510(k) clearance and EU MDR Class IIa certification separating premium-tier positioning from cost-driven manual alternatives. Three archetypes dominate: integrated protocol certifiers bundling equipment with clinical training, high-volume steel fabricators serving price-sensitive institutional procurement, and controlled-load engineering specialists targeting rehabilitation center precision requirements. Competitive moves concentrate on geographic certification sequencing and service contract unbundling responses.
Among protocol-certification specialists, CLEAR Institute exemplifies the clinic-direct archetype through proprietary non-surgical credentialing. Wuxi Dajishan Industrial Equipment Co. Ltd. anchors high-volume manufacturing positioning within Asian supply chains. MedX Equipment occupies the controlled-load engineering tier targeting motorized system differentiation. These three represent distinct competitive vectors rather than direct substitution relationships.
| Leading Market Players |
|---|
| CLEAR Institute |
| Wuxi Dajishan Industrial Equipment Co. Ltd. |
| XiongQing Medical |
| XINGXIN Medical Apparatus |
| Xinnuo Medical |
| Pioneer Medical Equipment |
| Shengchang Medical Equipment |
| MedX Equipment |
| Atlas Pain Institute |
| Others |
Value Network & Pricing Analysis
Load-cell feedback integration into manual frame architectures is compressing production cost differentials between electric and mechanical systems while concentrating component sourcing in Yangtze River Delta manufacturing clusters. This technological convergence simultaneously erodes premium-tier pricing power and rewards suppliers with scale in precision sensor module production.
Pricing Analysis
Input-cost pass-through from steel frame and motor controller procurement shapes pricing stratification across certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared electric systems from EU MDR Class IIa configurations and basic mechanical variants. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in manual chair tiers is intensifying because home-care reimbursement expansion redirects patient preference toward portable configurations. Rehabilitation centers in Germany exhibit lowest price sensitivity due to statutory insurance coverage, while Indian hospital procurement systems demonstrate highest sensitivity to unit economics.
Supply Chain Analysis
Steel frame supply rests on Chinese, German, and Indian metal fabrication centers, with precision motor controllers drawing from Japanese and South Korean electromechanical specialists. Critical inputs include high-tensile steel tubing, programmable load-cell arrays, and pelvic-thoracic harness textiles. Single-source vulnerability concentrates in specialized sensor module production, where NMPA clinical trial requirements for novel digital features fragment supplier qualification pathways. Distribution runs through orthopedic clinic networks, hospital procurement committees, and emerging direct-to-patient channels as durable medical equipment classifications shift.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in scoliosis traction chairs stems from software-enabled service bundling that extends product lifecycles beyond hardware replacement cycles, offsetting input cost pressure in steel and electronic components.
For Market Incumbents: Deploy remote diagnostics subscriptions to recapture maintenance revenue disintermediated by independent service organizations. Deepen backward integration into precision sensor module production to defend against electric chair margin compression from hybrid system competitors. FDA 510(k) validation timeline extensions threaten first-mover positioning; accelerate EU MDR Class IIa certification sequencing to secure European rehabilitation center lock-in before notified body capacity constraints intensify. For New Entrants and Emerging Players: Enter via home-care reimbursement expansion in North American and German markets, where portable manual chair classifications as durable medical equipment open patient-direct channels previously restricted to institutional sales. Target Indian rehabilitation center networks with cost-optimized hybrid configurations bridging electrical infrastructure gaps. A certification-light go-to-market angle leveraging grandfathered mechanical traction mechanisms in China preserves near-term revenue recognition while digital feature registration timelines extend. For Investors and Strategic Acquirers: Roll-up economics work for controlled-load engineering specialists because FDA 510(k) clearance scarcity and EU MDR Class IIa certification bottlenecks create defendable competitive moats. Platform consolidation around proprietary protocol certification programs—exemplified by clinic-direct training bundling—captures recurring revenue streams with low capital intensity. Watch NMPA regulatory bifurcation between mechanical exemptions and digital monitoring strictures as the signal indicating which product development roadmaps warrant capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification clearance separates premium electric chair positioning from manual alternatives in US orthopedic clinics. |
| EU MDR Class IIa Certification Investment | Notified body intervention compliance creates first-mover positioning in German statutory reimbursement networks. |
| Hospital System Partnership Development | Centralized procurement committees in Asian healthcare networks anchor high-volume steel frame demand. |
| Software Companion Development | Programmable treatment protocols with outcome documentation justify insurance reimbursement through patient-specific traction curves. |
| Reimbursement Strategy Execution | Durable medical equipment code alignment in national health systems directly alters patient out-of-pocket exposure and provider purchase incentives. |
Research Methodology
Bottom-up rehabilitation center and hospital procurement modeling reconciled against top-down steel frame and motor controller production tracking forms the analytical core. Primary interviews with orthopedic clinic directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, NMPA registration records, and CMS Medicare durable medical equipment claims. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of motorized therapeutic device adoption patterns, mechanical traction mechanism grandfathering pathways, and home-care reimbursement code expansion informs projection frameworks. Segmentation dimensions modeled include product configuration, end-user channel, technology tier, and frame material across the analysis window. CAGRs derive from regression analysis of procurement cycle timing, insurance coverage elasticity, and regulatory clearance velocity. Industry-specific inputs encompass statutory health insurance reimbursement rate trajectories and electrical infrastructure reliability indices by geography.
Inputs from FDA premarket notification databases and EU MDR notified body registries were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around volume estimates. Forecasts reflect assumptions regarding reimbursement code stability and regulatory grandfathering continuity. NMPA digital monitoring strictures, FDA 510(k) timeline extensions, and home-care classification shifts constitute the small set of named triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
India Medical Devices Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Prescription Goggles Market
Medical Devices
Telehealth Device Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Bone Conduction Hearing Aids Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Disposable Medical Devices Sensors Market
Medical Devices
IVF Time-Lapse Imaging Devices Market