
 Orthopedic Drill Bits Market | 2026-2036
Orthopedic Drill Bits Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Drill Bits Market Insights
German instrument manufacturing clusters is decoupling from legacy stainless steel supply chains as carbide and titanium sourcing diversifies across Central European forges. Stryker Corporation leverages captive production of modular drill systems to sustain margin control across trauma and joint reconstruction lines. Zimmer Biomet Holdings Inc. anchors its position through deep specialization in hip and knee surgery consumables. DePuy Synthes competes on scale, operating one of the broadest orthopedic power tool portfolios in North American hospitals.
Orthopedic drill bits are precision cutting instruments engineered from titanium alloys, stainless steel, cobalt chromium, or tungsten carbide with flute geometries optimized for bone tissue removal and thermal damage minimization during skeletal fixation procedures. Cannulated drill bits command premium positioning due to their compatibility with guidewire-based minimally invasive techniques, while standard drill bits occupy the high-volume, price-sensitive segment across emerging hospital systems. Trauma surgery applications generate the most recurrent demand given the procedural volume of fracture fixation, whereas hip surgery and knee surgery lines concentrate margin pools in revision and robotic-assisted cases.
FDA 510(k) premarket notification requirements and EU MDR technical documentation obligations shape sterilization validation, biocompatibility testing, and post-market surveillance burdens for manufacturers seeking dual-market access. ISO 13485 quality management standards and ASTM F1377 surgical alloy specifications further constrain material selection and supply chain qualification protocols. Stakeholders must monitor how FDA digital health pre-certification pilots and EU CSRD sustainability disclosure rules will extend compliance costs into component sourcing and end-of-life instrument recovery programs.
Market Dynamics
EU MDR conformity assessments and FDA 510(k) clearance pathways are compressing product development cycles while forcing sterilization validation investments that reshape competitive economics across the orthopedic power tool supply base.
Growth Catalysts
- EU MDR Technical Documentation:Stricter biocompatibility testing mandates under the Medical Device Regulation are accelerating hospital procurement of validated single-use drill bit systems to reduce sterilization liability exposure.
- Ambulatory Surgical Center Expansion:United States outpatient facility construction is driving demand for compact, battery-powered drill systems with disposable bit attachments optimized for same-day discharge protocols.
- Tungsten Carbide Material Substitution:German and Austrian forges are expanding output of carbide-tipped flutes that extend cutting life in high-volume trauma applications, displacing legacy stainless steel in premium instrument tiers.
Market Restraints
- Cobalt Chromium Supply Concentration:Russian and Central African ore processing bottlenecks are creating input cost volatility for superalloy drill bit substrates used in revision joint surgery.
- EU MDR Notified Body Capacity:Limited conformity assessment organization bandwidth is extending certification timelines for new drill bit geometries, delaying product launches by 12-18 months.
- Reusable System Depreciation:Hospital capital budgeting constraints in Japan are prolonging replacement cycles for modular drill handpieces, compressing aftermarket bit attachment demand.
Strategic Opportunities
- Robotic-Assisted Surgery Integration:Convergence of optical navigation with torque-controlled drilling is creating demand for instrumented bits compatible with Stryker Mako and Zimmer ROSA platforms in United States academic medical centers.
- India PLI Medical Device Scheme:Production-linked incentive structures are attracting contract manufacturers to establish carbide finishing operations for export-oriented orthopedic instrument production.
- CSRD Sustainability Disclosure:EU corporate sustainability reporting requirements are creating procurement preference for drill bit suppliers with documented end-of-life instrument recovery and remelting programs.
Industry Challenges
- ISO 13485 Auditor Shortage:Qualified quality management system assessors are concentrated in Germany and Switzerland, creating certification backlogs for emerging market manufacturers seeking European market access.
- Legacy Steam Sterilization Infrastructure:United States community hospitals face capital constraints in converting from gravity-displacement to pre-vacuum autoclaves required for validated reprocessing of complex cannulated bit geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Drill Bits Market |
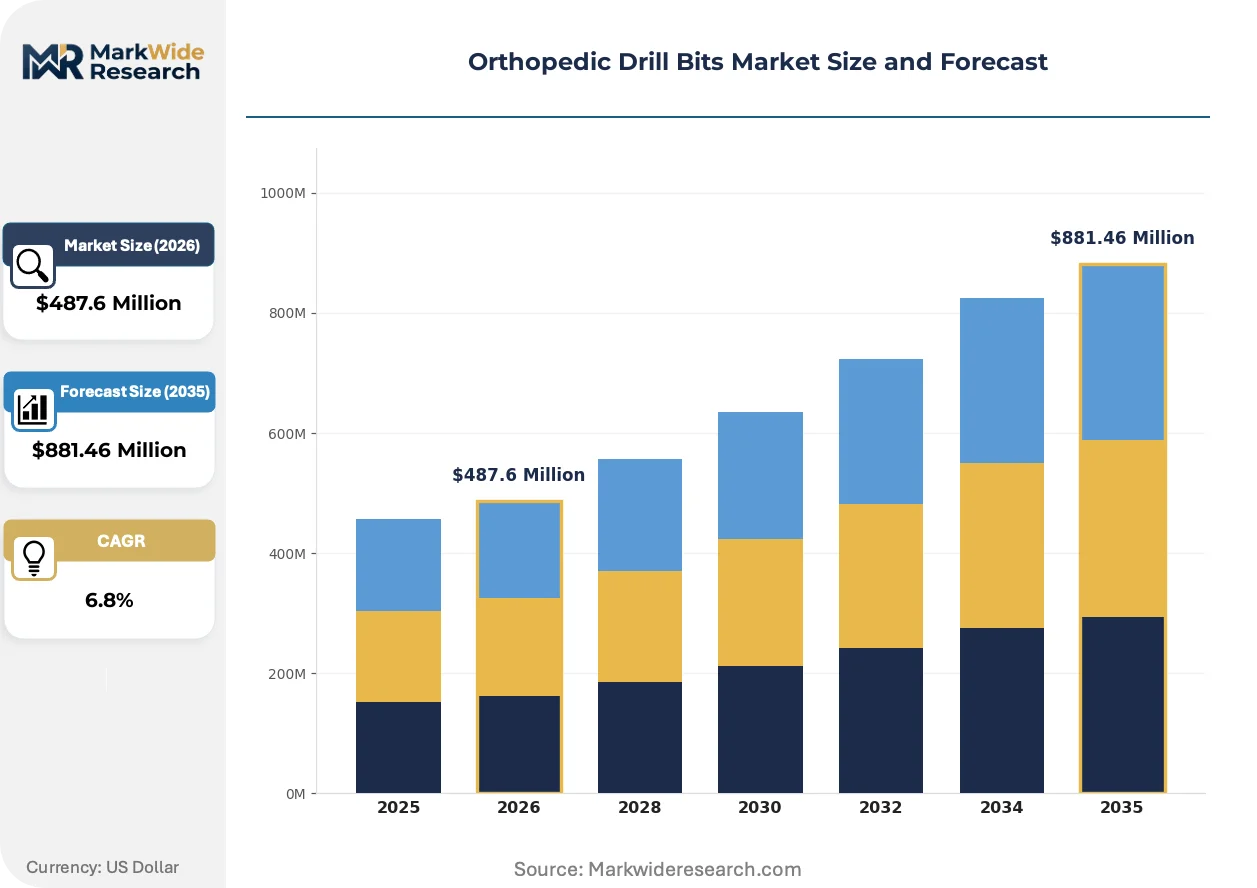
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Drill Bits, Cannulated Drill Bits, Reamer Bits, Modular Drill Bits Material: Titanium, Stainless Steel, Cobalt Chromium, Carbide Application: Hip Surgery, Knee Surgery, Shoulder Surgery, Trauma Surgery End User: Hospitals, Surgical Centers, Orthopedic Clinics, Academic Institutions |
| Companies Covered | Stryker Corporation, Zimmer Biomet Holdings Inc., DePuy Synthes, Medtronic plc, CONMED Corporation, Arthrex Inc., B. Braun Melsungen AG, Smith & Nephew plc, Integra LifeSciences Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Drill Bits Market Trends and Innovations
Orthopedic drill bit evolution is pivoting from incremental flute geometry refinement toward integrated sensing, materials science advances, and procurement model restructuring that redefines value capture across the surgical instrument value chain.
Additive manufacturing of patient-specific drill guides is integrating with standard bit platforms to enable trajectory-locked osteotomy procedures in complex pelvic reconstruction cases. United States Level I trauma centers are piloting these hybrid systems for acetabular fracture fixation, compressing operative time and fluoroscopy exposure while requiring instrument suppliers to validate bit-guide interface tolerances under accelerated wear protocols.
EU MDR post-market surveillance requirements are mandating systematic implantable device registration that extends to drill bits used in cannulated screw placement, creating traceability infrastructure obligations. Manufacturers serving European hospitals must now deploy unique device identification labeling and centralized vigilance reporting systems, with trauma surgery lines experiencing the heaviest documentation burden due to high procedural volumes and kit complexity.
Japanese hospital groups are consolidating orthopedic procurement through centralized purchasing organizations that unbundle power tool capital sales from consumable bit attachments. This model displaces traditional distributor relationships in Tokyo and Osaka metropolitan markets, forcing manufacturers to establish direct service capabilities and transparent lifecycle cost analytics to secure multi-year supply contracts.
Orthopedic Drill Bits Market Segmentation
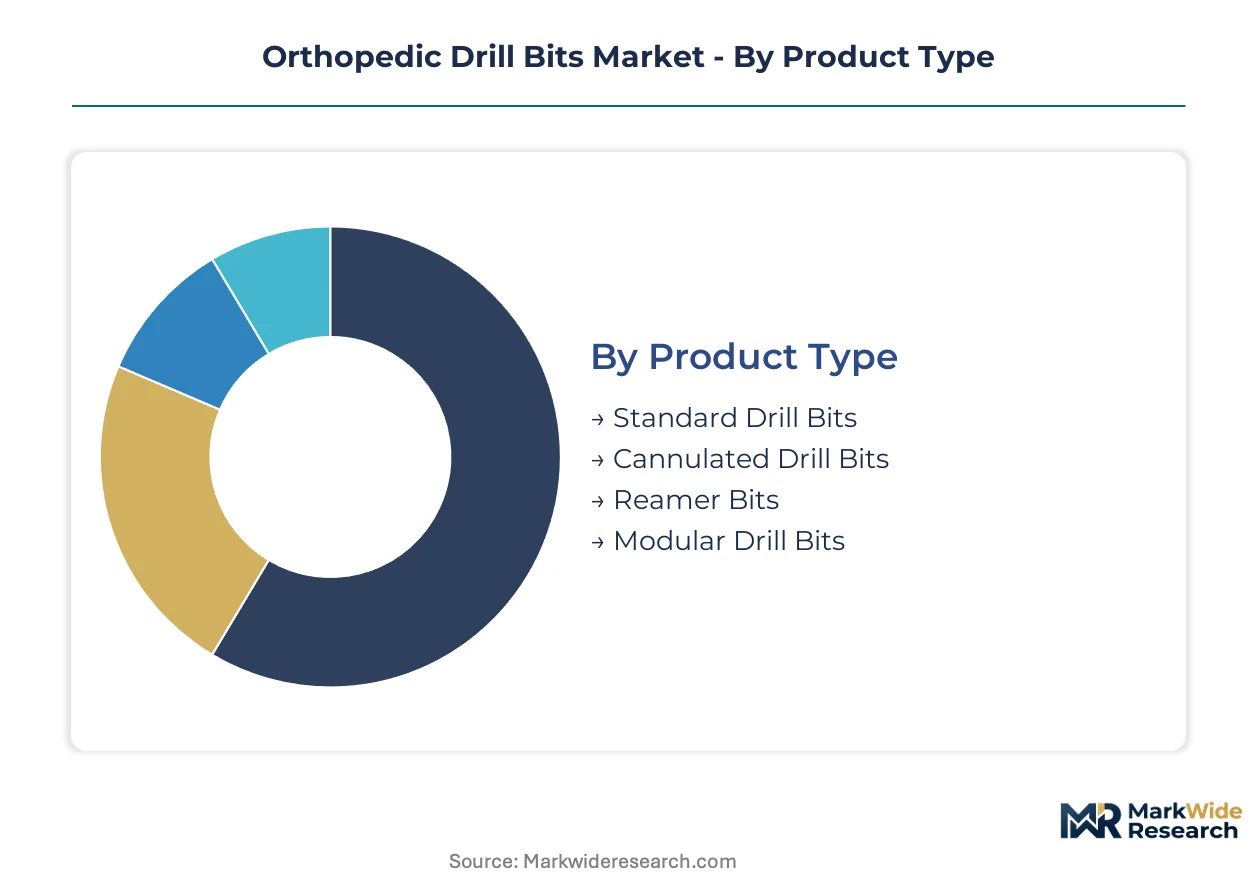
Orthopedic drill bit procurement splits across technical specifications, material grades, and care delivery settings. Each axis carries distinct margin profiles and regulatory burdens that reshape supplier strategies.
Product Type:
Flute geometry and lumen architecture define clinical utility and sterilization complexity across surgical workflows.
- Cannulated Drill Bits:Hollow-core construction enables guidewire passage for minimally invasive trajectory control. United States ambulatory surgical centers are expanding procurement of single-use cannulated systems to eliminate reprocessing validation overhead.
- Standard Drill Bits:Solid-flute designs dominate high-volume trauma fixation in emerging hospital systems. German trauma centers are retaining reusable standard bit inventories despite EU MDR documentation burdens.
- Reamer Bits:Aggressive flute profiles for intramedullary canal preparation in long-bone fracture repair.
- Modular Drill Bits:Quick-coupling interfaces compatible with multi-manufacturer handpiece ecosystems.
Mature deployment sits with Standard Drill Bits. Newer deployment is concentrated in Cannulated Drill Bits.
Material:
Alloy selection trades cutting longevity against biocompatibility certification costs and supply chain exposure.
- Carbide:Tungsten carbide tipping extends flute sharpness retention through high-volume caseloads. Austrian forges are expanding output for trauma drill bit contracts displacing legacy stainless steel.
- Titanium:Grade 5 Ti-6Al-4V substrates offer strength-to-weight optimization for battery-powered handpieces. Japanese orthopedic clinics are prioritizing titanium bits for revision joint procedures requiring reduced operator fatigue.
- Stainless Steel:440C and 17-4 PH grades remain the cost baseline for price-sensitive procurement.
- Cobalt Chromium:Superalloy substrates for high-torque applications in dense cortical bone.
Stainless Steel commands the widest installed base. Carbide is climbing the fastest as trauma centers prioritize cutting efficiency.
Application:
Procedural volume and reimbursement intensity create divergent demand profiles across anatomical targets.
- Trauma Surgery:Fracture fixation generates recurrent consumable demand through unpredictable case flow. United States Level I trauma centers maintain deep bit inventories across all material grades.
- Hip Surgery:Acetabular reaming and femoral canal preparation concentrate premium bit consumption. Academic medical centers in Germany are integrating instrumented bits with robotic navigation platforms.
- Knee Surgery:Tibial and femoral cutting guide compatibility shapes bit procurement specifications.
- Shoulder Surgery:Smaller diameter requirements and arthroscopic access constraints drive specialized geometries.
Trauma Surgery sustains the highest volume throughput. Hip Surgery is gaining share fastest on robotic-assisted case expansion.
End User:
Capital intensity and sterilization infrastructure determine reusable versus disposable system preferences.
- Hospitals:Tertiary centers with captive sterilization departments amortize modular drill system investments across high caseloads. EU MDR technical documentation is accelerating single-use bit adoption in French and Italian hospital systems.
- Surgical Centers:Outpatient facilities prioritize compact battery-powered systems with disposable attachments. United States ambulatory construction is driving demand for pre-sterilized bit kits.
- Orthopedic Clinics:Limited procedure volumes favor rental and consignment inventory models.
- Academic Institutions:Training programs require bit platforms compatible with multiple handpiece generations.
Hospitals retain the deepest reusable system investments. Surgical Centers represent the steepest expansion trajectory for single-use configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten carbide feedstock from Austrian forges and cobalt chromium ore processing in Russian and Central African localities anchor geographic supply patterns for orthopedic drill bit manufacturing. Hospital procurement intensity and regulatory validation requirements diverge sharply across major consuming markets.
United States
Ambulatory surgical center construction in Texas and Florida is accelerating demand for battery-powered drill systems with disposable bit attachments. FDA 510(k) premarket notification pathways shape sterilization validation protocols for reusable cannulated geometries. Level I trauma centers in Chicago and Baltimore maintain deep inventories across all material grades for unpredictable fracture fixation caseloads.
Germany
Academic medical centers in Berlin and Munich are integrating instrumented drill bits with robotic navigation platforms for hip and knee reconstruction. EU MDR technical documentation obligations extend certification timelines and accelerate single-use system adoption in hospital procurement. The Stuttgart and Tuttlingen instrument manufacturing clusters are diversifying carbide and titanium sourcing across Central European forges.
Japan
Orthopedic clinics in Tokyo and Osaka are prioritizing titanium drill bits for revision joint procedures requiring reduced operator fatigue. METI industrial policy supports domestic production of precision surgical instruments. Hospital capital budgeting constraints are prolonging replacement cycles for modular drill handpieces in Kansai metropolitan markets.
India
Production-linked incentive structures under the PLI Medical Device Scheme are attracting contract manufacturers to establish carbide finishing operations in Gujarat and Maharashtra. CDSCO medical device regulations are harmonizing with international standards for export-oriented production. Chennai and Bengaluru clusters are scaling precision machining capacity for trauma drill bit contracts.
United Kingdom
NHS procurement consolidation is shifting orthopedic instrument purchasing toward framework agreements with transparent lifecycle cost analytics. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards. The Cambridge and Oxford medical technology corridors are piloting additive manufacturing integration for patient-specific drill guide systems.
Orthopedic Drill Bits Market Competitive Landscape
Global majors compete with regional champions across sterilization validation capabilities and modular system compatibility. The vendor base clusters around three tiers: integrated orthopedic power tool houses with captive drill bit production, specialized instrument manufacturers supplying multi-brand handpiece ecosystems, and contract manufacturers serving private-label hospital procurement. Strategic moves concentrate on M&A for sterilization validation assets and capacity expansion in carbide-tipped flute finishing.
Among integrated orthopedic power tool houses, Stryker Corporation and Zimmer Biomet Holdings Inc. occupy positions that exemplify the premium-tier archetype through modular system control. DePuy Synthes represents the scale-driven end with broad portfolio coverage across North American hospital systems. These three companies anchor competitive dynamics in trauma and joint reconstruction lines where sterilization liability and surgeon preference lock-in determine procurement outcomes.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet Holdings Inc. |
| DePuy Synthes |
| Medtronic plc |
| CONMED Corporation |
| Arthrex Inc. |
| B. Braun Melsungen AG |
| Smith & Nephew plc |
| Integra LifeSciences Holdings Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between EU MDR-validated single-use systems and legacy reusable inventories manifests in both pricing power concentration and supply chain reconfiguration across Austrian carbide forges and German sterilization validation facilities. This bifurcation rewards suppliers with notified body relationships while compressing margins for stainless steel commodity producers serving price-sensitive hospital procurement in emerging markets.
Pricing Analysis
Warranty and service-bundling unbundling is accelerating as United States ambulatory surgical centers demand pure-transactional disposable bit procurement without reprocessing validation support. Contract-based long-term offtake dominates hospital procurement, with price differentiation driven by ISO 13485 certification tier and after-sales sterilization liability coverage. Pricing pressure stems from cobalt chromium ore volatility filtering into superalloy substrate costs. Surgical centers exhibit highest price sensitivity; academic medical centers with robotic surgery programs show least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stryker and Zimmer Biomet while specialized distributors serve mid-tier hospital networks. Geographic supply concentration centers on Austria for tungsten carbide finishing, Germany for precision instrument assembly, and Japan for titanium substrate processing. Raw material dependencies include Central African cobalt ore, Russian chromium feedstock, and Chinese rare earth processing. Single-source vulnerability in EU MDR notified body capacity creates certification bottlenecks. Distribution runs through GPO contracts in United States hospital systems and centralized purchasing organizations in Japanese metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU MDR compliance costs and sterilization validation investments force sub-scale instrument manufacturers toward exit or acquisition, concentrating viable competitors around integrated power tool houses with captive regulatory affairs capabilities.
For Market Incumbents: Acquire sterilization validation assets and notified body relationship portfolios to defend against emerging contract manufacturers from Indian PLI clusters. Build backward integration into Austrian carbide finishing to secure flute sharpness retention advantages. Channel control through direct service capabilities in Japanese CPO markets anchors multi-year supply contract renewal rates. For New Entrants and Emerging Players: The premium-to-economy price-point gap in cannulated drill bits creates entry space for CDSCO-certified contract manufacturers serving United States private-label hospital procurement. Target United States ambulatory surgical center construction in Texas and Florida with pre-sterilized bit kit offerings. Go-to-market leverage rests on transparent lifecycle cost analytics unbundled from capital equipment sales. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated orthopedic power tool houses seeking EU MDR technical documentation capabilities. Five-to-ten year viability favors targets with established carbide-tipped flute finishing and dual-market FDA-EU regulatory access. Watch FDA digital health pre-certification pilot expansion as inflection signal for instrumented bit platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates single-use system adoption in French and Italian hospital procurement frameworks. |
| Carbide Finishing Capacity Expansion | Austrian forges displace legacy stainless steel in trauma center premium instrument tiers. |
| Robotic Navigation Platform Integration | Instrumented bit compatibility with Stryker Mako drives academic medical center preference lock-in. |
| Centralized Purchasing Organization Direct Service | Tokyo and Osaka metropolitan contracts require transparent lifecycle cost analytics capabilities. |
| End-of-Life Instrument Recovery Program | CSRD sustainability disclosure rules create procurement preference for documented remelting operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this orthopedic drill bit market assessment. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and orthopedic trauma surgeons combined with FDA 510(k) databases, EU MDR notified body registers, and ASTM surgical alloy specifications. Bottom-up trauma procedure volume modeling and top-down instrument consumption estimates were triangulated against Austrian carbide forge output data and Japanese METI production statistics.
Granularity-level modeling proceeded at the product-type, material-grade, and end-user facility tier across the projection horizon. Segmentation dimensions included cannulated versus standard flute geometry, carbide-tipped versus stainless steel substrate, and ambulatory surgical center versus tertiary hospital procurement channel. CAGRs were derived from orthopedic procedure volume elasticities and instrument replacement cycle analysis. Forecast inputs incorporated EU MDR certification timeline delays and United States outpatient facility construction permits.
Inputs from notified body capacity registries and cobalt ore processing facility reports were available through the study window; gaps in Central African supply chain transparency introduce uncertainty bands around superalloy substrate cost assumptions. Forecasts reflect documented elasticity relationships between trauma surgery volumes and consumable bit attachment demand. Periodic stress-testing of base assumptions against FDA digital health pre-certification pilot outcomes and EU CSRD enforcement patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Vertebroplasty Needles Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Global Orthopedic Implant Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
Global Spinal Fusion Devices Market