
 Kyphoscoliosis Treatment Market | 2026-2036
Kyphoscoliosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Kyphoscoliosis Treatment Market Foresight
Patient-specific 3D-printed spinal implants is tilting surgical workflows toward personalized correction strategies. Medtronic leverages its integrated robotics and navigation platforms to sustain leadership in complex deformity correction. Stryker anchors its position through specialized hardware portfolios for adolescent idiopathic scoliosis. Globus Medical differentiates via advanced materials research in porous titanium constructs for spinal fusion.
Kyphoscoliosis treatment encompasses clinical interventions addressing abnormal spinal curvature combining kyphosis and scoliosis deformities, typically involving Cobb angle measurements exceeding 10 degrees in the coronal plane with associated sagittal imbalance. Surgical correction employs titanium alloy pedicle screws, cobalt-chrome rods, and interbody cages achieving 60-80% deformity correction while preserving neurological function. Surgery commands the dominant margin pool due to implant premium pricing and procedural complexity, while bracing retains volume leadership in adolescent populations with moderate curvature progression. Physical therapy represents the fastest-expanding conservative modality as reimbursement frameworks broaden for pre- and post-operative rehabilitation protocols.
FDA premarket notification pathways and ISO 13485 quality management standards govern implant commercialization, with FDA breakthrough device designations compressing review timelines for patient-matched constructs. The EU Medical Device Regulation enforces enhanced clinical evidence requirements for spinal implant conformity, reshaping market access costs for European manufacturers. Stakeholders must monitor evolving CMS coverage determinations for robotic-assisted procedures and decentralized physical therapy delivery models.
Market Dynamics
Patient-specific 3D-printed spinal implants are compressing surgical planning cycles from weeks to days, forcing traditional implant manufacturers to reconfigure their supply chains around digital manufacturing workflows rather than standardized inventory.
Growth Catalysts
- FDA Breakthrough Device Designation:Compressed review timelines for patient-matched constructs accelerate commercialization of personalized correction systems in the United States.
- Germany's Statutory Health Insurance:Comprehensive coverage of conservative and surgical interventions eliminates patient cost barriers and sustains procedure volume in Europe's largest orthopedic market.
- Pediatric Orthopedic Center Expansion:Systematic scoliosis screening programs across United States school districts are identifying curvature progression earlier, expanding the addressable patient pool for intervention.
Market Restraints
- Titanium Alloy Input Volatility:Sponge titanium price fluctuations from Ukrainian and Russian supply disruptions compress margin predictability for implant manufacturers.
- EU MDR Clinical Evidence Burden:Enhanced conformity requirements for spinal implants reshape market access costs, disproportionately burdening mid-tier European manufacturers.
- Conservative Modality Substitution:Schroth method physiotherapy and rigid bracing protocols delay surgical conversion in adolescent populations with moderate Cobb angles.
Strategic Opportunities
- Decentralized Physical Therapy Delivery:Telehealth-integrated rehabilitation protocols create channel expansion beyond hospital-based settings, particularly in rural United States markets.
- Robotic-Assisted Procedure Reimbursement:Evolving CMS coverage determinations for navigation-guided deformity correction open premium pricing corridors for integrated platform vendors.
- Porous Titanium Construct Innovation:Advanced materials research in osseointegration surfaces enables differentiation in spinal fusion outcomes, capturing surgeon preference shifts.
Industry Challenges
- ISO 13485 Certification Timeline Compression:Quality management system audits for patient-matched manufacturing workflows extend lead times for new production facility qualification.
- Complex Deformity Surgical Skill Scarcity:Fellowship-trained pediatric spinal deformity specialists concentrate at academic medical centers, constraining procedure capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kyphoscoliosis Treatment Market |
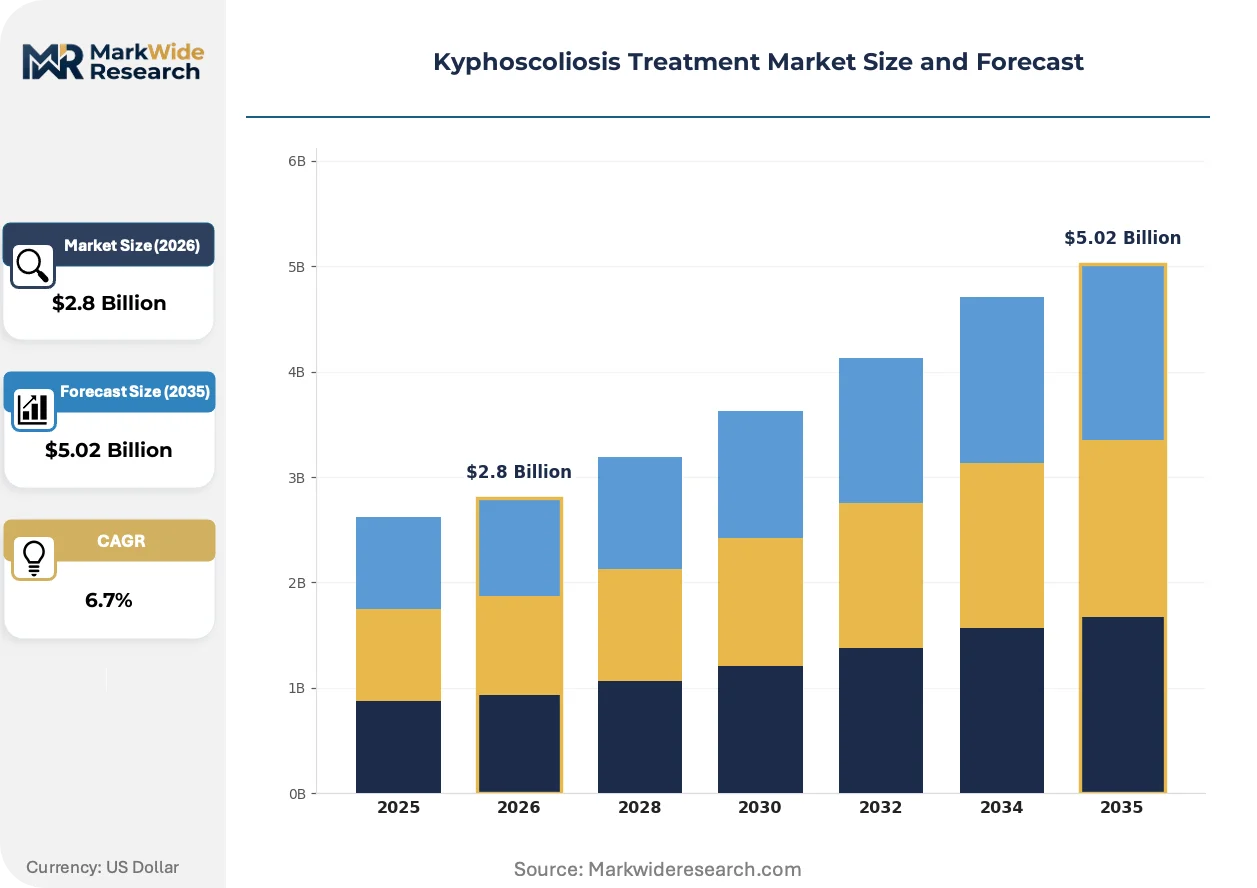
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Physical Therapy, Surgery, Bracing, Medication Patient Age Group: Children, Adolescents, Adults, Elderly Severity Level: Mild, Moderate, Severe, Critical Care Setting: Outpatient, Inpatient, Home Care, Rehabilitation |
| Companies Covered | Medtronic, Stryker, Zimmer Biomet, Johnson & Johnson, Globus Medical, NuVasive, Orthofix, B. Braun, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kyphoscoliosis Treatment Market Shifts & Advancements
Digital surgical planning ecosystems are collapsing the boundaries between pre-operative imaging, implant design, and intra-operative execution, creating integrated workflows that privilege vendors with end-to-end platform control.
Artificial intelligence-powered curvature progression prediction algorithms analyze longitudinal biplanar radiography datasets to forecast adolescent idiopathic scoliosis trajectory. Pediatric orthopedic centers in the United States are integrating these tools into screening protocols. Conventional Cobb angle measurement by manual radiograph assessment is rendering obsolete as automated quantification standardizes surgical decision thresholds.
The EU Medical Device Regulation enforces post-market clinical follow-up obligations for spinal implant manufacturers that exceed prior directive requirements. European orthopedic device firms are restructuring their clinical affairs departments to maintain conformity. High-risk implant categories face the steepest compliance cost escalation, pushing smaller manufacturers toward portfolio rationalization or strategic exits.
Hospital systems are consolidating orthopedic service line purchasing through value analysis committees that evaluate total episode cost rather than implant unit price. Integrated delivery networks negotiate bundled contracts spanning hardware, navigation, and rehabilitation services. This procurement model shift is most pronounced in United States metropolitan markets where health system concentration has accelerated post-pandemic.
Kyphoscoliosis Treatment Market Segmentation
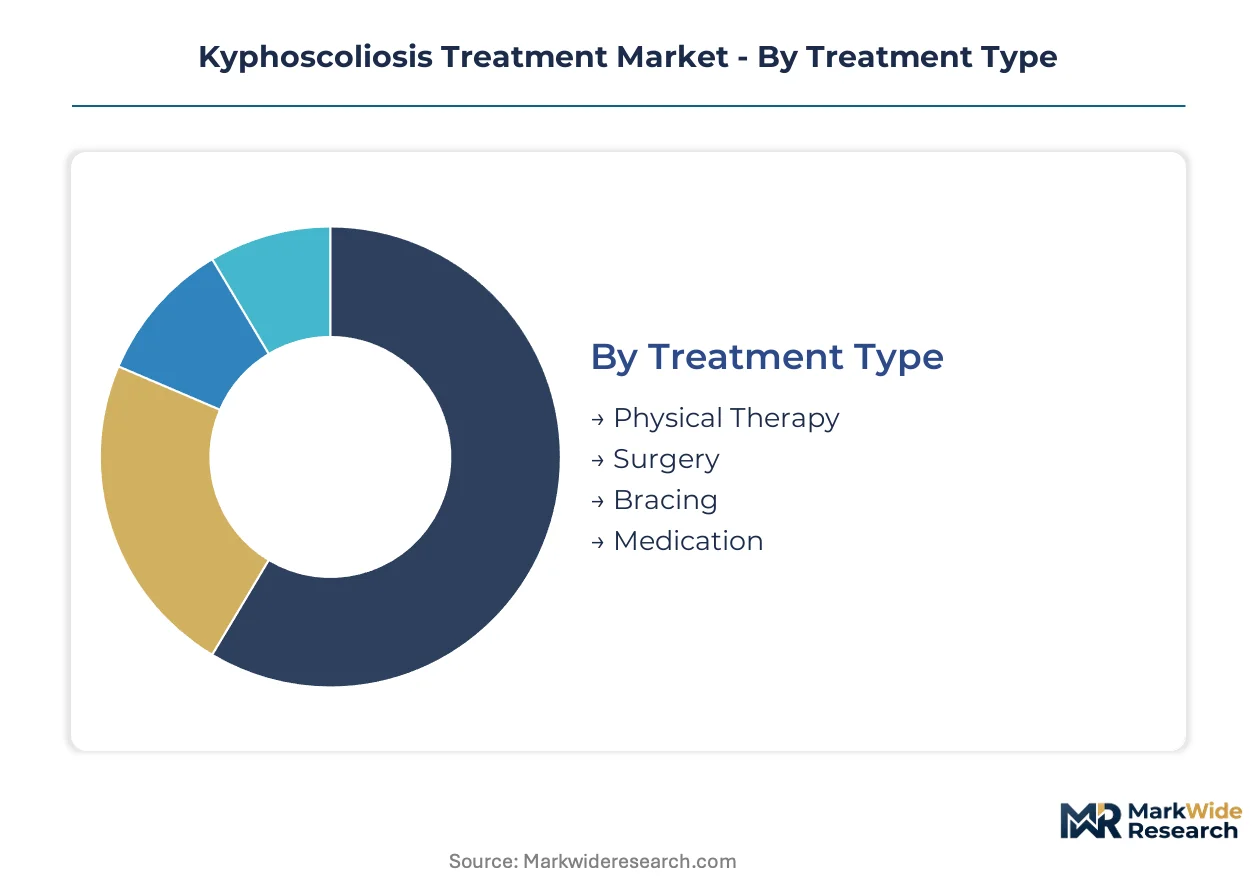
Kyphoscoliosis treatment segmentation reveals distinct service intensity patterns across intervention modalities. Patient age and deformity severity create divergent equipment utilization profiles that reshape vendor support obligations.
Treatment Type:
After-sales service intensity varies sharply across intervention categories, with surgical systems demanding 24/7 technical support while conservative modalities require patient compliance monitoring infrastructure.
- Surgery:Titanium alloy pedicle screws, cobalt-chrome rods, and interbody cages achieve 60-80% deformity correction. Demand concentrates at academic medical centers in Germany and the United States where fellowship-trained specialists manage complex deformity cases. Implant premium pricing and procedural complexity sustain the dominant margin pool.
- Bracing:Rigid thoracolumbosacral orthoses and dynamic correction systems target adolescent idiopathic scoliosis with moderate Cobb angle progression. Volume leadership resides in pediatric orthopedic centers expanding screening programs across United States school districts.
- Physical Therapy:Schroth method protocols and pre-operative rehabilitation programs represent the fastest-expanding conservative modality as CMS reimbursement frameworks broaden for musculoskeletal care.
- Medication:Analgesics and anti-inflammatory agents manage pain in patients awaiting surgical intervention or unsuitable for operative correction.
Surgery holds the largest share; momentum sits with physical therapy.
Patient Age Group:
Cost tier stratification separates pediatric intervention protocols from adult degenerative deformity management, with adolescent screening programs creating volume concentration distinct from elderly surgical conversion patterns.
- Adolescents:Idiopathic scoliosis detection drives bracing and early surgical intervention demand. United States pediatric orthopedic centers are expanding systematic screening infrastructure.
- Adults:Degenerative kyphoscoliosis and prior untreated adolescent curvature progression generate surgical volume. Germany's statutory health insurance eliminates cost barriers for operative correction.
- Children:Early-onset scoliosis requires growing rod systems and serial lengthening procedures. Complex deformity surgical skill scarcity concentrates treatment at major academic centers.
- Elderly:Osteoporotic compression fractures and sagittal imbalance drive demand for minimally invasive stabilization techniques.
Adolescents command procedure volume; adults generate premium surgical revenue.
Severity Level:
Application intensity escalates from monitoring protocols through emergency deformity correction, with Cobb angle thresholds determining intervention modality and reimbursement classification.
- Severe:Cobb angles exceeding 40-50 degrees mandate surgical correction with titanium instrumentation. FDA breakthrough device designations accelerate patient-matched implant commercialization.
- Moderate:25-40 degree curvature drives bracing protocols and Schroth physiotherapy to delay or prevent surgical conversion.
- Mild:Observation and physical therapy dominate, with artificial intelligence-powered progression prediction algorithms entering screening workflows.
- Critical:Neurological compromise and cardiopulmonary restriction require emergency deformity correction with specialized intraoperative monitoring.
Severe cases capture surgical revenue concentration; moderate severity expands conservative modality volume.
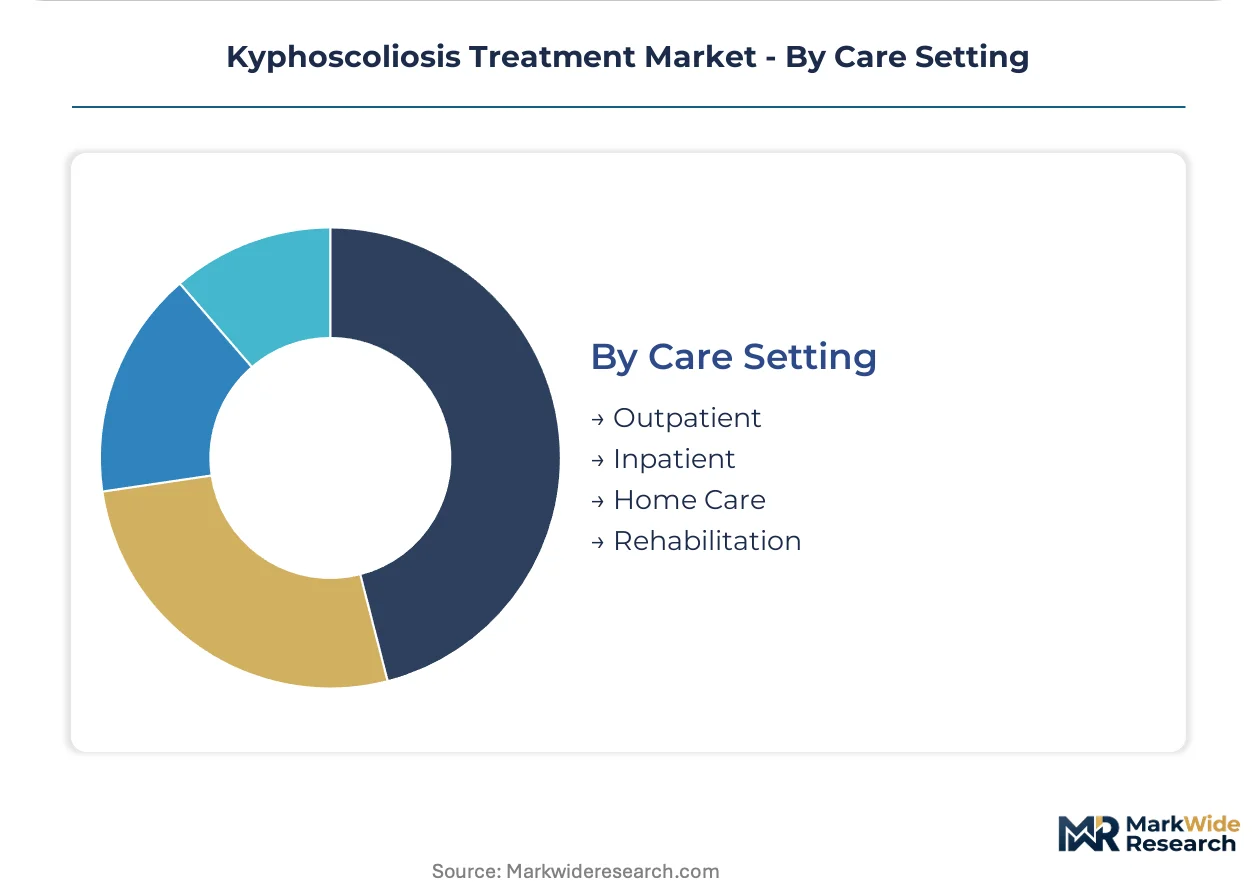
Care Setting:
Customer type fragmentation separates hospital-based surgical delivery from decentralized rehabilitation, with telehealth integration reshaping physical therapy access geography.
- Inpatient:Complex deformity correction and fusion procedures require specialized nursing and pain management infrastructure. Academic medical centers concentrate surgical capacity.
- Outpatient:Bracing fitting, physical therapy sessions, and post-operative follow-up generate recurring visit volume.
- Rehabilitation:Structured programs address post-surgical functional recovery and conservative management compliance.
- Home Care:Telehealth-integrated protocols and remote monitoring create channel expansion into rural United States markets.
Inpatient settings anchor surgical revenue; home care represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German implant manufacturers export titanium spinal instrumentation to United States academic medical centers, establishing a transatlantic trade corridor that concentrates premium surgical hardware procurement in major metropolitan hospital systems.
United States
Pediatric orthopedic centers in Texas and California are expanding school-based scoliosis screening infrastructure, capturing adolescent cases earlier in disease progression. FDA breakthrough device designations for patient-matched constructs compress commercialization timelines for domestic manufacturers. Philadelphia and Boston academic medical clusters concentrate fellowship-trained spinal deformity specialists managing complex surgical conversions.
Germany
Statutory health insurance eliminates patient cost barriers for both conservative and surgical kyphoscoliosis interventions, sustaining procedure volume across severity spectrums. EU Medical Device Regulation enforces enhanced clinical evidence requirements for spinal implant conformity, reshaping market access costs for domestic manufacturers. The Rhine-Ruhr industrial corridor hosts precision machining clusters supplying cobalt-chrome rod stock to European orthopedic device fabricators.
Japan
PMDA regulatory frameworks govern commercialization of titanium alloy pedicle screw systems, with aging demographics driving adult degenerative deformity surgical demand. METI industrial policy supports domestic production of advanced biomaterials for spinal fusion applications. The Kanto region around Tokyo concentrates specialized orthopedic surgical capacity at university-affiliated hospitals.
China
NMPA registration requirements for Class III spinal implants create regulatory barriers that favor domestic manufacturers with established quality management systems. Provincial healthcare procurement coalitions negotiate volume-based pricing for standard instrumentation, compressing margins for multinational suppliers. The Yangtze River Delta manufacturing belt produces titanium sponge and precision-forged implant blanks for regional device assembly.
United Kingdom
NHS England specialized commissioning frameworks route complex spinal deformity cases to designated supra-regional centers, concentrating surgical expertise in London, Manchester, and Birmingham. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards while streamlining domestic device approvals. The Oxford-Cambridge arc hosts medical technology incubators developing AI-powered curvature progression prediction tools.
Kyphoscoliosis Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform vendors with end-to-end control over navigation, robotics, and implant portfolios. Three strategic archetypes dominate: diversified orthopedic conglomerates with spinal divisions, pure-play spinal technology specialists, and emerging patient-matched manufacturing entrants. Competitive dynamics center on M&A activity capturing robotic navigation capabilities and strategic partnerships securing titanium alloy supply commitments.
Among diversified orthopedic conglomerates, Medtronic and Stryker occupy positions anchoring the premium-tier surgical hardware segment, while Globus Medical exemplifies the spinal-specialist archetype with concentrated focus on deformity correction technologies. These three entities represent distinct competitive positioning strategies—integrated robotics platforms, specialized adolescent scoliosis portfolios, and advanced materials research—without overlapping core value propositions.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Zimmer Biomet |
| Johnson & Johnson |
| Globus Medical |
| NuVasive |
| Orthofix |
| B. Braun |
| Integra LifeSciences |
| Others |
Supply & Pricing Matrix
Undercapacity in European titanium sponge processing is forcing implant manufacturers to accept longer lead times and elevated input costs, compressing margins across both premium patient-matched constructs and standard pedicle screw systems while simultaneously shifting procurement strategies toward multi-source qualification programs.
Pricing Analysis
Next-generation patient-matched 3D-printed constructs command substantial premiums over conventional cobalt-chrome rod systems and prior-generation titanium instrumentation. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated patient-specific implants from CE-marked standard hardware and unbranded economy alternatives. Price differentiation hinges on ISO 13485 certification tier and customization level, with academic medical centers demonstrating lowest price sensitivity due to bundled reimbursement frameworks while provincial procurement coalitions in China exert maximum pressure. Pricing pressure stems from NMPA-mandated volume-based tendering compressing margins for multinational suppliers.
Supply Chain Analysis
Export control restrictions on advanced additive manufacturing equipment limit patient-matched production capacity expansion outside designated technology-access jurisdictions. Geographic supply concentration centers on Germany for precision cobalt-chrome rod stock, China for titanium sponge and forged implant blanks, and the United States for navigation platform assembly. Raw material dependencies draw from Ukrainian and Russian sponge titanium flows, precision-machined pedicle screw blanks, and specialized porous titanium powders. Single-source vulnerability in fellowship-trained deformity specialist concentration constrains surgical capacity scaling. Distribution runs through hospital value analysis committees and integrated delivery network bundled contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kyphoscoliosis treatment sits at early-cycle expansion, with FDA breakthrough device designations compressing commercialization timelines for patient-matched constructs and expanding the addressable surgical population beyond traditional severity thresholds.
For Market Incumbents: Pre-empt consolidation of robotic navigation capabilities through targeted capability acquisitions, as digital surgical planning ecosystems privilege vendors with end-to-end platform control. Secure captive supply commitments for titanium alloy sponge through backward integration or long-term offtake agreements with German and Chinese processors to defend against input volatility from Eastern European supply disruptions. Prioritize ISO 13485 certification investment for patient-matched manufacturing workflows to accelerate new production facility qualification timelines.
For New Entrants and Emerging Players: Establish a beachhead in decentralized physical therapy delivery, where telehealth-integrated rehabilitation protocols remain underpenetrated in rural United States markets and CMS reimbursement frameworks are broadening. Target adolescent idiopathic scoliosis screening program infrastructure as the most penetrable entry point, partnering with pediatric orthopedic centers expanding systematic detection across school districts. Pursue a software companion development go-to-market angle, integrating AI-powered curvature progression prediction into existing screening workflows without requiring capital-intensive implant manufacturing scale.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform vendors combining navigation, robotics, and implant portfolios, as hospital systems consolidate orthopedic service line purchasing through bundled contracts spanning hardware and rehabilitation services. Five-to-ten year viability favors spinal-specialist archetypes with concentrated deformity correction expertise over diversified orthopedic conglomerates facing portfolio rationalization pressures. Monitor CMS coverage determination evolution for robotic-assisted procedures as the critical inflection signal for premium pricing corridor sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Compressed review timelines accelerate patient-matched construct commercialization for domestic manufacturers. |
| Hospital System Partnership | Bundled contracting with integrated delivery networks captures orthopedic service line consolidation in metropolitan markets. |
| Backward Integration into Titanium Supply | Captive sponge processing mitigates margin unpredictability from Ukrainian and Russian supply disruptions. |
| Software Companion Development | AI-powered curvature progression prediction integrates into pediatric screening protocols without implant manufacturing scale. |
| Reimbursement Strategy | CMS coverage determination navigation opens premium pricing corridors for robotic-assisted deformity correction. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with pediatric orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR conformity assessment documentation. Bottom-up modeling of procedure volumes by severity tier and age group triangulated against top-down implant shipment data from German and United States precision machining clusters.
Forecast inputs considered treatment modality segmentation, patient age group penetration patterns, severity-level intervention thresholds, and care setting migration trends across the analysis window. CAGRs derived from procedure volume elasticity to screening program expansion, statutory insurance coverage breadth, and regulatory pathway efficiency variations. Industry-specific inputs incorporated EU MDR clinical evidence burden cost escalation and PMDA framework evolution for titanium alloy systems.
Sensitivities concentrate around titanium sponge price volatility, EU MDR implementation timeline extensions, and CMS robotic-assisted procedure coverage determination shifts. Forecasts reflect documented assumptions on screening program rollout pace and fellowship-trained specialist supply expansion. Material shifts in statutory health insurance coverage scope or breakthrough device designation criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Orthopedic Extremity Market
Orthopedic Devices
Global Total Ankle Replacement Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Medical Crutches Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Global Elbow Replacement Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Orthobiologics Market