
 Birth Tissue Products Market | 2026-2036
Birth Tissue Products Market Size, Share, and Industry Trends Forecast 2026-2036
Birth Tissue Products Market Outlook
US-based tissue banks and specialized processors is expanding cryopreservation capacity to meet hospital procurement needs. MiMedx leverages vertical integration across tissue recovery and distribution to control supply chain quality. BioTissue sustains dominance in ocular surface applications through proprietary processing methods. Organogenesis anchors its position in wound healing with advanced amniotic membrane technologies.
Birth tissue products comprise minimally manipulated human allografts derived from placental and umbilical sources, processed under aseptic conditions with cryoprotectant preservation at controlled temperatures to maintain extracellular matrix integrity and bioactive protein content. These materials serve primarily as biological scaffolds that modulate inflammation and facilitate tissue regeneration in chronic and acute wounds. Amniotic membrane leads product type demand due to established reimbursement pathways in wound care, while cord tissue represents the fastest-growing category as orthopedic applications expand. Regenerative medicine applications command premium pricing, whereas wound healing constitutes the largest volume segment with mature margin compression.
FDA HCT/P regulations, AATB accreditation standards, and state tissue bank licensing requirements collectively govern donor eligibility, processing validation, and distribution chain integrity. These frameworks elevate compliance costs for new entrants while reinforcing incumbent quality advantages. Stakeholders must monitor evolving FDA enforcement discretion policies and state-level tissue distribution restrictions that could reshape competitive access.
Market Dynamics
FDA enforcement discretion tightening around HCT/P classification is forcing tissue processors to revalidate manufacturing protocols and absorb elevated compliance costs, compressing margins for minimally manipulated allografts while advantaging vertically integrated operators with captive donor screening infrastructure.
Growth Catalysts
- Orthopedic Application Expansion:Sports medicine clinics and ambulatory surgery centers are integrating cryopreserved cord tissue allografts into cartilage repair protocols, driving volume absorption beyond traditional wound care settings.
- Reimbursement Pathway Maturation:CMS coverage determinations for amniotic membrane products in diabetic foot ulcers have stabilized payment predictability, reducing hospital procurement friction and accelerating formulary adoption.
- Regenerative Medicine Pipeline:Clinical translation of birth tissue-derived extracellular matrix scaffolds into ophthalmology and urology applications is opening addressable procedure categories with premium pricing tolerance.
Market Restraints
- Donor Tissue Supply Concentration:Recovery network density clusters in southeastern United States hospital systems, creating geographic supply vulnerability and transportation cost escalation for western processing facilities.
- Cryoprotectant Input Volatility:Dimethyl sulfoxide and glycerol procurement costs fluctuate with pharmaceutical-grade chemical supply chains, directly pressuring per-unit processing economics.
- FDA Classification Uncertainty:Ambiguity between Section 361 HCT/P and Section 351 biologic product pathways subjects developers to unpredictable premarket review timelines and capital commitment risk.
Strategic Opportunities
- Veterans Affairs System Penetration:Undercontracted status with VA medical centers presents volume opportunity for chronic wound management in diabetes and combat trauma sequelae populations.
- Decentralized Processing Technology:Point-of-care tissue processing platforms enabling same-day allograft preparation could disintermediate centralized tissue bank distribution in metropolitan hospital networks.
- International Harmonization:Alignment with EMA's Advanced Therapy Medicinal Products framework may streamline European market entry for US processors with existing FDA quality management systems.
Industry Challenges
- Specialized Bioprocessing Talent Scarcity:Aseptic tissue processing technicians with combined cGMP and aseptic technique certification command premium compensation and exhibit high turnover in non-metropolitan processing locations.
- Legacy Electronic Record Integration:Tissue tracking systems must interface with hospital ERP platforms lacking standardized interoperability, forcing custom API development and validation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Birth Tissue Products Market |
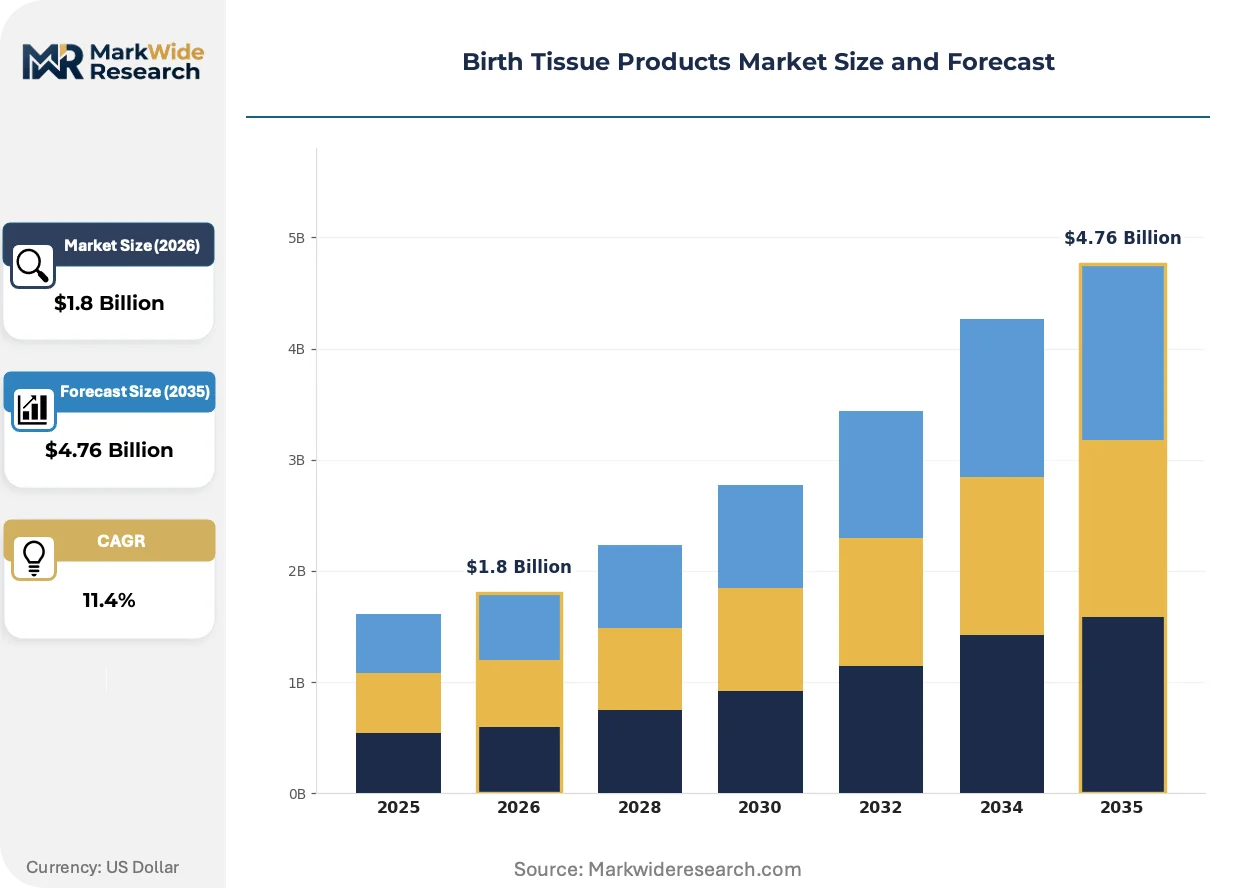
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Umbilical Cord Blood, Amniotic Membrane, Cord Tissue, Placental Tissue Application: Regenerative Medicine, Wound Healing, Orthopedics, Aesthetic Procedures Delivery Mode: Direct Shipment, Cryopreservation, In-Hospital, Outpatient Facilities End User: Hospitals, Clinics, Research Laboratories, Biotech Companies |
| Companies Covered | MiMedx, BioTissue, Organogenesis, MTF Biologics, Merakris Therapeutics, Surgenex, Stryker, Integra LifeSciences, Skye Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Birth Tissue Products Market Strategic Shifts
Lyophilization and ambient-stable preservation technologies are disrupting cryopreservation-dependent supply chains, enabling inventory positioning closer to point-of-care and reducing cold-chain infrastructure burden across distribution networks.
Lyophilized amniotic membrane products are absorbing shelf-life extension requirements from hospital materials management departments seeking to reduce wastage from expired cryopreserved inventory. Ambulatory surgery centers without dedicated cryogenic storage capacity are converting procurement toward these formats, compressing demand for traditional frozen allografts in outpatient settings.
REACH registration requirements for novel cryoprotectant chemistries are elevating formulation disclosure burdens for European market entrants, compelling processors to reformulate with pre-registered substances or absorb extended regulatory timelines. German and French notified bodies are enforcing enhanced substance characterization documentation, disproportionately affecting mid-cap tissue banks without dedicated regulatory affairs functions.
Hospital value analysis committees have displaced individual surgeon preference as the primary procurement decision node, consolidating purchasing authority and compressing vendor rosters to two-to-three preferred tissue bank relationships. This concentration is most visible in integrated delivery networks across Texas and Florida, where system-wide contracts now govern birth tissue product selection across dozens of affiliated facilities.
Birth Tissue Products Market Segmentation
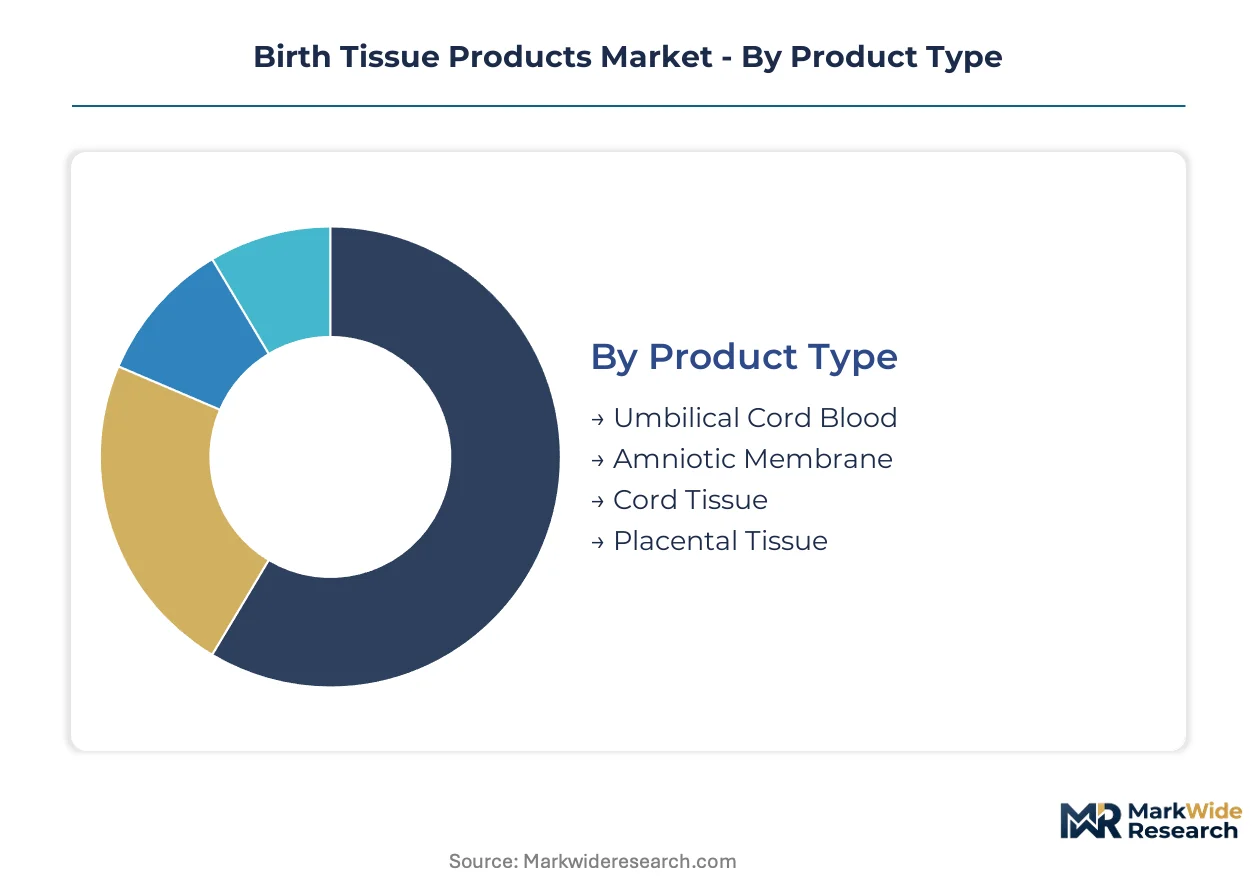
Birth tissue procurement decisions hinge on preservation requirements, reimbursement pathways, and procedure setting constraints. Segmentation reveals how cryopreservation economics and clinical application specificity reshape vendor selection and inventory management across customer tiers.
Product Type:
Hospital materials management departments prioritize shelf-life stability and cold-chain burden when evaluating allograft formats.
- Amniotic Membrane:Dehydrated and cryopreserved formats provide extracellular matrix scaffolding with retained growth factor content. CMS coverage determinations for diabetic foot ulcer applications have stabilized procurement predictability in United States hospital systems, entrenching this category as the volume anchor.
- Cord Tissue:Wharton's jelly-derived allografts deliver mesenchymal stem cell-rich matrix for cartilage and soft tissue repair. Orthopedic clinics in Texas and Florida integrated delivery networks are absorbing larger volumes as sports medicine applications expand beyond traditional wound care.
- Umbilical Cord Blood:Hematopoietic progenitor cell source for transplantation protocols, governed by distinct FDA biologics licensing requirements separate from Section 361 HCT/P pathways.
- Placental Tissue:Decidua-derived matrix products with anti-inflammatory cytokine profiles, primarily deployed in ophthalmology and urology subspecialties with premium pricing tolerance.
Volume sits with amniotic membrane; growth tilts toward cord tissue.
Application:
Margin compression severity varies sharply by therapeutic area maturity and competitive density.
- Wound Healing:Diabetic foot ulcer and venous leg ulcer management constitute the largest addressable procedure volume. Hospital value analysis committees in southeastern United States systems have consolidated vendor rosters, compressing margins for established allograft suppliers.
- Regenerative Medicine:Ophthalmology, urology, and cardiology applications command premium pricing due to specialized handling requirements and limited substitute availability. Clinical translation pipelines at research-intensive medical centers are expanding addressable categories.
- Orthopedics:Cartilage repair and tendon augmentation procedures in ambulatory surgery centers are driving format conversion toward ambient-stable preservation technologies.
- Aesthetic Procedures:Hair restoration and facial rejuvenation applications operate outside established reimbursement frameworks, with cash-pay dynamics insulating pricing from institutional procurement pressure.
Revenue concentrates in wound healing; margin expansion is steepest in regenerative medicine.
Delivery Mode:
Cold-chain infrastructure availability at the point of care dictates format viability and distribution economics.
- Cryopreservation:Controlled-rate freezing with dimethyl sulfoxide preservation maintains extracellular matrix integrity for extended storage. United States tissue banks are expanding capacity to meet hospital procurement needs, though transportation cost escalation affects western processing facilities.
- Direct Shipment:Just-in-time logistics from centralized processing facilities to metropolitan hospital networks, requiring validated temperature monitoring and chain-of-custody documentation.
- In-Hospital:On-site cryogenic storage and inventory management by hospital materials management departments, prevalent in level I trauma centers with high chronic wound admission volumes.
- Outpatient Facilities:Ambulatory surgery centers without dedicated cryogenic infrastructure are converting procurement toward lyophilized formats, reducing wastage from expired inventory.
Procurement weight rests with cryopreservation; format conversion accelerates fastest in outpatient facilities.
End User:
Purchasing authority concentration and technical specification complexity reshape account targeting priorities.
- Hospitals:Integrated delivery networks across Texas and Florida now govern birth tissue product selection through system-wide contracts, consolidating vendor relationships to two-to-three preferred tissue banks per network.
- Clinics:Sports medicine and wound care clinics exhibit surgeon-driven preference with limited value analysis oversight, preserving premium pricing for specialized allograft formats.
- Research Laboratories:Academic medical centers with IND-enabling studies require characterized, traceable tissue sources with documented donor screening protocols.
- Biotech Companies:Cell therapy developers source birth tissue derivatives for expansion media and scaffold manufacturing, with supply agreements spanning multi-year procurement commitments.
Transaction volume aggregates at hospitals; pricing power persists strongest in clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Placental tissue recovery networks concentrate in southeastern United States hospital systems, creating geographic supply asymmetries that reshape processing economics and distribution infrastructure investments across major markets.
United States
Hospital procurement of amniotic membrane products for wound care has intensified, particularly within Texas and Florida integrated delivery networks. FDA HCT/P guidance revisions are tightening donor screening protocols and elevating compliance costs for tissue processors. Atlanta and Miami anchor recovery network density, with metropolitan hospital systems expanding cryopreservation capacity to serve western distribution corridors.
Germany
Notified bodies are enforcing enhanced substance characterization documentation for cryoprotectant chemistries under REACH registration requirements. EMA's Advanced Therapy Medicinal Products framework is streamlining pathway alignment for US processors with existing FDA quality management systems. The Rhine-Ruhr medical technology cluster hosts specialized regulatory affairs functions serving mid-cap tissue banks seeking European market entry.
Japan
PMDA oversight of minimally manipulated allografts is creating premarket review timeline predictability for birth tissue-derived scaffolds in ophthalmology applications. METI-supported regenerative medicine commercialization programs are accelerating clinical translation pipelines at academic medical centers. The Kanto region's hospital procurement systems are evaluating lyophilized formats to reduce cold-chain infrastructure burdens.
United Kingdom
NHS value analysis committees are consolidating vendor rosters for chronic wound management products, compressing margins for established allograft suppliers. MHRA post-Brexit regulatory autonomy is creating divergence from EMA guidance on HCT/P classification pathways. London's research-intensive medical centers are expanding IND-enabling studies requiring characterized, traceable tissue sources.
Australia
TGA biologicals framework is clarifying oversight boundaries between minimally manipulated allografts and cellular therapy products. Public hospital procurement centralization in New South Wales and Victoria is shifting purchasing authority toward system-wide contracts. Melbourne's specialized wound care clinics are absorbing cryopreserved cord tissue volumes for sports medicine applications.
Birth Tissue Products Market Competitive Environment
Global majors compete with regional champions across regulatory compliance infrastructure and donor recovery network density. The vendor base stratifies into three tiers: vertically integrated tissue banks with captive supply chains, specialized processors with proprietary preservation technologies, and diversified medical device conglomerates with allograft divisions. Two strategic archetypes dominate competitive positioning: quality-certification leaders leveraging AATB accreditation advantages, and format-innovation specialists commercializing ambient-stable alternatives to cryopreserved products. M&A activity concentrates on recovery network acquisitions and lyophilization technology licensing.
Within the vertically integrated tier, MiMedx exemplifies upstream control across tissue recovery and distribution. BioTissue occupies a position among specialized processors with proprietary methods. Organogenesis anchors the wound care application segment. These three represent distinct competitive archetypes: captive supply chain operators, technology-differentiated specialists, and indication-focused commercializers.
| Leading Market Players |
|---|
| MiMedx |
| BioTissue |
| Organogenesis |
| MTF Biologics |
| Merakris Therapeutics |
| Surgenex |
| Stryker |
| Integra LifeSciences |
| Skye Biologics |
| Others |
Value Chain & Pricing Dynamics
Aseptic tissue processing technicians with combined cGMP certification cluster in southeastern United States metropolitan corridors, and this workforce concentration widens pricing spreads between premium-certified and standard-grade allograft tiers as labor-cost differentials compound cryoprotectant input volatility.
Pricing Analysis
Service bundling separates validated chain-of-custody documentation and temperature monitoring from unbundled direct-shipment alternatives, with premium tiers incorporating extended shelf-life guarantees and expedited logistics support. Price differentiation hinges on AATB accreditation status and cryopreservation format, with ambient-stable lyophilized products commanding modest premiums over frozen alternatives. Cost compression in standard-grade amniotic membrane is intensifying as hospital value analysis committees consolidate vendor rosters in Texas and Florida integrated delivery networks. Ambulatory surgery centers exhibit greatest price sensitivity due to absence of dedicated cryogenic infrastructure, while research-intensive medical centers demonstrate lowest sensitivity given IND-enabling study requirements.
Supply Chain Analysis
Single-source vulnerability sits with dimethyl sulfoxide and glycerol suppliers concentrated in pharmaceutical-grade chemical manufacturing corridors of Germany, China, and the United States. Birth tissue recovery networks draw from southeastern United States hospital systems anchored in Atlanta and Miami, with processing capacity expansion lagging procurement growth in western distribution corridors. Tariff exposure on cryoprotectant imports elevates formulation cost unpredictability for mid-cap tissue banks without captive chemical synthesis. Distribution runs through centralized tissue bank facilities with validated cold-chain logistics to metropolitan hospital networks, though point-of-care processing platforms threaten disintermediation in select markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Donor tissue recovery capacity constraints in southeastern United States hospital systems prop pricing power for vertically integrated operators with captive supply networks, as procurement demand outpaces qualified recovery technician availability.
For Market Incumbents: Cement AATB accreditation advantages through investment in proprietary lyophilization technologies that reduce cold-chain dependency, while expanding recovery network density in underserved western states to preempt geographic supply vulnerability. Defend against ambient-stable format disruption by locking multi-year exclusive supply agreements with level I trauma centers before point-of-care processing platforms achieve regulatory validation. For New Entrants and Emerging Players: Veterans Affairs medical centers present an underserved buyer archetype with chronic wound management volume opportunity and limited incumbent penetration. Target sports medicine clinics in ambulatory surgery centers lacking cryogenic infrastructure with lyophilized cord tissue formats, leveraging surgeon-driven procurement autonomy outside hospital value analysis committee oversight. Pursue go-to-market partnerships with orthopedic device distributors possessing established ASC relationships. For Investors and Strategic Acquirers: Re-rating potential sits with specialized processors possessing proprietary preservation technologies given FDA enforcement discretion tightening around HCT/P classification pathways. Long-term viability favors operators with demonstrated European regulatory navigation under EMA Advanced Therapy Medicinal Products frameworks. Watch for VA system contract awards as inflection indicators of procurement authority consolidation in government healthcare segments.| Strategic Initiative | Industry Significance |
|---|---|
| Recovery Network Expansion | Captive donor tissue supply in western states reduces transportation cost escalation and geographic vulnerability. |
| Lyophilization Technology Licensing | Ambient-stable formats unlock ambulatory surgery center procurement previously excluded by cryogenic constraints. |
| VA System Contract Acquisition | Federal procurement consolidation in diabetes and combat trauma populations diversifies revenue concentration. |
| EMA Pathway Alignment | Advanced Therapy Medicinal Products framework navigation streamlines European market entry for US processors. |
| Point-of-Care Platform Development | Same-day allograft preparation capabilities threaten centralized tissue bank distribution in metropolitan networks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with tissue bank operations directors, hospital materials management executives, AATB accreditation specialists, and orthopedic clinic administrators. FDA HCT/P guidance documents, EMA Advanced Therapy Medicinal Products submissions, CMS coverage determinations, and state tissue bank licensing databases provided regulatory context. Bottom-up triangulation across procurement volume estimates and top-down validation against aggregate market sizing ensured analytical consistency.
Granularity-level modeling proceeded at product-type, preservation-format, application, and end-user dimensions, with separate trajectory construction for cryopreserved versus lyophilized segments across the projection horizon. CAGRs derived from procedure volume elasticity analysis, reimbursement pathway maturation timelines, and format conversion adoption curves. Industry-specific inputs incorporated orthopedic clinic expansion rates, VA system contract award patterns, and cryoprotectant chemical supply chain stability indicators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA classification pathway revisions, state-level tissue distribution restriction enactments, and decentralized processing technology regulatory clearance timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Toothbrush Sanitizer Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Pressure Ulcer Prevention Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Australia Hair Transplant Market
Healthcare Products
Global Healthcare Distribution Market
Healthcare Products
Medical Products Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
North America Adult Incontinence Products Market