
 Orthopedic Contract Manufacturing Market | 2026-2036
Orthopedic Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Contract Manufacturing Market Outlook
Ambulatory surgical centers are redrawing procurement patterns in orthopedic contract manufacturing, pulling volume away from traditional hospital supply chains toward lower-lot, higher-mix production models. Paragon Medical Inc. leverages its Swiss machining expertise to serve this shift with quick-turn instrument sets. Norman Noble Inc. anchors complex implant-forging operations for spine and trauma OEMs seeking domestic US supply security. Orchid Orthopedic Solutions LLC differentiates through vertically integrated finishing and sterilization services that compress lead times for ASC-focused brands.
Orthopedic contract manufacturing encompasses the outsourced production of implantable devices, surgical instruments, and delivery systems, typically involving biocompatible alloys such as Ti-6Al-4V ELI titanium or cobalt-chrome-molybdenum processed to ISO 5832 standards and finished to sub-micron surface-roughness specifications for osseointegration. The primary commercial purpose is to enable original equipment manufacturers to scale production without capital-intensive cleanroom forging, machining, or additive-manufacturing infrastructure. Joint implants and spine implants command the deepest margin pools due to regulatory qualification barriers and long product lifecycles, while 3D-printed porous titanium structures represent the fastest-growing technology segment as patient-specific lattice geometries gain surgical adoption. CNC machining retains the largest volume share across trauma plates and revision stems where dimensional tolerances of ±25 micrometers remain non-negotiable.
FDA's Quality System Regulation under 21 CFR Part 820 and the EU MDR's Annex I general safety and performance requirements govern design controls, process validation, and post-market surveillance for contract manufacturers serving dual-continent OEMs. ISO 13485 certification has become table stakes, with unannounced audits by notified bodies now compressing response windows for corrective actions. Switzerland's Swissmedic maintains equivalence agreements that streamline market access for precision-forged implants, reinforcing the country's cluster dominance. Stakeholders must monitor how FDA's emerging guidance on artificial-intelligence-enabled manufacturing controls reshapes qualification protocols for automated inspection and real-time release testing.
Market Dynamics
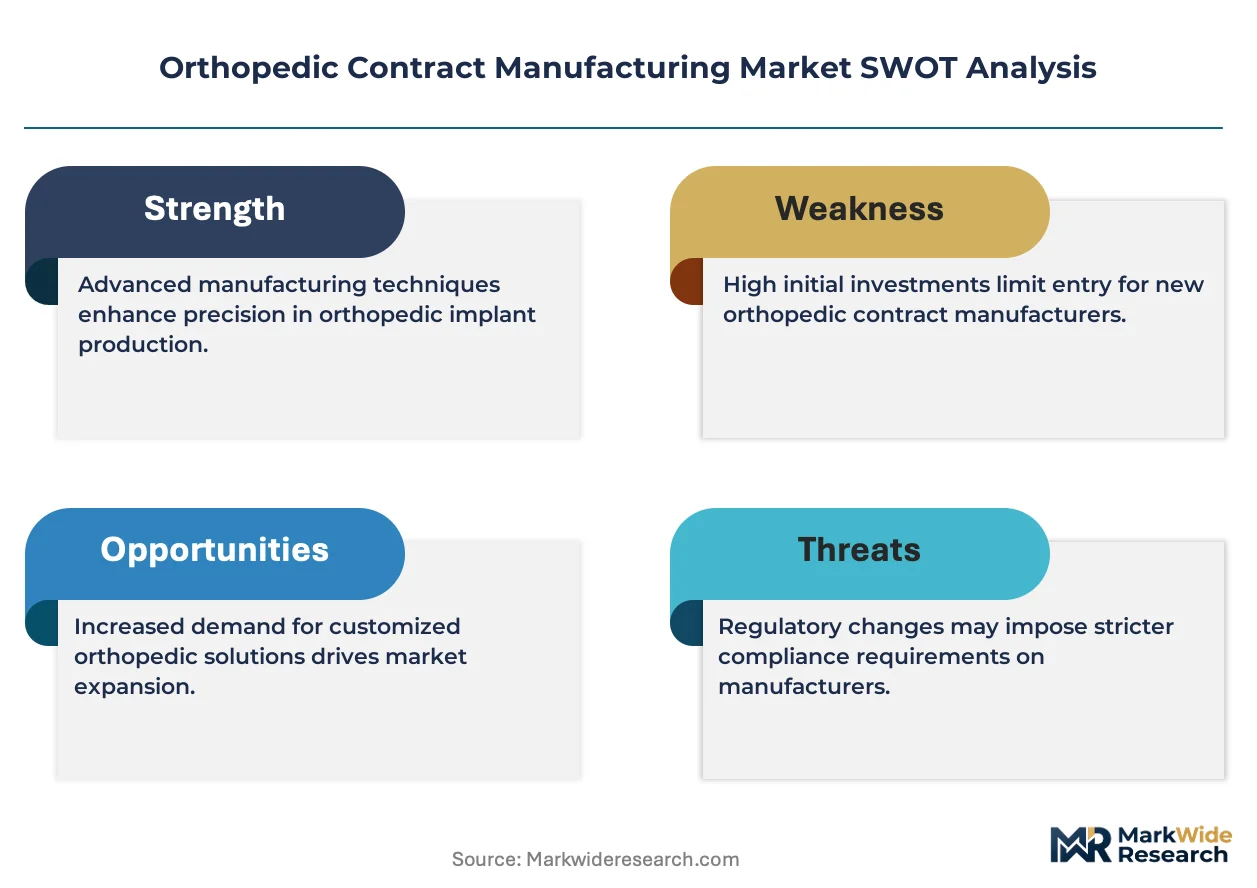
Orthopedic contract manufacturing is undergoing a fundamental restructuring as ambulatory surgical centers displace hospitals as the primary volume channel, forcing contract manufacturers to retool for smaller batch sizes and faster turnaround cycles without sacrificing regulatory compliance.
Growth Catalysts
- EU MDR clinical-evidence mandates:Stricter Annex I requirements for implantable devices are extending OEM reliance on qualified contract manufacturers with established quality systems and notified-body relationships.
- Additive manufacturing qualification:FDA's updated 510(k) pathway for laser-powder-bed-fusion implants is accelerating patient-specific porous titanium lattice adoption for hip and knee revision cases.
- Switzerland's precision cluster:Concentrated titanium-forging and polymer-molding capabilities around Solothurn and Tuttlingen attract OEMs seeking ISO 5832-certified supply security for trauma and spine portfolios.
Market Restraints
- Raw material concentration:Sponge titanium supply concentrates in a handful of producers, exposing contract manufacturers to price volatility for Ti-6Al-4V ELI feedstock essential for osseointegration-grade implants.
- Cleanroom capex intensity:ISO 14644 Class 7 forging and machining infrastructure requires eight-figure capital commitments that depress returns for mid-scale contract manufacturers serving second-tier OEMs.
- Notified-body capacity constraints:EU MDR transition has thinned the field of designated conformity assessment bodies, extending lead times for new product qualifications and freezing some OEM sourcing decisions.
Strategic Opportunities
- India's emerging orthopedic corridor:CDSCO's streamlined medical device licensing and the PLI scheme's capital subsidies are drawing contract manufacturing investment for trauma and extremities implants targeting domestic and export markets.
- Real-time release testing:Convergence of in-process analytical technologies with automated inspection systems offers pathways to compress sterility assurance and dimensional validation cycles for ASC-focused brands.
- Japan's aging demographic:PMDA's priority review designation for revision-joint solutions creates procurement pull for contract manufacturers with cobalt-chrome-molybdenum forging expertise and Japanese QP relationships.
Industry Challenges
- Metrology talent scarcity:Contract manufacturers struggle to recruit operators proficient in coordinate-measuring-machine programming for sub-25-micrometer tolerance verification on complex stem geometries.
- Legacy MES integration:Paper-based batch records and disconnected quality systems resist digitization, compling FDA 21 CFR Part 11 compliance for electronic signatures and audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Contract Manufacturing Market |
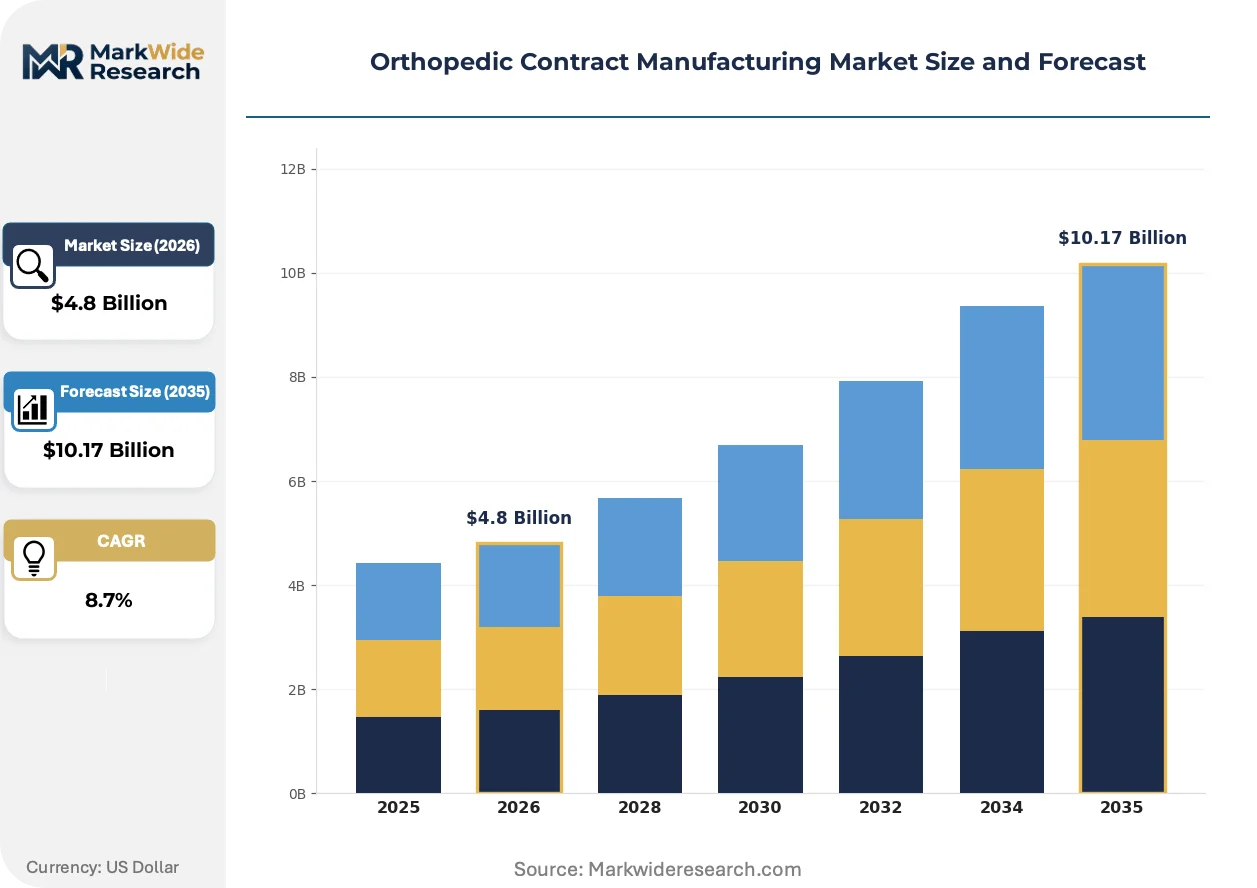
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Joint Implants, Trauma Devices, Spine Implants, Surgical Instruments Technology: 3D Printing, CNC Machining, Injection Molding, Forging End User: Hospitals, Clinics, Research Institutions, Rehabilitation Centers Service Type: Design Services, Prototyping, Assembly, Quality Control |
| Companies Covered | Avalign Technologies Inc., Paragon Medical Inc., Micron Products Inc., CRETEX Medical Inc., Norman Noble Inc., Orchid Orthopedic Solutions LLC, UFP Technologies Inc., Viant Medical Inc., Tecomet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Contract Manufacturing Market Strategic Shifts
Orthopedic contract manufacturing is pivoting from volume-scale production toward agile, technology-differentiated service models as OEMs fragment sourcing across specialized capabilities rather than consolidated full-service suppliers.
Robotic-assisted surgical systems are miniaturizing instrument set footprints and driving demand for micro-machined retractors and guide sleeves with sub-10-micrometer positional tolerances. ASC procurement teams specify these compact configurations to maximize suite turnover. Contract manufacturers with Swiss-type lathe arrays and automated bar-feed systems capture this shift by compressing lot-changeover intervals from days to hours.
Swissmedic's mutual recognition agreements with FDA and Health Canada are streamlining dual-continent market access for precision-forged implants originating in the Solothurn-Tuttlingen corridor. This regulatory equivalence reduces redundant facility audits and accelerates OEM time-to-revenue for trauma plate and revision stem launches. Contract manufacturers maintaining simultaneous ISO 13485 and MDSAP certifications capture disproportionate share of North American and European OEM dual-sourcing strategies.
Hospital supply chain consolidation is fragmenting as ASC networks and physician-owned surgery centers negotiate direct purchasing agreements bypassing traditional distributor markups. Contract manufacturers with in-house sterilization and direct-to-site logistics capabilities displace distributor-dependent competitors in the United States outpatient orthopedic segment. This channel compression rewards vertically integrated finishing operations that can validate sterile barrier integrity and manage lot-level traceability without third-party intervention.
Orthopedic Contract Manufacturing Market Segmentation
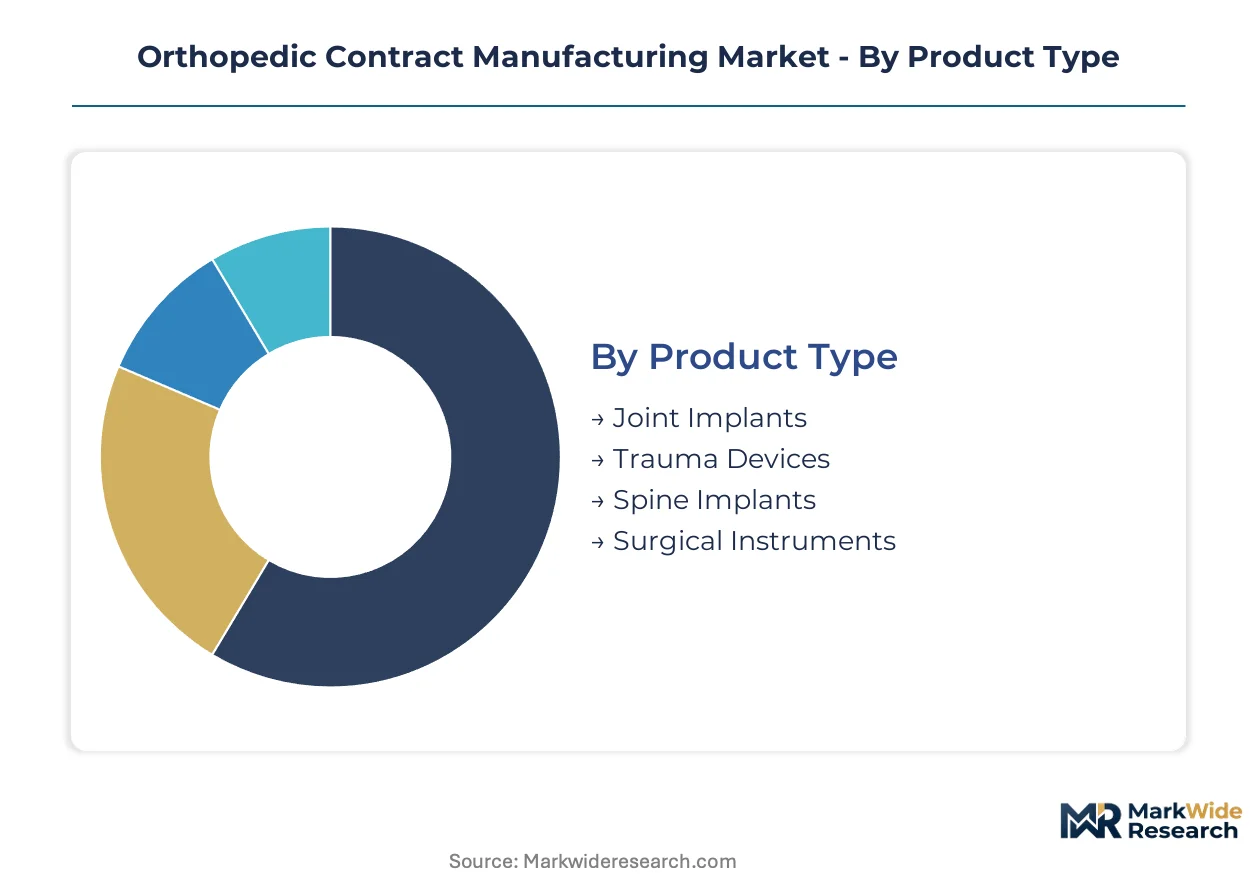
Orthopedic contract manufacturing segments diverge sharply in capital intensity and regulatory burden, with implantable devices demanding cleanroom forging infrastructure while instruments tolerate conventional machining. Understanding these tiered requirements shapes OEM sourcing strategies and contract manufacturer capability investments.
Product Type:
Substitution pressure from patient-specific additive manufacturing reshapes which implant categories retain outsourced forging demand versus those shifting toward in-house 3D printing operations.
- Joint Implants:Cobalt-chrome-molybdenum and titanium alloy constructs for hip and knee arthroplasty require ISO 5832-certified forging and sub-micron surface finishing for osseointegration. Demand concentrates in Switzerland's Solothurn precision cluster, where Tecomet and Viant Medical maintain dedicated capacity for OEMs seeking dual-continent regulatory equivalence through Swissmedic-FDA mutual recognition agreements.
- Spine Implants:Pedicle screws, interbody cages, and plating systems machined from Ti-6Al-4V ELI titanium demand ±25 micrometer tolerances and extensive fatigue testing. Procurement from academic medical centers and specialized spine hospitals in Germany and the United States drives specifications for complex geometries that resist commoditization despite additive manufacturing advances.
- Trauma Devices:Intramedullary nails and locking plates processed through closed-die forging and CNC finishing serve emergency surgery protocols requiring immediate availability.
- Surgical Instruments:Retractors, drills, and guide sleeves fabricated from surgical-grade stainless steel tolerate higher lot-to-lot variation than implants, enabling multi-purpose machine shop competition.
Joint implants retain volume leadership; spine implants hold the steepest expansion curve as minimally invasive procedures proliferate.
Technology:
Cost tier stratification separates capital-intensive additive systems from established subtractive methods, with mid-scale contract manufacturers facing equipment financing constraints that favor specialized technology pure-plays.
- 3D Printing:Laser powder bed fusion of porous titanium lattices enables patient-specific implant geometries with controlled pore sizes for bone ingrowth. FDA's updated 510(k) pathway accelerates qualification for hip and knee revision cases, concentrating demand among contract manufacturers with in-house metallurgical characterization and real-time process monitoring capabilities.
- CNC Machining:Multi-axis milling and Swiss-type turning of trauma plates and revision stems remains the volume backbone, with automated bar-feed systems compressing lot-changeover intervals for ambulatory surgical center procurement patterns. Bar-feed automation and palletized workholding distinguish competitive positioning in the United States and German markets.
- Injection Molding:PEEK polymer processing for spinal cages and instrument handles requires cleanroom ISO 14644 Class 8 environments and validated mold-flow analysis.
- Forging:Closed-die and isothermal forging of titanium alloy billets produces grain structures optimized for fatigue resistance in high-load joint applications.
CNC machining dominates current throughput; 3D printing gains share fastest as porous lattice designs achieve surgical adoption.
End User:
Customer type fragmentation between consolidated hospital systems and dispersed ambulatory networks forces contract manufacturers to bifurcate fulfillment models without duplicating quality systems.
- Hospitals:Integrated delivery networks and academic medical centers in the United States and Germany negotiate multi-year sole-source agreements for high-volume joint and spine implant categories, demanding validated sterile barrier packaging and electronic pedigree systems. These procurement structures favor contract manufacturers with MDSAP certification spanning FDA, Health Canada, and Japanese PMDA requirements.
- Clinics:Physician-owned surgery centers and specialized orthopedic clinics specify quick-turn instrument sets with compressed lead times, pulling volume toward contract manufacturers with Swiss-type lathe arrays and in-house sterilization. Paragon Medical captures this shift through dedicated quick-turn cells serving ASC-focused brands.
- Research Institutions:Preclinical and cadaveric studies require small-batch custom geometries with flexible specification tolerances.
- Rehabilitation Centers:Post-acute facilities drive demand for patient-specific bracing and external fixation accessories with shorter regulatory pathways.
Hospitals retain procurement volume leadership; clinics exhibit the most rapid demand acceleration as outpatient migration continues.
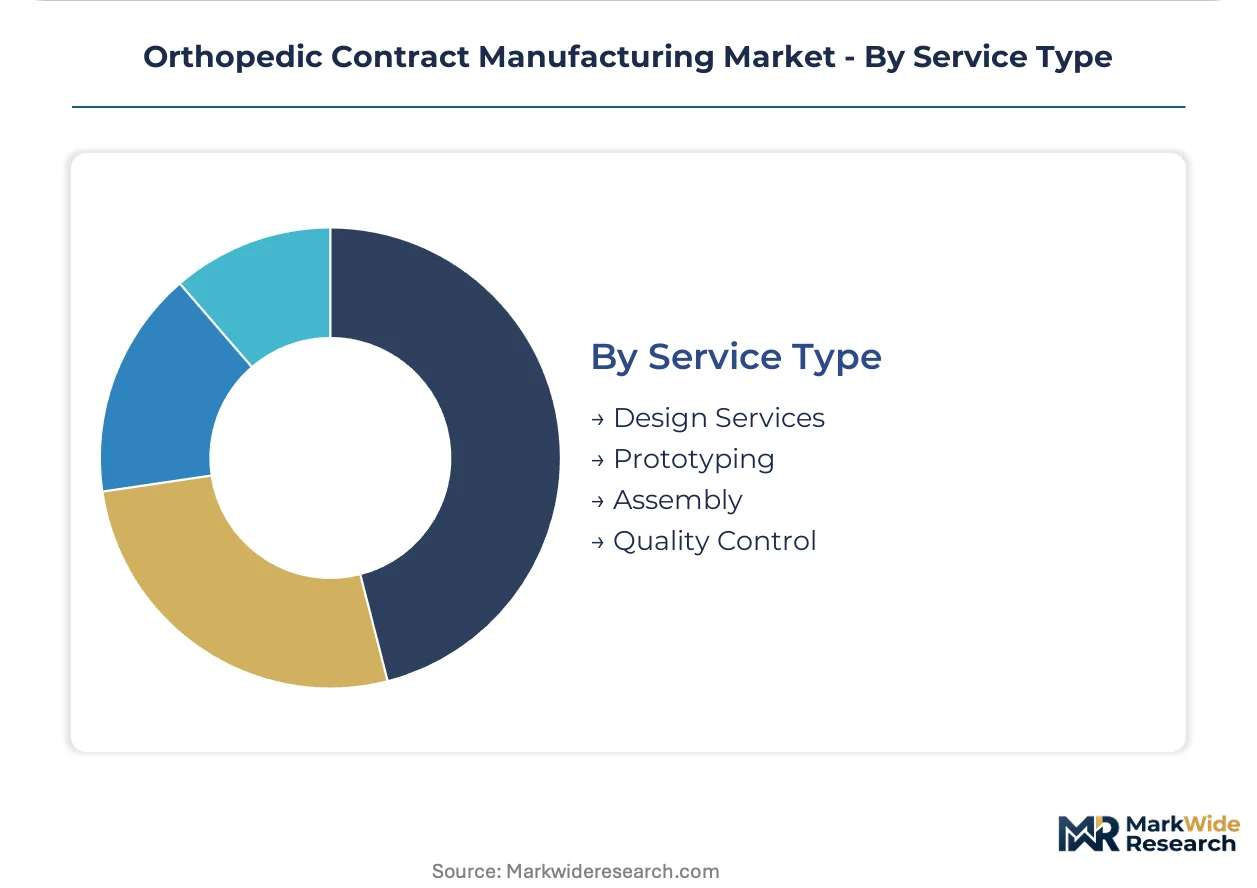
Service Type:
Margin concentration follows regulatory proximity, with quality control and sterilization services capturing premium pricing over commoditized assembly operations.
- Design Services:Collaborative development of implant geometries and surgical instruments requires ISO 13485 design control documentation and biocompatibility assessment capabilities. Orchid Orthopedic Solutions differentiates through integrated design-to-sterilization workflows that compress OEM time-to-market for complex spine portfolios.
- Prototyping:Rapid iteration of patient-specific implants and instrument concepts demands additive manufacturing capacity combined with dimensional inspection protocols. Swiss and German contract manufacturers leverage proximity to OEM engineering teams for iterative design refinement.
- Assembly:Component integration and kitting operations for modular implant systems require cleanroom environments and lot-level traceability systems.
- Quality Control:Coordinate measuring machine verification, surface roughness profiling, and sterility assurance testing represent the highest-margin service tier due to metrology talent scarcity and regulatory audit intensity.
Assembly commands the greatest labor hours; quality control delivers the steepest margin expansion trajectory as real-time release testing matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland exports precision-forged titanium implants to United States and German OEMs through Swissmedic-FDA mutual recognition agreements that compress dual-market qualification timelines.
United States
Ambulatory surgical centers now drive procurement volume for quick-turn instrument sets and sterilized implant kits. FDA's updated 510(k) pathway for additive-manufactured devices accelerates patient-specific lattice adoption. Minneapolis and Warsaw, Indiana anchor specialized machining and forging corridors serving domestic spine and trauma OEMs.
Germany
Tuttlingen's medical technology cluster concentrates CNC machining and polymer-molding capacity for European OEMs. EU MDR Annex I clinical-evidence mandates extend reliance on established contract manufacturers with notified-body relationships. Bavaria's precision-forging operations supply fatigue-tested cobalt-chrome components for revision joint portfolios.
Switzerland
Swissmedic maintains equivalence agreements with FDA and Health Canada that streamline North American market access. Solothurn's titanium-forging specialists serve dual-continent sourcing strategies for trauma plate and stem manufacturers. The precision-medical cluster attracts OEMs seeking ISO 5832-certified supply security.
India
CDSCO's streamlined medical device licensing and PLI scheme capital subsidies draw contract manufacturing investment for trauma implants. Domestic demand from tier-1 hospitals and export opportunities to Africa and Southeast Asia drive capacity expansion. Gujarat and Maharashtra host emerging machining corridors targeting extremities and external fixation devices.
Japan
PMDA's priority review designation for revision-joint solutions creates procurement pull for cobalt-chrome-molybdenum forging expertise. Aging demographics expand addressable surgical volumes for hip and knee arthroplasty. Osaka and Nagoya maintain concentrated metrology and finishing capabilities for sub-25-micrometer tolerance verification.
Orthopedic Contract Manufacturing Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory certification dimensions. The vendor base stratifies into three tiers: full-service integrators with sterile barrier packaging and direct-to-site logistics, technology pure-plays concentrated in additive manufacturing or Swiss-type micro-machining, and regional specialists serving single-continent OEMs with forged or molded components. Consolidation pressure favors M&A-driven capability stacking and geographic expansion into India's emerging orthopedic corridor.
Among United States-based fabricators, Norman Noble Inc. and Paragon Medical Inc. occupy positions within the precision-machining tier, while Orchid Orthopedic Solutions LLC exemplifies the vertically integrated service archetype spanning design through sterilization. These entities represent competitive positioning strategies that emphasize either specialized manufacturing depth or end-to-end workflow compression for ASC-focused brands.
| Leading Market Players |
|---|
| Avalign Technologies Inc. |
| Paragon Medical Inc. |
| Micron Products Inc. |
| CRETEX Medical Inc. |
| Norman Noble Inc. |
| Orchid Orthopedic Solutions LLC |
| UFP Technologies Inc. |
| Viant Medical Inc. |
| Tecomet Inc. |
| Others |
Value Chain & Pricing Dynamics
Eight-figure cleanroom forging investments create steep scale thresholds that concentrate pricing power among Swiss and German precision clusters while compressing margins for mid-scale contract manufacturers serving second-tier OEMs. Capacity utilization rates at ISO 14644 Class 7 facilities directly determine per-unit cost floors for Ti-6Al-4V ELI titanium implants, forcing ambulatory surgical center procurement teams toward suppliers with bar-feed automation and palletized workholding systems.
Pricing Analysis
Current-generation CNC machining of trauma plates and revision stems commands premium-mid-economy pricing differentiation against prior-generation manual Swiss-type turning and emerging laser-powder-bed-fusion lattice structures. Price differentiation hinges on ISO 13485 certification tier and MDSAP multi-market accreditation, with FDA-equivalent Swissmedic-certified suppliers capturing 15-20% premiums over single-continent qualified competitors. Pricing pressure stems from ASC procurement teams demanding compressed lot-changeover intervals without volume scale. Hospital integrated delivery networks exhibit lowest price sensitivity due to multi-year sole-source agreements, while physician-owned surgery centers drive hardest bargain terms.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Hamburg container terminals constrain just-in-time titanium sponge delivery to Solothurn and Tuttlingen forging corridors, with port congestion extending raw material lead windows. Supply concentrates in Switzerland, Germany, and the United States for precision-forged implants, drawing from Ukrainian and Kazakhstani sponge titanium feedstock and German cobalt-chrome-molybdenum billet producers. Single-source vulnerability concentrates in Ti-6Al-4V ELI titanium sponge supply. Distribution runs through direct-to-site sterile barrier logistics for ASC networks, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthopedic contract manufacturing is exiting a capital-expansion trough as EU MDR qualification backlogs clear and ASC procurement volumes normalize, with additive manufacturing adoption cyclically amplifying equipment financing demand.
For Market Incumbents: Compound Swiss machining expertise into adjacent micro-machining capabilities for robotic-assisted surgical instruments, defending against pure-play additive manufacturers encroaching on patient-specific lattice markets. Prioritize backward integration into titanium forging to secure Ti-6Al-4V ELI feedstock access against sponge supply volatility. Capture ASC channel control through in-house sterilization and direct-to-site logistics investments that displace distributor-dependent competitors. For New Entrants and Emerging Players: Quick-turn instrument sets for ambulatory surgical centers represent the most penetrable service gap, as incumbents optimize for high-volume joint implant production. Target India's emerging orthopedic corridor through CDSCO-licensed trauma and extremities manufacturing, leveraging PLI scheme capital subsidies. Establish go-to-market positioning through design-to-sterilization workflow compression that matches Orchid Orthopedic Solutions' integrated service model. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated contract manufacturers with captive sterilization and MDSAP certification spanning FDA, Health Canada, and Japanese PMDA requirements. Long-term viability over a 5-10 year window favors acquisition targets with additive manufacturing qualification capabilities and Swiss-type micro-machining arrays. Monitor FDA guidance on artificial-intelligence-enabled manufacturing controls as the inflection signal for automated inspection and real-time release testing adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Annex I Compliance Investment | Extends OEM reliance on established contract manufacturers with notified-body relationships and ISO 13485 certification. |
| Additive Manufacturing Qualification | FDA's updated 510(k) pathway accelerates patient-specific porous titanium lattice adoption for hip and knee revision cases. |
| Swiss-Type Micro-Machining Expansion | Captures ASC procurement shift toward quick-turn instrument sets with sub-10-micrometer positional tolerances. |
| Backward Integration into Titanium Forging | Secures Ti-6Al-4V ELI feedstock access against Ukrainian and Kazakhstani sponge supply concentration. |
| In-House Sterilization and Direct Logistics | Displaces distributor-dependent competitors in United States outpatient orthopedic segment through channel compression. |
Study Parameters
Cross-validation between primary interviews with orthopedic OEM procurement directors, contract manufacturing operations executives, and Swissmedic regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR notified-body designation records, and hospital GPO contract databases. Bottom-up capacity assessments at Solothurn and Tuttlingen precision clusters triangulate against top-down market sizing from trade flow data and medical device import statistics.
Sensitivity analysis across titanium sponge price volatility scenarios, EU MDR transition timelines, and ASC procurement penetration rates shapes the analytical framework over the projection horizon. Segmentation dimensions span product type, technology platform, end-user channel, and service tier, with CAGRs derived from equipment utilization curves and OEM outsourcing ratio trends. Forecast inputs incorporate CDSCO licensing velocity in India and PMDA priority review designation patterns for revision-joint solutions.
Forecasts assume regulatory continuity in FDA 21 CFR Part 820, EU MDR Annex I, and Swissmedic-FDA mutual recognition agreements; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
US Tendon Repair Market
Orthopedic Devices
India Orthopedic Braces and Supports Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
US Orthopedic Implants Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
France Neurology Devices Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Global Minimally Invasive Spine Surgery Market
Orthopedic Devices
Orthopedic Wire Pin Driver Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
North America Knee Cartilage Repair Market
Orthopedic Devices
Spinal Implants and Surgical Devices Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market