
 North America Knee Cartilage Repair Market | 2026-2036
North America Knee Cartilage Repair Market Size, Share, and Industry Trends Forecast 2026-2036
North America Knee Cartilage Repair Market Analytics
Canada is rewriting competitive dynamics in the North America Knee Cartilage Repair Market through expanded biologics manufacturing capacity and research infrastructure. Smith & Nephew leverages its integrated sports medicine portfolio to control distribution across major hospital networks. Zimmer Biomet anchors its position through specialized implant systems for focal cartilage defects. Stryker competes with advanced arthroscopy platforms that streamline surgical workflow in outpatient settings.
North America knee cartilage repair encompasses surgical and biological interventions that restore articular hyaline cartilage, including autologous chondrocyte implantation requiring two-stage procedures with cell culture expansion periods of four to six weeks. These therapies address full-thickness chondral lesions in the femoral condyle, patella, and tibial plateau to delay or prevent total knee arthroplasty. Cell-based therapies occupy the highest margin pool due to manufacturing complexity and proprietary cell processing requirements, while scaffolds lead procedure volume through simpler intraoperative application. Stem cell technology segments show accelerated development activity as investigators refine mesenchymal stem cell sourcing and differentiation protocols.
FDA regulates knee cartilage repair products through distinct pathways for devices, biologics, and combination products, creating compliance complexity that shapes development timelines and market access strategies. Health Canada and the FDA both enforce current good manufacturing practice standards for cell-based therapies, raising production costs but ensuring product consistency. Stakeholders must monitor evolving reimbursement decisions from CMS and private payers regarding Category III CPT codes for novel regenerative procedures, as coverage determination will dictate commercial viability faster than regulatory approval alone.
Market Dynamics
FDA's accelerated pathway for regenerative medicine advanced therapies is compressing development timelines for cell-based cartilage products while simultaneously fragmenting competitive positioning between device-dominant and biologic-native manufacturers.
Growth Catalysts
- CMS reimbursement expansion:Medicare coverage determinations for Category III CPT codes are unlocking outpatient procedure volume across ambulatory surgery centers in the United States.
- Mesenchymal stem cell sourcing:Improved adipose and bone marrow harvest protocols are reducing cell processing costs and expanding treatable patient populations.
- California-Texas orthopedic clusters:Concentrated specialist networks in these states are generating procedure volume density that supports dedicated cartilage repair service lines.
Market Restraints
- Biologics manufacturing complexity:Current good manufacturing practice compliance for autologous cell therapies requires specialized cleanroom infrastructure that limits production scale.
- Two-stage procedure burden:Autologous chondrocyte implantation's four-to-six-week cell culture period creates patient dropout and scheduling friction.
- Allograft substitution pressure:Osteochondral allografts offer single-stage alternatives for larger defects, capturing cases that might otherwise advance to cell-based therapy.
Strategic Opportunities
- Canadian biologics infrastructure:Expanded manufacturing capacity in Ontario and Quebec creates regional supply advantages for North American distribution.
- Point-of-care cell processing:Intraoperative concentration systems are collapsing the two-stage paradigm into single-visit procedures.
- Private payer coverage expansion:UnitedHealth and Aetna pilot programs for regenerative knee procedures are establishing precedents for broader reimbursement.
Industry Challenges
- Cartilage histology expertise gap:Pathologists skilled in hyaline cartilage grading are scarce, creating diagnostic bottlenecks for lesion classification.
- Bioreactor capital intensity:Automated cell expansion systems require seven-figure equipment investments that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Knee Cartilage Repair Market |
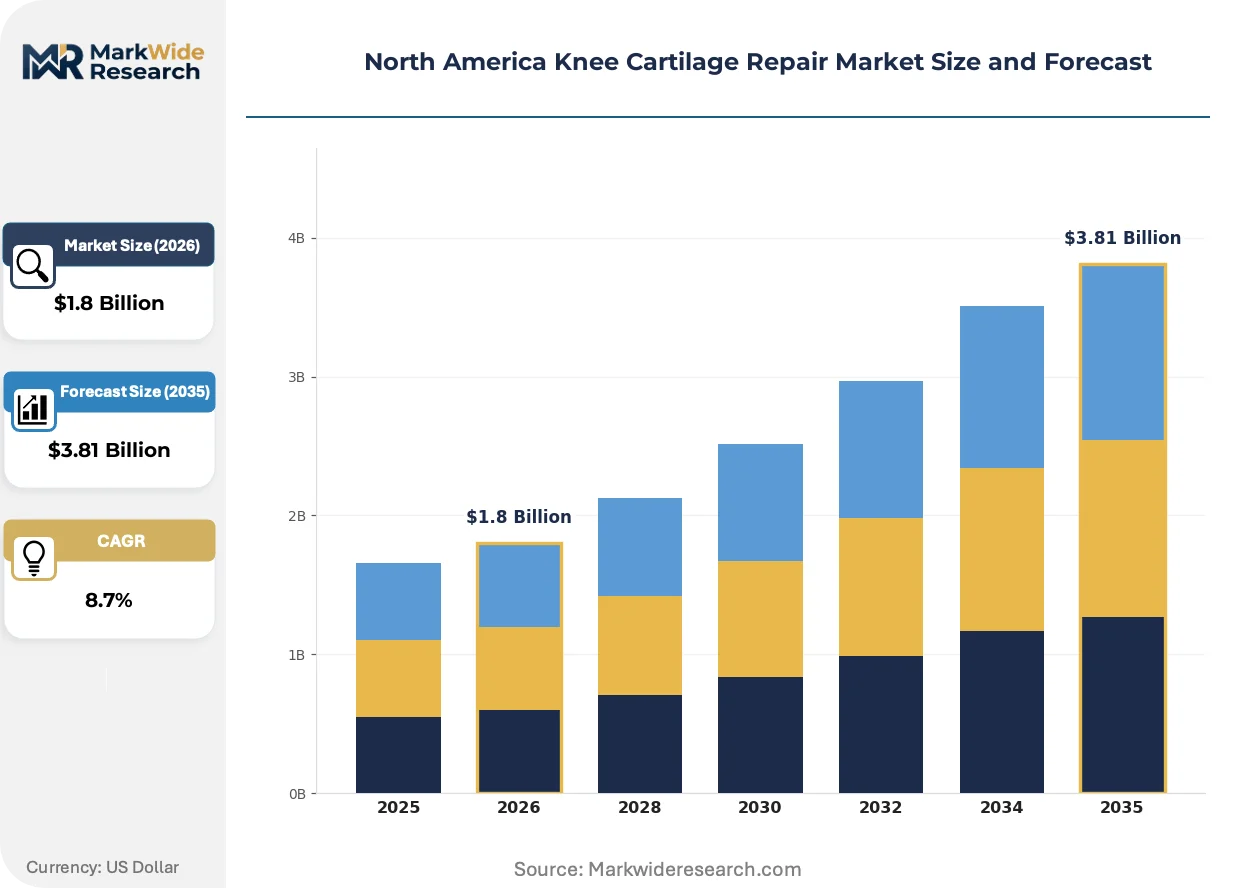
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell-Based Therapies, Injectable Gels, Scaffolds, Microfracture Systems End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Sports Medicine Facilities Procedure Type: Arthroscopy, Open Surgery, Regenerative Medicine, Biological Repair Technology: 3D Bioprinting, Stem Cell Technology, Nanotechnology, Tissue Engineering |
| Companies Covered | Smith & Nephew, Zimmer Biomet, Stryker, Vericel Corporation, Arthrex, Johnson & Johnson, Anika Therapeutics, Bioventus, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Knee Cartilage Repair Market Evolving Landscape
Biologic-device convergence is dismantling traditional category boundaries in knee cartilage repair, with hybrid scaffolds incorporating living cells and synthetic matrices simultaneously. This fusion is compressing legacy product lifecycles and forcing portfolio repositioning across the competitive landscape.
Three-dimensional bioprinting of hyaline-mimetic constructs is collapsing the functional gap between engineered tissue and native cartilage. Academic medical centers in Boston and San Diego are piloting patient-specific implants printed from MRI-derived defect geometries. The technology is collapsing the addressable market for off-the-shelf scaffolds by enabling lesion-matched geometry that manual trimming cannot replicate.
Health Canada's alignment with FDA quality standards for cell-based therapies is harmonizing North American compliance requirements. Dual-approval strategies now dominate manufacturer planning, with Toronto and Vancouver emerging as parallel clinical trial sites. Canadian regulators are moving faster than CMS on coverage determination, creating a policy laboratory that United States payers monitor for precedent.
Athletes and active seniors are demanding cartilage repair before joint replacement eligibility, compressing the traditional age-based treatment algorithm. Sports medicine clinics in Texas and Florida are responding with bundled cash-pay packages that bypass prior authorization delays. This consumer-direct channel is most visible in metropolitan markets with high deductible health plan penetration and established orthopedic brand recognition.
North America Knee Cartilage Repair Market Segmentation
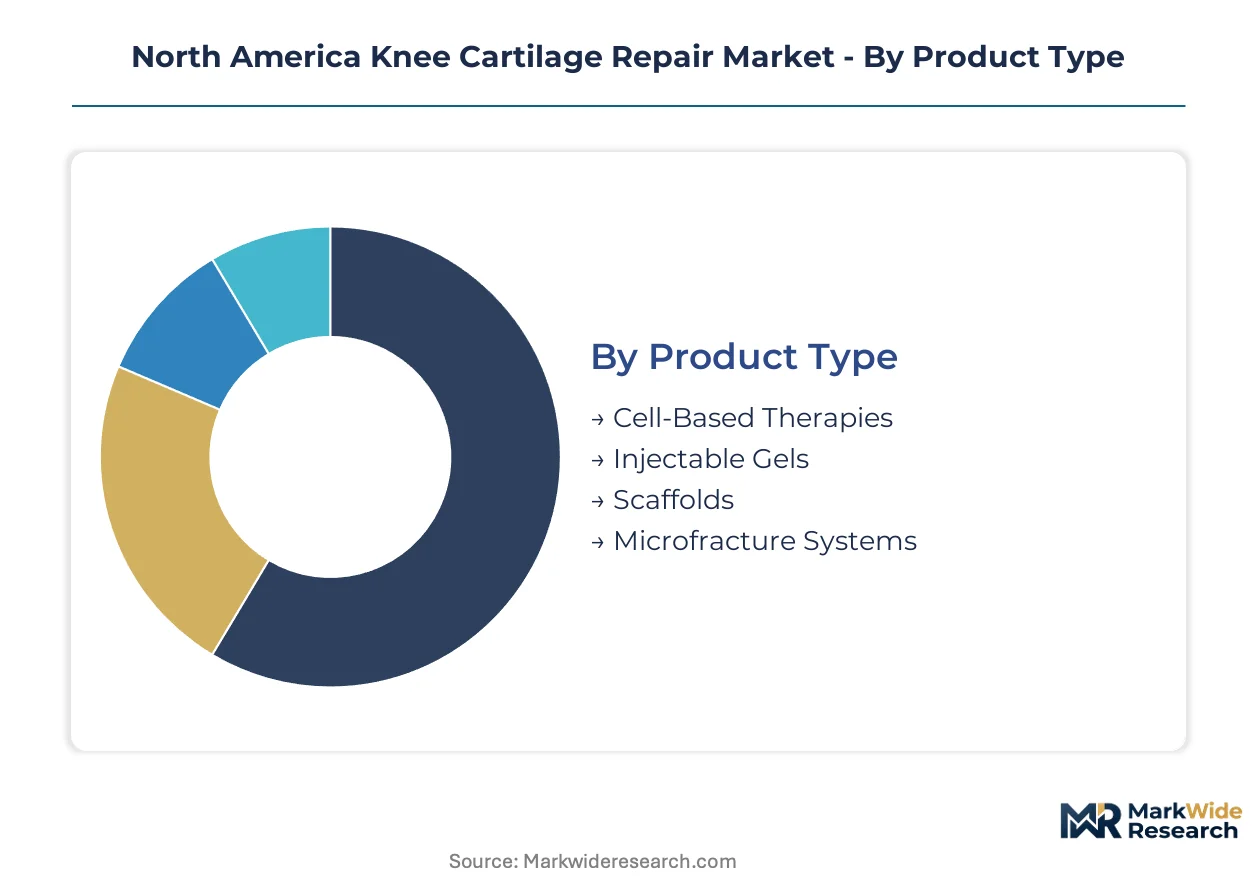
Knee cartilage repair markets fragment across four intersecting dimensions that determine reimbursement pathways, regulatory requirements, and clinical adoption curves. Each segmentation axis reveals distinct margin structures and competitive intensity patterns that shape portfolio strategy.
Product Type:
Cost tier determines manufacturing complexity and pricing power across the four product categories.
- Cell-Based Therapies:Autologous chondrocyte implantation and matrix-induced autologous chondrocyte implantation require FDA-compliant bioreactor processing and six-week culture periods. Demand concentrates in California and Texas orthopedic clusters where specialized cell processing labs support two-stage procedure workflows and CMS Category III code coverage unlocks outpatient volume.
- Scaffolds:Collagen-based and synthetic polymer matrices enable single-stage implantation with immediate mechanical stability. Sports medicine facilities across Florida are expanding scaffold adoption for focal condyle defects where patient compliance with extended rehabilitation protocols remains uncertain.
- Injectable Gels:Hyaluronic acid and platelet-rich plasma formulations target early-stage chondral lesions through office-based administration.
- Microfracture Systems:Awl and drill instruments for marrow stimulation remain the lowest-cost entry point despite inferior long-term outcomes versus biologic alternatives.
Cell-Based Therapies holds installed capacity. Scaffolds is rotating up the share rankings.
End User:
Application setting dictates capital equipment requirements and reimbursement negotiation leverage.
- Sports Medicine Facilities:Dedicated orthopedic surgery centers in metropolitan markets bundle cartilage repair with physical therapy and imaging. Texas and Florida facilities are pioneering cash-pay packages that bypass prior authorization delays for active patients seeking joint preservation before arthroplasty eligibility.
- Hospitals:Academic medical centers in Boston and San Diego anchor clinical trial recruitment for novel biologic-device combinations while maintaining high-volume service lines for complex multi-compartment lesions.
- Orthopedic Clinics:Private practice networks concentrate diagnostic arthroscopy and patient selection for referral to specialized surgical centers.
- Rehabilitation Centers:Post-operative care facilities manage the twelve-to-twenty-four-week return-to-activity protocols that determine functional outcomes and revision rates.
Sports Medicine Facilities commands procedure volume density. Orthopedic Clinics is climbing the fastest as gatekeeper influence expands.
Procedure Type:
Volume distribution reflects the tension between minimally invasive adoption and biological sophistication.
- Arthroscopy:Minimally invasive joint access enables diagnostic grading and simultaneous treatment of focal lesions. California surgical centers are deploying advanced visualization systems that reduce operative time and support same-day discharge under CMS outpatient reimbursement.
- Regenerative Medicine:Cell-based and stem cell procedures occupy the highest reimbursement tier but require specialized training and infrastructure investment that limits geographic penetration.
- Open Surgery:Osteochondral autograft transfer and allograft implantation persist for large uncontained defects where arthroscopic access proves inadequate.
- Biological Repair:Marrow stimulation and scaffold implantation bridge the gap between mechanical debridement and cell-based restoration.
Arthroscopy holds installed capacity. Regenerative Medicine is gaining share fastest as biologics manufacturing scales.
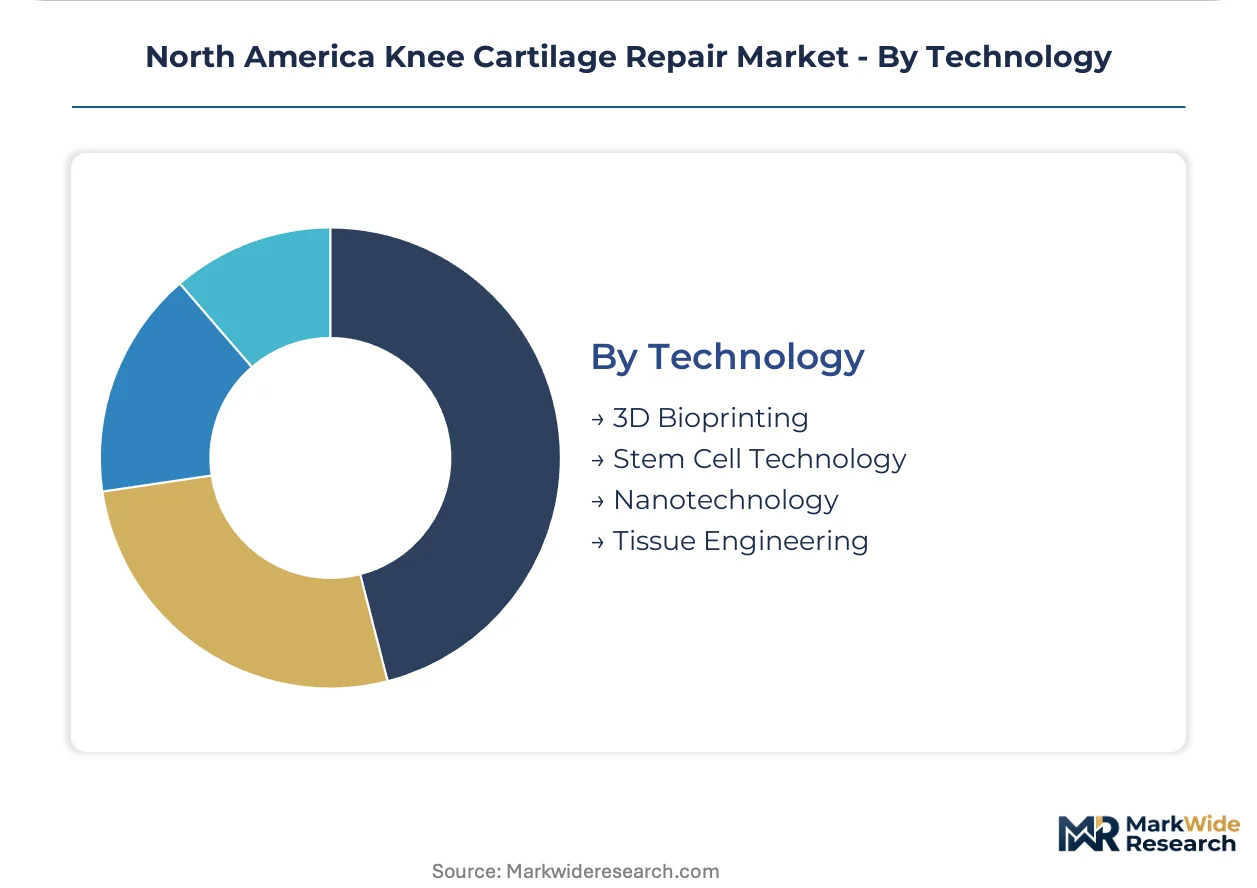
Technology:
Customer type stratification separates research-stage platforms from commercialized therapeutic modalities.
- Stem Cell Technology:Mesenchymal stem cell sourcing from adipose tissue and bone marrow is collapsing processing costs and enabling point-of-care concentration systems. Canadian manufacturing infrastructure in Ontario is expanding to supply North American distribution networks with standardized cell products.
- 3D Bioprinting:Patient-specific construct fabrication from MRI-derived geometries is piloting at academic centers with seven-figure capital requirements that strain mid-tier manufacturer balance sheets.
- Tissue Engineering:Bioreactor-based autologous cell expansion remains constrained by current good manufacturing practice compliance costs and pathologist expertise gaps in hyaline cartilage grading.
- Nanotechnology:Nanofiber scaffolds and growth factor delivery systems are advancing through preclinical development with limited commercial penetration.
Stem Cell Technology holds installed capacity. 3D Bioprinting is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulates the dominant United States market through distinct pathways for devices, biologics, and combination products. Health Canada enforces parallel quality standards that harmonize North American compliance requirements. Mexico's national pharmaceutical regulator oversees emerging demand for joint preservation procedures.
United States
California and Texas orthopedic clusters generate the highest procedure volume density for cartilage repair service lines. CMS reimbursement determinations for Category III CPT codes unlock outpatient volume across ambulatory surgery centers. Academic medical centers in Boston and San Diego anchor clinical trial recruitment for novel biologic-device combinations.
Canada
Ontario and Quebec manufacturing infrastructure expands regional supply advantages for cell-based therapy distribution. Health Canada alignment with FDA quality standards accelerates dual-approval strategies for regenerative medicine products. Toronto and Vancouver emerge as parallel clinical trial sites that United States payers monitor for coverage precedent.
Mexico
Border state medical tourism corridors attract United States patients seeking cost-advantaged cartilage procedures. The national pharmaceutical regulator oversees compliance for imported biologic-device combinations. Monterrey and Tijuana surgical centers develop specialized sports medicine service lines for cross-border patient flows.
North America Knee Cartilage Repair Market Competitive Landscape
Integrated device-biologic conglomerates and specialized cell therapy developers split the market between scale-driven distribution control and innovation-focused niche positioning. The vendor base concentrates around three strategic archetypes: diversified orthopedic multinationals with sports medicine portfolios, dedicated regenerative medicine firms with proprietary cell processing capabilities, and arthroscopy equipment specialists with workflow optimization platforms. Dominant competitive moves include point-of-care cell processing technology licensing and Canadian biologics manufacturing capacity expansion.
Within the diversified multinational tier, Smith & Nephew and Zimmer Biomet occupy positions that exemplify integrated sports medicine portfolio leverage. Stryker represents the arthroscopy equipment specialist archetype with workflow-focused platform positioning. Vericel Corporation anchors the dedicated regenerative medicine tier as a cell therapy-native developer.
| Leading Market Players |
|---|
| Smith & Nephew |
| Zimmer Biomet |
| Stryker |
| Vericel Corporation |
| Arthrex |
| Johnson & Johnson |
| Anika Therapeutics |
| Bioventus |
| CONMED Corporation |
| Others |
Value Network & Pricing Analysis
Undercapacity in Canadian biologics cleanroom infrastructure is compressing cell therapy production economics and forcing manufacturers toward premium pricing postures for autologous chondrocyte implantation. This utilization squeeze simultaneously elevates input costs for United States distributors and creates margin capture opportunities for Ontario-based contract manufacturers serving North American demand.
Pricing Analysis
California-Texas price spreads for cell-based cartilage repair exceed scaffold alternatives by triple-digit percentage points, reflecting bioreactor processing premiums and FDA compliance overhead. Pricing stratifies across premium cell therapies, standard scaffold systems, and economy microfracture instruments, with differentiation anchored in hyaline cartilage grading certification and outpatient versus inpatient reimbursement pathways. Cost compression in scaffold tiers is intensifying as collagen suppliers consolidate, while cell therapy margins remain protected by pathologist expertise scarcity. Sports medicine facilities exhibit lowest price sensitivity due to bundled cash-pay packaging, whereas hospital systems face acute budget pressure from Category III CPT code uncertainty.
Supply Chain Analysis
Tariff exposure between United States and Canadian biologics trade dominates supply chain risk calculus for cell therapy manufacturers navigating cross-border distribution. Manufacturing concentrates in Ontario, Quebec, and Massachusetts, with raw material dependencies on bovine collagen sourcing, synthetic polymer feedstocks, and proprietary cell culture media formulations. Single-source vulnerability in bioreactor equipment from German and Japanese suppliers creates procurement bottlenecks for mid-tier developers. Distribution runs through specialized cold-chain logistics networks serving orthopedic clusters in California, Texas, and Florida, with hospital system GPOs consolidating purchasing leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of pathologists trained in hyaline cartilage histology grading is constraining diagnostic throughput and creating bottlenecks that limit addressable procedure volume across North American orthopedic networks.
For Market Incumbents: Harden cell processing lab capacity in Ontario and Quebec to capture Canadian manufacturing advantages before Health Canada approval pathways mature. Consolidate distribution control through exclusive hospital system partnerships that lock out emerging scaffold competitors, while investing in point-of-care cell concentration technology to collapse the two-stage procedure burden threatening patient retention. For New Entrants and Emerging Players: Mexico's border state medical tourism corridors represent the most penetrable geographic white space, with Monterrey and Tijuana surgical centers seeking cost-advantaged biologic-device combinations for United States patient flows. Target cash-pay sports medicine clinics in Florida metropolitan markets with high deductible health plan penetration, using direct-to-consumer bundled pricing that bypasses prior authorization friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cell therapy-native developers with proprietary bioreactor platforms and established CMS Category III code coverage. Long-term viability hinges on reimbursement precedent durability rather than regulatory approval alone, making Health Canada coverage determination velocity the critical signal to watch for United States payer behavior alignment.| Strategic Initiative | Industry Significance |
|---|---|
| Canadian Biologics Manufacturing Scale-Up | Ontario cleanroom expansion captures North American cell therapy supply advantages under Health Canada-FDA harmonized standards. |
| Point-of-Care Cell Processing Development | Intraoperative concentration systems collapse two-stage ACI workflows into single-visit procedures, reducing patient dropout. |
| CMS Reimbursement Strategy Advancement | Category III CPT code coverage determination unlocks outpatient volume across ambulatory surgery centers in Texas and Florida. |
| 3D Bioprinting Platform Integration | Patient-specific construct fabrication from MRI geometries enables lesion-matched implants that manual trimming cannot replicate. |
| Hospital System Partnership Consolidation | Exclusive GPO contracts with California and Texas orthopedic clusters secure procedure volume density for dedicated service lines. |
Research Methodology
A standing panel of orthopedic surgeons, cell processing lab directors, hospital purchasing committee members, and CMS reimbursement specialists provided ongoing calibration across the research program. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, Health Canada medical device licenses, hospital procurement databases, and GPO contract disclosures. Bottom-up procedure volume estimates from state-level ambulatory surgery center data were triangulated against top-down manufacturer revenue segmentation.
Scenario-bracketing anchored the analytical framework, with volume and value outputs reflecting conservative, baseline, and accelerated adoption trajectories across the projection horizon. Segmentation dimensions modeled include product type tier, end-user facility category, procedure approach, and technology maturity stage, with CAGRs derived from historical reimbursement pattern analysis and biologics manufacturing capacity expansion schedules. Stem cell sourcing cost curves and 3D bioprinting capital intensity thresholds served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive point-of-care processing investment by arthroscopy equipment specialists would shift outcomes toward single-stage procedure dominance. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Limb Salvage Systems Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Non-Operative Spine Care Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Orthopedic Trauma Devices Market
Orthopedic Devices
Orthopedic Braces Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Humeral Implant Market
Orthopedic Devices
Spinal Devices Market