
 France Neurology Devices Market | 2026-2036
France Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Neurology Devices Market Foresight
The EU Medical Device Regulation is pivoting French hospital procurement toward higher-assay-class neurology devices with reinforced clinical evidence requirements. Medtronic PLC dominates the neurostimulation segment through its deep entrenchment in French epilepsy centers. Abbott Laboratories anchors the brain-monitoring portfolio with proprietary wireless intracranial platforms. Boston Scientific Corporation differentiates via its specialized deep-brain stimulation electrode arrays designed for movement disorders.
France neurology devices comprise electromechanical and software-integrated instruments engineered to diagnose, monitor, or therapeutically modulate the central and peripheral nervous systems, typically operating within signal frequencies of 0.5–100 Hz for EEG acquisition and output currents below 25 mA for transcranial magnetic stimulation protocols. These systems serve primarily to enable precise neural pathway mapping, real-time seizure detection, and targeted neuroelectrical intervention in clinical settings. Neuroimaging devices lead product-type value pools due to their capital intensity and recurring contrast-agent revenues, while nerve stimulators represent the fastest-expanding category as ambulatory vagus-nerve and spinal-cord systems displace inpatient pharmacological management. Epilepsy management commands the largest application share, though neurodegenerative disorder platforms are gaining structural importance as French geriatric demographics expand and reimbursement pathways for closed-loop DBS tighten.
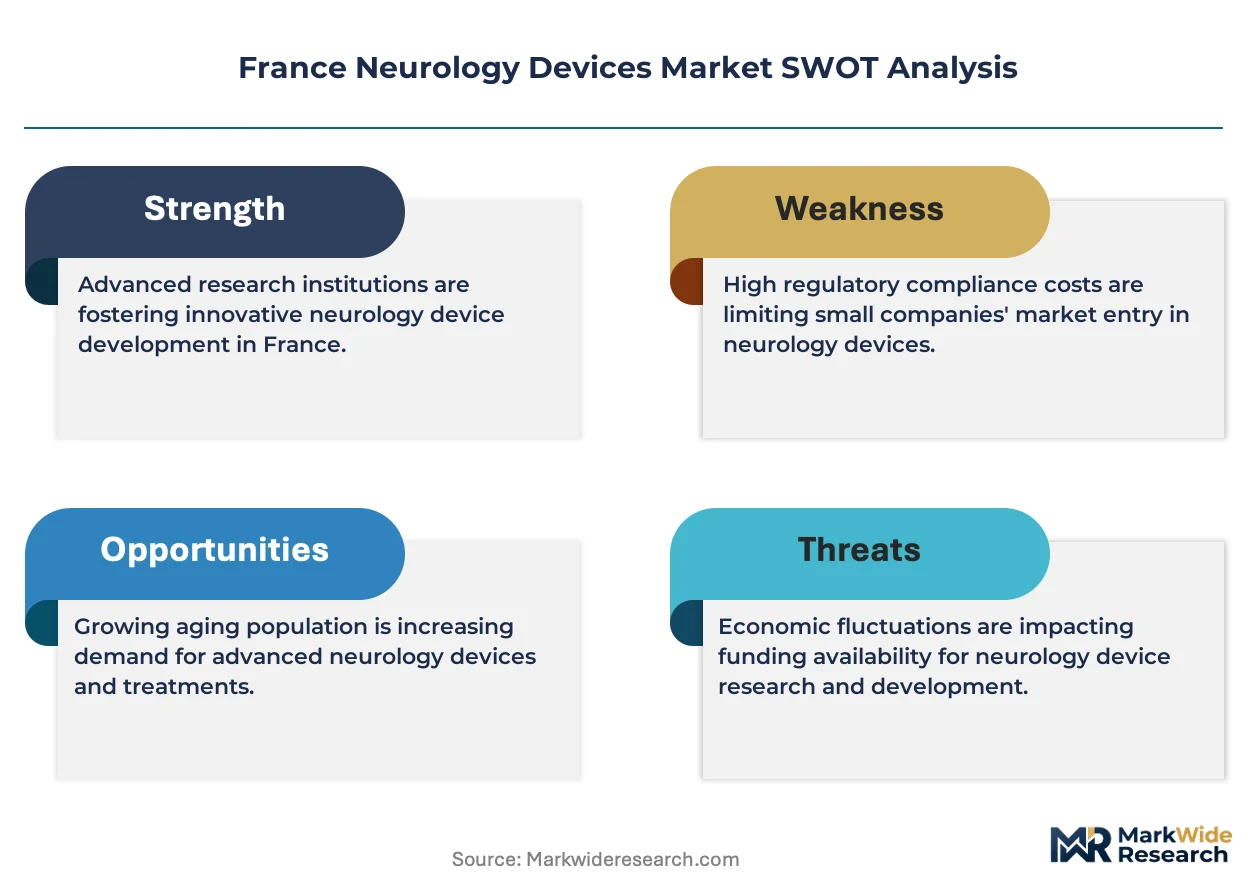
ANSM enforces CE marking under MDR alongside post-market surveillance mandates that compel manufacturers to maintain French-language risk-management files and localized vigilance representatives, effectively raising barriers for non-EU suppliers. The French national health technology assessment body, HAS, conditions reimbursement listing for novel neurology devices upon demonstrated comparative efficacy against existing standard-of-care protocols, directly shaping R&D investment timelines. Stakeholders must monitor the convergence of AI-enabled diagnostic algorithms with MDR software-as-a-medical-device classifications, as this interface will determine which technology suppliers retain market access versus face forced partnership structures with established device incumbents.
Market Dynamics
ANSM's strengthened vigilance requirements for implantable neural devices are compressing procurement timelines while forcing hospitals to consolidate supplier relationships around MDR-certified portfolios.
Growth Catalysts
- Île-de-France neurosurgical concentration:Parisian university hospitals are expanding dedicated neurointerventional suites, creating concentrated demand pull for advanced neuromonitoring platforms and driving regional adoption curves.
- MDR clinical evidence requirements:The EU Medical Device Regulation's reinforced post-market surveillance mandates are filtering out lower-assay-class competitors, elevating procurement standards toward premium-tier neurology devices with robust risk-management files.
- Geriatric demographic expansion:France's aging population is amplifying structural demand for neurodegenerative disorder management platforms, particularly closed-loop deep-brain stimulation systems targeting Parkinson's and related movement disorders.
Market Restraints
- Capital intensity barriers:Neuroimaging suites require substantial upfront investment in MRI-compatible infrastructure and shielded installation environments, limiting penetration beyond major academic medical centers.
- Localized vigilance representative mandates:ANSM's requirement for French-based post-market surveillance personnel creates fixed cost burdens that disproportionately constrain mid-tier device manufacturers without established EU operational footprints.
- Pharmacological substitution threat:Next-generation antiepileptic drug formulations continue to capture first-line therapy positioning, delaying neurostimulator implantation timelines in newly diagnosed patient cohorts.
Strategic Opportunities
- Auvergne-Rhône-Alpes regional expansion:Lyon and Grenoble's emerging neurotechnology clusters present underpenetrated demand for ambulatory vagus-nerve stimulation systems outside the saturated Paris basin.
- AI-enabled diagnostic convergence:Machine-learning seizure detection algorithms interfacing with MDR software-as-a-medical-device classifications are opening partnership pathways between algorithm developers and established hardware incumbents.
- HAS comparative efficacy pathways:The French national health technology assessment body's reimbursement conditioning on demonstrated standard-of-care superiority creates first-mover advantages for manufacturers investing in head-to-head clinical trials.
Industry Challenges
- Neurointerventional specialist scarcity:France faces acute shortages of trained neurointerventional radiologists capable of operating advanced endovascular neurology devices, constraining deployment velocity regardless of capital availability.
- Legacy system integration friction:New wireless intracranial monitoring platforms must interface with heterogeneous hospital IT architectures and proprietary EEG archival systems, extending implementation timelines and elevating total cost of ownership.
- CE-MDR certification timeline compression:The transition from MDD to MDR notified body capacity constraints has elongated technical file review periods, delaying market access for novel neurology device submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Neurology Devices Market |
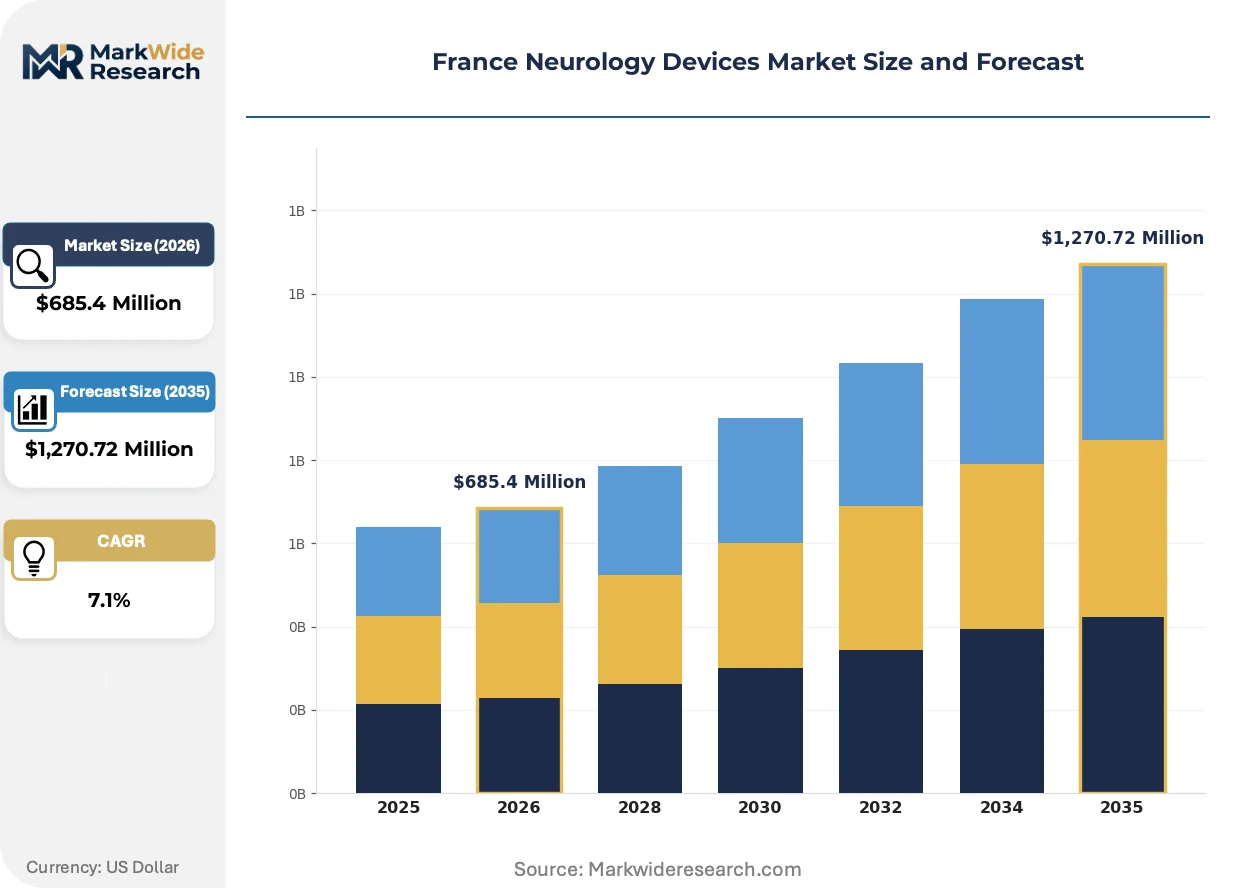
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,270.72 Million |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EEG Machines, Nerve Stimulators, Neuroimaging Devices, Brain-Monitoring Systems Application: Epilepsy Management, Stroke Rehabilitation, Neurodegenerative Disorders, Sleep Disorders End User: Neurology Clinics, Diagnostic Laboratories, Research Centers, Rehabilitation Facilities Technology: Magnetoencephalography, Functional MRI, Transcranial Magnetic Stimulation, Electromyography |
| Companies Covered | Abbott Laboratories, Johnson and Johnson, Medtronic PLC, Danaher Corporation, F. Hoffmann-La Roche Ltd., Boston Scientific Corporation, B. Braun SE, Smith & Nephew, Stryker Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Neurology Devices Market Shifts & Advancements
Neural interface technologies are converging with embedded computing architectures, reshaping how French clinical centers capture, process, and act upon neurophysiological data streams in real time.
Closed-loop neurostimulation systems are absorbing predictive algorithm capabilities that anticipate seizure onset before clinical manifestation. French epilepsy centers in Paris and Marseille are piloting these platforms at accelerated cadences compared to peripheral regions. The technology is absorbing capital allocation from conventional open-loop stimulators, compressing the addressable market for first-generation devices.
MDR Article 10 clinical evidence requirements are mandating prospective post-market clinical follow-up studies for Class III implantable neural devices. Manufacturers must now maintain active French patient registries with minimum five-year follow-up protocols. Deep-brain stimulation electrode arrays and responsive neurostimulators face the steepest compliance burden, with several suppliers restructuring EU commercial organizations to accommodate expanded medical affairs staffing.
French hospital purchasing consortia are consolidating procurement authority around outcome-guarantee frameworks that tie device reimbursement to demonstrated patient functional improvement. The Groupement des Hôpitaux de l'Assistance Publique in Paris and regional hospital groups in Provence-Alpes-Côte d'Azur are piloting these models for spinal cord stimulation systems. This behavioral shift is most visible in movement disorder applications, where payers demand objective motor score improvements as a condition of continued device support.
France Neurology Devices Market Segmentation
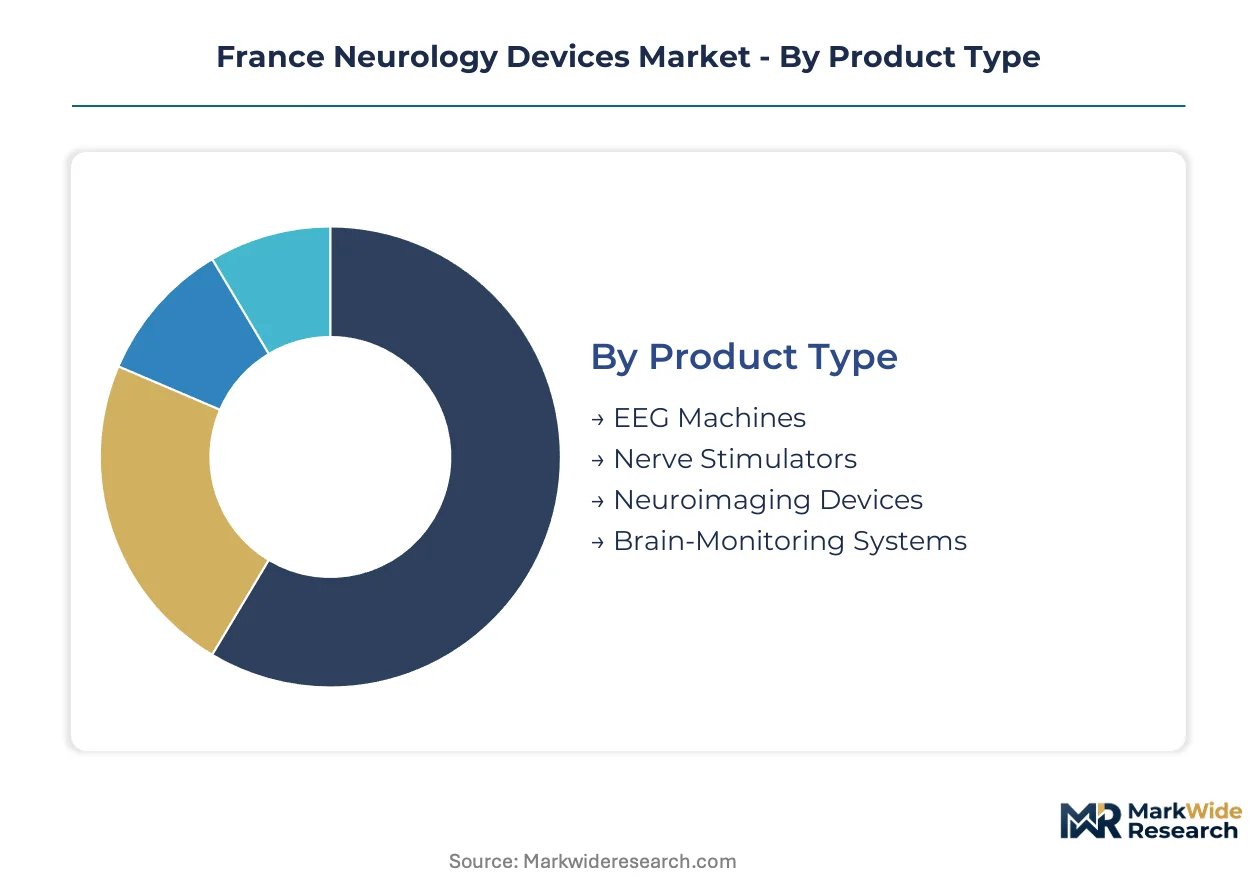
Neurology device segmentation in France reveals distinct procurement patterns across product categories. Hospital purchasing consortia weight capital intensity against clinical workflow integration when allocating budgets across these dimensions.
Product Type:
Standalone capital equipment dominates hospital procurement cycles, while embedded monitoring modules integrate into broader surgical platforms.
- Neuroimaging Devices:MRI and CT systems with neurology-optimized sequences require shielded installation environments and recurring contrast-agent supply contracts. Île-de-France university hospitals concentrate demand for 3T and 7T research-grade scanners. ANSM's MDR vigilance mandates elevate procurement scrutiny toward manufacturers with established French post-market surveillance infrastructure.
- Nerve Stimulators:Implantable pulse generators and lead systems for vagus nerve and spinal cord modulation operate at sub-milliampere output ranges with wireless telemetry capabilities. Ambulatory system demand is expanding fastest outside Paris as regional centers build neurostimulation programs. HAS reimbursement conditioning on demonstrated functional outcomes shapes manufacturer clinical trial investment.
- EEG Machines:Multi-channel electroencephalography platforms with 0.5–100 Hz acquisition bandwidth serve diagnostic and intraoperative monitoring roles.
- Brain-Monitoring Systems:Wireless intracranial pressure and electrocorticography platforms interface with critical care informatics architectures.
Neuroimaging devices lead volumes today; nerve stimulators are gaining share fastest.
Application:
Reimbursement pathways diverge sharply between acute intervention protocols and chronic disease management platforms.
- Epilepsy Management:Surgical resection planning, responsive neurostimulation, and chronic vagus nerve therapy constitute the most mature reimbursement category. Parisian centers concentrate presurgical evaluation volume while regional hospitals expand implantation capacity. Pharmacological substitution pressures from next-generation antiepileptics constrain first-line neurostimulator adoption timelines.
- Neurodegenerative Disorders:Closed-loop deep brain stimulation for Parkinson's disease and related movement disorders demands specialized neurosurgical infrastructure. HAS comparative efficacy requirements favor manufacturers with head-to-head trial data against standard-of-care protocols. France's geriatric demographic expansion structurally amplifies addressable patient cohorts.
- Stroke Rehabilitation:Transcranial magnetic stimulation and robot-assisted neurorecovery platforms target motor function restoration.
- Sleep Disorders:Polysomnography systems and hypoglossal nerve stimulation address obstructive sleep apnea and narcolepsy diagnoses.
Epilepsy management anchors current revenue; neurodegenerative disorder platforms are climbing the fastest.
End User:
Procurement authority concentrates in purchasing consortia that aggregate demand across facility types.
- Neurology Clinics:Private practice and hospital-affiliated outpatient centers drive ambulatory monitoring device demand. Lyon and Marseille clusters are expanding fastest as Paris saturation limits new entrant opportunity.
- Diagnostic Laboratories:Centralized neurophysiology testing facilities concentrate EEG and EMG interpretation volume.
- Research Centers:INSERM-affiliated institutions and university hospitals prioritize investigational device access.
- Rehabilitation Facilities:Post-acute and long-term care settings adopt lower-cost neurostimulation and monitoring platforms.
Neurology clinics generate the highest absolute volumes; rehabilitation facilities are expanding most quickly.
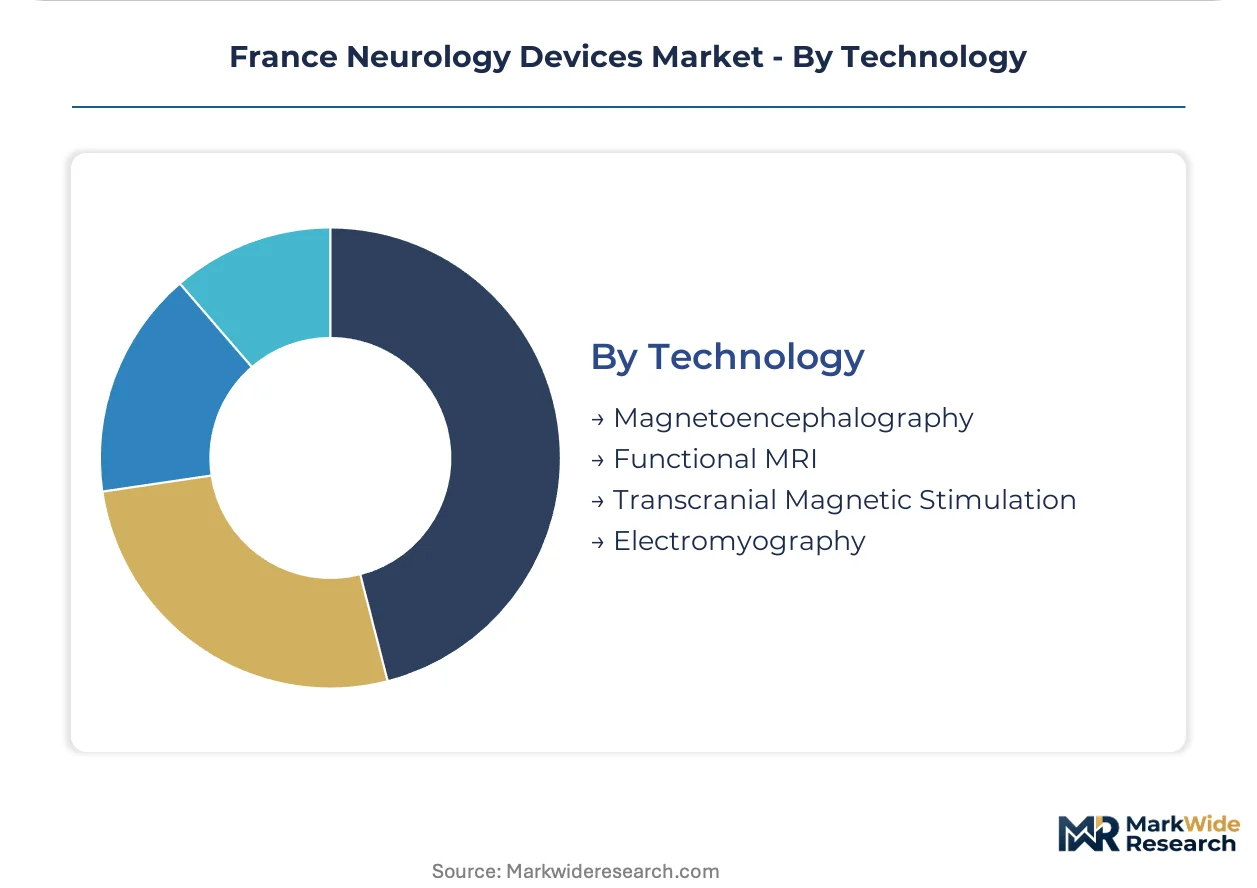
Technology:
Regulatory classification complexity varies significantly across measurement modalities.
- Functional MRI:Blood-oxygen-level-dependent imaging with real-time neurofeedback capabilities requires substantial capital deployment and specialized radiologist training. Île-de-France research hospitals concentrate advanced applications.
- Transcranial Magnetic Stimulation:Non-invasive neuromodulation with 1–2 Tesla pulse output treats depression and movement disorders in outpatient settings. HAS reimbursement expansion for psychiatric indications is broadening addressable demand.
- Magnetoencephalography:Superconducting quantum interference device arrays detect femtotesla-scale magnetic fields for epileptic focus localization.
- Electromyography:Needle and surface electrode systems assess peripheral nerve and muscle function.
Functional MRI leads installed base volumes; transcranial magnetic stimulation shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's neurology device industry traces its institutional foundations to the post-war expansion of Parisian university hospitals, where neurosurgical specialization first achieved critical mass. Regional demand patterns now reflect this historical concentration, with procurement authority fragmented across competing hospital consortia.
Île-de-France
Parisian neurosurgical centers drive national adoption curves for advanced neuromonitoring platforms. ANSM's MDR vigilance mandates filter procurement toward manufacturers with established French post-market surveillance infrastructure. The Assistance Publique-Hôpitaux de Paris consortium concentrates demand for 7T research-grade MRI and closed-loop deep-brain stimulation systems.
Auvergne-Rhône-Alpes
Lyon and Grenoble's emerging neurotechnology clusters present underpenetrated demand for ambulatory vagus-nerve stimulation outside the saturated Paris basin. HAS reimbursement conditioning on demonstrated functional outcomes shapes manufacturer clinical trial investment toward regional expansion. The Hospices Civils de Lyon group is consolidating neurointerventional capacity across multiple sites.
Provence-Alpes-Côte d'Azur
Marseille's epilepsy centers pilot predictive seizure-detection algorithms at accelerated cadences compared to peripheral regions. Regional hospital groups are piloting outcome-guarantee frameworks that tie device reimbursement to demonstrated patient functional improvement. The Aix-Marseille University hospital network anchors neurodegenerative disorder management capacity.
Hauts-de-France
Lille's university hospital system builds neurostimulation programs targeting movement disorders amid geriatric demographic expansion. ANSM's requirement for French-based post-market surveillance personnel creates fixed cost burdens that constrain mid-tier manufacturers. The CHU de Lille consortium aggregates procurement authority for spinal cord stimulation systems.
France Neurology Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the French neurology device market. The vendor base fragments across three tiers: diversified multinationals with full MDR certification, regional specialists with targeted product portfolios, and emerging algorithm developers seeking hardware partnerships. Consolidation pressure intensifies as hospital purchasing consortia aggregate demand around outcome-guarantee frameworks. Two dominant competitive moves are reshaping positioning: M&A activity targeting MDR-ready portfolios and strategic partnerships between AI developers and established device incumbents.
Among diversified healthcare conglomerates, Abbott Laboratories, Medtronic PLC, and Boston Scientific Corporation exemplify the premium-tier archetype. These entities anchor competitive dynamics through entrenched relationships with French epilepsy and movement disorder centers. Abbott Laboratories occupies a position representing wireless intracranial monitoring capabilities. Medtronic PLC exemplifies deep entrenchment in neurostimulation segments. Boston Scientific Corporation sits within the specialized electrode array tier. Mid-tier European manufacturers and algorithm developers compete for partnership access rather than direct procurement contracts.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Johnson and Johnson |
| Medtronic PLC |
| Danaher Corporation |
| F. Hoffmann-La Roche Ltd. |
| Boston Scientific Corporation |
| B. Braun SE |
| Smith & Nephew |
| Stryker Corporation |
| Others |
Supply & Pricing Matrix
HAS outcome-guarantee frameworks compel French hospital purchasing consortia to consolidate procurement around MDR-certified manufacturers with proven post-market surveillance infrastructure, squeezing mid-tier suppliers and compressing margins for non-premium device tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates French neurology device procurement. Premium tiers command substantial markups through CE-MDR certification badges and bundled French-language vigilance support, while standard tiers compete on HAS reimbursement pathway speed. Cost compression in economy-tier neuroimaging equipment is intensifying because ANSM's localized representative mandates impose fixed compliance burdens regardless of shipment volume. Academic medical centers in Paris exhibit lowest price sensitivity due to research funding offsets, whereas regional hospital groups in Hauts-de-France face acute budget constraints.
Supply Chain Analysis
Reverse-logistics flows for implantable neural devices center on specialized remanufacturing facilities in Germany and Switzerland that handle pulse generator refurbishment and lead extraction protocols. Manufacturing concentration in Ireland, Germany, and the United States anchors European device supply, with critical dependencies on rare-earth magnet arrays from China and biocompatible polymer feedstocks from Belgium. Single-source vulnerability in superconducting quantum interference device components for magnetoencephalography systems presents structural risk. Distribution runs through GPO-aggregated contracts managed by French hospital purchasing consortia rather than direct manufacturer-to-facility shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's neurology device market offers margin expansion potential through MDR certification premiums and AI-enabled diagnostic software bundling that shifts revenue toward recurring SaaS streams.
For Market Incumbents: To counter algorithm developers seeking hardware partnerships, Abbott and Medtronic should deepen exclusive software companion development for closed-loop neurostimulation platforms. Defensive consolidation through acquiring MDR-ready mid-tier electrode array specialists in Germany or Switzerland would secure component supply and eliminate emerging competitive threats before HAS reimbursement conditioning locks in market positions.
For New Entrants and Emerging Players: MDR Article 10 clinical evidence requirements in France open a window for AI seizure-detection developers to partner with established hardware incumbents rather than pursue standalone certification. White-space targets include ambulatory vagus-nerve stimulation in Auvergne-Rhône-Alpes and wireless intracranial pressure monitoring for regional critical care networks. Go-to-market traction requires embedding algorithms into existing neuromonitoring platforms through FDA-cleared or CE-marked integration pathways.
For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm developers holding FDA breakthrough device designation for predictive neurostimulation control. Long-term viability hinges on five-year post-market surveillance data generation capabilities and established French medical affairs staffing. Acquisition targets should demonstrate active patient registries in at least two French regions. Practitioners should monitor HAS comparative efficacy trial readouts for closed-loop deep-brain stimulation systems as inflection indicators for reimbursement expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR certification under ANSM oversight unlocks French procurement access and HAS reimbursement eligibility. |
| Hospital System Partnership | Assistance Publique-Hôpitaux de Paris consortium agreements concentrate demand for research-grade neuroimaging platforms. |
| Software Companion Development | AI-enabled seizure prediction algorithms bundled with neurostimulators shift revenue toward recurring SaaS streams. |
| Reimbursement Strategy | HAS comparative efficacy submissions for closed-loop DBS systems secure premium pricing through outcome-guarantee frameworks. |
| Post-Market Surveillance Infrastructure | French-based vigilance representatives and patient registries satisfy ANSM mandates for Class III implantable devices. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with French neurosurgeons, biomedical engineers, GPO contracts managers, and ANSM regulatory affairs officers combined with secondary validation from CE marking databases, HAS reimbursement decision records, and hospital procurement consortium tender archives. Top-down triangulation against EU MDR notified body capacity data and neurotechnology patent filings anchored volume estimates.
Input-output matrices mapped device shipments across product type, application, end user, and technology dimensions over the projection horizon. CAGRs derived from segment-level growth rate distributions weighted by HAS reimbursement pathway maturity and ANSM vigilance enforcement intensity. Forecast inputs included geriatric demographic trajectories from INSEE, neurointerventional specialist supply from French medical college registries, and MDR certification timelines from notified body disclosure statements.
Revisions become necessary when ANSM enforcement intensity shifts, HAS comparative efficacy criteria tighten, or AI diagnostic software reclassification under MDR SaaMD rules materialize. Practitioners should monitor CE-MDR notified body capacity constraints and neurointerventional radiologist training pipeline expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
Hip Resurfacing Implants Market
Orthopedic Devices
Global Hip Replacement Implants Market
Orthopedic Devices
Global Orthopedic Splints Market
Orthopedic Devices
Spinal Implants and Devices Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Kyphoplasty Systems Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Orthopedic Trauma Fixation Devices Market
Orthopedic Devices
Global Total Ankle Replacement Market
Orthopedic Devices
Global Shoulder Replacement Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
China Spinal Surgery Devices Market
Orthopedic Devices
Distal Compression Plates Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Cartilage Repair Market