
 Outsourced Orthopedic Manufacturing Market | 2026-2036
Outsourced Orthopedic Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Outsourced Orthopedic Manufacturing Market Analysis
Multi-source outsourcing is expanding across the orthopedic supply base as device OEMs reduce captive manufacturing exposure. Tecomet Inc. anchors high-volume implant machining across North American facilities. Orchid Orthopedic Solutions differentiates through vertically integrated forging and finishing capabilities for complex joint reconstruction components. Cretex Companies sustains leadership in polymer-based instrument housings and delivery systems.
Outsourced orthopedic manufacturing encompasses the contract production of metallic and polymeric devices used in musculoskeletal repair, including titanium alloy implants machined to ISO 5832 tolerances and PEEK-based spinal cages fabricated via injection molding or additive processes. The primary purpose is to enable OEMs to access specialized production capacity without capital-intensive facility investments. Implants generate the deepest margin pools due to regulatory validation burdens and material certification requirements. Additive manufacturing represents the fastest-growing process segment as design freedoms for patient-specific instrumentation expand. Hospitals remain the dominant end-user channel, though ambulatory surgical centers are gaining procurement influence for outpatient joint procedures.
FDA 21 CFR Part 820 quality system requirements, EU MDR technical documentation mandates, and ISO 13485 certification standards collectively elevate barriers for contract manufacturers seeking orthopedic work. These frameworks shape demand by forcing OEMs toward partners with established regulatory dossiers and validated sterilization pathways. Stakeholders must monitor how FDA inspection priorities and Notified Body capacity constraints redistribute outsourcing awards among qualified suppliers.
Market Dynamics
Original equipment manufacturers are dismantling captive production footprints as FDA 21 CFR Part 820 and EU MDR compliance costs render in-house orthopedic manufacturing economically unsustainable for mid-tier device firms.
Growth Catalysts
- EU MDR technical documentation mandates:Smaller orthopedic OEMs lacking established quality management systems are outsourcing entire product lines to contract manufacturers with pre-validated regulatory dossiers.
- Additive manufacturing process maturation:Electron beam melting and selective laser sintering of titanium alloys now achieve ISO 5832 mechanical tolerances, unlocking patient-specific implant geometries previously impossible via subtractive machining.
- United States surgical volume concentration:Ambulatory surgical centers in Florida, Texas, and California are driving instrument demand for outpatient joint procedures, pulling production capacity toward North American contract manufacturers.
Market Restraints
- Titanium alloy feedstock volatility:Sponge titanium prices fluctuate with aerospace demand cycles, compressing margins for implant-focused contract manufacturers locked into long-term OEM supply agreements.
- Notified Body capacity constraints:EU MDR designation bottlenecks in Germany and the Netherlands are extending certification timelines for new orthopedic contract manufacturers seeking CE marking.
- Polymer substitution limitations:PEEK spinal cages face competitive pressure from 3D-printed titanium lattice structures in fusion procedures, constraining growth in polymer-centric outsourcing portfolios.
Strategic Opportunities
- Japan's aging surgical population:METI reimbursement reforms favoring domestic manufacturing partnerships create entry pathways for contract manufacturers establishing JIS-compliant production facilities.
- India's orthopedic device PLI scheme:Production-linked incentives for Class C and D implants under CDSCO jurisdiction attract contract manufacturers seeking cost-advantaged precision machining capacity.
- Digital thread integration:Convergence of CT-to-implant design software with CNC programming platforms enables same-day surgical planning and next-day implant production for trauma applications.
Industry Challenges
- AS9100D-to-ISO 13485 workforce conversion:Contract manufacturers recruiting aerospace machinists face 12-18 month retraining cycles to master biocompatibility documentation and sterile handling protocols.
- Cleanroom capex intensity:ISO 14644 Class 7 implant finishing facilities require $15-25 million per production line, forcing mid-cap contractors toward equipment financing structures that dilute operational flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outsourced Orthopedic Manufacturing Market |
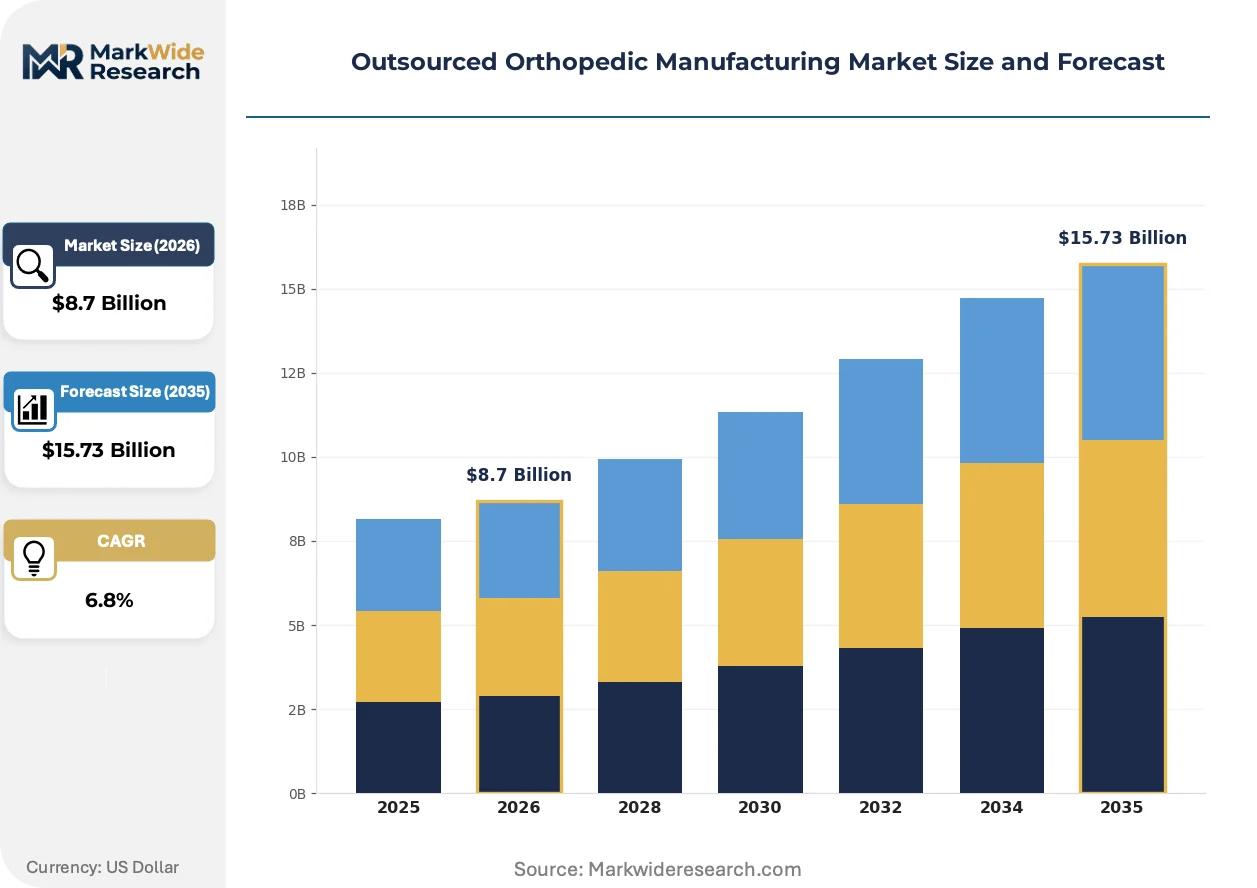
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Instruments, Surgical Accessories, Bone Grafts Delivery Model: Direct Shipping, Inventory Management, Just-In-Time, Bulk Delivery End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Facilities Manufacturing Process: Injection Molding, CNC Machining, Additive Manufacturing, Forging |
| Companies Covered | Tecomet Inc., Orchid Orthopedic Solutions, Cretex Companies, Viant, ARCH Medical Solutions Corp., Avalign Technologies, LISI Medical, Autocam Medical, Norman Noble Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outsourced Orthopedic Manufacturing Market Emerging Trajectories
Orthopedic contract manufacturing is experiencing a process-level transformation as additive technologies mature and regulatory data requirements reshape how production partners validate and document device histories.
Electron beam melting of Ti-6Al-4V ELI is rewriting the economics of acetabular cup production. Leading joint reconstruction OEMs are converting 30-40% of bearing surface geometries to additively manufactured lattice structures. This shift compresses lead times from 16 weeks to under 6 weeks while enabling porosity gradients that improve osseointegration outcomes.
EU MDR Annex XIV clinical evaluation requirements are forcing contract manufacturers to maintain post-market surveillance infrastructure previously borne by OEMs alone. German Notified Bodies are rejecting technical documentation lacking supplier-held clinical data. Swiss and Irish contract manufacturers are responding by building in-house clinical affairs teams to support OEM regulatory submissions.
Hospital procurement departments are consolidating instrument sets across multiple OEM brands, demanding contract manufacturers supply sterilization-validated cases compatible with competing navigation systems. This pattern is most visible in German university hospitals and US integrated delivery networks, where standardization committees now specify case dimensions and instrument marking conventions in competitive tenders.
Outsourced Orthopedic Manufacturing Market Segmentation
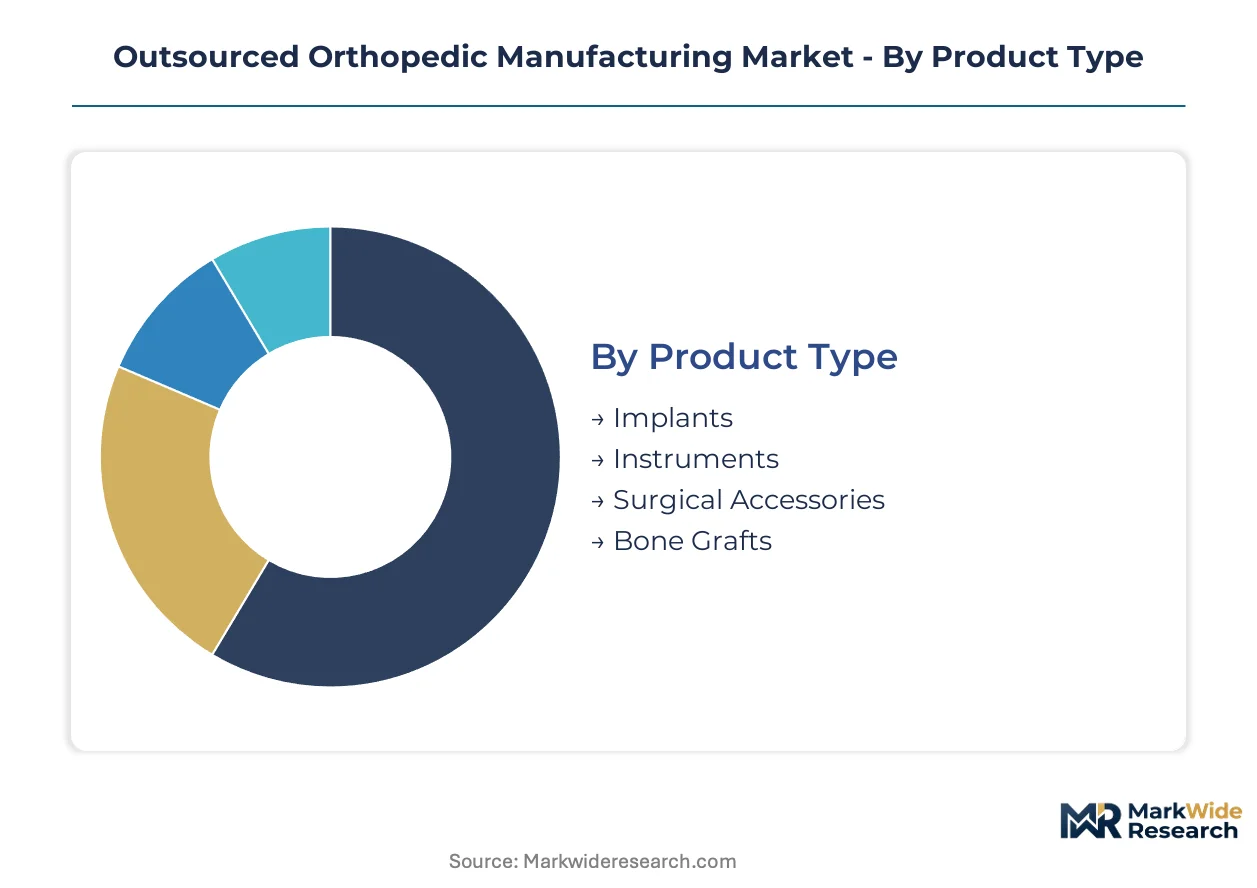
Orthopedic contract manufacturing segments reflect divergent regulatory burdens and capital intensity. Product type determines margin structure, while manufacturing process selection increasingly dictates competitive positioning against additive technology adopters.
Product Type:
Implant production concentrates among a handful of validated suppliers due to ISO 5832 material certification requirements and FDA 21 CFR Part 820 quality system burdens that smaller contractors cannot sustain.
- Implants:Titanium alloy and PEEK devices requiring full design history files and biocompatibility testing. Demand clusters in the United States and Germany where joint reconstruction OEMs source acetabular cups and spinal cages from partners with established sterilization validation. Regulatory dossier maintenance costs favor long-term supplier relationships over spot contracting.
- Instruments:Reusable stainless steel and polymer surgical tools with shorter validation cycles. Ambulatory surgical centers in Florida and Texas are consolidating procurement across multiple OEM brands, pulling instrument production toward North American contract manufacturers with case-standardization capabilities.
- Surgical Accessories:Single-use drapes, suction devices, and positioning aids. German university hospitals specify these in bundled tenders alongside primary implants.
- Bone Grafts:Allograft and synthetic matrices processed under tissue bank regulations. Swissmedic oversight in Switzerland creates specialized outsourcing demand distinct from standard device manufacturing.
Today's leader: Implants. Tomorrow's challenger: Instruments.
Delivery Model:
Cost tier differentiation separates premium inventory-carrying relationships from transaction-based bulk arrangements, with hospital consolidation favoring sophisticated logistics partners.
- Direct Shipping:Point-to-point distribution from contract manufacturer to hospital or ASC. German integrated delivery networks specify direct shipping with electronic proof-of-delivery to reduce receiving dock congestion.
- Inventory Management:Vendor-managed stock programs with consignment arrangements. United States health systems in California demand real-time inventory visibility through EDI integration, raising IT infrastructure requirements for contract manufacturers.
- Just-In-Time:Scheduled replenishment tied to surgical block calendars. This segment is gaining share fastest as ASC volume expansion in Texas and Florida compresses implant shelf-life exposure.
- Bulk Delivery:Quarterly shipments to OEM central warehouses for redistribution. Cost-driven standard instruments and accessories still move through this channel, though hospital preference is shifting toward more responsive models.
Inventory management commands premium pricing. Just-in-time delivery offers the steepest expansion trajectory.
End User:
Application-specific requirements reshape contract manufacturer capabilities, with outpatient migration demanding instrument standardization incompatible with traditional hospital-centric production.
- Hospitals:Academic medical centers and community hospitals performing complex revision surgeries. These facilities in Germany and Switzerland require contract manufacturers to support custom instrument set modifications for navigation system compatibility.
- Ambulatory Surgical Centers:Outpatient joint replacement hubs driving same-day discharge protocols. ASCs in the United States concentrate in Florida, Texas, and California, demanding sterilization-validated cases with reduced instrument counts.
- Orthopedic Clinics:Physician-owned facilities performing minor procedures. These accounts purchase pre-sterilized disposable instruments through distributor intermediaries rather than direct OEM relationships.
- Rehabilitation Facilities:Post-acute settings requiring bracing and external fixation devices. CDSCO-regulated manufacturing in India serves this price-sensitive segment through cost-optimized polymer processing.
Hospitals retain procurement volume leadership. Ambulatory surgical centers represent the fastest-growing demand source.
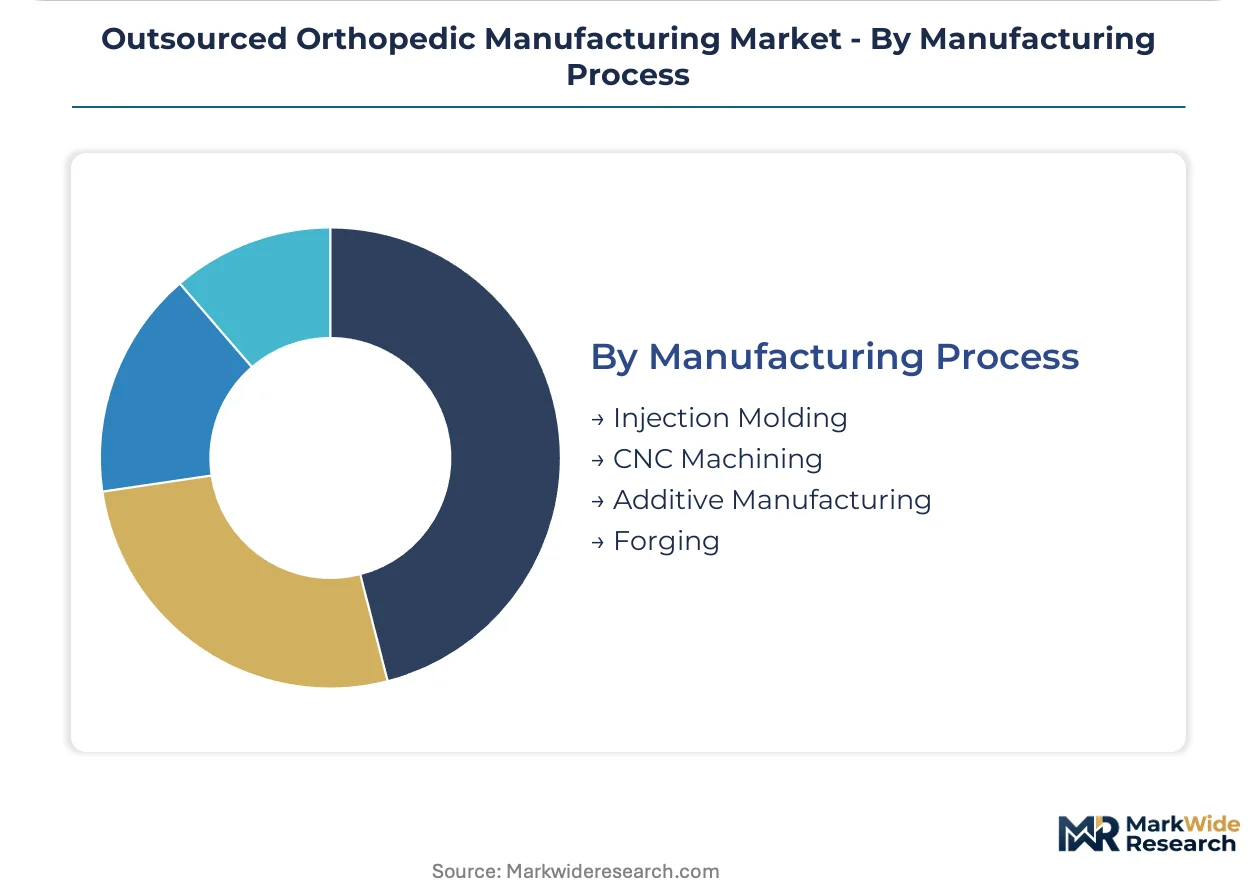
Manufacturing Process:
Technology maturity curves separate established subtractive methods from additive processes still accumulating regulatory validation data.
- Injection Molding:PEEK and high-performance polymer processing for spinal cages and instrument housings. Swiss precision molders maintain leadership through multi-cavity tooling investments that Asian competitors have not replicated.
- CNC Machining:Subtractive manufacturing of titanium and cobalt-chrome implants. United States and German machine shops with AS9100D-to-ISO 13485 converted workforces dominate high-tolerance acetabular component production.
- Additive Manufacturing:Electron beam melting and selective laser sintering of Ti-6Al-4V ELI lattice structures. This segment is expanding most quickly as FDA clears patient-specific instrumentation workflows and joint reconstruction OEMs convert bearing surfaces to porous additively manufactured geometries.
- Forging:Closed-die and isothermal forming of titanium alloy hip stems and knee tibial trays. Orchid Orthopedic Solutions and similar vertically integrated suppliers control this capital-intensive segment through captive forging capacity.
CNC machining anchors current production volumes. Additive manufacturing offers the most significant technology displacement potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The precision manufacturing corridor stretching from Warsaw to Zurich anchors contract orthopedic production capacity. FDA 21 CFR Part 820 and EU MDR compliance burdens concentrate validated suppliers in jurisdictions with established regulatory infrastructure. Four countries dominate outsourcing awards through distinct capability specializations.
United States
Ambulatory surgical centers in Florida, Texas, and California drive instrument demand for outpatient joint procedures. FDA inspection priorities and 510(k) submission volumes push OEMs toward domestic contract manufacturers with established quality management systems. The Minneapolis-St. Paul corridor hosts machining clusters serving major joint reconstruction OEMs.
Germany
University hospitals in Bavaria and North Rhine-Westphalia consolidate procurement across multiple OEM brands, demanding sterilization-validated instrument sets. Notified Body capacity constraints under EU MDR extend certification timelines, favoring incumbent contract manufacturers with existing CE dossiers. The Stuttgart precision engineering cluster supplies acetabular components to European OEMs.
Switzerland
Swissmedic oversight creates specialized outsourcing demand distinct from standard device manufacturing, particularly for bone graft processing. The Jura Arc watchmaking-to-medical conversion supplies high-tolerance titanium machining for spinal implants. Geneva and Basel host contract manufacturers with vertically integrated forging and finishing capabilities.
India
CDSCO production-linked incentives for Class C and D implants attract contract manufacturers seeking cost-advantaged precision machining capacity. Maharashtra and Gujarat host emerging machining clusters serving price-sensitive trauma and external fixation markets. Domestic OEM partnerships with multinational device companies accelerate technology transfer.
Japan
METI reimbursement reforms favoring domestic manufacturing partnerships create entry pathways for contract manufacturers establishing JIS-compliant production facilities. The Nagoya medical device corridor concentrates polymer processing for instrument housings. Aging surgical population demographics expand joint replacement volumes requiring localized supply chains.
Outsourced Orthopedic Manufacturing Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing certifications and patient-specific instrumentation capabilities. The vendor base stratifies across three capability tiers: vertically integrated forging specialists, precision machining job shops with regulatory dossiers, and polymer-focused instrument fabricators. Two strategic archetypes dominate competitive positioning: capacity-locked incumbents with ISO 13485-validated cleanrooms, and technology-forward challengers betting on electron beam melting process adoption. Consolidation pressure manifests through OEM mandates for single-source implant supply, while mid-tier contractors defend position through equipment financing partnerships.
Within the vertically integrated tier, Orchid Orthopedic Solutions and Tecomet Inc. exemplify divergent scale strategies. Orchid anchors high-volume forging and finishing for complex joint reconstruction components across North American facilities. Tecomet represents the precision machining archetype with distributed production footprints serving multiple OEM quality systems. Cretex Companies occupies a specialized position in polymer-based instrument housings and delivery systems. These three entities collectively illustrate how regulatory validation burdens create defensive moats against unqualified entrants.
| Leading Market Players |
|---|
| Tecomet Inc. |
| Orchid Orthopedic Solutions |
| Cretex Companies |
| Viant |
| ARCH Medical Solutions Corp. |
| Avalign Technologies |
| LISI Medical |
| Autocam Medical |
| Norman Noble Inc. |
| Others |
Supply Flow & Price Mechanics
Joint reconstruction OEMs with captive manufacturing dismantling programs concentrate procurement power among validated contract manufacturers, locking pricing into long-term supply agreements indexed to titanium alloy feedstock volatility.
Pricing Analysis
Titanium alloy sponge costs pass through directly to implant pricing under multi-year OEM contracts, compressing margins when aerospace demand cycles spike raw material benchmarks. Pricing stratifies across FDA-validated premium tiers, ISO 13485-certified standard tiers, and emerging economy tiers serving Indian trauma markets. Cost compression in polymer instrument segments is intensifying because PEEK substitution pressure from 3D-printed titanium lattices forces contract manufacturers to absorb tooling amortization. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge reimbursement constraints, while German university hospitals prioritize sterilization validation over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle high-volume implant demand from Minneapolis-St. Paul machining clusters and Stuttgart precision engineering hubs. Supply concentrates in the United States, Germany, and Switzerland where FDA and EU MDR compliance infrastructure anchors validated production. Raw material dependencies center on titanium sponge from aerospace suppliers, PEEK resin from specialty polymer producers, and cobalt-chrome feedstock for bearing surfaces. Single-source vulnerability in electron beam melting equipment creates chokepoint risk for additive manufacturing adopters. Distribution runs through vendor-managed inventory programs with consignment arrangements at California health systems and German integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Additive manufacturing process maturation enables margin expansion through patient-specific instrumentation premiums, while EU MDR compliance costs drive smaller OEMs toward outsourced production models.
For Market Incumbents: Deepen captive forging capacity in North American facilities to defend against electron beam melting challengers converting acetabular cup geometries to lattice structures. Anchor long-term supplier relationships through sterilization validation investments that smaller contractors cannot replicate under ISO 14644 Class 7 capex requirements. For New Entrants and Emerging Players: Digital thread integration platforms offer the most penetrable entry pathway, converging CT-to-implant design software with CNC programming for trauma applications. Target India's CDSCO PLI scheme for Class C and D implants to establish cost-advantaged precision machining before pursuing FDA validation. Build clinical affairs capabilities early to support OEM EU MDR Annex XIV submissions. For Investors and Strategic Acquirers: Vertically integrated orthopedic contract manufacturers with ISO 13485-validated cleanrooms are the most active acquirer targets in this space, as OEM consolidation mandates single-source implant supply. Watch Notified Body capacity constraints in Germany and the Netherlands as the signal for certification timeline inflection that redistributes outsourcing awards among qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Certification | FDA 510(k) clearances for electron beam melting processes unlock patient-specific implant geometries. |
| EU MDR Technical Documentation Buildout | Post-market surveillance infrastructure investments satisfy German Notified Body clinical data requirements. |
| Vendor-Managed Inventory Expansion | Real-time EDI integration with California health systems reduces implant shelf-life exposure. |
| JIS-Compliant Production Facility | METI reimbursement reforms in Japan favor domestic manufacturing partnerships for aging surgical populations. |
| AS9100D-to-ISO 13485 Workforce Conversion | Retrained aerospace machinists master biocompatibility documentation for high-tolerance acetabular components. |
Methodological Framework
Direct dialogue with contract manufacturing executives, OEM procurement directors, FDA quality system consultants, and German Notified Body auditors grounded qualitative findings in operational reality. Secondary validation drew from FDA 510(k) submission databases, EU MDR technical documentation guidance, ISO 13485 certification registries, and hospital procurement contract disclosures. Bottom-up and top-down triangulation cross-checked production capacity estimates against OEM outsourcing spend patterns.
Bottom-up modeling aggregated contract manufacturer revenue trajectories across product type, delivery model, and manufacturing process segments. Top-down validation calibrated aggregate market expansion against ambulatory surgical center volume growth in Florida, Texas, and California. CAGRs were derived from regression analysis of historical outsourcing penetration rates and forward projections of EU MDR compliance cost burdens. Forecast inputs included electron beam melting adoption curves, titanium alloy price volatility indices, and Notified Body capacity expansion timelines.
Regulatory enforcement shifts, feedstock price spikes, and additive manufacturing process failures are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about OEM captive manufacturing dismantling pace and ASC outpatient migration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Spinal Devices Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Orthopedic Drill Bits Market
Orthopedic Devices
Total Wrist Prosthesis Market
Orthopedic Devices
Global Orthopedic Bone Cement Market
Orthopedic Devices
US Orthopedic Devices Market
Orthopedic Devices
Europe Orthopedic Devices Market
Orthopedic Devices
Orthopedic Prosthetic Devices Market
Orthopedic Devices
Adult Orthopedic Insole Market
Orthopedic Devices
Bone Graft Fixation System Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Vertebroplasty Needles Market