
 Kyphoplasty Market | 2026-2036
Kyphoplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Kyphoplasty Market Intelligence
MDR compliance in Europe is consolidating the cost-of-entry calculus for kyphoplasty device manufacturers seeking CE marking. Medtronic leverages its balloon catheter manufacturing scale to sustain European market presence despite notified body bottlenecks. Stryker anchors its competitive position through dedicated spine division R&D intensity. DePuy Synthes competes via Johnson & Johnson's hospital contracting networks, which control procurement access across integrated delivery systems.
Kyphoplasty denotes a percutaneous vertebral augmentation procedure wherein an inflatable bone tamp creates a cavity within a fractured vertebral body, followed by polymethylmethacrylate cement injection to restore height and mechanical stability. The technique addresses pathological fractures from osteoporosis, metastatic disease, or trauma, with fluoroscopic guidance serving as the dominant intraoperative imaging modality. Balloon kyphoplasty systems occupy the premium tier of product type segmentation, while cement formulations generate recurring revenue streams that extend per-procedure economics. Hospitals dominate end user channels due to anesthesia requirements and overnight observation protocols, though outpatient clinics represent the fastest-growing site-of-care shift as ambulatory surgical center reimbursement expands.
FDA 510(k) clearance pathways, EU MDR technical documentation requirements, and ISO 13485 quality management standards collectively shape product development timelines and commercial geography for kyphoplasty manufacturers. The FDA's Special Controls guidance for vertebral body replacement devices mandates biomechanical testing and clinical performance data that extend regulatory investment horizons. Stakeholders must monitor reimbursement parity between inpatient and outpatient settings, as site-of-care economics increasingly determine manufacturer channel strategy and provider adoption velocity.
Market Dynamics
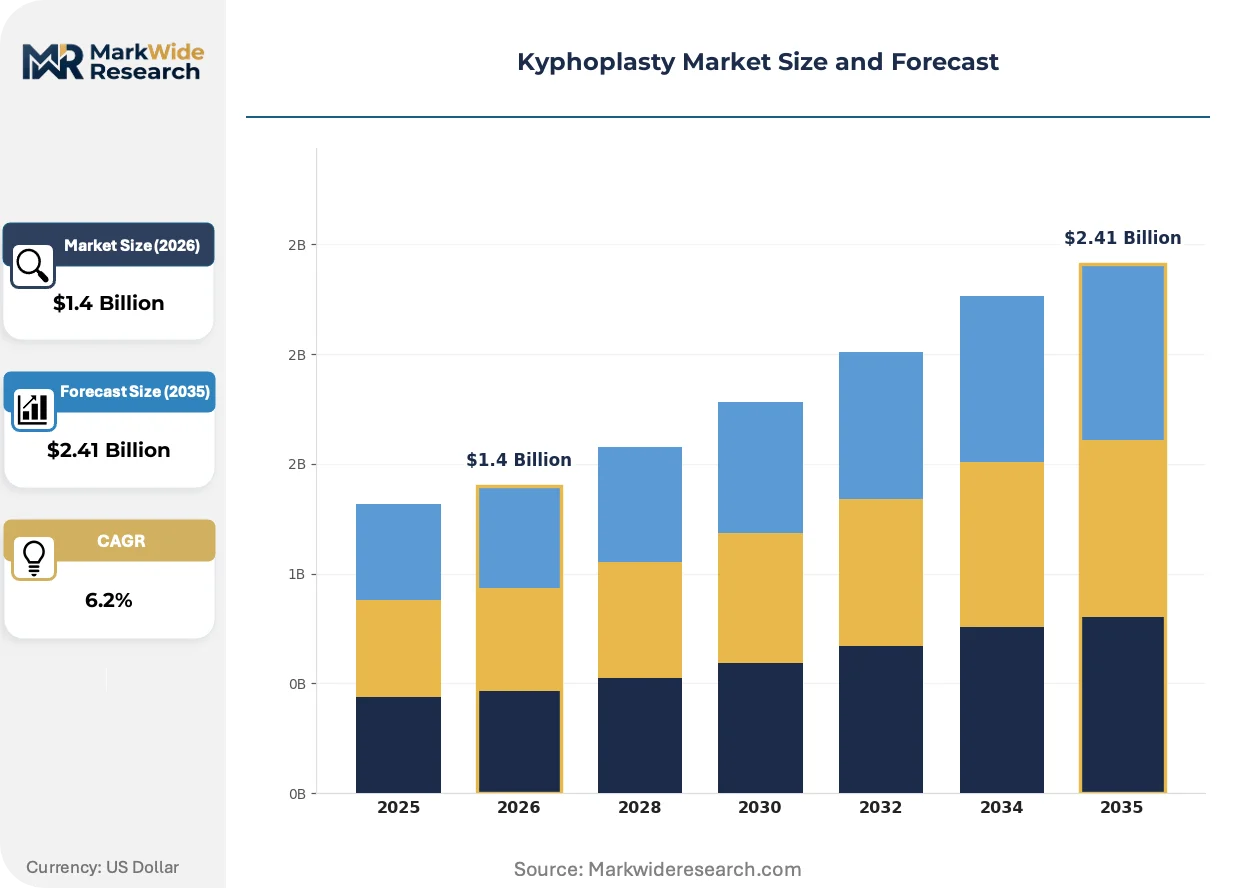
The kyphoplasty market pivots on Medicare reimbursement parity between inpatient and ambulatory surgical centers, which is compressing site-of-care economics and forcing manufacturers to reconfigure channel strategies around procedural volume migration.
Growth Catalysts
- Ambulatory Surgical Center Reimbursement Expansion:Medicare's site-neutral payment policies enable procedural migration to outpatient settings, expanding addressable procedure volumes beyond traditional hospital anchors.
- Polymethylmethacrylate Cement Formulation Advances:Viscosity-modified cements with extended working times reduce extravasation risk and expand treatable patient populations to osteoporotic and metastatic fracture cases.
- EU MDR Technical Documentation Harmonization:Standardized clinical evidence requirements across notified bodies accelerate CE marking timelines for established manufacturers with robust quality management systems.
Market Restraints
- Balloon Catheter Supply Concentration:Polymer extrusion capabilities for compliant balloon manufacturing concentrate among a limited supplier base in Germany and Switzerland, creating input vulnerability.
- FDA Special Controls Compliance Burden:Biomechanical testing mandates for vertebral body replacement devices extend regulatory investment horizons and compress returns for mid-tier entrants.
- Vertebroplasty Substitution Threat:Unaugmented cement injection procedures offer lower per-procedure costs in price-sensitive hospital systems, constraining kyphoplasty premium positioning.
Strategic Opportunities
- Underpenetrated Japanese Geriatric Population:Japan's super-aged demographic and PMDA streamlined review pathways for designated medical devices create procedural volume expansion potential.
- Navigation-Integrated Fluoroscopy Convergence:Real-time 3D navigation systems combined with conventional C-arm imaging reduce radiation exposure and enable complex multi-level procedures.
- Integrated Delivery System Contracting Access:Johnson & Johnson's hospital network control demonstrates procurement channel leverage that specialty manufacturers can replicate through GPO partnerships.
Industry Challenges
- Interventional Spine Fellowship Pipeline Constraints:The limited number of accredited training programs restricts qualified operator supply and constrains procedural expansion velocity.
- ISO 13485 Certification Timeline Compression:Notified body audit backlogs extend quality management system certification cycles, delaying commercial launch windows for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kyphoplasty Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Kyphoplasty, Cement, Delivery Systems, Imaging Systems End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Academic Institutions Technology: Fluoroscopy, CT Guidance, MRI Guidance, Ultrasound Application: Vertebral Compression Fractures, Osteoporosis, Trauma, Tumors |
| Companies Covered | Medtronic, Stryker, DePuy Synthes, Merit Medical Systems, IZI Medical Products, Johnson & Johnson, Globus Medical, MicroPort Scientific Corporation, Joimax GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kyphoplasty Market Strategic Shifts & Innovations
Device miniaturization and digital workflow integration are compressing procedural complexity while expanding treatable patient populations beyond traditional tertiary hospital settings.
Radiofrequency-targeted vertebral augmentation is integrating thermal energy delivery with conventional balloon cavity creation to improve cement interdigitation with cancellous bone. Academic medical centers in the United States are piloting this hybrid approach for pathological fractures with lytic tumor involvement. The technology is integrating cement polymerization control with tumor necrosis objectives, expanding indication scope beyond simple osteoporotic compression fractures.
EU MDR Article 117 clinical evaluation requirements for class IIb spinal devices mandate systematic literature reviews and post-market clinical follow-up protocols that reshape product development resource allocation. Manufacturers must demonstrate equivalence to existing devices or generate proprietary clinical data, extending time-to-market for iterative product improvements. European spine divisions are responding by consolidating product portfolios to focus resources on highest-volume SKUs with established clinical evidence bases.
Hospital procurement departments are unbundling balloon catheter systems from cement kits to optimize inventory turnover and reduce expiration waste. This specification behavior disrupts traditional bundled pricing models and forces manufacturers to demonstrate standalone value for each component category. The shift is most visible in United States integrated delivery networks with centralized supply chain governance and standardized physician preference item committees.
Kyphoplasty Market Segmentation
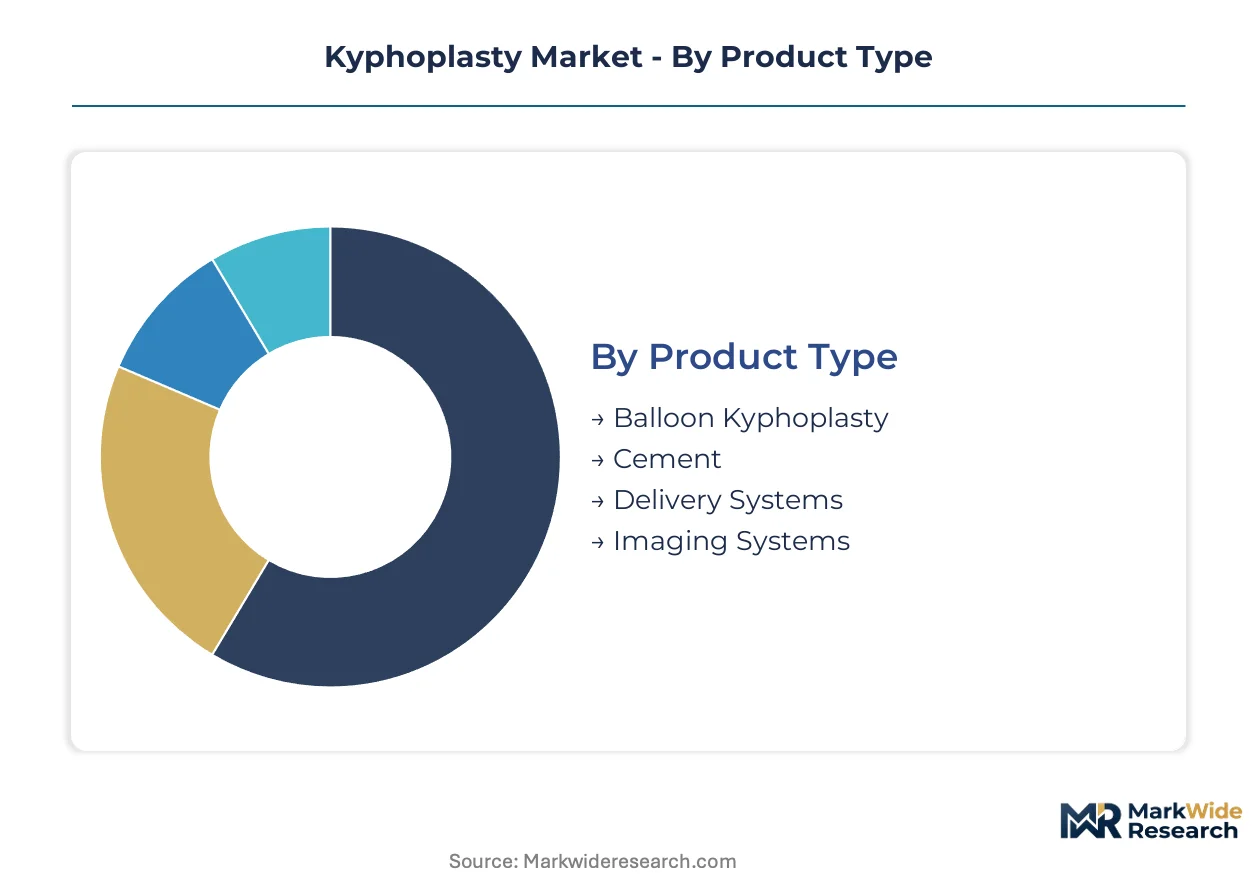
Kyphoplasty market segmentation reveals distinct regulatory pathways and margin structures across device categories. Product type and end-user channels drive the most significant commercial strategy divergence for manufacturers navigating FDA 510(k) and EU MDR compliance timelines.
Product Type:
FDA Class II spinal device classification applies differentially across this category, with balloon systems facing Special Controls while cement formulations navigate 510(k) exemptions for predicate-established materials.
- Balloon Kyphoplasty:Inflatable bone tamp systems with compliant polymer construction command premium pricing tiers. Tertiary hospital orthopedic departments in the United States concentrate demand here, driven by Medicare reimbursement parity that sustains inpatient procedural economics despite ambulatory migration pressures.
- Cement:Polymethylmethacrylate formulations with viscosity modification and extended working times generate recurring revenue streams. German and Swiss polymer extrusion suppliers control input quality for high-viscosity variants, creating supply-side concentration that extends lead times for formulation modifications.
- Delivery Systems:Cannula and injector assemblies with ergonomic grip design for single-operator control.
- Imaging Systems:Mobile C-arm fluoroscopy units with dedicated spine software packages.
Balloon Kyphoplasty sits at the top of the volume ranking, with Cement climbing the fastest as outpatient clinics drive per-procedure consumption rates.
End User:
Site-of-care economics fragment procurement behavior, with integrated delivery networks unbundling component purchasing while standalone facilities retain bundled kit preferences.
- Hospitals:Tertiary centers with accredited interventional spine fellowship programs anchor procedural volume. United States Medicare inpatient reimbursement codes sustain overnight observation protocols that preserve hospital-based economics despite site-neutral payment policy compression.
- Outpatient Clinics:Ambulatory surgical centers with anesthesia partnerships represent the steepest expansion trajectory. United States site-neutral payment policies enable procedural migration, though state-level certificate-of-need restrictions constrain physical expansion in concentrated markets.
- Rehabilitation Centers:Post-acute facilities with pain management integration for conservative care pathways.
- Academic Institutions:Teaching hospitals with NIH-funded biomechanics research programs driving device innovation.
Hospitals retain the dominant volume position, though Outpatient Clinics are gaining share fastest as ambulatory infrastructure investment accelerates.
Technology:
Radiation exposure liability and capital equipment depreciation schedules differentiate adoption economics across imaging modalities.
- Fluoroscopy:Real-time C-arm imaging with pulsed fluoroscopy modes dominates intraoperative guidance. United States hospital capital budgets concentrate procurement here, constrained by interventional radiologist staffing shortages that limit multi-room utilization rates.
- CT Guidance:Pre-procedural planning with intraoperative cone-beam integration reduces revision rates. Japanese academic medical centers pilot intraoperative CT for complex multi-level procedures, leveraging PMDA streamlined review pathways for navigation-integrated systems.
- MRI Guidance:Open-configuration systems for radiation-sensitive patient populations.
- Ultrasound:Emerging modality for cost-sensitive markets with limited fluoroscopy infrastructure.
Fluoroscopy maintains volume leadership, with CT Guidance expanding most quickly as navigation convergence reduces procedural radiation burden.
Application:
Pathology-specific reimbursement coding and clinical evidence requirements shape manufacturer indication expansion strategies.
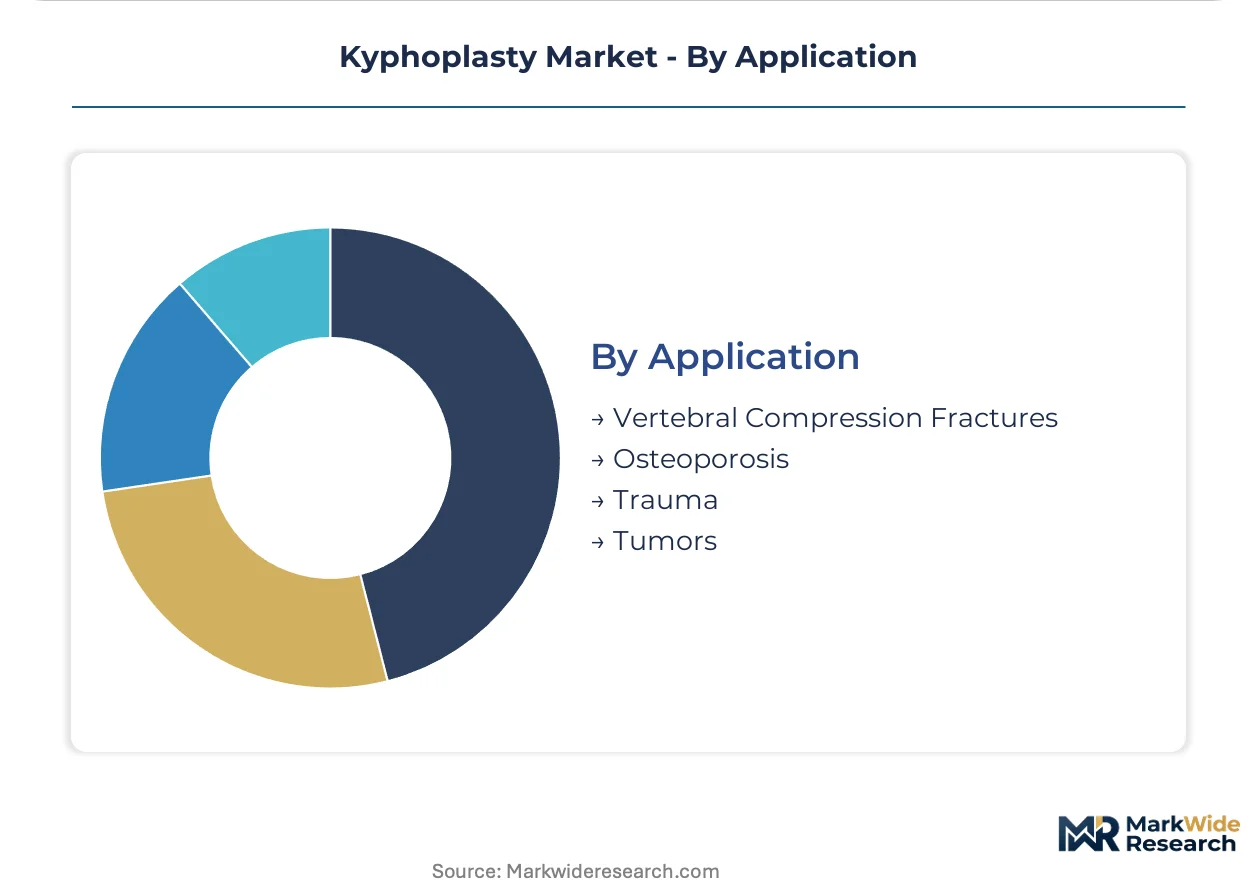
- Vertebral Compression Fractures:Osteoporotic collapse patterns in thoracolumbar spine segments constitute the core addressable population. United States Medicare coverage determinations for percutaneous vertebral augmentation sustain procedural access for beneficiaries with failed conservative management.
- Osteoporosis:Primary disease state indication with established clinical guidelines from the National Osteoporosis Foundation. Bone mineral density testing referral patterns in United States primary care networks drive diagnostic funnel volume toward kyphoplasty-eligible patients.
- Trauma:Acute fracture stabilization for polytrauma patients with vertebral involvement.
- Tumors:Pathological fracture management with radiofrequency-targeted augmentation for lytic lesions.
Vertebral Compression Fractures anchor volume rankings, with Tumors showing the steepest indication expansion as thermal-augmentation hybrid techniques mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional spine fellowship programs concentrate in tertiary medical centers across five countries, anchoring procedural capacity and device procurement volume.
United States
Medicare reimbursement parity between inpatient and ambulatory surgical centers drives site-of-care migration. FDA Special Controls guidance for vertebral body replacement devices mandates biomechanical testing that extends regulatory timelines. The Cleveland Clinic and Mayo Clinic anchor multi-level kyphoplasty training pipelines in the Midwest.
Germany
Polymer extrusion capabilities for compliant balloon manufacturing cluster in Baden-Württemberg and Bavaria. EU MDR technical documentation requirements reshape CE marking timelines for Class IIb spinal devices. Berlin-Brandenburg academic hospitals pilot navigation-integrated fluoroscopy systems for complex tumor cases.
Japan
Super-aged demographics expand the addressable patient population for osteoporotic compression fractures. PMDA streamlined review pathways for designated medical devices accelerate regulatory clearance for navigation-integrated systems. Tokyo and Osaka metropolitan academic centers drive adoption of radiofrequency-targeted vertebral augmentation.
Switzerland
Precision polymer manufacturing for high-pressure balloon systems concentrates in the Lake Geneva region. Swissmedic maintains alignment with EU MDR requirements while preserving national notification procedures. Basel-area orthopedic research institutes collaborate with device manufacturers on cement formulation biomechanics.
China
Rapid hospital infrastructure expansion in tier-one cities builds interventional spine capacity. NMPA regulatory harmonization with international standards accelerates approval timelines for predicate-established devices. Shanghai and Beijing tertiary hospitals anchor domestic kyphoplasty training networks.
Kyphoplasty Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Tier-one participants leverage hospital contracting networks and integrated delivery system procurement access. Mid-tier specialists concentrate on balloon catheter manufacturing scale and cement formulation differentiation. Dominant competitive moves include strategic partnerships with academic medical centers for clinical evidence generation and geographic expansion into underpenetrated Asian markets.
Within the diversified medical technology tier, Medtronic and Stryker exemplify scale-driven positioning through dedicated spine division structures and balloon catheter manufacturing capabilities. DePuy Synthes occupies a position anchored by Johnson & Johnson's hospital network control and integrated delivery system contracting leverage.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| DePuy Synthes |
| Merit Medical Systems |
| IZI Medical Products |
| Johnson & Johnson |
| Globus Medical |
| MicroPort Scientific Corporation |
| Joimax GmbH |
| Others |
Cost & Logistics Intelligence
Balloon catheter premium tiers diverge sharply from cement commodity grades, with FDA Special Controls compliance costs concentrating pricing power among German and Swiss polymer extrusion specialists while unbundled procurement in United States integrated delivery networks compresses kit margins.
Pricing Analysis
Bundled kit pricing versus unbundled component purchasing splits the market. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) predicate complexity and ISO 13485 certification depth. Price differentiation stems from balloon compliance engineering and viscosity-modified cement formulation patents. Cost compression in standard-tier balloon systems intensifies as hospital procurement committees unbundle catheters from cement. Ambulatory surgical centers exhibit highest price sensitivity; tertiary academic centers with NIH research funding show lowest.
Supply Chain Analysis
Compliant balloon polymer supply rests on specialty extrusion houses in Germany, Switzerland, and select United States medical device corridors. Raw material dependencies include medical-grade silicone elastomers, radiopaque barium sulfate, and high-purity PMMA resin powder. Single-source vulnerability concentrates in Baden-Württemberg polymer compounders serving CE marking timelines. Distribution runs through group purchasing organizations and integrated delivery network central warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kyphoplasty market compounds regulatory investment into sustainable competitive moats, with EU MDR Article 117 clinical evaluation requirements and FDA Special Controls guidance creating irreversible barriers that favor incumbents with amortized quality management infrastructure.
For Market Incumbents: Hedge against vertebroplasty substitution by deepening cement formulation differentiation through radiofrequency-targeted augmentation patents. Secure backward integration into polymer extrusion capacity in Switzerland or Germany to insulate balloon input costs from notified body audit backlogs. Channel control through GPO exclusive contracting remains the priority defensive lever. For New Entrants and Emerging Players: Underserved outpatient clinics with anesthesia partnerships offer the most penetrable entry vector. Japanese academic medical centers piloting navigation-integrated systems present white-space demand with PMDA streamlined review pathways. A software companion development strategy for fluoroscopy workflow integration enables differentiation without capital-intensive balloon manufacturing scale. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed standalone revenue bases for mid-tier balloon catheter specialists. Long-term viability favors acquiring targets with ISO 13485 certification and established predicate device equivalence libraries. Watch Medicare site-neutral payment policy expansion as the signal indicating ambulatory volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation harmonization accelerates notified body clearance for established quality systems. |
| Hospital System Partnership | Integrated delivery network contracting secures procurement access across Johnson & Johnson-style network control. |
| Reimbursement Strategy | Medicare inpatient-ambulatory parity alignment maximizes addressable procedure volume migration. |
| Software Companion Development | Navigation-integrated fluoroscopy convergence reduces radiation exposure and enables complex multi-level cases. |
| Backward Integration | Captive polymer extrusion capacity insulates balloon input costs from German-Swiss supply concentration. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged interventional spine fellowship directors, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers at tertiary centers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body technical documentation filings, CMS Medicare reimbursement schedules, and hospital procurement expenditure records. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored value estimates.
Segment-weighting distributed volume and value across product type, end-user channel, technology modality, and application indication dimensions. CAGRs were derived from regression analysis of historical procedural migration patterns and reimbursement policy elasticity across the analysis window. Forecast inputs incorporated interventional radiologist fellowship pipeline constraints and ambulatory surgical center certificate-of-need expansion rates.
Inputs from FDA premarket notification filings and EU MDR clinical evaluation reports were available through the study window; gaps in real-time notified body audit queue data introduce uncertainty bands around CE marking timeline assumptions. Forecasts reflect documented assumptions regarding Medicare site-neutral payment policy implementation and PMDA designated device pathway utilization. A small set of triggers—balloon catheter supply disruption, vertebroplasty guideline revision, and Japanese super-aged demographic acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Veterinary Orthopedic Injectable Drug Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
Orthopedic Braces and Supports Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Orthopedic Joint Reconstruction Market
Orthopedic Devices
Orthopedic Artificial Bone Defect Repair Materials Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market
Orthopedic Devices
UAE Spinal Surgery Devices Market
Orthopedic Devices
Knee Arthrodesis Implant Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Outsourced Orthopedic Manufacturing Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Scoliosis Treatment Market
Orthopedic Devices
Kyphoscoliosis Treatment Market