
 Global Limb Prosthetics Market | 2026-2036
Global Limb Prosthetics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Limb Prosthetics Market Foresight
Microprocessor-controlled knee systems is redrawing competitive boundaries in premium limb prosthetics. Ottobock SE & Co. KGaA leverages integrated mechatronic platforms to dominate European rehabilitation channels. Össur hf anchors its position in sports prosthetics through carbon fiber blade technology and direct-to-clinic distribution. Hanger, Inc. operates the largest orthotic and prosthetic care network in the United States, sustaining volume through captive patient access.
Limb prosthetics are electromechanical or passive mechanical devices engineered to replace absent or non-functional extremities, with socket interfaces typically fabricated from thermoplastic copolymer or carbon fiber composites and rated for cyclic loading exceeding three million gait cycles. Their primary purpose is restoring ambulatory function, dexterity, or cosmetic appearance to individuals with acquired or congenital limb absence. Lower limb prosthetics command the largest revenue pool due to weight-bearing mechanical demands and higher replacement frequency, while myoelectric upper limb systems represent the fastest-expanding margin segment as pattern recognition algorithms improve grip precision. Application demand concentrates in trauma rehabilitation where acute injury volumes and workers compensation funding create predictable procurement cycles.
FDA 510(k) clearance pathways govern electromechanical limb introductions in the United States, while EU MDR Class IIa rules now mandate clinical evidence for socket suspension systems marketed in Europe. ISO 10328 structural testing standards define static and cyclic load verification protocols that manufacturers must satisfy for international market access. Stakeholders should monitor reimbursement code revisions by national health technology assessment bodies, as these determinations directly gate patient access to premium myoelectric and microprocessor technologies.
Market Dynamics
Microprocessor-controlled knee systems are compressing replacement cycles for passive mechanical devices while simultaneously elevating reimbursement scrutiny from health technology assessment bodies across OECD markets.
Growth Catalysts
- EU MDR Class IIa mandates:Socket suspension systems now require clinical evidence for CE marking, accelerating R&D investment in validated interface technologies.
- Carbon fiber composite adoption:Sports medicine channels in Germany and Australia are standardizing blade-style foot prosthetics for trauma rehabilitation protocols.
- Japan's geriatric infrastructure:Municipal long-term care insurance expansions are broadening access to myoelectric upper limb systems for age-related amputations.
Market Restraints
- Thermoplastic copolymer supply concentration:Medical-grade polypropylene feedstock pricing volatility constrains socket fabrication margins.
- FDA 510(k) pathway friction:Electromechanical knee submissions face extended review timelines for novel pattern recognition algorithms.
- Passive mechanical substitution:Developing markets continue prioritizing body-powered devices over microprocessor systems due to maintenance complexity.
Strategic Opportunities
- Australia's veteran rehabilitation networks:Defense procurement programs are consolidating multi-limb trauma care into specialized centers of excellence.
- ISO 10328 convergence with EU MDR:Unified structural testing protocols enable single-validation market access across 32 regulatory jurisdictions.
- Direct-to-clinic distribution platforms:Orthotic and prosthetic care networks are bypassing traditional device wholesalers in the United States.
Industry Challenges
- Prosthetist training pipelines:Mechatronic device calibration requires specialized biomechanical engineering competencies scarce in vocational programs.
- Legacy EMR integration:Gait analysis data from microprocessor knees lacks standardized interoperability with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Limb Prosthetics Market |
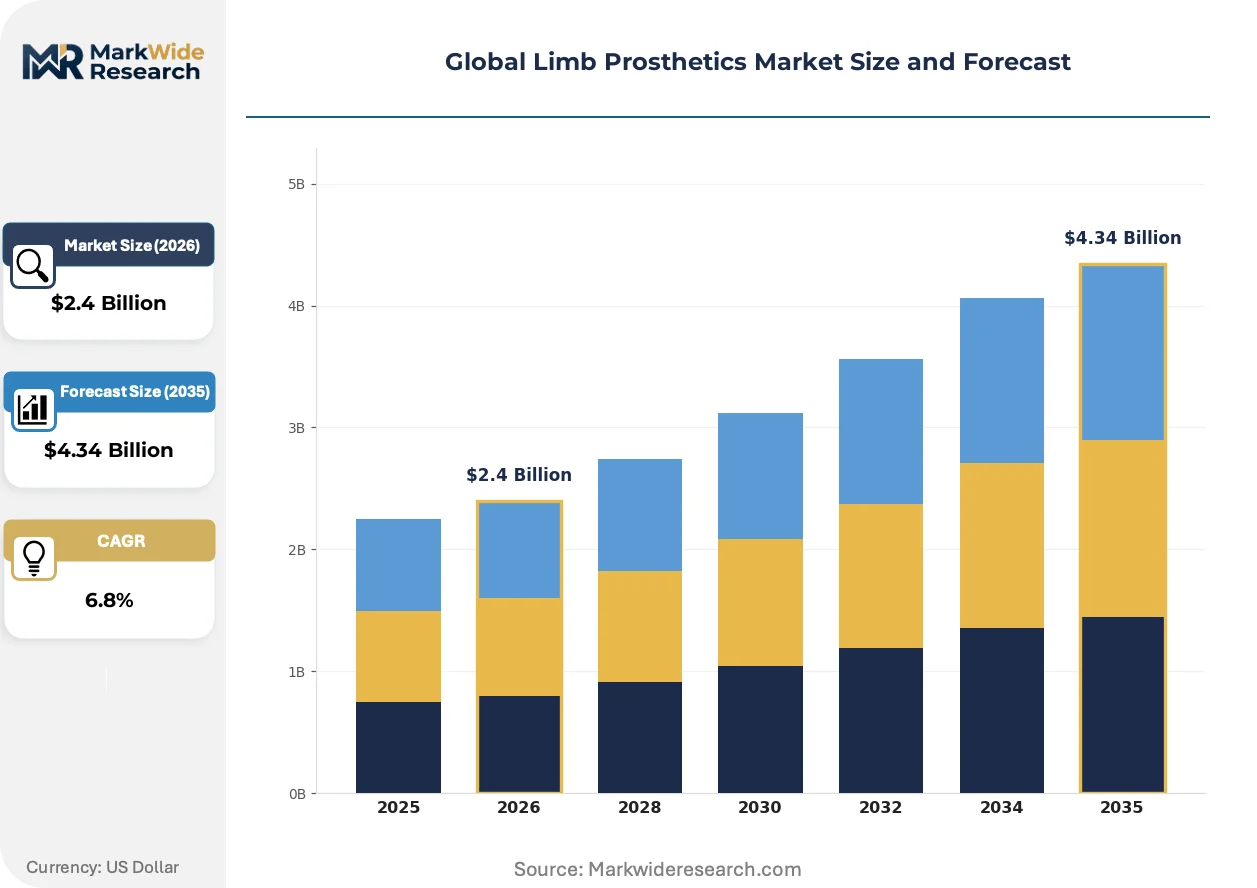
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upper Limb Prosthetics, Lower Limb Prosthetics, Myoelectric Prosthetics, Cosmetic Prosthetics Technology: Suction Suspension, Hydraulic Systems, Microprocessor-Controlled, Body-Powered Application: Trauma Rehabilitation, Congenital Limb Loss, Vascular Disorders, Cancer Amputation End User: Orthopedic Clinics, Rehabilitation Centers, Prosthetic Manufacturers, Research Institutions |
| Companies Covered | Ottobock SE & Co. KGaA, Össur hf, Hanger, Inc., Blatchford Limited, Fillauer LLC, WillowWood Global LLC, Steeper Group, College Park Industries, Proteor SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Limb Prosthetics Market Shifts & Advancements
Pattern recognition algorithms are redefining grip precision benchmarks while regulatory convergence is compressing time-to-market differentials across developed economies.
Myoelectric upper limb systems is fragmenting the historical dominance of body-powered hooks in industrial workplace rehabilitation. German trauma centers are adopting pattern-recognition hand prosthetics at replacement rates threefold higher than passive alternatives. This technology is fragmenting procurement categories previously consolidated under workers compensation durable medical equipment schedules.
EU MDR clinical evidence requirements for Class IIa socket suspension systems are elevating validation costs for European market entry. Manufacturers must now submit prospective biomechanical studies rather than predicate device equivalency demonstrations. Lower limb microprocessor knees face the steepest compliance burden as notified bodies scrutinize cyclic loading durability claims.
After-sales service unbundling is disrupting traditional device-plus-maintenance bundled contracts in United States orthotic and prosthetic channels. Large rehabilitation networks are negotiating separate service level agreements for microprocessor calibration and socket replacement intervals. This behavioral shift concentrates in Medicare Advantage plans where capitated payments incentivize predictive maintenance over episodic device replacement.
Global Limb Prosthetics Market Segmentation
Segmentation in limb prosthetics reveals divergent commercial pathways. Technology tiers command distinct reimbursement codes, while end-user concentration shapes distribution economics across trauma rehabilitation networks.
Product Type:
Lower limb systems dominate domestic procurement in Germany and the United States, while myoelectric upper limb exports concentrate through Japanese geriatric infrastructure and Australian veteran networks.
- Lower Limb Prosthetics:Carbon fiber composite sockets and pylon assemblies withstand cyclic loading exceeding three million gait cycles. Demand concentrates in trauma rehabilitation centers across Germany and the United States, where workers compensation funding creates predictable replacement cycles for weight-bearing devices.
- Myoelectric Prosthetics:Surface electrode arrays capture electromyographic signals to drive servo-actuated grip mechanisms. Japanese municipal long-term care insurance expansions are broadening access for age-related amputations, displacing body-powered hooks in industrial workplace rehabilitation.
- Upper Limb Prosthetics:Passive mechanical and body-powered configurations retain cost advantages in developing markets with limited reimbursement infrastructure.
- Cosmetic Prosthetics:Silicone laminates replicate skin texture and pigmentation for aesthetic restoration in congenital limb absence cases.
Lower limb prosthetics holds the largest share; momentum sits with myoelectric systems.
Technology:
Cost tiers separate premium electromechanical platforms from standard mechanical alternatives, with calibration complexity determining service revenue attachment rates.
- Microprocessor-Controlled:Embedded gyroscopes and accelerometers enable real-time stance-phase damping adjustments. FDA 510(k) submissions for novel pattern recognition algorithms face extended review timelines, compressing competitive windows for mechatronic knee introductions.
- Body-Powered:Cable harness systems translate shoulder girdle movement into terminal device actuation. Procurement in India's tier-2 cities prioritizes these devices due to maintenance simplicity and absence of battery dependency.
- Suction Suspension:Silicone liners with shuttle lock mechanisms create negative pressure interfaces for transfemoral amputations.
- Hydraulic Systems:Pneumatic knee units provide stance-phase stability without electronic components for moderate activity levels.
Microprocessor-controlled systems capture premium pricing; body-powered alternatives retain volume leadership in price-sensitive procurement.
Application:
Volume concentration tracks acute injury epidemiology and vascular disease prevalence, with reimbursement eligibility varying by etiology classification.
- Trauma Rehabilitation:Acute injury volumes and workers compensation funding create predictable procurement cycles in German and United States trauma centers. Carbon fiber blade prosthetics are standardizing in sports medicine protocols for younger amputees.
- Vascular Disorders:Diabetes-related peripheral artery disease drives transtibial amputation volumes in aging populations. Australia's public hospital systems are consolidating multi-limb care into specialized centers of excellence.
- Congenital Limb Loss:Pediatric socket replacement schedules accelerate through growth spurts, creating recurring fabrication demand.
- Cancer Amputation:Oncologic resections require immediate post-surgical fitting protocols distinct from trauma rehabilitation pathways.
Trauma rehabilitation generates the highest absolute device volume; vascular disorders are climbing the fastest as diabetes prevalence expands.
End User:
Customer type determines procurement authority, with captive networks bypassing traditional device wholesalers through direct-to-clinic distribution platforms.
- Rehabilitation Centers:Integrated gait analysis laboratories and prosthetist staffing enable microprocessor knee calibration services. United States Medicare Advantage plans are negotiating separate service level agreements for predictive maintenance.
- Orthopedic Clinics:Physician-owned facilities concentrate initial fitting decisions and referral control in suburban markets.
- Prosthetic Manufacturers:Vertical integration into patient care networks captures margin from device fabrication through follow-up services.
- Research Institutions:Academic medical centers generate clinical evidence for EU MDR Class IIa socket suspension system submissions.
Rehabilitation centers command the highest service revenue attachment; orthopedic clinics retain gatekeeper influence over initial device selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Socket fabrication capacity clusters in Germany and the United States, with mechatronic knee assembly concentrating around Duderstadt and Austin metropolitan zones. Trauma rehabilitation infrastructure drives procurement volume in OECD markets, while Japanese geriatric networks and Australian veteran systems anchor Asia-Pacific demand.
United States
Medicare Advantage capitation models are restructuring orthotic and prosthetic procurement toward predictive maintenance contracts. FDA 510(k) review timelines for electromechanical knee systems have extended substantially for novel pattern recognition algorithms. The Austin-San Antonio corridor hosts concentrated microprocessor knee calibration facilities serving Department of Veterans Affairs networks.
Germany
Workers compensation frameworks in North Rhine-Westphalia and Bavaria generate predictable replacement cycles for carbon fiber composite lower limb systems. EU MDR Class IIa mandates now require prospective biomechanical studies for socket suspension CE marking rather than predicate device equivalency. The Duderstadt-Goettingen cluster anchors Ottobock's integrated mechatronic platform production for European rehabilitation channels.
Japan
Municipal long-term care insurance expansions are broadening myoelectric upper limb access for age-related vascular amputations. METI medical device reimbursement revisions are elevating pattern-recognition hand prosthetics above body-powered alternatives in industrial workplace rehabilitation. Tokyo and Osaka metropolitan areas concentrate prosthetist training programs for mechatronic device calibration.
Australia
Defense procurement programs are consolidating multi-limb trauma care into specialized centers of excellence in Sydney and Melbourne. TGA alignment with ISO 10328 structural testing standards is streamlining market entry for validated socket suspension technologies. The veteran rehabilitation network in Queensland is standardizing carbon fiber blade prosthetics for younger trauma amputees.
India
Tier-2 city procurement prioritizes body-powered devices over microprocessor systems due to maintenance simplicity and battery independence. CDSCO medical device rules are tightening import documentation for electromechanical limb components without established predicate devices. The Bangalore-Hyderabad corridor hosts emerging domestic socket fabrication capacity serving government hospital systems.
Global Limb Prosthetics Market Competitive Landscape
Concentration sits with integrated mechatronic platform specialists and captive patient care networks. Three to five conglomerates with rehabilitation channel integration control premium pricing tiers, while mid-scale fabricators compete on socket customization velocity. Market structure stratifies across technology licensors, carbon fiber composite specialists, and orthotic-prosthetic care networks with direct-to-clinic distribution. Dominant competitive moves include backward integration into patient care networks and technology licensing agreements for pattern recognition algorithms.
Within the integrated platform tier, Ottobock SE & Co. KGaA and Össur hf exemplify divergent specialization strategies—Duderstadt-based conglomerate versus Reykjavik-rooted sports prosthetics anchor. Hanger, Inc. occupies a position representing captive network scale, with United States clinic density creating volume leverage. These three entities collectively illustrate the competitive spectrum: European mechatronic integration, Nordic carbon fiber blade technology, and American direct-to-patient distribution infrastructure.
| Leading Market Players |
|---|
| Ottobock SE & Co. KGaA |
| Össur hf |
| Hanger, Inc. |
| Blatchford Limited |
| Fillauer LLC |
| WillowWood Global LLC |
| Steeper Group |
| College Park Industries |
| Proteor SAS |
| Others |
Supply & Pricing Matrix
Long-term service level agreements between rehabilitation networks and device manufacturers lock in socket replacement schedules and calibration revenue visibility across United States Medicare Advantage plans. These contracts bundle predictive maintenance with device procurement, insulating premium microprocessor knee pricing from spot-market volatility while tethering margin performance to prosthetist labor availability.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing stratification across electromechanical limb systems. Three-tier pricing separates microprocessor-controlled platforms from hydraulic units and body-powered alternatives, with EU MDR Class IIa certification costs elevating European entry thresholds. Pricing pressure stems from thermoplastic copolymer feedstock volatility compressing socket fabrication margins. Developing market procurement shows highest price sensitivity, while Japanese geriatric infrastructure demonstrates lowest sensitivity due to municipal insurance coverage.
Supply Chain Analysis
Inventory cycles for carbon fiber composite prepregs stretch sixteen to twenty-four weeks, constraining socket fabrication responsiveness. Manufacturing gravity centers on Germany, the United States, and Iceland for mechatronic knee assembly and carbon fiber blade production. Supply chains draw from medical-grade polypropylene feedstocks, silicone liner elastomers, and servo-actuator electronics. Single-source vulnerability concentrates in aerospace-grade carbon fiber suppliers. Distribution runs through direct-to-clinic platforms bypassing traditional orthotic and prosthetic wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with pattern recognition algorithm specialization displacing consolidated body-powered hook categories. Myoelectric upper limb demand from Japan's aging vascular amputation population creates addressable niches outside incumbent trauma rehabilitation dominance.
For Market Incumbents: Secure prosthetist training pipeline control through accredited biomechanical engineering partnerships, limiting calibration service capacity for rival microprocessor knee platforms. Deepen backward integration into silicone liner manufacturing to capture margin from EU MDR-mandated socket suspension validation requirements. For New Entrants and Emerging Players: Anchor in India's tier-2 city government hospital systems where body-powered device simplicity matches maintenance infrastructure constraints. Target pediatric congenital limb loss segments with growth-adjustable socket platforms, leveraging direct procurement relationships bypassing rehabilitation network gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward pattern recognition algorithm licensors with FDA 510(k) submission track records and established predicate device pathways. Watch EU MDR notified body backlog clearance rates as inflection indicator for European market entry cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Prosthetist Training Pipeline Partnership | Secures calibration service capacity for microprocessor knee platforms against labor scarcity. |
| FDA 510(k) Predicate Device Pathway | Accelerates electromechanical limb clearance timelines for pattern recognition algorithms. |
| Silicone Liner Backward Integration | Captures margin from EU MDR Class IIa socket suspension clinical evidence mandates. |
| Direct-to-Clinic Distribution Platform | Bypasses traditional orthotic and prosthetic wholesalers in United States Medicare Advantage networks. |
| ISO 10328 Structural Testing Convergence | Enables single-validation market access across 32 regulatory jurisdictions for socket assemblies. |
Research Methodology
Operator-level perspectives from prosthetists, rehabilitation center administrators, biomedical engineers, and GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, EU MDR notified body guidance documents, CMS Medicare reimbursement schedules, and hospital procurement databases. Bottom-up socket fabrication volume estimates triangulated against top-down trauma rehabilitation spending analysis.
Sensitivity analysis tested forecast robustness across alternative reimbursement code revision scenarios and prosthetist labor supply constraints. Segmentation modeling spanned technology tier, application etiology, end-user channel type, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated base-year estimates. Forecast inputs included workers compensation claim volumes and diabetes-related amputation incidence projections.
Material uncertainties — reimbursement code downgrades, thermoplastic copolymer supply disruptions, EU MDR notified body capacity constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding prosthetist training graduation rates and municipal long-term care insurance expansion trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Pancreas Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
Global Wedge Pressure Catheter Market
Medical Devices
AI-enabled Medical Devices Market
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Indonesia Devices Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Bone Allografts Market
Medical Devices
Medical Goggle Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Medical Device Tester Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Automated CPR Devices Market
Medical Devices
Digital Sphygmomanometer Market
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
US Medical Device Outsourcing Market