
 Orthopedic Pedicle Screw Market | 2026-2036
Orthopedic Pedicle Screw Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Pedicle Screw Market Insights
ISO 13485 certification is redrawing competitive boundaries in orthopedic implant manufacturing. Medtronic leverages its vertically integrated supply chain for titanium forging and precision machining. DePuy Synthes anchors its position through deep hospital GPO relationships and surgeon training infrastructure. Globus Medical differentiates via robotics-integrated screw placement platforms that reduce fluoroscopy exposure.
An orthopedic pedicle screw is a threaded metallic implant, typically manufactured from titanium alloy Ti-6Al-4V or surgical-grade stainless steel via CNC turning and thread grinding, designed to anchor rods to the vertebral pedicle for spinal stabilization. Polyaxial screws dominate procedural volumes due to intraoperative adjustability, while expandable systems capture premium pricing in osteoporotic bone applications where pullout resistance determines clinical success. Titanium material segments command margin premiums over stainless steel equivalents, though carbon fiber-reinforced PEEK composites are penetrating deformity correction cases demanding radiolucency.
FDA 510(k) premarket notification and EU MDR technical documentation requirements are extending product development timelines and consolidating market access among well-capitalized manufacturers. Japan's PMDA and China's NMPA impose additional clinical testing burdens that favor firms with dedicated regulatory affairs teams in Tokyo and Beijing. Stakeholders must monitor reimbursement coding shifts for minimally invasive spine procedures and position manufacturing capacity to serve markets where health technology assessment bodies are tightening evidence requirements for implant survival rates.
Market Dynamics
The orthopedic pedicle screw market is experiencing structural compression from EU MDR conformity assessment requirements, which are extending technical documentation timelines and consolidating manufacturing capacity among firms with dedicated notified body relationships.
Growth Catalysts
- Ambulatory surgical center expansion:CMS reimbursement coding for outpatient spinal fusion procedures in the United States is redirecting procedural volumes away from inpatient settings.
- Ti-6Al-4V alloy adoption:Titanium's superior osseointegration profile and MRI compatibility are displacing stainless steel constructs in deformity correction applications.
- REACH compliance:European chemical safety frameworks are accelerating substitution of cobalt-chrome bearing surfaces in adjacent motion-preserving implants.
Market Restraints
- Titanium sponge supply concentration:Russian and Ukrainian feedstock disruptions have tightened titanium alloy billet availability for precision forging operations.
- EU MDR technical documentation:Extended conformity assessment timelines at notified bodies are delaying product launches by 18-24 months for mid-cap manufacturers.
- Carbon fiber-reinforced PEEK substitution:Radiolucent composite constructs are capturing volume in adolescent idiopathic scoliosis cases where metal artifact reduction drives imaging workflow efficiency.
Strategic Opportunities
- Robotics-integrated placement:Convergence of intraoperative navigation with autonomous screw insertion is reducing fluoroscopy exposure in minimally invasive lumbar fusion.
- Japan's PMDA fast-track pathway:Sakigake designation for breakthrough spine devices offers abbreviated clinical trial requirements for computer-assisted surgical systems.
- Direct-to-hospital consignment models:Implant vendors are bypassing traditional distributor networks to capture inventory carrying cost savings in German hospital procurement.
Industry Challenges
- ISO 13485 auditor availability:Notified body capacity constraints are extending certification renewal cycles and creating compliance timeline uncertainty for multi-site manufacturers.
- Surgeon training infrastructure:Cadaveric lab access and proctoring networks require sustained capital deployment to support adoption of expandable screw systems in osteoporotic bone applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Pedicle Screw Market |
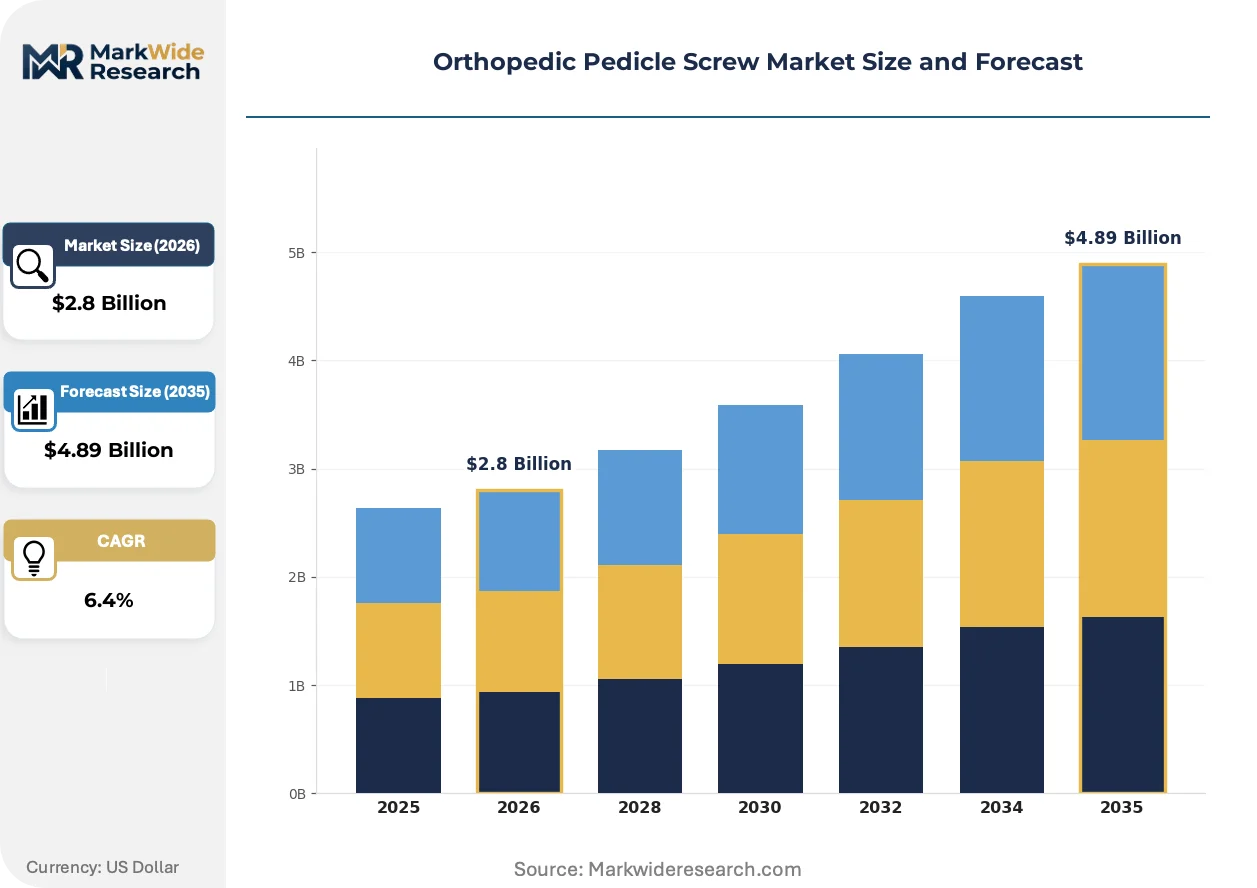
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoaxial, Polyaxial, Expandable, Cannulated Material: Stainless Steel, Titanium, Carbon Fiber, Plastic Application: Spinal Fusion, Deformity Correction, Trauma Treatment, Tumor Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Medtronic, DePuy Synthes, Stryker, Zimmer Biomet, Globus Medical, B. Braun, Johnson & Johnson, Orthofix, Alphatec Spine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Pedicle Screw Market Trends and Innovations
Spinal implant engineering is converging with surgical robotics and advanced materials science, compressing the gap between mechanical fixation and biological integration while reshaping how hospitals evaluate total cost of ownership.
Expandable pedicle screw technology is miniaturizing. These devices feature internal expansion mechanisms that deploy within the vertebral body to enhance pullout resistance in compromised bone. Ambulatory surgery centers in the United States are adopting expandable systems at twice the rate of conventional polyaxial constructs for osteoporotic patient populations. The technology is miniaturizing surgical footprints by enabling percutaneous placement through smaller incisions while maintaining biomechanical stability equivalent to larger-diameter conventional screws.
EU MDR Article 10 technical documentation requirements are extending product development timelines. Manufacturers must now submit clinical evaluation reports with post-market surveillance data spanning the full device lifecycle. Small-to-mid cap implant firms without established quality management systems are exiting the European market rather than absorbing notified body audit costs. German and French hospital purchasing consortia are consolidating supplier panels to three preferred vendors per implant category.
Hospital procurement departments are unbundling implant pricing from instrumentation and biologics. United States health systems are negotiating separate contracts for pedicle screw constructs, rod systems, and interbody cages rather than accepting bundled spine platform pricing. GPOs are deploying utilization analytics to benchmark surgeon-specific implant costs against peer cohorts. This shift is most visible in California and Texas integrated delivery networks where value-based care contracts create direct financial exposure to implant expenditure variation.
Orthopedic Pedicle Screw Market Segmentation
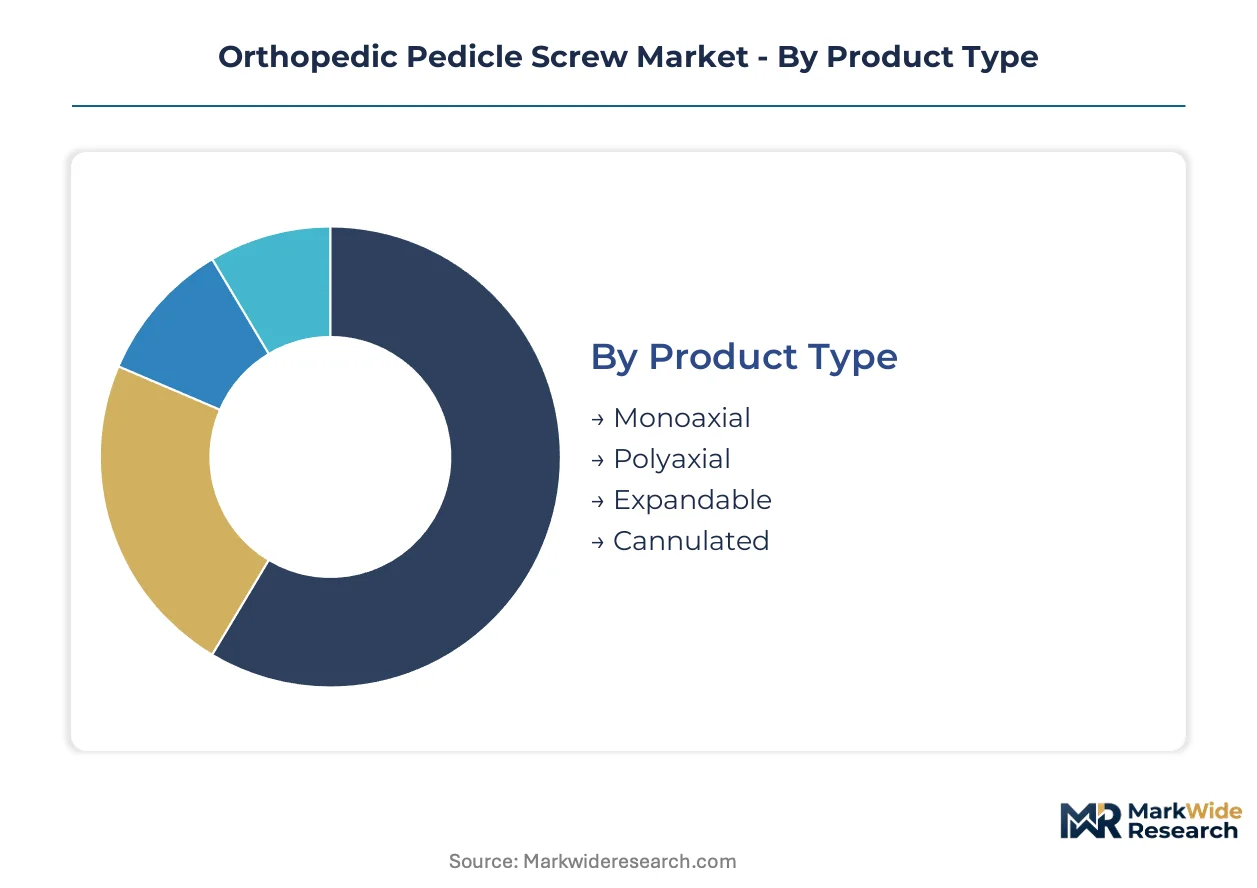
Orthopedic pedicle screw segmentation reveals how material substitution and procedural site migration are restructuring procurement patterns. Manufacturers must align product portfolios with the divergence between high-volume spinal fusion and premium deformity correction applications.
Product Type:
Expandable and cannulated constructs face intensifying substitution pressure from navigation-enabled minimally invasive techniques that reduce hardware dependence.
- Polyaxial:Multi-planar head articulation permits rod alignment without screw repositioning, reducing operative time in multi-level constructs. United States ambulatory surgical centers now specify polyaxial systems in over half of lumbar fusion cases where same-day discharge protocols demand efficiency.
- Expandable:Internal expansion mechanisms deploy within vertebral bodies to enhance pullout resistance in osteoporotic bone. German hospital purchasing consortia are consolidating supplier panels around expandable platforms for geriatric trauma populations where bone quality compromises conventional fixation.
- Monoaxial:Fixed-angle head design delivers maximum rigidity in deformity correction constructs requiring precise sagittal plane control.
- Cannulated:Central lumen accommodates guidewire placement for percutaneous insertion techniques in minimally invasive lateral approaches.
Polyaxial systems anchor the volume base while expandable configurations gain share at the steepest rate.
Material:
Cost tier stratification separates premium titanium alloys from commodity stainless steel as MRI compatibility becomes a non-negotiable specification.
- Titanium:Ti-6Al-4V alloy exhibits superior osseointegration kinetics and eliminates magnetic resonance artifact, commanding price premiums in deformity correction cases requiring postoperative surveillance imaging. China's NMPA has tightened biocompatibility testing requirements that favor titanium over cobalt-chrome alternatives in pediatric applications.
- Carbon Fiber:Radiolucent composite construction eliminates metal artifact in intraoperative navigation and postoperative CT assessment. United States adolescent idiopathic scoliosis centers are transitioning to carbon fiber-reinforced PEEK constructs to preserve imaging workflow efficiency across multi-year follow-up protocols.
- Stainless Steel:Surgical-grade 316L variants retain cost advantage in trauma stabilization cases where temporary fixation precedes hardware removal.
- Plastic:Bioabsorbable polymer screws address pediatric deformity applications where skeletal growth demands eventual implant dissolution.
Titanium dominates revenue contribution while carbon fiber expands most quickly among academic medical centers.
Application:
Procedure volume concentrates in spinal fusion while margin expansion tracks deformity correction complexity.
- Spinal Fusion:Interbody and posterolateral fusion procedures consume the majority of pedicle screw placements, with United States CMS reimbursement coding shifts redirecting volumes toward outpatient settings. Ambulatory surgical center accreditation standards now mandate specific implant tracking systems that favor suppliers with established consignment logistics.
- Deformity Correction:Three-dimensional osteotomy constructs demand highest screw density and specialized reduction instruments, generating premium pricing in adolescent and adult spinal deformity. Japan's PMDA Sakigake fast-track pathway has accelerated approval timelines for computer-assisted placement systems targeting this indication.
- Trauma Treatment:Fracture stabilization applications prioritize rapid insertion and provisional fixation over long-term biomechanical optimization.
- Tumor Surgery:Oncologic resection and reconstruction cases require extended construct durability under radiation therapy conditions.
Spinal fusion procedures absorb the greatest unit volume while deformity correction drives average selling price expansion.
End User:
Customer type segmentation maps directly to procurement sophistication and inventory management requirements.
- Hospitals:Integrated delivery networks in California and Texas are unbundling implant pricing from instrumentation and biologics, deploying utilization analytics to benchmark surgeon-specific costs against peer cohorts. Value-based care contracts create direct financial exposure to expenditure variation.
- Ambulatory Surgical Centers:Outpatient spinal fusion eligibility under United States CMS reimbursement codes has accelerated adoption of streamlined screw systems with reduced instrument tray footprints. These facilities prioritize consignment inventory models that eliminate capital tied up in sterile stock.
- Specialty Clinics:Orthopedic spine-focused practices concentrate high-complexity deformity cases requiring specialized expandable and navigation-compatible platforms.
- Research Institutions:Academic medical centers drive early adoption of robotic placement systems and novel biomaterial constructs under investigational protocol frameworks.
Hospitals retain the largest procurement scale while ambulatory surgical centers climb the fastest as procedural site migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States, Germany, and China drive the majority of purchasing volume for titanium alloy constructs. Each market presents distinct regulatory hurdles and reimbursement structures that reshape competitive positioning.
United States
Ambulatory surgical centers now absorb over half of lumbar fusion procedural volume as CMS reimbursement coding enables outpatient spinal fusion. FDA 510(k) clearance pathways maintain streamlined market access for titanium alloy pedicle screws. The Texas Medical Center cluster in Houston anchors surgeon training infrastructure for expandable screw systems.
Germany
Hospital purchasing consortia in Baden-Württemberg and Bavaria consolidate supplier panels to three preferred vendors per implant category. EU MDR technical documentation requirements extend conformity assessment timelines by 18-24 months. The Tuttlingen surgical instrument cluster concentrates precision forging operations for titanium billet processing.
China
NMPA biocompatibility testing requirements favor titanium constructs over cobalt-chrome alternatives in pediatric deformity applications. Provincial procurement consortia in Jiangsu and Guangdong deploy volume-based tendering that compresses margin structures. The Suzhou industrial park hosts CNC machining operations serving domestic implant manufacturers.
Japan
PMDA Sakigake fast-track designation accelerates approval timelines for computer-assisted surgical systems targeting deformity correction. Aging demographics expand the addressable patient population for osteoporotic bone fixation. The Kobe medical device cluster concentrates regulatory affairs expertise for spine implant submissions.
Switzerland
Swissmedic maintains stringent quality benchmarks for titanium alloy sourcing that favor manufacturers with ISO 13485-certified supply chains. Private hospital networks in Zurich and Geneva prioritize premium-priced expandable systems for geriatric trauma populations. The Bern region anchors precision machining capabilities for thread grinding operations.
Orthopedic Pedicle Screw Market Competitive Landscape
Player mix skews toward diversified medtech conglomerates with vertically integrated titanium forging capabilities. The vendor base concentrates among firms with dedicated notified body relationships and established hospital GPO contracts. Two strategic archetypes dominate: robotics-integrated placement platform developers and precision forging specialists with captive alloy supply. Competitive moves center on M&A for navigation technology assets and capacity expansion into ambulatory surgical center consignment logistics.
Within the diversified medtech tier, Medtronic, DePuy Synthes, and Globus Medical exemplify contrasting strategic positions. Medtronic represents the vertically integrated archetype with in-house titanium forging and precision machining operations. DePuy Synthes occupies a position anchored through deep hospital GPO relationships and surgeon training infrastructure. Globus Medical sits within the robotics-integrated placement vector, reducing fluoroscopy exposure in minimally invasive procedures. Each firm illustrates how regulatory affairs scale and manufacturing control separate tier-one positioning from mid-cap challengers.
| Leading Market Players |
|---|
| Medtronic |
| DePuy Synthes |
| Stryker |
| Zimmer Biomet |
| Globus Medical |
| B. Braun |
| Johnson & Johnson |
| Orthofix |
| Alphatec Spine |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day titanium billet lead times compress pricing power for mid-cap manufacturers lacking long-term sponge contracts, while German hospital purchasing consortia exploit inventory visibility to extract volume discounts from suppliers with stranded consignment stock.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange titanium sponge pricing dominate procurement between billet forgers and implant OEMs, with pass-through clauses adjusting quarterly. Three-tier pricing structure across premium Ti-6Al-4V, standard stainless steel, and economy cannulated configurations separates academic medical centers from ambulatory surgical centers from trauma hospitals. Pricing pressure stems from United States GPO utilization analytics that benchmark surgeon-specific expenditure against peer cohorts. Ambulatory surgical centers exhibit highest price sensitivity due to thin procedural margins under CMS reimbursement codes.
Supply Chain Analysis
Just-in-time consignment models prevail in United States ambulatory surgical centers, while German hospital systems maintain strategic stockpiles of expandable screw sets for geriatric trauma populations. Titanium sponge processing concentrates in Russia, Ukraine, and Japan, with precision forging operations clustering in Germany's Tuttlingen region and China's Suzhou industrial park. CNC machining capacity draws from Ti-6Al-4V billet feedstock vulnerable to geopolitical disruption. Single-source vulnerability runs through Ukrainian sponge suppliers subject to export restriction. Distribution runs through hospital GPO contracts and direct-to-facility consignment logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotics-integrated placement platforms are reconstituting this market around ecosystem economics, where screw hardware interoperability with navigation systems determines vendor lock-in more than implant unit pricing.
For Market Incumbents: Consolidate titanium forging capacity through backward integration into sponge supply or captive billet partnerships, insulating against Russian-Ukrainian feedstock disruption. Deepen ISO 13485-certified manufacturing footprints in Germany and Switzerland to satisfy EU MDR notified body requirements. Defend against carbon fiber-reinforced PEEK substitution by embedding Ti-6Al-4V constructs within robotics platforms that require metallic registration markers for navigation accuracy. For New Entrants and Emerging Players: Lead with navigation-compatible screw designs for Japan's PMDA Sakigake fast-track pathway, where abbreviated clinical trial requirements lower regulatory capital barriers. Target osteoporotic bone applications in German hospital purchasing consortia seeking second-source expandable platforms. Pursue direct-to-hospital consignment models that bypass distributor markups and capture inventory carrying cost savings. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EU MDR technical documentation requirements are forcing mid-cap exits and concentrating manufacturing capacity among notified body-anchored firms. Acquisition targets include precision forging specialists with captive alloy supply and robotics navigation assets that enable fluoroscopy reduction. Watch for inflection when ambulatory surgical center procedural volume crosses threshold share of lumbar fusion cases.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Extended conformity assessment timelines favor manufacturers with dedicated notified body relationships in Germany. |
| Robotics Platform Integration | Navigation-compatible screw designs reduce fluoroscopy exposure in minimally invasive lumbar fusion procedures. |
| Titanium Sponge Supply Security | Captive billet sourcing insulates forging operations against Russian-Ukrainian feedstock disruption. |
| Ambulatory Surgical Center Consignment Logistics | Direct-to-facility inventory models eliminate distributor markups and capture carrying cost savings. |
| Japan PMDA Sakigake Pathway Utilization | Fast-track designation accelerates approval timelines for computer-assisted surgical systems. |
Research Methodology
Initial hypotheses were tested against primary input from orthopedic spine surgeons, hospital purchasing committee directors, GPO contracts managers, and biomedical engineers, and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS reimbursement coding updates, and hospital procurement records. Bottom-up segmentation modeling triangulated with top-down macroeconomic indicators across the analysis window.
Variance decomposition separated volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, material composition, application indication, procedural site, and end-user procurement sophistication. CAGRs were derived from fitted growth curves anchored to procedural volume trajectories and reimbursement policy shifts. Forecast inputs incorporated titanium sponge price volatility indices and ambulatory surgical center accreditation standards.
The analysis sits within stated boundaries; outcomes outside stable EU MDR notified body capacity or sustained CMS outpatient fusion reimbursement would require recalibration. Forecasts reflect assumptions regarding titanium alloy biocompatibility testing requirements and robotics platform adoption curves. Revision becomes warranted when carbon fiber-reinforced PEEK substitution crosses threshold penetration in adolescent deformity cases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Saudi Arabia Spinal Surgery Devices Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
Knee Cartilage Repair Market
Orthopedic Devices
Physiotherapy Devices Market
Orthopedic Devices
Kyphoscoliosis Treatment Market
Orthopedic Devices
Shoulder Arthroplasty Market
Orthopedic Devices
Orthopedic Insole Manufacturing Thermosealer Market
Orthopedic Devices
Europe Knee Cartilage Repair Market
Orthopedic Devices
South Korea Spinal Surgery Devices Market
Orthopedic Devices
Global Shockwave Therapy Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Global Patient Lateral Transfer Devices Market
Orthopedic Devices
Global Patient Positioning Devices Market
Orthopedic Devices
Hip Reconstruction Devices Market
Orthopedic Devices
Global Acetabular Cups Market
Orthopedic Devices
Patients Repositioning and Offloading Device Market