
 FFC/FPC Jumper Cables Market | 2026-2036
FFC/FPC Jumper Cables Market Size, Share, and Industry Trends Forecast 2026-2036
FFC/FPC Jumper Cables Market Foresight
Market Overview
East Asian flexible circuit producers is repositioning capacity toward high-layer-count FPC substrates for automotive and medical applications. Molex leverages its connector-cable integration expertise to dominate North American automotive design-ins. TE Connectivity sustains technology leadership through precision lamination and roll-to-roll manufacturing scale. Sumitomo Electric anchors Japanese supply chains with captive polyimide film production and vertical control over critical raw materials.
Product and Technology Insights
FFC/FPC jumper cables are flat, flexible interconnects comprising laminated copper conductors between polyimide or polyester dielectric layers, engineered for space-constrained signal routing in electronic assemblies. Shielded FPC variants command premium positioning due to electromagnetic compatibility requirements in automotive camera modules and medical imaging equipment. Consumer electronics applications remain the largest volume pool, though automotive applications represent the fastest-growing segment as advanced driver-assistance systems multiply sensor count per vehicle. ZIF connectors dominate design preference for serviceable assemblies, while SMT connectors gain share in cost-optimized consumer products where rework frequency is minimal.
Regulatory and Strategic Outlook
REACH restrictions on halogenated flame retardants and RoHS substance limits reshape material formulation requirements for European-bound shipments, while China's GB standards and MIIT regulations govern domestic electromagnetic emissions testing. FDA 21 CFR Part 820 quality system requirements and ISO 13485 certification create barrier-to-entry conditions for medical device cable suppliers in the United States and European Union markets. Stakeholders must monitor evolving automotive functional safety standards and polymer supply chain certification requirements as qualification cycles lengthen and OEM traceability mandates tighten.
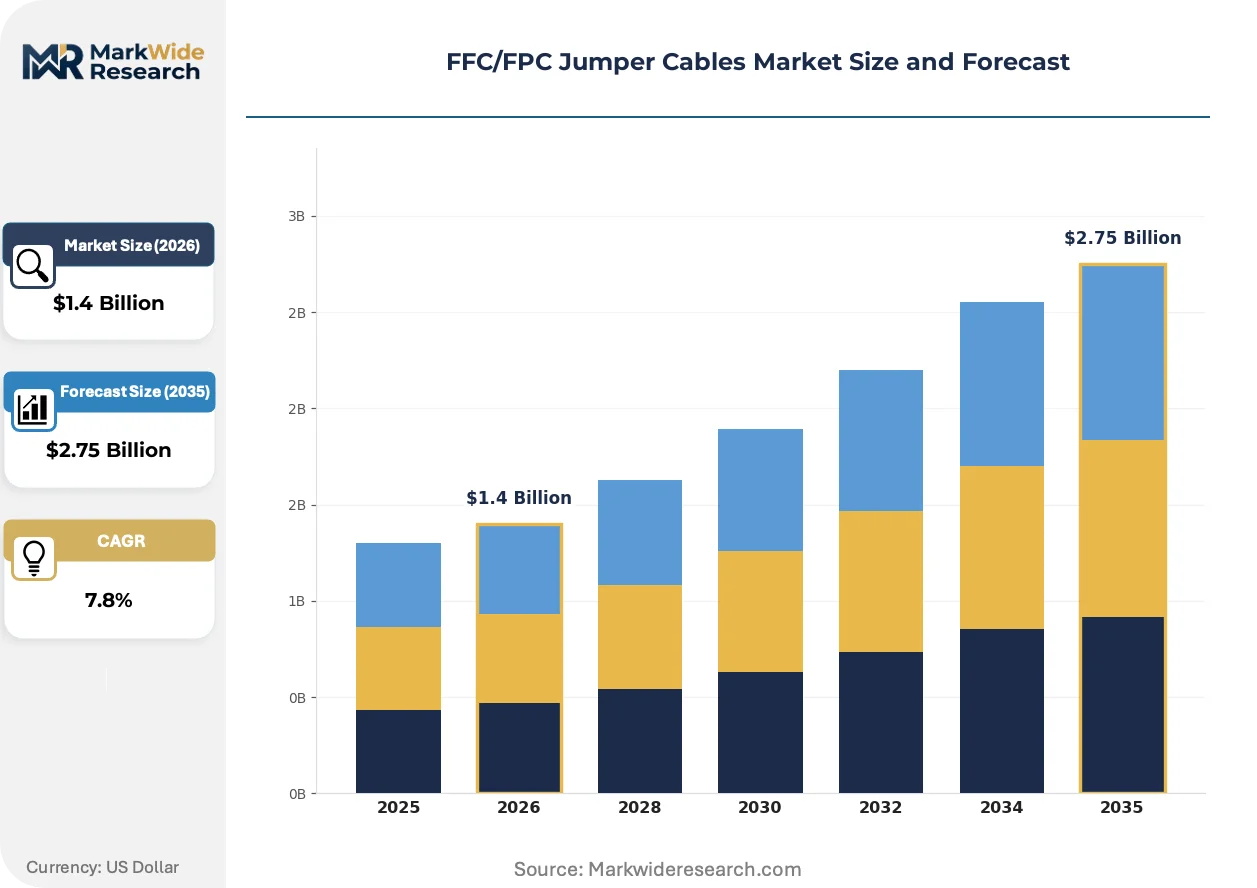
Market Dynamics
Automotive electrification is compressing interconnect density requirements while tightening electromagnetic compatibility specifications, forcing cable producers to recalibrate lamination precision and shielding architectures against shorter OEM qualification cycles.
Growth Catalysts
- MIIT dual carbon mandates:China's tightening energy efficiency standards for polyimide film production are accelerating factory automation investments and yield improvements across East Asian substrate lines.
- Camera module proliferation:Advanced driver-assistance systems in electric vehicles now integrate twelve to sixteen imaging sensors per platform, each requiring shielded FPC jumpers for high-speed data transmission.
- Roll-to-roll lamination advances:Precision coating technologies enable sub-25-micron dielectric layers that preserve signal integrity in medical endoscopes and wearable diagnostic patches.
Market Restraints
- Polyimide feedstock concentration:Captive film production in Japan and South Korea limits second-tier cable assemblers' negotiating leverage on raw material costs.
- REACH substance restrictions:ECHA's evolving halogenated flame retardant limits force European-bound shipments through costly reformulation and retesting protocols.
- Copper conductor gauge floors:Mechanical durability requirements in automotive underhood applications prevent migration to ultra-fine conductors that would reduce material intensity.
Strategic Opportunities
- Indian electronics manufacturing clusters:PLI scheme incentives for smartphone and component production are attracting FPC assembly investments around Chennai and Noida.
- 5G mmWave infrastructure:Base station antenna arrays demand low-loss flexible interconnects between RF modules and phased-array elements, opening a volume pool beyond consumer electronics.
- FDA 21 CFR Part 820 alignment:Medical device OEMs seeking dual US-EU market access favor suppliers pre-qualified to FDA quality system requirements, creating premium positioning for compliant cable producers.
Industry Challenges
- Functional safety certification timelines:ISO 26262 qualification for automotive signal paths now extends eighteen to twenty-four months, straining working capital for mid-scale producers.
- Legacy connector interoperability:Industrial automation retrofit projects require backward-compatible ZIF interfaces that constrain pitch miniaturization roadmaps.
- Cleanroom lamination capacity:Medical-grade FPC production demands Class 1000 or better environments that absorb disproportionate capex relative to standard consumer cable lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FFC/FPC Jumper Cables Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard FFC, Standard FPC, Shielded FFC, Shielded FPC Application: Consumer Electronics, Automotive Applications, Medical Devices, Industrial Equipment Connector Type: ZIF Connectors, Non-ZIF Connectors, Press-Fit Connectors, SMT Connectors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors |
| Companies Covered | Molex, TE Connectivity, Sumitomo Electric, Amphenol, Johnson Electric, Samtec, 3M, Yamaichi Electronics, Würth Elektronik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FFC/FPC Jumper Cables Market Shifts & Advancements
Flexible circuit manufacturing is bifurcating between commodity consumer volumes and precision automotive-medical tiers, with process control and material traceability becoming the primary differentiation vectors rather than raw conductor counts.
Liquid crystal polymer substrates are absorbing thermal management requirements in power-dense automotive modules where traditional polyimide films degrade under sustained 150°C operation. Tier-1 harness suppliers in Germany and South Korea are qualifying LCP-based jumpers for battery management systems and inverter control boards. This material transition is compressing the addressable market for standard polyimide constructions in underhood applications while expanding premium substrate demand.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing European cable producers to abandon certain plasma etching chemistries used in microvia formation for high-layer-count FPCs. Alternative laser drilling and chemical routing processes are gaining industrial acceptance despite throughput penalties. Medical imaging equipment manufacturers in the Netherlands and Switzerland are most affected, as their multi-layer rigid-flex assemblies require dense via fields that previously relied on fluorinated process gases.
Automotive OEMs are consolidating approved vendor lists for interconnect suppliers, compressing the number of qualified FPC sources per platform from six to eight down to two or three strategic partners. Tier-2 cable assemblers in Michigan and Bavaria report extended qualification audits and joint development contract requirements that favor producers with captive polymer film supply and in-house connector molding. This concentration is most visible in North American electric vehicle programs where single-source accountability for signal integrity failures has become a non-negotiable procurement criterion.
FFC/FPC Jumper Cables Market Segmentation
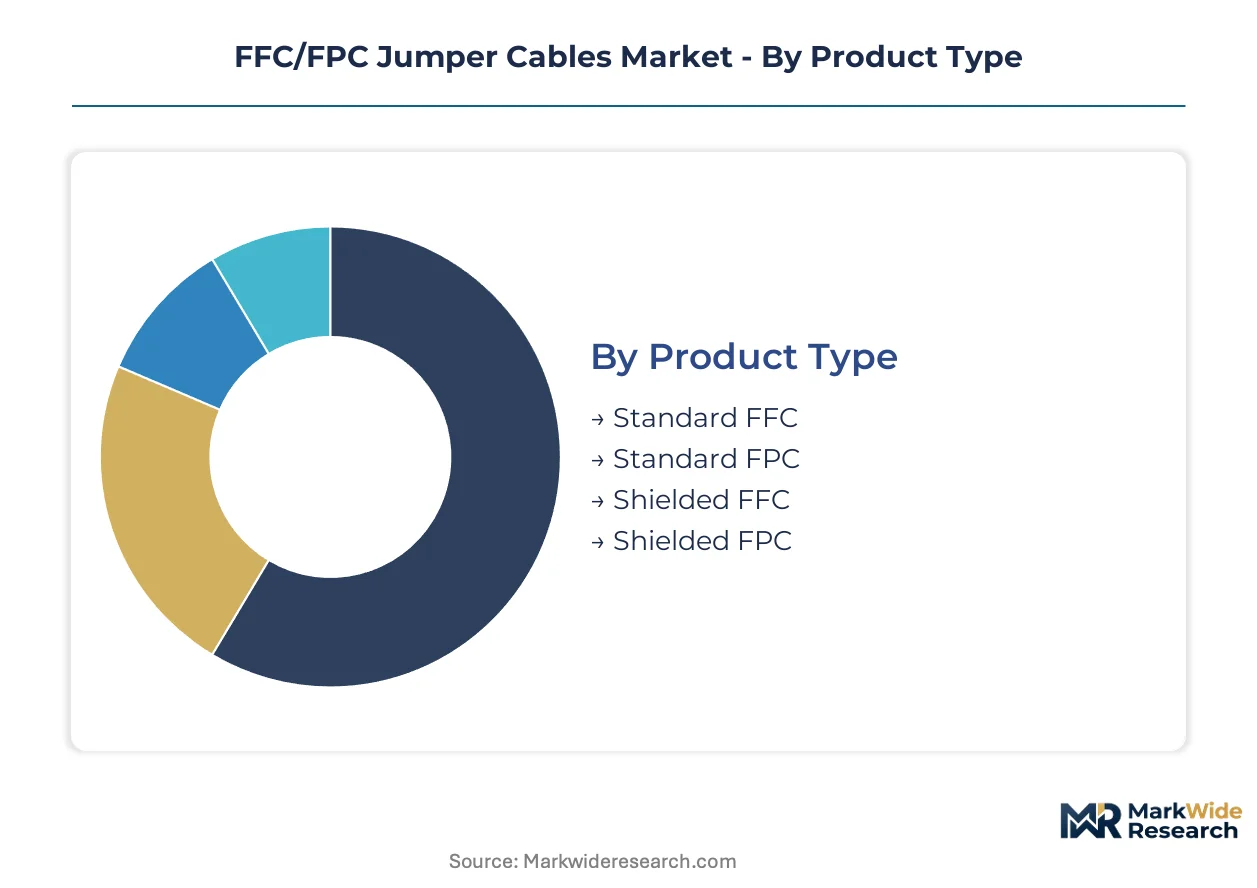
FFC/FPC jumper cable configurations diverge sharply between high-volume consumer electronics and precision automotive-medical tiers. Product architecture, connector selection, and supply chain positioning determine margin capture across each segment boundary.
Product Type:
Customization intensity spans from commodity laminated constructions to engineered shielded variants with embedded electromagnetic compatibility layers.
- Shielded FPC:Copper-foil or silver-ink shielding layers sandwich the conductor stack to attenuate interference in high-speed signal environments. Automotive camera modules and medical imaging heads in Germany and Japan specify these constructions for ADAS and endoscopic platforms where signal integrity failures carry liability exposure. MIIT electromagnetic emissions testing in China now requires shielded architectures for domestic EV programs.
- Shielded FFC:Simpler laminated shielding suits cost-constrained applications needing moderate noise suppression. Korean display panel manufacturers deploy these for internal flat-screen interconnects where external interference is predictable and controlled.
- Standard FPC:Unshielded polyimide constructions dominate consumer electronics with tight bend-radius requirements.
- Standard FFC:Polyester-dielectric variants serve lowest-cost applications with minimal flex-cycle demands.
Most installed capacity flows through Standard FFC. Expansion is steepest in Shielded FPC.
Application:
Volume concentration sits with consumer electronics, while qualification complexity and per-unit value concentrate in regulated end-uses.
- Automotive Applications:Battery management systems, inverter control boards, and surround-view camera arrays demand automotive-grade polyimide or liquid crystal polymer substrates rated for sustained 150°C operation. OEM qualification cycles now extend eighteen to twenty-four months under ISO 26262 functional safety mandates, favoring suppliers with captive film production and in-house connector molding in Michigan and Bavaria.
- Medical Devices:FDA 21 CFR Part 820 and ISO 13485 certification requirements create barrier-to-entry conditions for wearable diagnostic patches, endoscopic equipment, and imaging heads. Cleanroom lamination to Class 1000 standards absorbs disproportionate capital expenditure relative to consumer cable lines.
- Consumer Electronics:Smartphones, tablets, and laptops drive the largest unit volumes with shortest product lifecycles and sharpest cost compression.
- Industrial Equipment:Factory automation retrofit projects require backward-compatible ZIF interfaces that constrain pitch miniaturization roadmaps.
Unit volume concentrates in Consumer Electronics. Value-per-meter and margin expansion concentrate in Automotive Applications.
Connector Type:
Serviceability requirements and rework frequency determine connector architecture selection across assembly tiers.
- ZIF Connectors:Zero-insertion-force mechanisms with actuator latches enable field-replaceable assemblies without solder rework. Medical device OEMs and industrial automation integrators specify these for serviceable equipment where downtime costs exceed connector price premiums.
- SMT Connectors:Surface-mount configurations suit cost-optimized consumer products where rework frequency is minimal and assembly automation drives unit economics. Chinese smartphone contract manufacturers in Shenzhen and Dongguan specify these for high-volume SMT lines.
- Non-ZIF Connectors:Friction-fit alternatives occupy mid-tier applications balancing cost and reliability.
- Press-Fit Connectors:Compliant-pin interfaces serve backplane and rigid-flex assemblies needing solderless board attachment.
Design preference tilts toward ZIF Connectors in serviceable assemblies. SMT Connectors gain share fastest in cost-optimized consumer tiers.
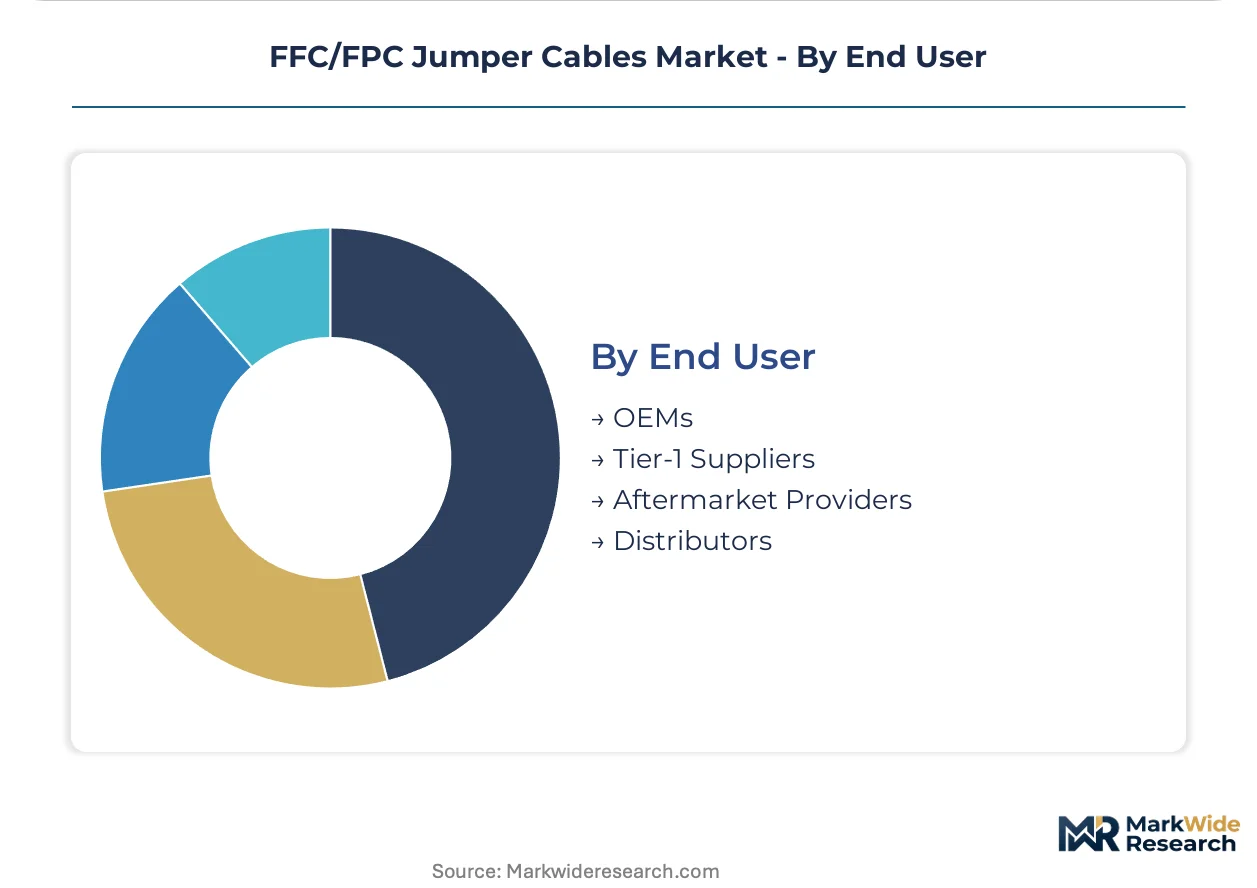
End User:
Procurement authority and technical specification control shift dramatically across the OEM-to-aftermarket spectrum.
- OEMs:Original equipment manufacturers in electric vehicle platforms and medical imaging systems consolidate approved vendor lists to two or three strategic partners per platform. Single-source accountability for signal integrity failures has become non-negotiable in North American EV procurement.
- Tier-1 Suppliers:Harness and module integrators in Germany and South Korea qualify cable producers for joint development contracts requiring captive polymer supply and traceability documentation.
- Distributors:Catalog and value-added distributors serve mid-scale electronics manufacturers with standard pitch configurations and shorter lead times.
- Aftermarket Providers:Repair and replacement channels address legacy industrial equipment with backward-compatible connector interfaces.
Specification control concentrates with OEMs. Channel expansion runs fastest through Tier-1 Suppliers as platform consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting FFC/FPC assembly investments toward jurisdictions with streamlined electromagnetic emissions certification and polymer feedstock access, compressing European-bound production while expanding East Asian and select South Asian capacity.
China
Domestic electric vehicle platforms from BYD and NIO are absorbing shielded FPC volumes for camera module arrays at rates exceeding prior consumer electronics cycles. MIIT dual carbon mandates are tightening energy efficiency benchmarks for polyimide film extrusion lines, forcing substrate producers toward automated lamination upgrades. The Yangtze River Delta cluster around Suzhou and Kunshan concentrates the highest cleanroom-grade FPC capacity serving medical device exporters.
South Korea
Samsung Display and LG Innotek are vertically integrating FFC supply for OLED panel production, reducing external procurement for internal interconnects. MFDS medical device quality regulations govern export-bound diagnostic cable assemblies, creating certification overhead for non-captive producers. The Gyeonggi-Seoul corridor hosts the densest concentration of roll-to-roll lamination equipment serving both display and semiconductor test socket applications.
Germany
BMW and Mercedes-Benz EV platforms are consolidating approved vendor lists to two strategic FPC partners per battery management system program, extending qualification timelines. ECHA REACH restrictions on halogenated flame retardants are forcing reformulation of European-bound cable constructions, adding retesting costs. Bavarian harness integrators in Ingolstadt and Munich are demanding captive polyimide supply and ISO 26262 traceability documentation as non-negotiable entry criteria.
United States
Ford and GM electric vehicle programs are sourcing shielded FPC jumpers for autonomous sensor suites under single-source accountability contracts that favor producers with in-house connector molding. FDA 21 CFR Part 820 quality system requirements create barrier-to-entry conditions for medical device cable suppliers seeking dual US-EU market access. Michigan-based Tier-2 assemblers report eighteen-month ISO 26262 qualification cycles straining working capital reserves.
India
PLI scheme incentives for smartphone and component production are attracting FPC assembly investments around Chennai and Noida, though polyimide film remains import-dependent. BIS electromagnetic emissions testing standards are converging with EU frameworks, reducing dual-certification burdens for export-oriented producers. Tamil Nadu's electronics manufacturing clusters are prioritizing SMT-compatible FFC configurations for high-volume contract assembly lines.
FFC/FPC Jumper Cables Market Competitive Landscape
Japanese and South Korean producers anchor the premium substrate tier; Chinese specialists hold volume-driven consumer electronics positions. Market structure tilts toward consolidation as automotive OEMs compress approved vendor lists from six sources to two strategic partners per platform. Three archetypes dominate: integrated polymer-to-cable producers with captive film supply, precision laminators serving medical-automotive qualification tiers, and scale-driven assemblers feeding consumer electronics contract manufacturers. Dominant competitive moves include backward integration into polyimide film production and joint development contracts with Tier-1 harness integrators requiring traceability documentation.
Among connector-cable integration specialists, Molex and TE Connectivity exemplify the premium-tier archetype through their North American automotive design-in positions. Sumitomo Electric occupies a distinct position as a Japanese integrated producer with upstream control over critical raw materials. These three companies represent the consolidation trajectory as OEM qualification cycles lengthen and single-source accountability becomes standard procurement protocol.
| Leading Market Players |
|---|
| Molex |
| TE Connectivity |
| Sumitomo Electric |
| Amphenol |
| Johnson Electric |
| Samtec |
| 3M |
| Yamaichi Electronics |
| Würth Elektronik |
| Others |
Supply & Pricing Matrix
Family-owned Japanese mid-caps with captive polyimide film production anchor premium-tier pricing discipline, while PE-rolled Chinese assemblers compete on volume scale. This ownership split concentrates supply-side bargaining power among integrated producers and compresses margins for second-tier cable converters serving automotive OEMs.
Pricing Analysis
Distributor markups of 15-25% separate catalog pricing from direct-to-OEM contract rates for shielded FPC volumes. Three-tier pricing structure across automotive-grade, medical-grade, and consumer-grade certification levels reflects ISO 26262 traceability costs and FDA 21 CFR Part 820 compliance investments. Cost compression in standard FFC tiers intensifies as polyester-dielectric variants commoditize around Shenzhen contract manufacturers. Consumer electronics contract assemblers exhibit highest price sensitivity, while German EV platform engineers prioritize signal integrity over unit cost.
Supply Chain Analysis
ISO 26262 and FDA 21 CFR Part 820 qualification gating restricts automotive and medical supply bases to producers with Class 1000 cleanroom lamination and captive polymer film supply. Manufacturing concentrates in Japan, South Korea, and China's Yangtze River Delta clusters. Raw material dependencies center on polyimide film from Ube Industries and Kaneka, copper foil from Furukawa Electric, and liquid crystal polymer resin from Polyplastics. Single-source vulnerability runs through Japanese polyimide feedstock. Distribution feeds from Tier-1 harness integrators in Bavaria and Michigan through to catalog distributors serving mid-scale electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where MIIT dual carbon mandates and REACH substance restrictions continuously requalify supplier bases and sustain premium pricing for compliant producers.
For Market Incumbents: Cement automotive design-in positions through captive polyimide film supply and in-house ZIF connector molding capabilities. Extend ISO 26262 traceability documentation to match BMW and Mercedes-Benz consolidation of approved vendor lists. Threat substitution from liquid crystal polymer substrates in battery management systems demands R&D investment in thermal-grade lamination processes. For New Entrants and Emerging Players: E-commerce catalog channels offer the lowest-friction entry path for standard FFC configurations serving industrial automation retrofit projects. White-space targets cluster around Indian PLI scheme electronics manufacturing zones near Chennai and Noida, plus 5G mmWave base station antenna interconnects outside consumer electronics saturation. Go-to-market leverage rests on BIS electromagnetic emissions pre-certification for dual EU-India market access. For Investors and Strategic Acquirers: Valuations sit cheapest among second-tier cable assemblers without captive film supply yet possessing cleanroom lamination assets. Long-term viability across a decade horizon favors targets with automotive qualification pipelines already initiated. The signal to watch is Tier-1 harness integrator joint development contract announcements from South Korean battery platform suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyimide Film | Captive supply from Ube Industries or Kaneka insulates margin from feedstock volatility. |
| ISO 26262 Certification Investment | Eighteen-month qualification cycles lock in BMW and Ford EV platform design-ins. |
| Cleanroom Lamination Capacity Expansion | Class 1000 environments open FDA 21 CFR Part 820 medical device cable opportunities. |
| Joint Development Contracts | Sumitomo Electric-style partnerships with German harness integrators secure traceability mandates. |
| Digital Channel Distributor Partnerships | Würth Elektronik and Samtec catalog presence captures mid-scale industrial automation demand. |
Research Methodology
Bottom-up automotive and medical device modeling reconciled against top-down polyimide film production tracking forms the analytical core. Primary interviews with Tier-1 harness procurement managers, OEM platform engineers, FPC lamination plant managers, and medical device quality assurance directors combined with secondary validation from MIIT energy efficiency disclosures, ECHA REACH substance restriction updates, FDA 510(k) filings, and customs trade data. Triangulation across these sources reconciles volume estimates with material flow analysis.
Input-output matrices map conductor gauge, dielectric layer count, and shielding architecture against end-use qualification tiers across the projection horizon. Segmentation dimensions include product type, application, connector configuration, and regional regulatory cluster. CAGRs derive from rolling qualification pipeline analysis and OEM platform production schedules. Forecast inputs incorporate liquid crystal polymer substrate adoption curves and REACH reformulation cost pass-through assumptions.
The model assumes a particular technology adoption path; alternative pathways for liquid crystal polymer displacement of polyimide in underhood applications would alter the outlook. Forecasts reflect documented assumptions about OEM vendor list consolidation velocity and polymer feedstock capacity expansion. A model refresh is warranted upon material change in MIIT dual carbon enforcement intensity or ECHA halogenated flame retardant restriction scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Fiber Optic Cable Materials Market
Cables
Cable Tags Market
Cables
Patch Cable Market
Cables
Global Cable Tie Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Cable Assembly Market
Cables
Submarine Data Cables Market
Cables
Usb Data Cable Market
Cables
Smartphone Type-C Charging and Data Cable Market
Cables
Fiber Optic Cable Accessories Market
Cables
Water Leak Sensing Cable Market
Cables
Global Cable Gland Market
Cables
Power and Signal Cables Market
Cables
Cable Market
Cables
Cable Flange Market
Cables
Network Cable Tester Market