
 Europe Cable Accessories Market | 2026-2036
Europe Cable Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cable Accessories Market Intelligence
Market Context
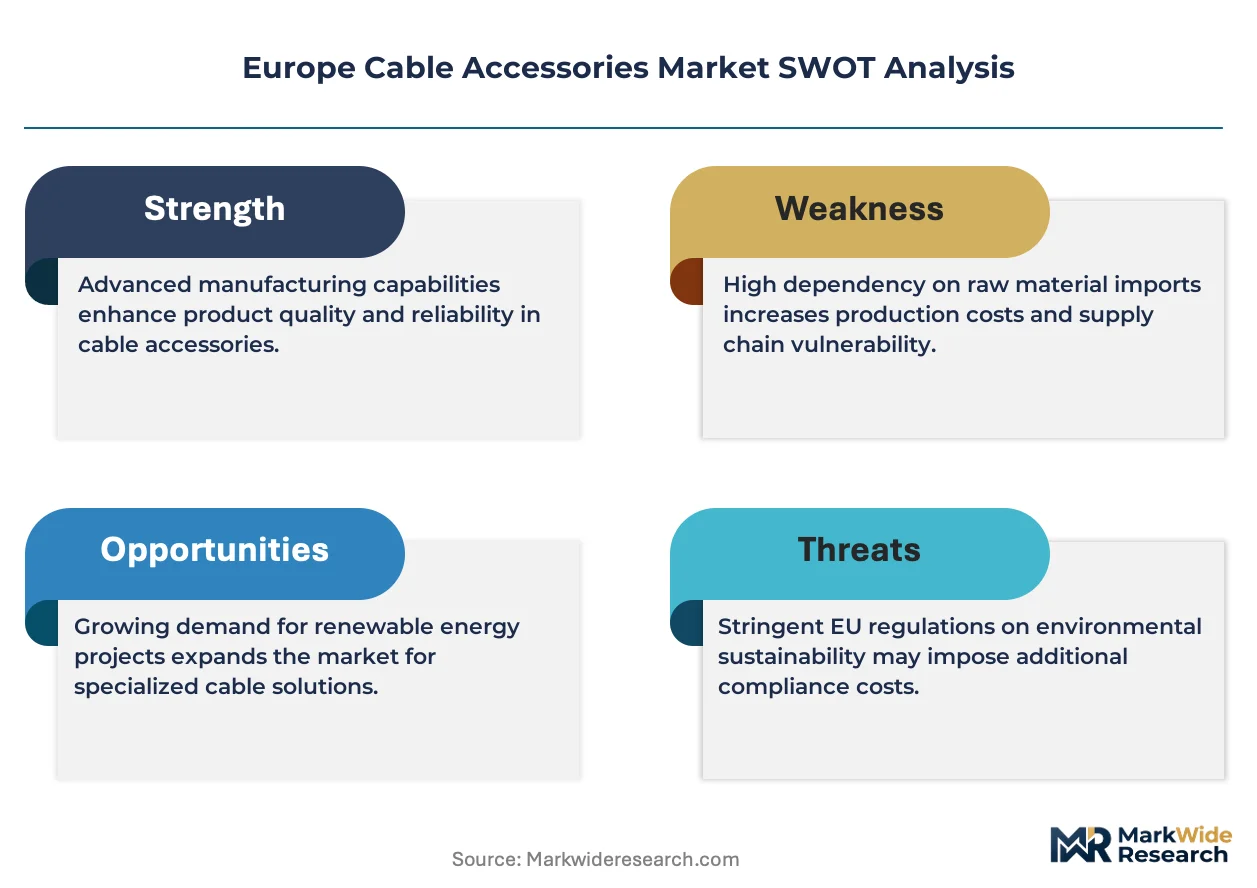
Capital-intensity divergence between integrated manufacturers and component assemblers is unwinding competitive stability across the European cable accessories landscape. Prysmian Group leverages captive compound production and submarine cable expertise to dominate high-voltage marine terminations. Nexans anchors its position through deep vertical integration into polymer compounding and European utility relationships. Pfisterer Group specializes in live-line connection systems, competing on installation speed and grid uptime guarantees.
Technical Definition and Segment Structure
Europe cable accessories encompass termination kits, splice enclosures, connectors, and junction boxes engineered to maintain electrical continuity, environmental sealing, and mechanical protection across copper, aluminum, PVC, and rubber insulated conductors rated from low voltage through extra-high voltage. These components enable safe power distribution in indoor switchgear, outdoor overhead lines, underground urban networks, and aerial rural installations across telecommunications, energy generation, industrial plants, and public infrastructure. Termination and splicing products command the largest revenue pools given their criticality in high-voltage grid reliability, while underground installation accessories represent the fastest-expanding category as European cities mandate subterranean routing to preserve urban aesthetics and climate resilience. Material segmentation shows copper-dominant connectors retaining premium positioning for conductivity-critical applications, though aluminum alternatives gain traction where weight and cost sensitivity shape procurement.
Regulatory Framework and Outlook
CE marking under the EU Low Voltage Directive and Construction Products Regulation governs market access, while REACH and RoHS constrain hazardous substance use in polymer housings and metal alloys. ECHA's evolving SVHC candidate list pressures manufacturers to reformulate halogenated flame retardants ahead of restriction proposals. Grid operators and accessory suppliers must monitor F-Gas Regulation phase-down timelines, as SF6-dependent switchgear connectors face substitution mandates that will reshape product portfolios and qualification requirements.
Market Dynamics
The EU Green Deal's electrification mandates and REPowerEU's grid modernization directives are concentrating capital flows into high-voltage infrastructure, forcing accessory suppliers to requalify products for submarine and interconnector applications at unprecedented speed.
Growth Catalysts
- Submarine Cable Deployment:Offshore wind farm developers across the North Sea corridor are expanding procurement of high-voltage submarine cable kits. German transmission system operators are retrofitting aging substations and expanding interconnector capacity.
- REACH Compliance Reformulation:ECHA's evolving SVHC candidate list pressures manufacturers to reformulate halogenated flame retardants ahead of restriction proposals. This regulatory pressure is accelerating R&D investment in compliant polymer compounds.
- Urban Underground Mandates:European cities are mandating subterranean cable routing to preserve urban aesthetics and climate resilience. Underground installation accessories represent the fastest-expanding category as municipal planners reject overhead infrastructure.
Market Restraints
- Copper Price Volatility:Copper-dominant connectors retain premium positioning for conductivity-critical applications, yet raw material cost swings compress margin predictability for manufacturers without captive metal sourcing.
- SF6 Substitution Timeline:The F-Gas Regulation phase-down mandates are forcing SF6-dependent switchgear connectors toward substitution. Qualification requirements for alternative gas-insulated systems remain undefined, freezing procurement decisions.
- Specialized Compound Concentration:Polymer compounding for marine-grade terminations concentrates among integrated cable manufacturers. Component assemblers face supply access constraints and technical dependency.
Strategic Opportunities
- Polish Grid Expansion:Poland's coal-to-renewables transition is creating demand for high-voltage accessories in new transmission corridors connecting Baltic offshore wind to central European load centers.
- Live-Line Installation Systems:Grid operators are prioritizing connection systems that eliminate outage requirements. Installation speed and uptime guarantees are becoming decisive procurement criteria.
- Aluminum Connector Adoption:Weight and cost sensitivity in aerial rural installations are driving specification shifts toward aluminum alternatives. Manufacturers with flexible metallurgy capabilities can capture margin from copper substitution.
Industry Challenges
- Cross-Border Certification Complexity:CE marking under the EU Low Voltage Directive and Construction Products Regulation governs market access, yet national implementation variations create qualification duplication for pan-European suppliers.
- Submarine Qualification Duration:High-voltage marine terminations require extended type-testing protocols for pressure-rated sealing and corrosion resistance. Development timelines stretch 18-24 months, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cable Accessories Market |
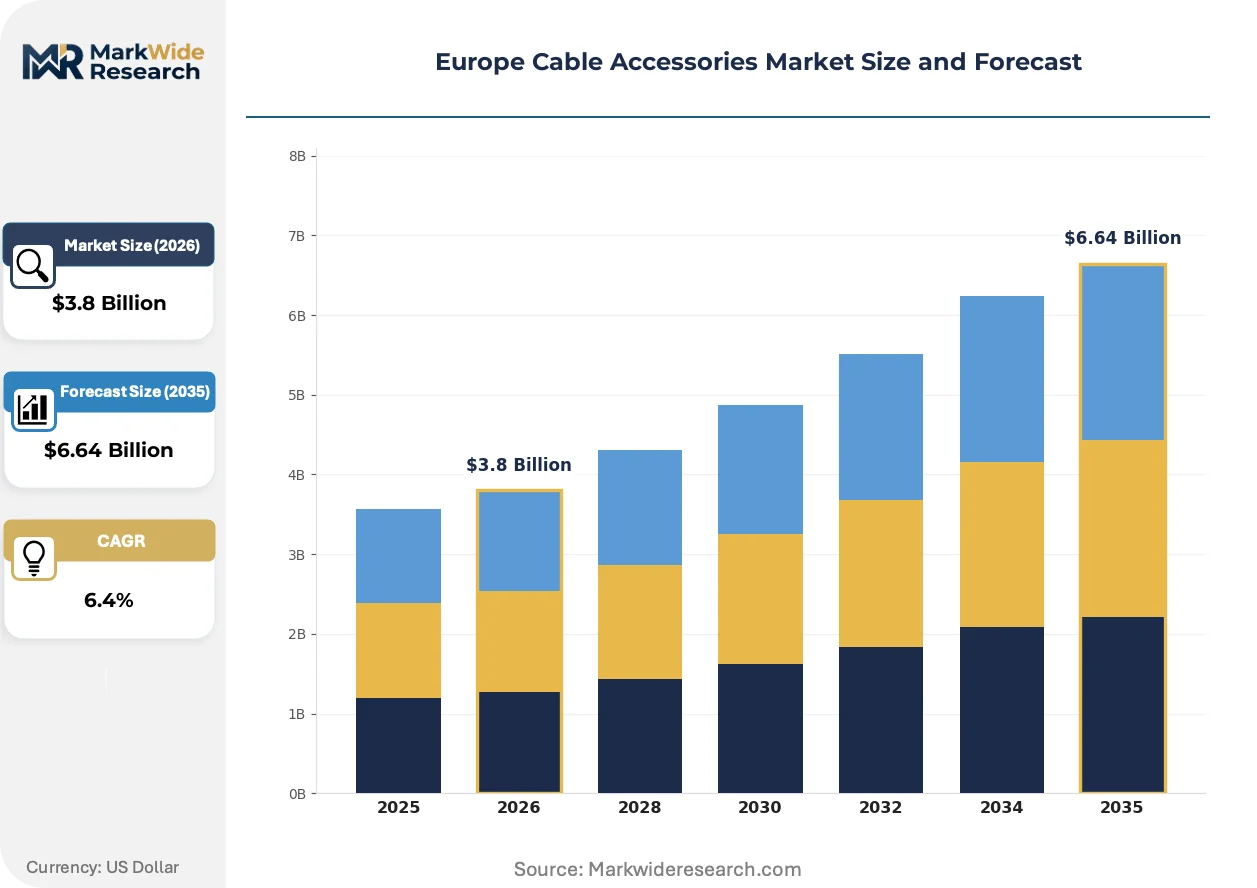
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Termination, Splicing, Connectors, Junction Boxes Material: Copper, Aluminum, PVC, Rubber Installation Type: Indoor, Outdoor, Underground, Aerial End User: Telecommunications, Energy, Industrial, Infrastructure |
| Companies Covered | Nexans, Prysmian Group, Pfisterer Group, HellermannTyton, Hager Group, Electrium, Fischer Connectors, NKT A/S, ABB Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cable Accessories Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry constraints are converging to reshape product architectures. Suppliers are racing to decouple performance from hazardous substance dependencies while meeting intensified reliability standards for offshore and urban applications.
Silicone rubber cold-shrink terminations are displacing heat-shrink alternatives in medium-voltage distribution networks. German distribution system operators are specifying cold-shrink for retrofit programs to accelerate installation speed and reduce outage windows. This displacement is compressing the addressable market for traditional heat-shrink kits and forcing compound suppliers to reformulate silicone grades for European climate cycling.
The F-Gas Regulation's SF6 phase-down timeline is mandating connector redesign for gas-insulated switchgear. Manufacturers must qualify vacuum-interrupter and solid-dielectric alternatives without established test protocols. High-voltage switchgear segments in Germany and the Netherlands are piloting fluoronitrile-based systems, though accessory interoperability remains unstandardized.
Utility procurement departments are consolidating supplier panels and unbundling installation services from material supply. French and Belgian transmission operators now separate accessory procurement from commissioning contracts, compressing margins for integrated service providers. This unbundling favors specialized installation contractors with live-line certifications over traditional full-service cable manufacturers.
Europe Cable Accessories Market Segmentation
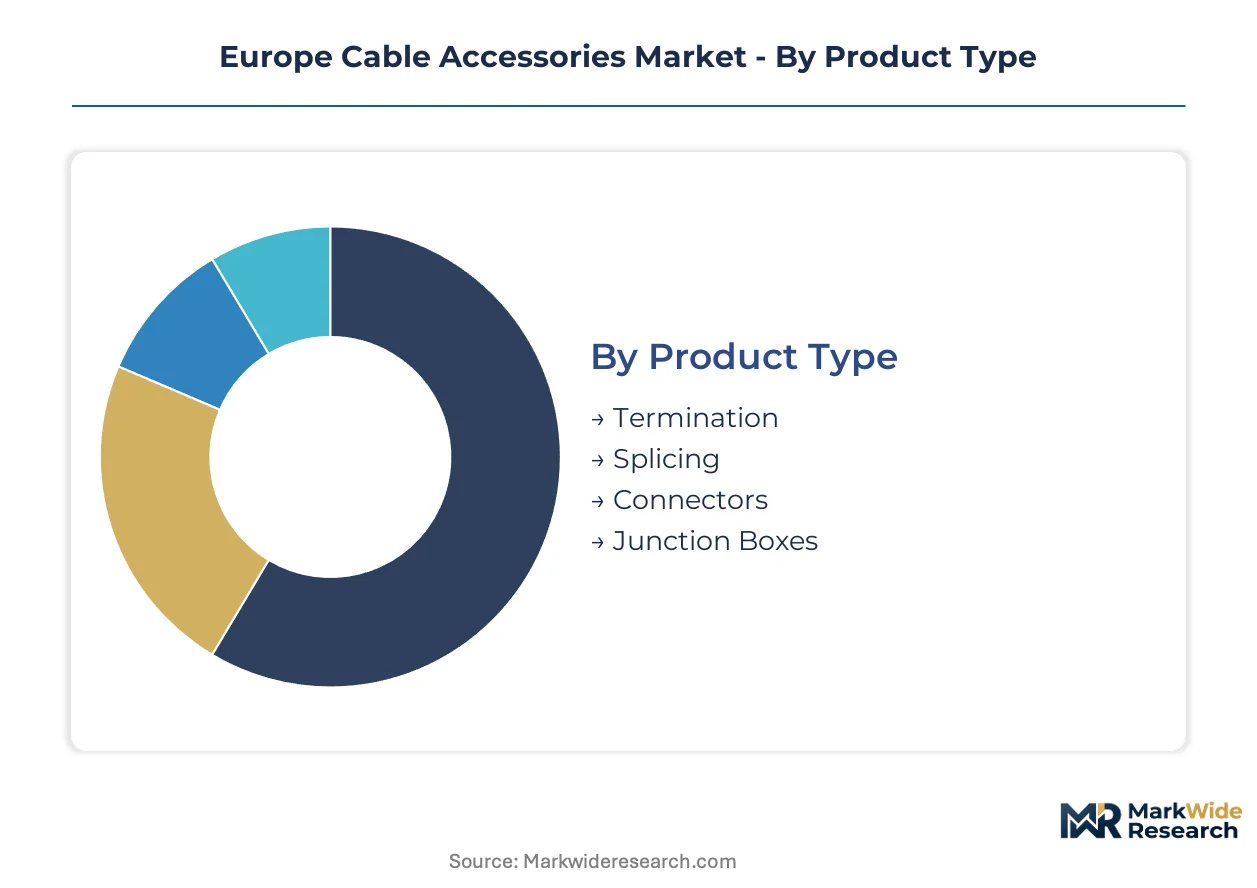
Cable accessories in Europe face divergent qualification requirements across voltage classes and installation environments. Regulatory fragmentation under CE marking, REACH, and F-Gas mandates forces suppliers to maintain parallel product portfolios optimized for specific conductor materials and deployment contexts.
Product Type:
REACH and RoHS constrain polymer formulations differently across termination, splicing, and connector categories, with submarine-rated products facing the most stringent SVHC scrutiny.
- Termination:Kits engineered for high-voltage sealing and electrical stress control use silicone rubber or EPDM compounds. German transmission system operators specify cold-shrink terminations for retrofit programs to compress outage windows. ECHA's evolving SVHC list pressures reformulation of halogenated flame retardants in these housings.
- Splicing:Enclosures maintain conductor continuity across joint sections while providing environmental sealing and mechanical protection. Offshore wind developers across the North Sea corridor procure pressure-rated splice kits for submarine interconnector projects. Qualification timelines for marine-grade pressure sealing stretch 18-24 months.
- Connectors:Compression and mechanical clamps ensure low-resistance conductor joining across copper and aluminum interfaces.
- Junction Boxes:Enclosures route and protect multi-circuit terminations in indoor switchgear and outdoor substations.
Termination handles the majority of throughput; splicing is expanding most quickly on share.
Material:
Cost tier differentiation separates conductivity-critical applications from weight-sensitive aerial deployments.
- Copper:Dominates connectors for high-current density and reliability-critical grid infrastructure. Raw material price volatility compresses margin predictability for manufacturers without captive metal sourcing or long-term supply agreements.
- Aluminum:Gains specification in aerial rural installations where weight reduction and cost sensitivity override conductivity premiums. Polish grid expansion projects connecting Baltic offshore wind to central European load centers specify aluminum for long-span transmission corridors.
- PVC:Standard insulation and jacketing for low-voltage distribution in indoor and protected outdoor environments.
- Rubber:EPDM and silicone compounds provide flexibility and temperature resistance for medium-voltage terminations and cold-shrink applications.
Copper handles the majority of throughput; aluminum is climbing the fastest on specification share.
Installation Type:
Urban planning mandates and climate resilience requirements are reshaping volume distribution across deployment contexts.
- Underground:Municipal mandates across European cities favor subterranean routing to preserve urban aesthetics and harden infrastructure against extreme weather. Underground installation accessories represent the steepest expansion trajectory as planners reject overhead alternatives in dense urban cores.
- Outdoor:Overhead lines and substation yards require weather-resistant terminations and surge protection. Benelux transmission operators pilot fluoronitrile-based switchgear connectors as F-Gas Regulation phase-downs force SF6 substitution.
- Indoor:Switchgear and control room applications prioritize compact termination designs and fire-resistant polymer housings.
- Aerial:Rural distribution networks and temporary construction feeds rely on messenger-supported cable systems with lightweight aluminum connectors.
Outdoor handles the majority of installed base; underground is gaining share fastest.
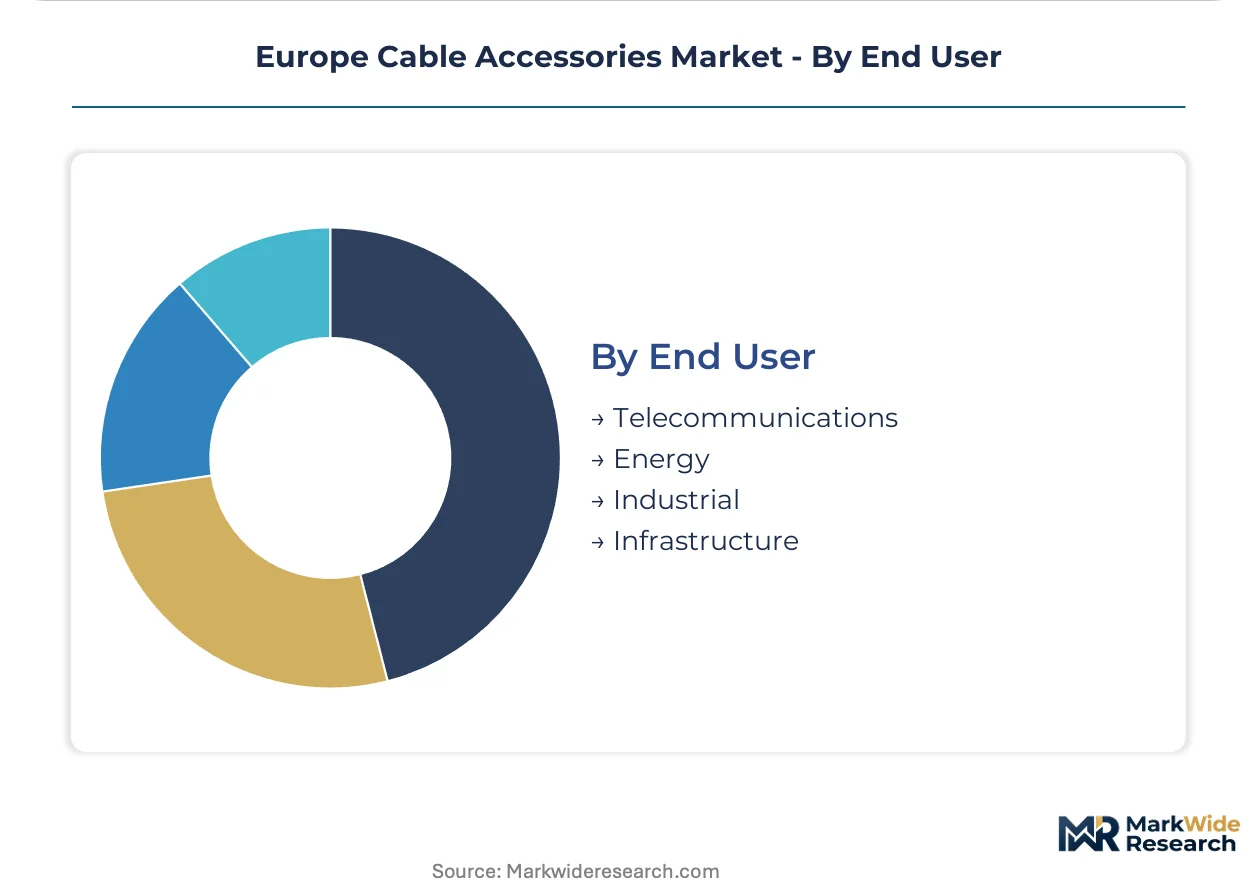
End User:
Customer type determines procurement sophistication, with utilities enforcing the most stringent qualification protocols.
- Energy:Transmission and distribution system operators drive high-voltage accessory demand through grid modernization and interconnector expansion. REPowerEU mandates concentrate capital flows into compliant submarine and extra-high voltage products.
- Infrastructure:Rail electrification, port power systems, and public building networks specify medium-voltage accessories with extended service life guarantees. French and Belgian operators now unbundle accessory procurement from commissioning contracts.
- Telecommunications:Fiber and copper network operators require sealed splice enclosures and weather-resistant junction boxes for outdoor cabinet deployments.
- Industrial:Manufacturing plants and process facilities specify flame-retardant and halogen-free accessories for safety-critical power distribution.
Energy handles the majority of procurement volume; infrastructure is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities consume submarine-rated terminations for North Sea interconnectors, while Polish grid planners favor aluminum connectors for long-span rural corridors. This consumption-mix differential separates marine-grade procurement in coastal markets from cost-optimized aerial specifications in eastern expansion zones.
Germany
Transmission system operators retrofit aging substations and expand interconnector capacity across the North Sea corridor. The EU Green Deal's electrification targets accelerate utility spending on compliant high-voltage accessories. Industrial clusters in Bavaria and North Rhine-Westphalia host compound formulation facilities serving submarine cable manufacturers.
Poland
Coal-to-renewables transition creates demand for high-voltage accessories in new transmission corridors connecting Baltic offshore wind to central European load centers. REPowerEU grid modernization mandates direct capital into compliant interconnector kits. Manufacturing activity concentrates in Silesia and Greater Poland Voivodeships where cable assembly plants serve regional infrastructure projects.
Netherlands
Benelux transmission operators pilot fluoronitrile-based switchgear connectors as F-Gas Regulation phase-downs force SF6 substitution. Port power systems and rail electrification specify medium-voltage accessories with extended service life guarantees. Rotterdam-The Hague metropolitan area hosts specialist installation contractors with live-line certifications.
France
Transmission operators unbundle accessory procurement from commissioning contracts, compressing margins for integrated service providers. CE marking under the Construction Products Regulation governs market access for polymer housings and metal alloys. Lyon and Paris regions concentrate distribution system operator headquarters driving cold-shrink termination specifications.
United Kingdom
Offshore wind farm developers procure high-voltage submarine cable kits for North Sea deployment zones. ECHA's evolving SVHC candidate list pressures reformulation of halogenated flame retardants in termination housings. Aberdeen and Humberside clusters anchor marine cable engineering expertise serving North Sea energy infrastructure.
Europe Cable Accessories Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the European cable accessories landscape. Captive compound production and submarine cable expertise distinguish the upper tier from component assemblers dependent on external polymer supply. Strategic archetypes include vertically integrated cable manufacturers, live-line connection specialists, and regional electrical distributors. Competitive moves concentrate on backward integration into polymer compounding and qualification acceleration for marine-rated products.
Within the integrated manufacturing tier, Prysmian Group and Nexans occupy positions defined by captive supply chains and utility relationships across high-voltage applications. Pfisterer Group exemplifies the specialist archetype focused on connection systems and installation speed guarantees. These three anchors represent distinct competitive vectors: compound control, vertical scope, and service unbundling.
| Leading Market Players |
|---|
| Nexans |
| Prysmian Group |
| Pfisterer Group |
| HellermannTyton |
| Hager Group |
| Electrium |
| Fischer Connectors |
| NKT A/S |
| ABB Ltd |
| Others |
Cost & Logistics Intelligence
Aluminum substitution for copper connectors in Polish and Baltic transmission corridors simultaneously redraws raw material sourcing maps and compresses premium pricing tiers for conductivity-critical applications. This material pivot rewards manufacturers with flexible metallurgy capabilities while eroding margin buffers for suppliers locked into single-metal production lines.
Pricing Analysis
Installation and commissioning service contracts now drive lifetime value as French and Belgian transmission operators unbundle accessory procurement from technical support. Three-tier pricing structure across premium, standard, and economy levels separates marine-qualified terminations from distribution-grade cold-shrink kits and commodity indoor connectors. Cost compression in standard-tier products intensifies because utility procurement panels are consolidating supplier lists and demanding volume discounts. Distribution system operators exhibit highest price sensitivity due to municipal budget constraints, while offshore wind developers prioritize qualification speed over unit economics.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam feeds into extended lead times for silicone rubber compounds imported from German industrial clusters and Asian specialty chemical producers. Polymer compounding concentrates in Germany, Italy, and Belgium, with marine-grade EPDM formulations drawing from captive production at integrated cable manufacturers. Single-source vulnerability concentrates in halogenated flame retardant supply as ECHA's SVHC restrictions force reformulation cycles. Distribution runs through direct utility contracts for high-voltage projects and electrical wholesalers for retrofit and maintenance volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's electrification mandates constitute a structural inflection, concentrating capital flows into submarine and interconnector-rated accessories faster than qualification timelines can accommodate.
For Market Incumbents: Consolidate backward integration into polymer compounding to secure marine-grade compound access against supply rationing. Prysmian and Nexans already control captive silicone production; smaller integrated manufacturers must defend position by accelerating pressure-rated termination testing to compress 18-24 month qualification windows. Channel control through live-line installation certification partnerships offers secondary defensive leverage as service unbundling separates material supply from commissioning revenue. For New Entrants and Emerging Players: Anchor in Poland's coal-to-renewables transmission buildout, where aluminum connector specification for long-span rural corridors creates penetrable white space outside incumbent utility relationships. Baltic offshore wind interconnector projects offer secondary entry points for specialized splicing contractors with pressure-rated enclosure expertise. A go-to-market angle emphasizing REACH-compliant halogen-free formulations addresses regulatory pressure points where established suppliers face reformulation lag. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed electrical distribution platforms that acquired regional cable accessory specialists during prior consolidation waves. Five-to-ten year viability hinges on exposure to submarine qualification capabilities and utility direct relationships rather than wholesale channel dependency. The signal to watch is ECHA restriction proposal timing for halogenated flame retardants, which would force portfolio-wide reformulation investment and separate prepared from reactive asset bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive silicone production insulates Prysmian and Nexans from marine-grade compound rationing. |
| Live-Line Installation Certification | Grid uptime guarantees become decisive procurement criteria as outage costs escalate. |
| Aluminum Connector Portfolio Expansion | Polish and Baltic specifications reward flexible metallurgy with margin capture from copper substitution. |
| REACH-Compliant Reformulation | Halogen-free flame retardant investment preempts ECHA restriction proposals and SVHC listing impacts. |
| Submarine Qualification Acceleration | Pressure-rated termination testing compression captures North Sea offshore wind procurement windows. |
Research Approach
Initial hypotheses were tested against primary input from transmission system operator procurement directors, submarine cable project developers, polymer compounding technical leads, and electrical distribution channel managers and refined through secondary validation. Regulatory filings from ECHA, EU Green Deal implementation documents, and REPowerEU grid modernization directives anchored policy impact assessment. Customs data on copper and aluminum connector trade flows, utility capital expenditure disclosures, and offshore wind project development databases supplied volume triangulation. Bottom-up project pipeline analysis and top-down utility spending forecasts were reconciled across independent estimation paths.
Variance decomposition across voltage class, installation environment, conductor material, and end-user procurement sophistication shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume buildups and price trajectory assumptions indexed to raw material cost indices and regulatory compliance cost overlays. Submarine cable deployment schedules, substation retrofit timelines, and municipal undergrounding mandates provided industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained EU electrification funding and ECHA regulatory timelines; material deviation would warrant model refresh. Commodity price volatility in copper and aluminum, F-Gas Regulation implementation pace, and offshore wind permitting delays constitute specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Usb Data Cable Market
Cables
High Voltage Cable Termination Market
Cables
Submarine Optical Fiber Cables Market
Cables
India Optic Fiber Cable and Accessories Market
Cables
Submarine Cabling Systems Market
Cables
Sensor Cable Market
Cables
Cable Assembly Market
Cables
Electric Submersible Cables (ESP) Market
Cables
Anti-Static Space Wires Market
Cables
Solar Cable Market
Cables
South Africa Wire and Cable Market
Cables
Global Wires and Cables Market
Cables
Flat Flexible Cables Market
Cables
Cable Detector Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
Power Cable Accessories Market