
 Magnetic Charging Cable Market | 2026-2036
Magnetic Charging Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Charging Cable Market Outlook
Nylon braided sheathing is pivoting away from basic PVC jackets across premium magnetic cable tiers, compressing unit costs while extending flex-cycle durability past ten thousand bends. Anker Innovations leverages its charging R&D campus in Changsha to sustain fast-magnetic protocol leadership. TOPK dominates Southeast Asian e-commerce channels with price-optimized 3-in-1 configurations. Belkin anchors North American retail placement through Best Buy and Apple Store partnerships.
A magnetic charging cable employs a detachable connector tip seated within the device port, mating magnetically to a cable head that delivers power and optionally data through spring-loaded pogo pins or contact pads; conductor gauges typically range from 22 AWG for standard charging to 18 AWG for 100W USB Power Delivery implementations, with neodymium magnet arrays providing 1-2 kilogram pull-force ratings for secure attachment. USB Type-C magnetic adapters lead volume shipments due to universal device compatibility, while nylon braided cable jackets capture margin pools through perceived durability premiums and reduced return rates. Fast Charging technology segments are expanding fastest as 65W and 100W magnetic adapters displace standard 5V/2A legacy products in laptop and tablet applications.
FCC Part 15 electromagnetic interference rules constrain magnetic connector spark emissions in US-bound products, while CE marking under the EU Radio Equipment Directive governs magnetic charging accessories sold in European Economic Area markets. China's GB 4943.1 safety standard for information technology equipment mandates insulation and temperature-rise testing that shapes factory-level quality systems. Stakeholders must monitor USB-IF certification timelines and regional right-to-repair legislative drafts that could mandate standardized magnetic tip interoperability across consumer electronics brands.
Market Dynamics
USB Power Delivery protocol revisions above 100W are fragmenting connector compatibility matrices, forcing magnetic adapter manufacturers to maintain parallel certification tracks for 65W, 100W, and 240W implementations across consumer electronics portfolios.
Growth Catalysts
- IEC 62684 Harmonization:Standardized charging interface requirements in European Economic Area markets are reducing SKU complexity for magnetic tip manufacturers serving multi-brand retail channels.
- Wearable Computing Expansion:Smartwatch and hearable device makers are integrating magnetic pogo-pin systems to enable sealed enclosures without compromising charging accessibility.
- Shenzhen Component Clustering:Concentrated neodymium magnet and USB-C controller supply within Guangdong Province compresses procurement lead times for cable assemblers.
Market Restraints
- Neodymium Price Volatility:Rare earth magnet supply from Chinese separation facilities exposes BOM cost fluctuations that cable brands cannot fully pass to retail price points.
- FCC Part 15 Spark Emission Limits:Electromagnetic interference constraints on magnetic connector arcing require additional ferrite shielding that adds unit cost and assembly complexity.
- Integrated Wireless Charging:Qi2 and MagSafe native integration in flagship smartphones reduces addressable market for aftermarket magnetic cable accessories in premium tiers.
Strategic Opportunities
- India BIS Certification Pipeline:Mandatory safety marking for information technology equipment creates first-mover advantage for magnetic cable suppliers establishing local testing partnerships.
- Automotive USB-C Infotainment:In-cabin charging port standardization across electric vehicle platforms opens fleet-scale procurement contracts for 100W magnetic adapters.
- Right-to-Repair Mandates:Draft legislation in multiple US states and EU member countries may require standardized magnetic tip interoperability, reducing brand-lock-in switching costs.
Industry Challenges
- USB-IF Certification Backlogs:Extended approval timelines for Power Delivery 3.1 compliance are delaying product launches and compressing effective selling seasons.
- Pogo-Pin Corrosion Engineering:Salt spray testing failures in marine and industrial environments require specialized plating processes that strain in-house metallurgy capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Charging Cable Market |
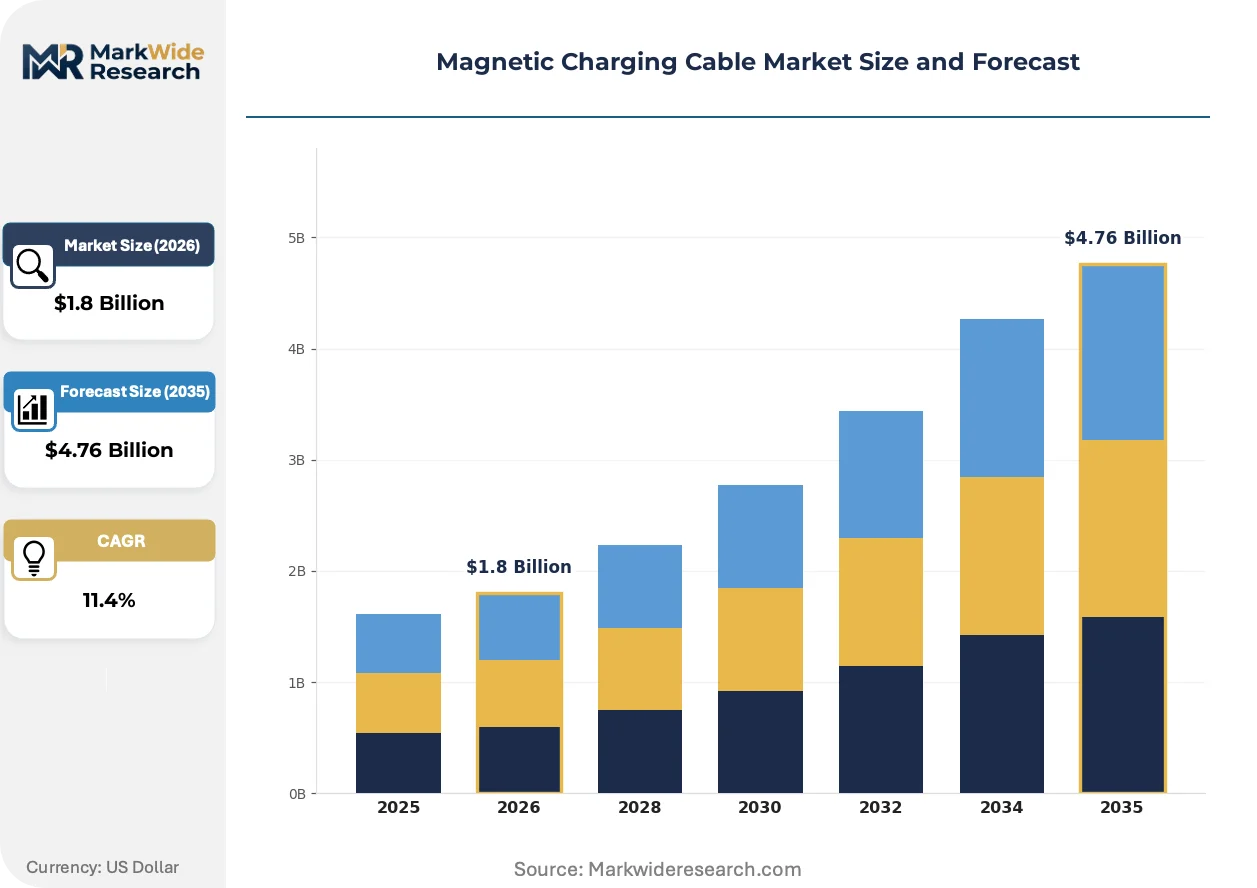
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB Type-C, Lightning, Micro USB, 3-in-1 End User: Consumers, Retailers, OEMs, Industrial Technology: Fast Charging, Standard Charging, Magnetic Alignment, Data Transfer Material: Aluminum Alloy, PVC, Nylon Braided, Copper |
| Companies Covered | NetDot, TOPK, Anker Innovations, Essager, Terasako, Belkin, Mcdodo, Changzhou Helge International Trade Co., Ltd., VCOM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Charging Cable Market Strategic Shifts
Material substitution and protocol convergence are compressing product lifecycles while expanding addressable power tiers across mobile computing and industrial handheld segments.
Gallium nitride power ICs are decentralizing thermal management architectures in magnetic charging adapters. Laptop and tablet manufacturers are adopting 100W and 140W GaN-based bricks with detachable magnetic heads to reduce cable strain failures. This semiconductor transition is decentralizing charger manufacturing away from legacy silicon foundry regions toward specialized GaN packaging facilities in Taiwan and Malaysia.
EU Radio Equipment Directive enforcement is tightening electromagnetic compatibility documentation for magnetic accessories sold in member states. Cable brands must now submit third-party test reports for spark suppression and contact resistance stability. The directive most heavily affects multi-tip 3-in-1 configurations sold through Amazon EU marketplaces, where sellers are consolidating SKUs to reduce compliance overhead.
Enterprise IT procurement teams are unbundling charging accessories from device fleet purchases. Corporate buyers in North America and Western Europe are issuing separate RFPs for magnetic cable systems with standardized tips across mixed-device environments. This pattern is most visible in healthcare and field service verticals where device heterogeneity complicates inventory management.
Magnetic Charging Cable Market Segmentation
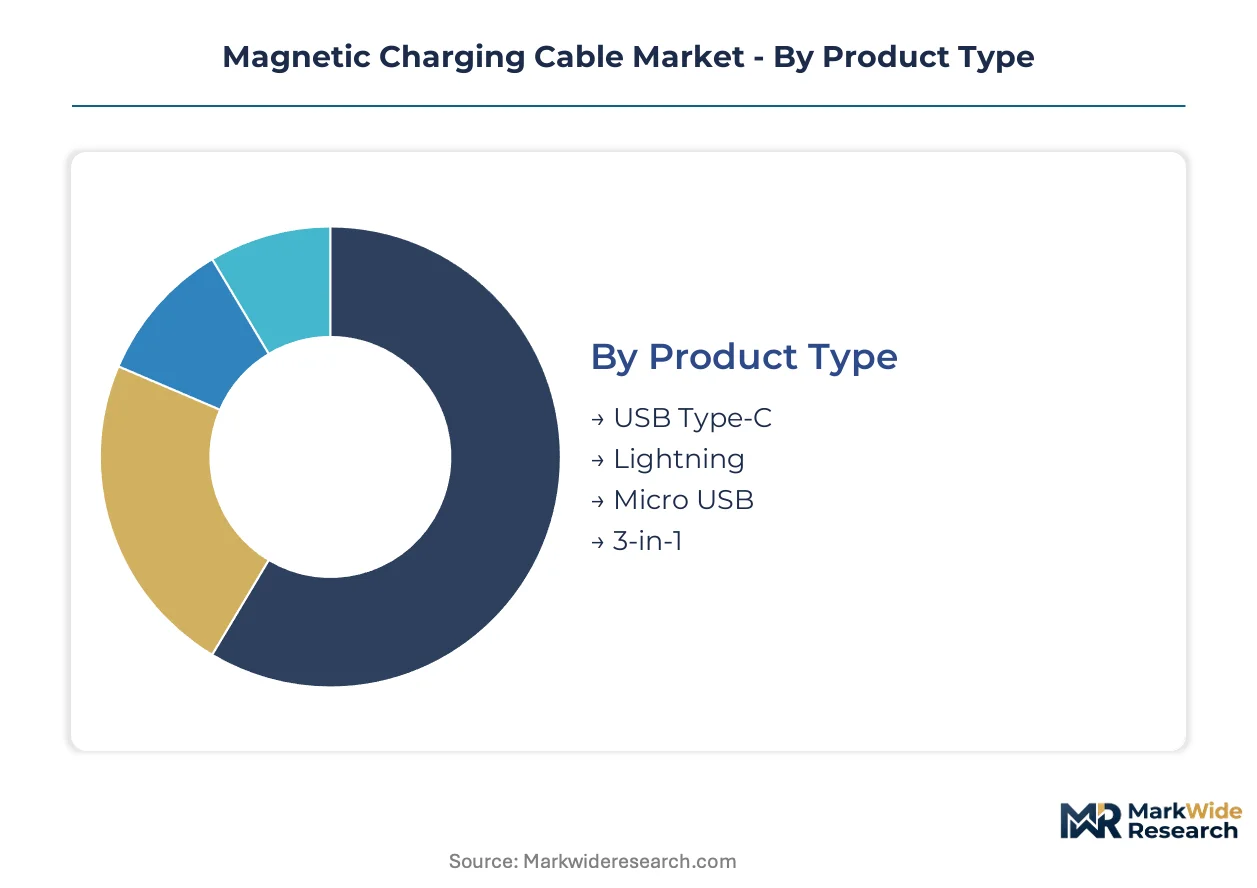
Magnetic charging cable procurement decisions split across connector protocol compatibility, power delivery specifications, and environmental durability requirements. Buyers prioritize interoperability certifications and flex-cycle longevity over unit price in enterprise and premium consumer tiers.
Product Type:
Purchaser selection hinges on device port standardization and backward compatibility requirements across mixed-device fleets.
- USB Type-C:Dominant protocol supporting USB Power Delivery up to 240W through EPR configurations. Enterprise IT procurement in the United States and Germany concentrates here for laptop and tablet standardization, driven by IEC 62684 harmonization reducing SKU proliferation.
- Lightning:Apple's proprietary connector retains installed-base demand despite USB-C transition mandates. Accessories for legacy iPhone inventories in Japan and premium aftermarket channels in South Korea sustain procurement volumes.
- Micro USB:Declining share confined to entry-tier Android handsets and IoT peripherals in cost-sensitive markets.
- 3-in-1:Multi-tip configurations serving hospitality, vehicle fleet, and shared workspace applications where device heterogeneity prevents single-connector standardization.
Volume sits with USB Type-C; growth tilts toward 3-in-1 configurations in commercial deployment scenarios.
End User:
Procurement authority and volume scale determine margin capture and certification investment returns across the value chain.
- Consumers:Individual purchasers prioritize price-to-durability ratios and e-commerce review aggregation. Amazon and Shopee channels in Southeast Asia concentrate this demand, with nylon braided configurations commanding premium positioning.
- Retailers:Electronics chains and mobile carrier stores negotiate exclusive SKUs and private-label magnetic cable programs. Best Buy and Apple Store partnerships in North America exemplify placement-driven procurement.
- OEMs:Device manufacturers integrate magnetic connectors at factory level, requiring USB-IF certification and custom tip geometries. Shenzhen-based mobile computing brands dominate this procurement tier.
- Industrial:Field service, healthcare, and logistics operations specify IP-rated sealed connectors with salt-spray resistance. Salt spray testing failures have pushed demand toward specialized plating processes in marine environments.
Margin concentrates with OEMs; volume expansion favors industrial verticals deploying standardized fleet accessories.
Technology:
Power delivery wattage and data capability separate premium positioning from commodity replacement cycles.
- Fast Charging:GaN-based architectures supporting 65W, 100W, and 140W outputs displace legacy silicon in laptop and tablet applications. Taiwan and Malaysia packaging facilities capture semiconductor value migration.
- Standard Charging:5V/2A legacy implementations persist in low-power IoT and entry smartphone tiers where BOM cost constraints dominate.
- Magnetic Alignment:Neodymium magnet arrays with 1-2 kilogram pull-force ratings enable single-handed attachment for accessibility-focused and automotive applications.
- Data Transfer:USB 3.2 and Thunderbolt-enabled magnetic tips serve creative professional workflows requiring high-bandwidth external storage connectivity.
Revenue pools deepest in fast charging; steepest expansion trajectory belongs to data transfer capabilities in professional computing segments.
Material:
Jacket composition and conductor metallurgy determine flex-cycle longevity, thermal dissipation, and perceived quality premiums.
- Nylon Braided:Multi-filament woven sheathing extends durability past ten thousand bends while reducing return rates in premium e-commerce channels. Perceived durability supports margin capture over basic PVC alternatives.
- Aluminum Alloy:Connector housings provide EMI shielding and thermal conductivity for high-wattage Power Delivery implementations. CNC machining clusters in Dongguan supply this component tier.
- PVC:Extruded jackets dominate entry-price tiers with limited flex-cycle ratings and higher environmental degradation susceptibility.
- Copper:Conductor gauges from 22 AWG standard to 18 AWG for 100W implementations determine current-carrying capacity and voltage drop characteristics.
Shipments weight toward PVC; value capture shifts fastest to nylon braided configurations in premium consumer and enterprise procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of magnetic charging cable procurement, with Shenzhen-based OEMs and component clusters driving both manufacturing scale and export volumes to North American and European retail channels.
China
Guangdong Province concentrates neodymium magnet supply and USB-C controller production within Dongguan machining clusters and Shenzhen assembly operations. GB 4943.1 safety standards for information technology equipment mandate insulation and temperature-rise testing that shapes factory-level quality systems. Changsha hosts Anker Innovations' charging R&D campus, sustaining fast-magnetic protocol development for laptop and tablet applications.
United States
Enterprise IT procurement teams in healthcare and field service verticals issue separate RFPs for magnetic cable systems with standardized tips across mixed-device fleets. FCC Part 15 electromagnetic interference rules constrain magnetic connector spark emissions, requiring additional ferrite shielding for US-bound products. Best Buy and Apple Store partnerships anchor North American retail placement for premium-tier accessories.
Germany
Industrial buyers specify IP-rated sealed connectors with salt-spray resistance for logistics and manufacturing environments. CE marking under the EU Radio Equipment Directive governs magnetic charging accessories, with third-party test reports now mandatory for spark suppression documentation. Berlin-based procurement offices coordinate standardized fleet accessory deployments across EU member states.
India
Domestic smartphone assembly expansion under the PLI scheme is generating pull-through demand for charging accessories in Maharashtra and Karnataka industrial corridors. BIS certification for information technology equipment creates first-mover advantage for suppliers establishing local testing partnerships. Mumbai and Delhi-NCR distribution hubs consolidate import volumes from Shenzhen for redistribution to tier-2 cities.
Japan
Legacy iPhone installed bases in Tokyo and Osaka sustain procurement volumes for Lightning-compatible magnetic adapters despite USB-C transition mandates. METI efficiency regulations shape power adapter specifications for consumer electronics. Nagoya-area electronics retailers maintain premium positioning for nylon braided configurations with extended flex-cycle ratings.
Magnetic Charging Cable Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consumer-facing brands capturing margin premiums and OEM suppliers dominating volume throughput. The vendor base arranges into three tiers: multinational electronics accessory houses with retail partnerships, Shenzhen-based direct-to-consumer brands optimizing e-commerce channels, and contract assemblers serving device manufacturers. Strategic archetypes include fast-charging technology leaders, price-optimized multi-tip configurators, and industrial-grade sealed connector specialists. Competitive moves center on GaN semiconductor integration partnerships and geographic certification expansion into India BIS and EU CE marking pipelines.
Among Chinese fabricators, Changzhou Helge International Trade Co., Ltd. occupies a position within the export-oriented contract manufacturing tier, while Anker Innovations anchors the branded technology leadership archetype with its Changsha R&D infrastructure. TOPK exemplifies the price-optimized direct-to-consumer model through Southeast Asian e-commerce channel dominance. Belkin represents the multinational retail partnership archetype through North American electronics chain placement. These three named entities collectively illustrate the geographic and strategic segmentation shaping competitive positioning without exhausting the participant roster.
| Leading Market Players |
|---|
| NetDot |
| TOPK |
| Anker Innovations |
| Essager |
| Terasako |
| Belkin |
| Mcdodo |
| Changzhou Helge International Trade Co., Ltd. |
| VCOM |
| Others |
Value Chain & Pricing Dynamics
Enterprise IT procurement teams demanding USB-IF certification and 100W Power Delivery compatibility are forcing cable assemblers toward specialized GaN controller suppliers and third-party testing partnerships, compressing margins in standard tiers while concentrating pricing power with certified premium suppliers.
Pricing Analysis
Volume concentrates in entry-tier PVC-jacketed cables where Shenzhen contract manufacturers compete on BOM cost, while margin pools accrue to nylon braided configurations with 10,000+ flex-cycle ratings and GaN-enabled fast charging tiers. Price differentiation separates USB-IF certified products from uncertified alternatives, with enterprise buyers absorbing premiums for standardized tip interoperability across mixed-device fleets. Cost compression in standard charging tiers is intensifying because neodymium magnet price volatility from Chinese separation facilities cannot be fully passed through. Consumer e-commerce channels exhibit highest price sensitivity; industrial and OEM procurement shows lowest sensitivity due to certification requirements and fleet standardization needs.
Supply Chain Analysis
India's BIS certification mandate for information technology equipment is reshaping sourcing strategies, pushing brands toward local testing partnerships and component qualification programs that extend procurement lead times. Manufacturing gravity centers on China for neodymium magnet arrays and USB-C controller supply, Taiwan and Malaysia for GaN power IC packaging, and Vietnam for cable assembly diversification. Raw material dependencies span neodymium rare earth elements, copper conductor stock, and nylon braided sheathing feedstock. Single-source vulnerability concentrates in Chinese rare earth separation facilities. Distribution runs through Shenzhen export hubs for North American and European retail channels, with Mumbai and Delhi-NCR consolidating import volumes for Indian redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neodymium magnet supply concentration in Chinese separation facilities constrains input cost predictability, propping pricing power with vertically integrated assemblers maintaining captive magnet sourcing relationships.
For Market Incumbents: Extend certification moats by accelerating USB-IF Power Delivery 3.1 compliance pipelines ahead of backlog resolution, while securing GaN semiconductor partnerships with Taiwan and Malaysia packaging facilities to defend fast-charging positioning against silicon legacy suppliers. Wireless charging integration in flagship smartphones threatens aftermarket cable volumes; backward integration into neodymium magnet procurement hedges BOM volatility. For New Entrants and Emerging Players: Capture first-mover positioning in India's BIS certification pipeline by establishing local testing partnerships before mandatory marking enforcement tightens import pathways. Industrial verticals specifying IP-rated sealed connectors with salt-spray resistance represent the most penetrable white space, given incumbent underinvestment in marine and healthcare plating capabilities. Direct procurement engagement with Mumbai and Delhi-NCR distribution hubs enables rapid tier-2 city penetration. For Investors and Strategic Acquirers: Re-rating potential sits with GaN-enabled fast-charging specialists given USB Power Delivery protocol fragmentation above 100W, which fragments competitor certification matrices and consolidates procurement with protocol-fluent suppliers. Long-term viability favors assemblers with demonstrated salt-spray testing capabilities and automotive USB-C infotainment pipeline access. Watch USB-IF certification backlog resolution timelines as inflection indicator for effective selling season capture.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Integration Partnership | Taiwan and Malaysia packaging facilities capture value migration from legacy silicon foundries. |
| India BIS Certification Pipeline Establishment | Local testing partnerships create defensible positioning before mandatory marking enforcement. |
| Salt-Spray Resistant Plating Process Investment | Marine and healthcare verticals demand specialized metallurgy capabilities incumbent suppliers lack. |
| Automotive USB-C Infotainment Qualification | Electric vehicle platform standardization opens fleet-scale procurement for 100W magnetic adapters. |
| Right-to-Repair Standardized Tip Development | Draft EU and US state legislation may mandate interoperability, reducing brand-lock-in switching costs. |
Study Parameters
Document review covered USB-IF certification databases, FCC Part 15 electromagnetic interference filings, and EU Radio Equipment Directive compliance records, complemented by interviews with charging R&D directors at Shenzhen OEMs, procurement managers at North American enterprise IT departments, and neodymium magnet supply specialists at Guangdong separation facilities. Secondary validation drew from customs trade data, SEC 10-K disclosures of listed electronics accessory brands, and IEA technology cost tracking reports. Bottom-up demand modeling triangulated against top-down market sizing from component shipment aggregates.
Segmentation outputs reflect product type splits across USB Type-C, Lightning, Micro USB, and 3-in-1 configurations; power delivery tiers spanning standard, fast charging, and magnetic alignment specifications; and end-user categories including consumers, retailers, OEMs, and industrial buyers. CAGRs were derived from installed base replacement cycles, protocol transition timelines, and regional certification pipeline maturation. Forecast inputs incorporated GaN semiconductor cost curves, neodymium price volatility bands, and wireless charging penetration assumptions across smartphone tiers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to USB Power Delivery protocol fragmentation trajectories, right-to-repair legislative passage timelines, and rare earth export policy shifts from Chinese regulators. Forecasts reflect documented assumptions regarding certification backlog resolution and automotive platform standardization adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Single Core Cables Market
Cables
Global Cable Gland Market
Cables
Power and Signal Cables Market
Cables
High Voltage Cable Termination Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Fiber Optic Cable Accessories Market
Cables
Electric Vehicle Cables Market
Cables
Anti-Static Space Wires Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Submarine Optical Fiber Cables Market
Cables
Europe HVAC Cables Market
Cables
Global Ethernet Cable Market
Cables
LASER Light Cables Market
Cables
Europe Cable Joints Market
Cables
Sensor Cable Market
Cables
Multicore Cables Market