
 Middle East and Africa Submarine Cable System Market | 2026-2036
Middle East and Africa Submarine Cable System Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Submarine Cable System Market Foresight
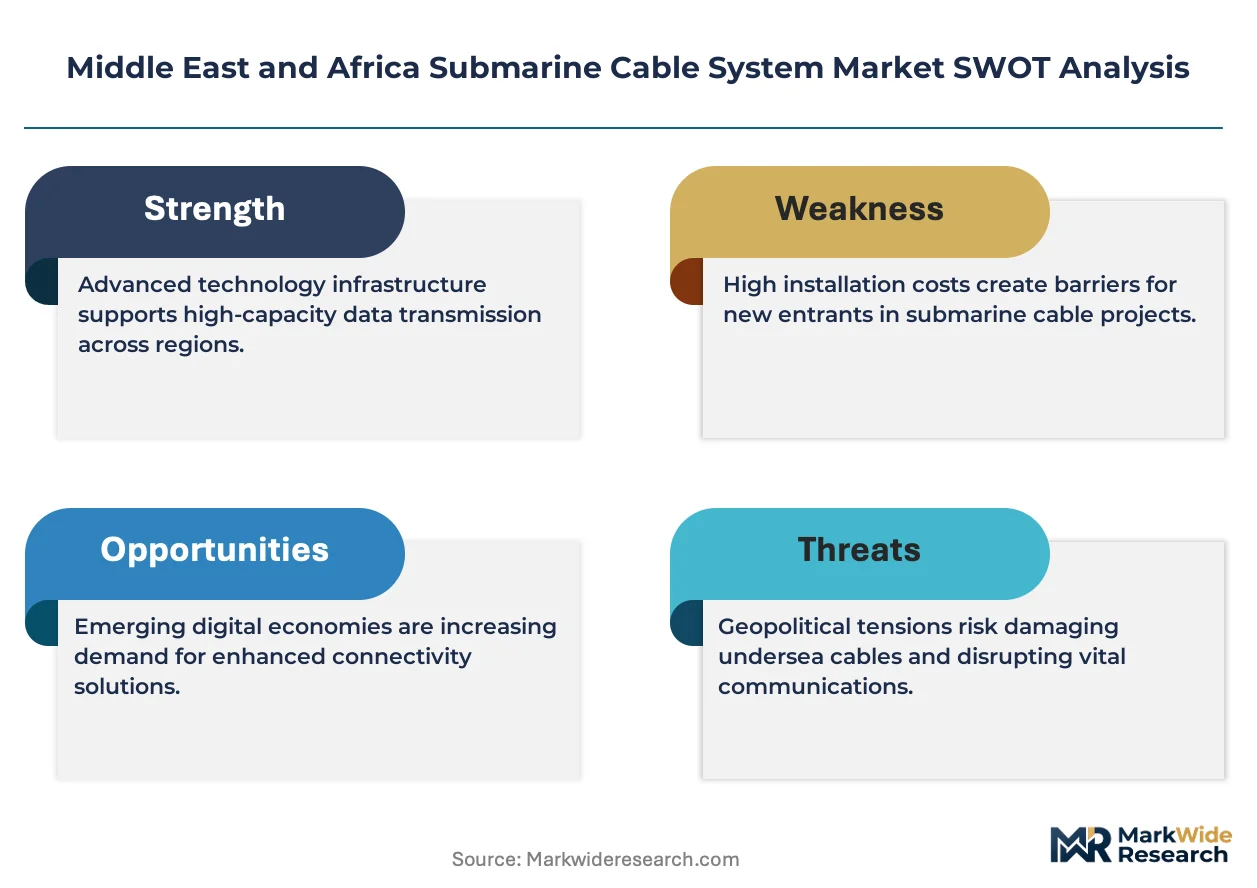
Subsea fiber routes between Europe and Asia are fragmenting as new entrants challenge legacy consortium models. Prysmian SpA leverages its Milan-based cable manufacturing complex to sustain supply continuity for Mediterranean-African projects. Alcatel Submarine Networks anchors turnkey installation capabilities across the Red Sea and East African littoral. NEC Corp competes through advanced repeater technology optimized for ultra-long-haul segments spanning the Indian Ocean.
A submarine cable system comprises fiber-optic bundles sheathed in polyethylene and steel armor, laid by specialized vessels across ocean floors to transmit terabit-scale data traffic between land-based stations. These systems serve as the physical backbone for intercontinental internet traffic, financial transaction networks, and cloud provider data synchronization. Fiber optic technology leads the technology dimension due to its near-zero signal attenuation over transoceanic distances, while telecom services dominate the application layer as mobile penetration across Sub-Saharan Africa strains existing backhaul infrastructure. Shore-end installation commands disproportionate margin pools because landing station permitting and coastal engineering complexity create bottlenecks that specialist contractors exploit.
Saudi Arabia's CITC, Egypt's National Telecom Regulatory Authority, and South Africa's ICASA each enforce cable landing licensing regimes that shape market access and foreign ownership structures for system operators. The EU's GDPR extraterritorially affects data routing decisions through Middle Eastern cable nodes serving European traffic. Stakeholders must monitor how the African Union's emerging digital sovereignty frameworks recalibrate cross-border bandwidth governance and investment protection terms.
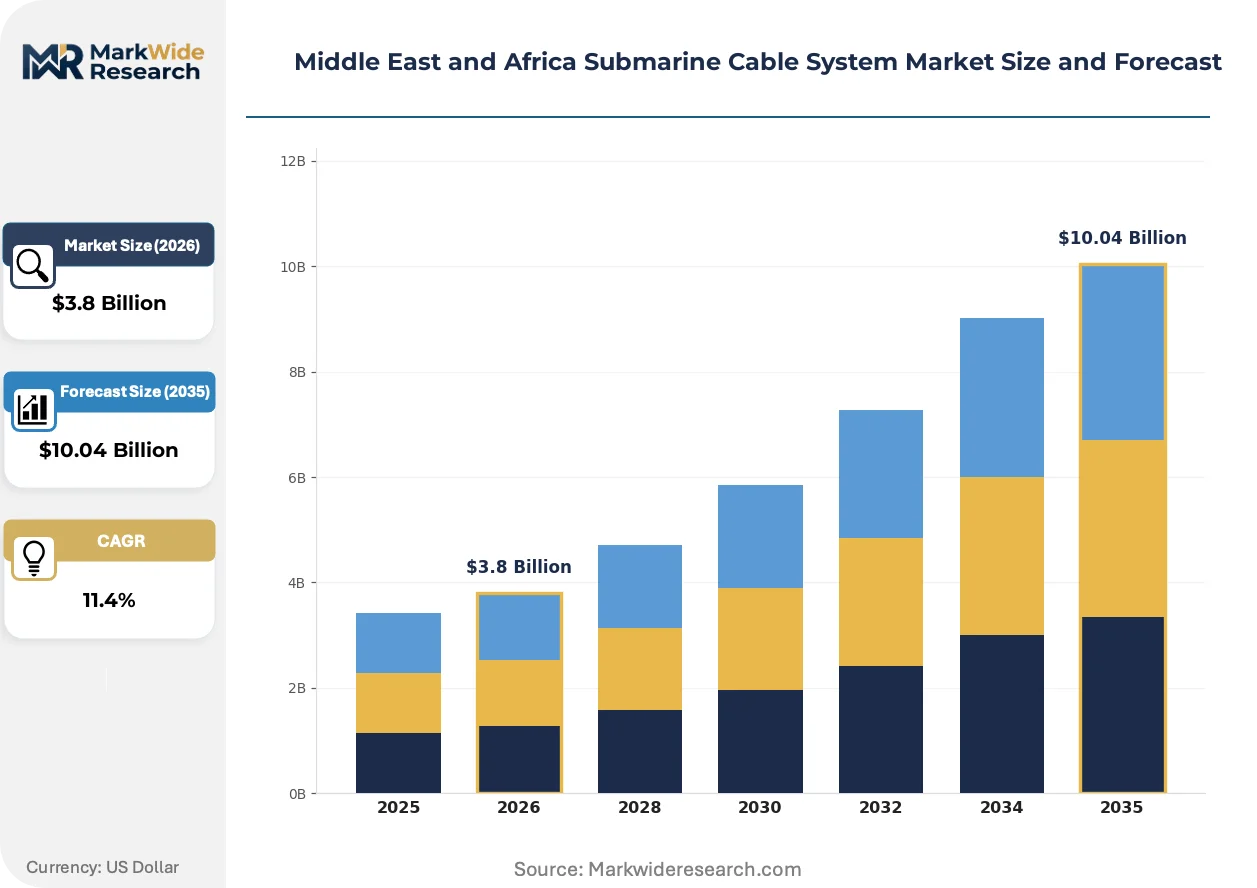
Market Dynamics
The Red Sea corridor is consolidating as the primary interconnection hub between Europe and Asia, with Egypt, Djibouti, and Saudi Arabia competing for cable landing primacy through streamlined licensing and coastal infrastructure investments.
Growth Catalysts
- Data Center Interconnect Scaling:Cloud service providers across the Middle East and Africa are expanding fiber capacity to synchronize distributed computing nodes. This demand surge is pulling cable capacity through the Suez corridor toward new landing stations in Djibouti and Saudi Arabia.
- CITC Licensing Streamlining:Saudi Arabia's Communications and Information Technology Commission has reduced approval timelines for international cable landing permits. Foreign system operators now secure coastal access rights faster than under previous regulatory frameworks.
- Sub-Saharan Mobile Backhaul Strain:Telecom operators from Nigeria to Kenya require submarine fiber extensions to relieve congestion on satellite-dependent rural networks. Terrestrial fiber extensions from coastal landing points are extending inland to serve these markets.
Market Restraints
- Specialized Vessel Scarcity:Cable-laying ship availability concentrates among European and East Asian operators. Charter rates for deep-water installation vessels have risen substantially, compressing project margins for consortia without captive fleet access.
- Copper and Steel Armor Volatility:Raw material costs for submarine cable sheathing fluctuate with commodity cycles. Manufacturers face margin pressure when hedging strategies fail to anticipate six-month price swings in polyethylene and galvanized steel wire.
- GDPR Extraterritorial Routing Constraints:The European Union's data protection framework restricts how traffic traverses Middle Eastern nodes serving European endpoints. Cable operators must architect redundant paths that avoid jurisdictional complications.
Strategic Opportunities
- East African Littoral Expansion:Mozambique, Tanzania, and Madagascar remain underserved by high-capacity submarine links. New cable landings at Maputo and Dar es Salaam would capture traffic from landlocked neighbors including Zambia and Malawi.
- Space-Ground Convergence:Low-earth orbit satellite constellations are creating hybrid architectures with submarine fiber. Cable operators can position landing stations as terrestrial aggregation points for Starlink and OneWeb backhaul traffic.
- African Union Digital Sovereignty Frameworks:Emerging continental policies on cross-border bandwidth governance may favor intra-African cable routes. Operators investing in direct Kenya-South Africa or Egypt-Nigeria links could benefit from preferential investment protection terms.
Industry Challenges
- Marine Survey and Permitting Expertise Gap:Qualified seabed route surveyors familiar with Red Sea bathymetry and coral reef protection protocols are scarce. Projects stall when environmental impact assessments require specialist contractors from outside the region.
- Shore-End Engineering Bottlenecks:Coastal landing station construction demands civil engineering capabilities that concentrate in Egyptian and South African firms. Other markets lack qualified contractors for beach manhole installation and terrestrial fiber handoff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Submarine Cable System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fiber Optic, Copper, Submarine Amplifiers, Repeaters Application: Telecom Services, Internet Backbone, Data Transmission, Broadcasting Services End User: Telecommunication Companies, Government, Enterprises, Research Institutions Installation Type: Shore-End, Deep-Sea, Undersea, Maintenance Operations |
| Companies Covered | SubCom, LLC, Prysmian SpA, Alcatel Submarine Networks, Nexans SA, NEC Corp, HMN Technologies Co., Ltd., Mitsubishi Electric Corp, Fujitsu Ltd, Hengtong Group Co., Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Submarine Cable System Market Shifts & Advancements
Submarine cable architecture is fragmenting from consortium ownership toward private systems, while optical transmission technology advances enable fewer repeaters over longer unrepeatered spans.
Multi-core fiber is virtualizing how capacity scales across transoceanic routes. This technology bundles independent optical paths within a single cladding, multiplying terabit throughput without additional cable lays. Hyperscale cloud providers are specifying multi-core designs for new private cable builds. The technology is virtualizing traditional consortium economics by enabling single-owner systems to match previous consortium capacity at lower coordination cost.
Saudi Arabia's CITC has introduced mandatory cybersecurity certification for cable landing station equipment. This policy requires foreign system operators to source switching hardware from approved vendor lists and submit source code audits. European and Asian cable consortia are restructuring procurement to pre-qualify compliant suppliers before bidding on Red Sea routes.
Buyer concentration among hyperscale cloud providers is compressing procurement cycles for new cable capacity. Amazon Web Services, Microsoft Azure, and Google Cloud now contract directly with manufacturers for dedicated fiber pairs, bypassing traditional telecom carrier intermediaries. This disintermediation is most visible in the Red Sea corridor, where private cable announcements now outnumber consortium projects.
Middle East and Africa Submarine Cable System Market Segmentation
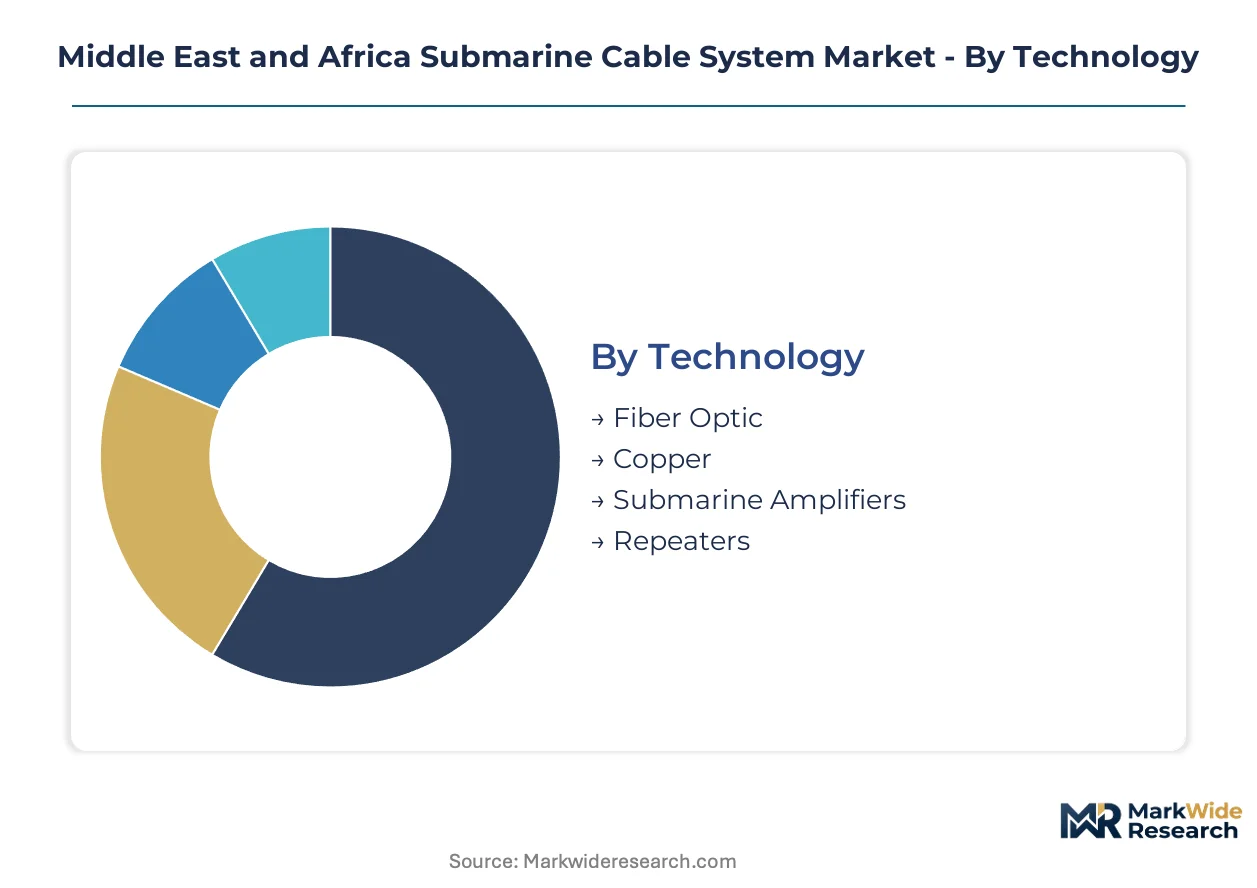
Segmentation in submarine cable systems reveals how capital cycles and operational intensity vary across technical layers. Technology choices lock in 15-25 year depreciation schedules, while installation types turn over on project-based rhythms measured in months.
Technology:
Fiber optic cables refresh slowest due to embedded capacity headroom, while amplifiers and repeaters cycle faster as optical transmission standards advance.
- Fiber Optic:Bundled silica strands sheathed in polyethylene and steel armor transmit terabit-scale traffic with near-zero attenuation over transoceanic distances. Demand concentrates along the Red Sea corridor where Egypt, Saudi Arabia, and Djibouti anchor new cable landings driven by hyperscale cloud provider requirements for data center interconnects.
- Submarine Amplifiers:Erbium-doped fiber modules spaced every 50-100 kilometers regenerate optical signals without electrical conversion. Procurement accelerates in the Indian Ocean basin where NEC Corp and Alcatel Submarine Networks compete on repeater efficiency for ultra-long-haul segments.
- Copper:Legacy coaxial conductors now limited to shore-end power feed applications and specialized military systems.
- Repeaters:Bidirectional optical amplifiers housed in pressure-resistant titanium casings for deep-water deployment.
Fiber optic dominates installed base across the Middle East and Africa. Submarine amplifiers represent where expansion concentrates as cable operators upgrade existing routes rather than lay new fiber.
Application:
Margin profiles diverge sharply between wholesale bandwidth arbitrage and managed enterprise services, with infrastructure ownership separating high-fixed-cost backbone operators from variable-cost service resellers.
- Telecom Services:Wholesale capacity leasing to mobile operators and internet service providers generates recurring revenue streams with 10-15 year contract tenors. Nigeria, Kenya, and South Africa drive demand as 4G and 5G rollouts strain satellite-dependent backhaul in Sub-Saharan Africa.
- Data Transmission:Dedicated fiber pairs for financial transaction networks and cloud synchronization command premium pricing due to latency sensitivity. The Suez corridor attracts private cable builds from Amazon Web Services, Microsoft Azure, and Google Cloud seeking direct control over Europe-Asia routing.
- Internet Backbone:Public internet traffic aggregation at cable landing stations for distribution to national networks.
- Broadcasting Services:Dedicated video distribution circuits for satellite backup and live event transmission.
Telecom services anchor revenue stability through long-term capacity agreements. Data transmission is climbing the fastest as hyperscale cloud providers disintermediate traditional carrier intermediaries.
End User:
Procurement sophistication varies from standardized RFP processes at incumbent telecom operators to bespoke security requirements at government agencies.
- Telecommunication Companies:MTN, Vodacom, and Saudi Telecom Company source capacity through consortium memberships or IRU (Indefeasible Right of Use) agreements. These operators prioritize route diversity and landing station redundancy over per-gigabit pricing.
- Government:National security and diplomatic networks require encrypted dedicated circuits with domestic landing station mandates. Saudi Arabia's CITC cybersecurity certification requirements now govern switching hardware procurement for state traffic.
- Enterprises:Multinational corporations in extractive industries and banking lease private wavelengths for intra-regional data synchronization.
- Research Institutions:Academic networks such as UbuntuNet Alliance and WACREN procure subsidized capacity for education and research traffic exchange.
Telecommunication companies control the largest share of contracted capacity. Government demand is expanding most quickly as digital sovereignty frameworks mandate domestic data routing and landing station ownership.
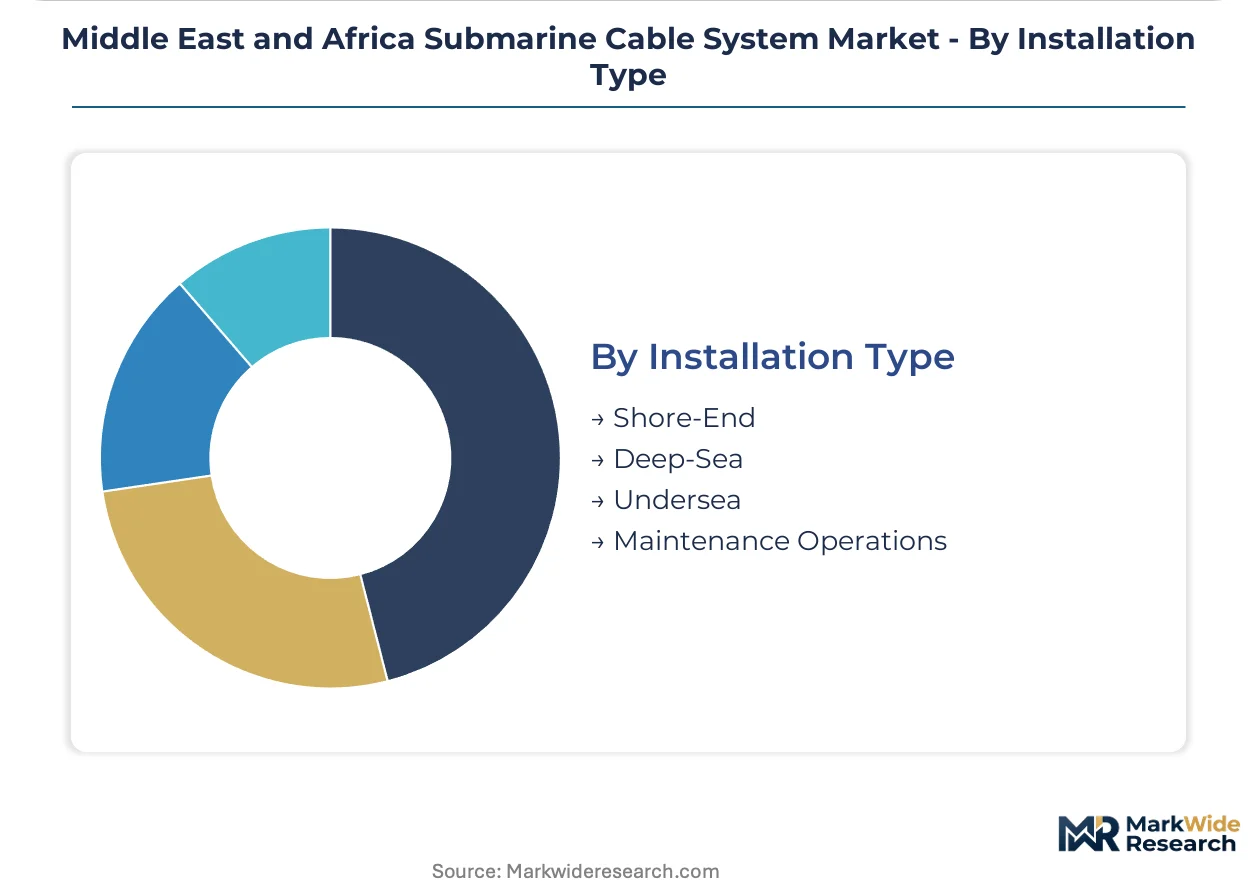
Installation Type:
Project duration and margin concentration invert between shore-end civil works and deep-sea cable laying, with coastal permitting bottlenecks extending timelines and inflating specialist contractor pricing.
- Shore-End:Beach manhole construction, terrestrial fiber handoff, and landing station civil engineering concentrate in Egyptian and South African contractors. Saudi Arabia's streamlined CITC licensing has compressed approval timelines, though coastal engineering capabilities remain scarce outside established markets.
- Deep-Sea:Cable-laying vessel operations across the Red Sea and Indian Ocean face charter rate inflation due to fleet concentration among European and East Asian operators. Prysmian SpA leverages its Milan manufacturing complex to sustain supply continuity for Mediterranean-African projects.
- Undersea:Shallow-water burial and protection systems in continental shelf zones.
- Maintenance Operations:Repair vessel dispatch and spare cable depot management for fault recovery.
Deep-sea installation commands the largest project value pools. Shore-end work is where margin expansion concentrates due to permitting bottlenecks and civil engineering capability scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt commands premium landing fees that Saudi Arabia and Djibouti now undercut through streamlined permitting, fragmenting pricing power across the Red Sea corridor.
Egypt
Submarine cable operators prioritize Alexandria and Port Said for Europe-Asia route diversity. The National Telecom Regulatory Authority enforces domestic landing station ownership mandates for state traffic. Cairo-based contractors dominate shore-end civil engineering, though Red Sea coastal projects face coral reef protection delays.
Saudi Arabia
Jeddah and Duba anchor new cable landings serving hyperscale cloud data center interconnects. CITC licensing reforms compressed international landing permit timelines from years to months. The King Abdullah Economic City cluster attracts private cable builds from Amazon Web Services and Microsoft Azure seeking direct Europe-Asia routing control.
Djibouti
Strategic positioning at the Bab el-Mandeb strait draws cable landings from multiple consortia. The national telecom regulator maintains open-access landing station policies that contrast with restrictive regimes elsewhere. Djibouti Telecom's coastal infrastructure investments position the city-state as a neutral interconnection hub for competing systems.
South Africa
Cape Town and Durban landing stations relieve Sub-Saharan backhaul congestion for MTN and Vodacom. ICASA licensing frameworks shape foreign ownership structures for system operators. The Western Cape civil engineering cluster supplies shore-end expertise that extends into Mozambique and Tanzanian projects.
United Arab Emirates
Fujairah's Indian Ocean positioning captures Asia-Africa traffic outside Suez-dependent routes. The national telecom regulator coordinates with Saudi CITC on cross-border fiber extensions. Dubai's financial transaction networks drive demand for dedicated low-latency circuits to European trading hubs.
Middle East and Africa Submarine Cable System Market Competitive Landscape
Integrated cable manufacturers and turnkey installation specialists split the market along capital intensity lines. European and East Asian players concentrate manufacturing and fleet ownership, creating tiered access for regional consortia. Three archetypes dominate: vertically integrated manufacturers with captive cable-laying vessels, pure-play installation contractors leasing fleet capacity, and state-backed champions securing domestic landing rights. Competitive moves center on manufacturing capacity expansion in Mediterranean hubs and strategic partnerships for Red Sea route access.
Among integrated manufacturers, Prysmian SpA leverages its Milan-based production complex for Mediterranean-African supply continuity, while Alcatel Submarine Networks anchors turnkey capabilities across the Red Sea littoral. NEC Corp occupies a distinct position through advanced repeater technology for Indian Ocean ultra-long-haul segments. These three exemplify how manufacturing scale, installation integration, and component specialization create defensible positions in a capital-intensive industry.
| Leading Market Players |
|---|
| SubCom, LLC |
| Prysmian SpA |
| Alcatel Submarine Networks |
| Nexans SA |
| NEC Corp |
| HMN Technologies Co., Ltd. |
| Mitsubishi Electric Corp |
| Fujitsu Ltd |
| Hengtong Group Co., Ltd. |
| Others |
Supply & Pricing Matrix
Deep-water cable-laying vessel undercapacity across the Red Sea corridor is compressing project margins and forcing consortia into longer-term charter commitments that lock in cost structures. Saudi Arabia's CITC licensing reforms have intensified competition for coastal access rights, fragmenting pricing power that Egypt previously monopolized.
Pricing Analysis
The customization-premium spread between configured-to-order private cable systems and standard consortium capacity runs wide across the Middle East and Africa. Project-based long-term offtake contracts dominate, with price differentiation driven by repeater technology grade and landing station redundancy levels. Pricing pressure stems from hyperscale cloud providers disintermediating traditional carriers and negotiating directly with manufacturers. Telecom operators remain most price-sensitive due to thin wholesale margins, while financial services buyers absorb premiums for latency-guaranteed circuits.
Supply Chain Analysis
Tariff exposure between European cable-laying vessel operators and East Asian component suppliers dominates supply chain risk calculus for Red Sea projects. Manufacturing concentrates in Italy, France, and Japan for fiber-optic cable and repeater housings. Raw material dependencies rest on polyethylene sheathing, galvanized steel armor wire, and erbium-doped fiber for amplifiers. Single-source vulnerability concentrates in specialized titanium casing foundries for deep-water repeaters. Distribution runs through turnkey installation contractors who bundle manufacturing, marine survey, and vessel charter into unified project delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa submarine cable market sits at a high-growth inflection as multi-core fiber technology virtualizes traditional consortium economics and enables private system builds at previously unattainable scale. Saudi Arabia's CITC cybersecurity certification mandates for landing station equipment are reshaping procurement requirements and vendor qualification timelines.
For Market Incumbents: Pre-empt hyperscale cloud provider disintermediation by securing captive cable-laying vessel capacity through long-term charter agreements or fleet acquisitions. Prysmian SpA and Alcatel Submarine Networks should deepen backward integration into repeater component manufacturing to defend margin position against NEC Corp's technology specialization. Shore-end engineering capability scarcity in emerging markets like Mozambique and Tanzania presents consolidation targets for Egyptian and South African civil engineering clusters. For New Entrants and Emerging Players: Establish a beachhead in East African littoral markets where Maputo and Dar es Salaam remain underserved by high-capacity submarine links. The Kenya-South Africa direct route segment offers white-space opportunity as African Union digital sovereignty frameworks may favor intra-African cable investments with preferential terms. Target research and education networks through subsidized capacity partnerships with UbuntuNet Alliance and WACREN as a low-competition entry channel. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across private cable system builds as multi-core fiber technology and advanced repeater specifications raise upfront project costs. Long-term viability favors vertically integrated manufacturers with captive vessel fleets and Mediterranean production hubs over pure-play installation contractors exposed to charter rate volatility. Acquisition target archetypes include shore-end civil engineering specialists in Egypt and South Africa with proven Red Sea bathymetry expertise. The signal to watch is CITC-equivalent cybersecurity certification spreading to other national regulators, which would force hardware procurement restructuring across existing systems.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Core Fiber Deployment | Hyperscale cloud providers specify multi-core designs to multiply terabit throughput without additional cable lays. |
| Cable-Laying Vessel Acquisition | Consortia secure captive fleet access to escape charter rate inflation from European and East Asian operator concentration. |
| Cybersecurity Certification Compliance | Saudi CITC mandates force foreign operators to pre-qualify approved switching hardware vendors before Red Sea bidding. |
| East African Littoral Expansion | New landings at Maputo and Dar es Salaam capture landlocked neighbor traffic from Zambia and Malawi. |
| Space-Ground Convergence Positioning | Cable operators configure landing stations as terrestrial aggregation points for Starlink and OneWeb backhaul traffic. |
Research Methodology
Desk research of regulatory filings from Saudi CITC, Egypt's National Telecom Regulatory Authority, and South Africa's ICASA preceded structured interviews with submarine cable system procurement leads at hyperscale cloud providers, marine survey contractors, and shore-end civil engineering specialists. Secondary validation drew from cable consortium press releases, vessel charter market reports, and hyperscaler capex disclosures. Bottom-up project pipeline aggregation and top-down bandwidth demand modeling were triangulated against regional mobile penetration forecasts and data center interconnect scaling announcements.
Forecasts assume stable regulatory licensing frameworks across the analysis window, with segmentation dimensions spanning technology type, application layer, end-user category, and installation type. CAGRs were derived from capacity deployment schedules and bandwidth pricing trajectories, incorporating hyperscale cloud provider demand elasticity and Sub-Saharan mobile backhaul investment cycles. Industry-specific inputs include Red Sea cable landing station permitting timelines and specialized vessel availability constraints.
Sensitivities concentrate around CITC cybersecurity certification adoption by other national regulators, African Union digital sovereignty framework implementation timelines, and deep-water vessel charter rate volatility. Forecasts reflect assumptions about hyperscale cloud provider procurement acceleration and terrestrial fiber extension pace from coastal landing points. Material shifts in Red Sea geopolitical stability or multi-core fiber commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Twisted Pair Cable Market
Cables
Magnetic Charging Cable Market
Cables
North America Copper Wire and Cable Market
Cables
Submarine Cabling Systems Market
Cables
Flat Flexible Cables Market
Cables
Polyurethane Cable Market
Cables
Electric Vehicle Cables Market
Cables
High Voltage Cable Termination Market
Cables
Europe Wire and Cable Market
Cables
Cable Carrier Market
Cables
Aluminium Battery Cable Market
Cables
Global Ethernet Cable Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Submarine Cable System Market
Cables
Wire and Cable Label Market
Cables
Cable Clamp Market