
 Ethernet Converters Market | 2026-2036
Ethernet Converters Market Size, Share, and Industry Trends Forecast 2026-2036
Ethernet Converters Market Foresight
The Ethernet Converters Market is recalibrating around a widening gap between hardened industrial-grade units and low-cost consumer-oriented devices. Moxa Inc. dominates the premium industrial tier with extended temperature-range designs and rail-specific certifications. Advantech Co., Ltd. leverages its embedded computing heritage to bundle converters with edge gateways. Belden Inc. anchors North American factory-floor demand through its cable-to-converter integration strategy.
Ethernet converters translate signal types between disparate physical layers, typically bridging copper twisted-pair, fibre optic, or serial RS-232/485 interfaces to standard IEEE 802.3 Ethernet with throughput from 10 Mbps to 10 Gbps depending on port configuration. Fibre Optic technology leads in revenue contribution due to electromagnetic immunity requirements in heavy industrial settings, while PoE Injector units represent the fastest-expanding product type as powered-device deployments multiply in security and building-automation networks. DIN Rail installation formats command the strongest margin pools given their integration into controlled-environment electrical enclosures.
FCC Part 15 emissions rules in the United States, CE marking under the EU's Radio Equipment Directive, and China's GB/T standards enforced by SAMR collectively dictate electromagnetic compatibility and safety compliance for cross-border shipments. IEC 62443 industrial cybersecurity frameworks are forcing firmware-hardening investments that smaller vendors struggle to absorb. Stakeholders must weigh certification depth against addressable market breadth when configuring regional product portfolios.
Market Dynamics
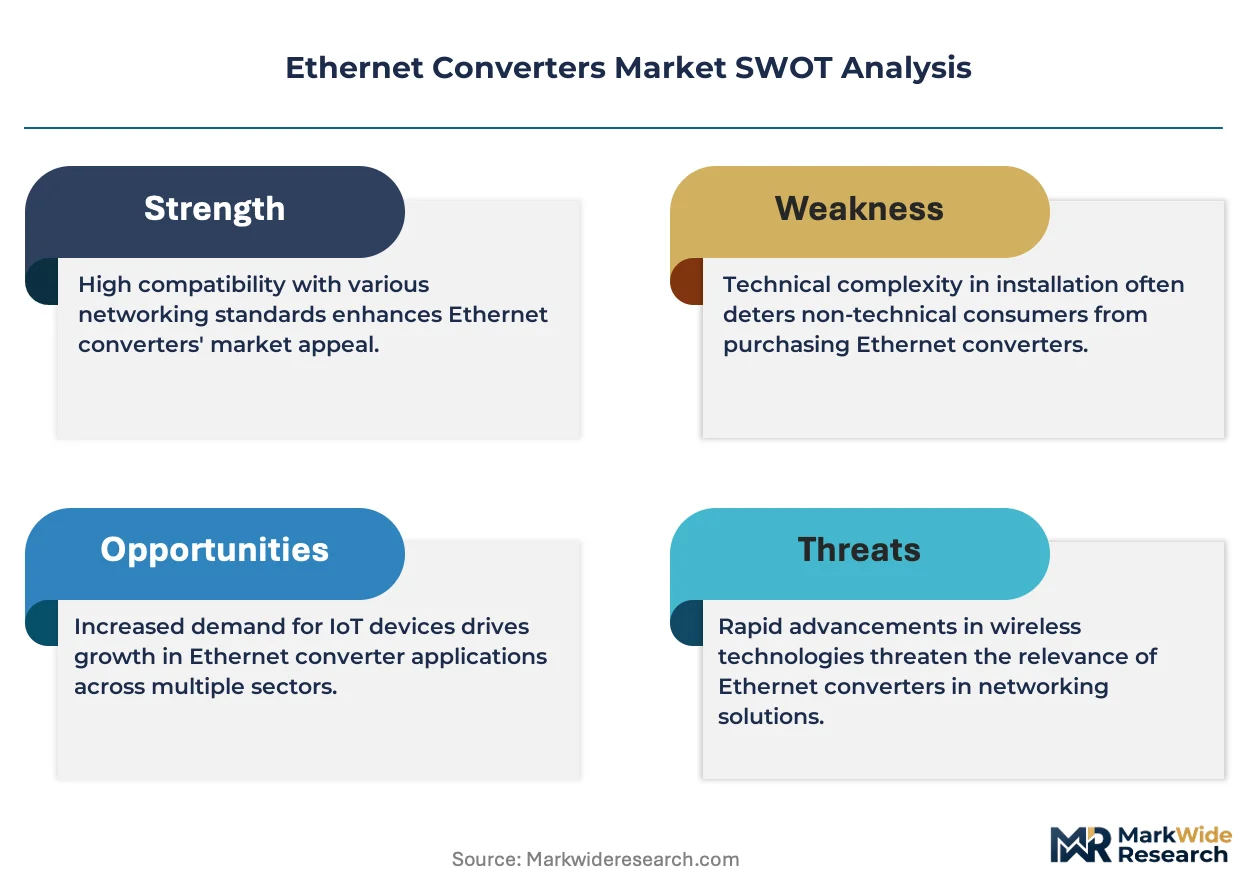
The Ethernet Converters Market is restructuring around IEC 62443 cybersecurity mandates that force firmware-hardening investments, creating a capability gap between industrial-grade specialists and cost-focused commodity vendors.
Growth Catalysts
- Smart Factory Retrofits:China's eastern manufacturing corridor accelerates deployment of serial-to-Ethernet bridges as legacy equipment integrates with modern backbones.
- IEEE 802.3bt High-Power PoE:Powered-device proliferation in building automation and security networks expands addressable use cases for injector-style converters.
- Electromagnetic Immunity Requirements:Heavy industrial settings in Germany and Japan drive fibre optic converter adoption to eliminate interference risks in high-noise environments.
Market Restraints
- Semiconductor Input Volatility:FPGA and industrial-grade PHY chip supply concentration in Taiwan creates component cost instability for converter manufacturers.
- Certification Timeline Friction:FCC Part 15 emissions testing and CE marking under the EU Radio Equipment Directive extend product launch cycles by 8-14 months.
- Wireless Substitution Threat:Wi-Fi 6E and 5G private networks displace copper-to-fibre conversion in mobile equipment and temporary installations.
Strategic Opportunities
- Edge Gateway Convergence:Bundling protocol converters with local analytics engines captures value from IT/OT integration budgets in process industries.
- India Manufacturing Incentives:PLI scheme subsidies for electronics production attract converter assembly investments serving domestic automation demand.
- Single-Pair Ethernet Expansion:IEEE 802.3cg 10BASE-T1L standard enables long-reach sensor networks in oil and gas infrastructure previously served by serial buses.
Industry Challenges
- Firmware Security Skill Scarcity:IEC 62443-4-2 secure development lifecycle requirements outpace available embedded cybersecurity engineering talent pools.
- Legacy Protocol Integration Complexity:Multi-generational RS-485 networks in brownfield facilities demand custom baud-rate mapping and timing calibration that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethernet Converters Market |
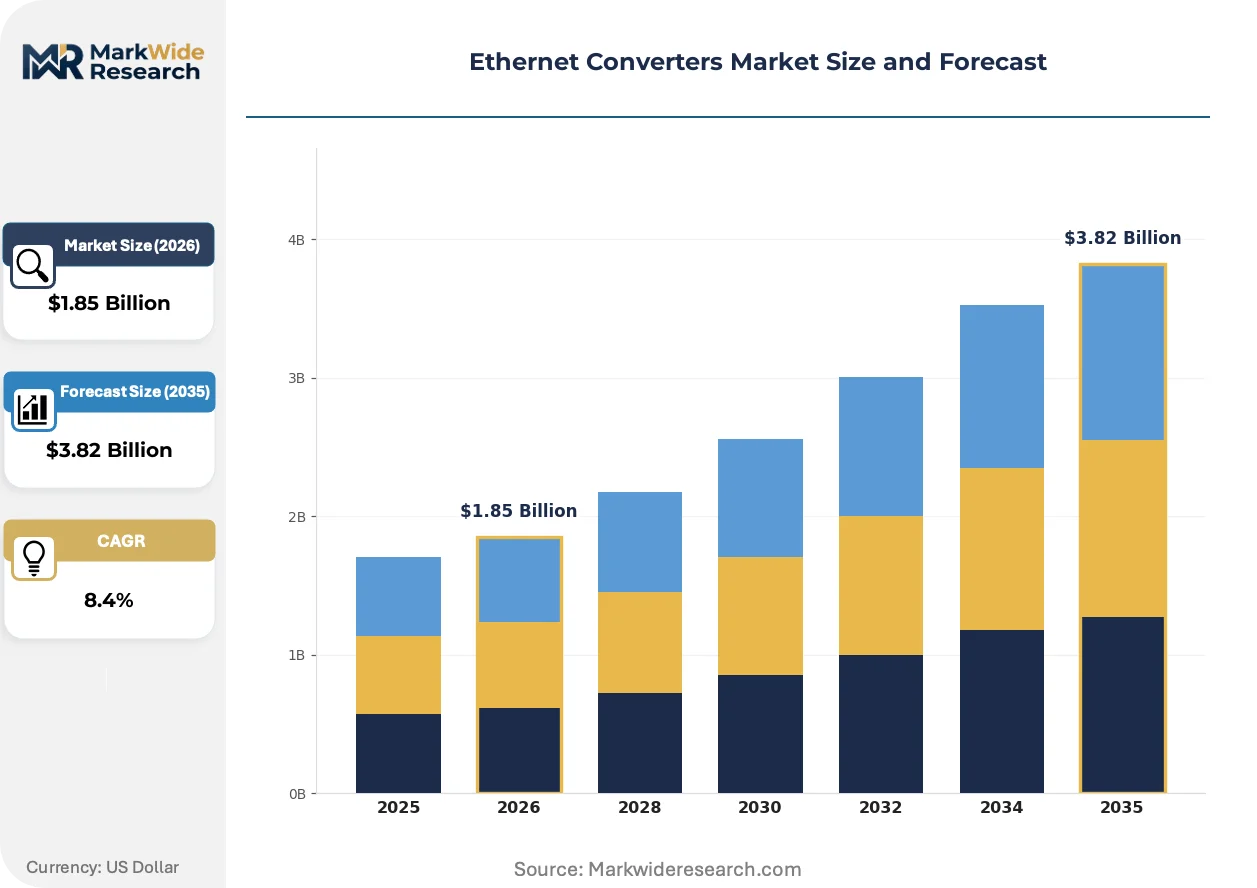
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Media Converter, Serial Converter, PoE Injector, Network Switch Technology: Fibre Optic, Copper, Wireless, Hybrid End User: Telecommunications, Industrial Automation, IT & Networking, Security Systems Installation: Wall-Mounted, Rack-Mounted, DIN Rail, Desktop |
| Companies Covered | Moxa Inc., Advantech Co., Ltd., Cisco Systems Inc., Belden Inc., PLANET Technology, Allied Telesis, Antaira, Omnitron Systems, Versa Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethernet Converters Market Shifts & Advancements
Converter architecture is bifurcating between hardened industrial platforms and software-defined edge nodes, with cybersecurity certification becoming the primary competitive differentiator rather than port density or raw throughput.
Fibre optic Ethernet converters are overtaking copper-based alternatives in heavy industrial settings where electromagnetic immunity determines operational reliability. Mining operations and steel mills in Germany and Japan have standardized on fibre-to-Ethernet bridges to eliminate ground-loop failures. This shift is compressing margins for copper-centric vendors while rewarding suppliers with integrated fibre termination capabilities.
REACH substance restrictions and RoHS 3 amendments in Europe are forcing converter manufacturers to eliminate cadmium-plated connectors and specific brominated flame retardants from enclosure materials. Industrial automation OEMs serving EU export markets now demand full material declaration documentation upstream. DIN rail converter suppliers with pre-certified component libraries are capturing specification preference from system integrators.
Buying committees in process industries now unbundle hardware procurement from lifecycle service contracts, separating converter supply from configuration support and firmware update subscriptions. System integrators in North American oil and gas verticals are shifting from distributor-led purchasing to direct manufacturer relationships with dedicated application engineering. This disintermediation pressures traditional industrial distribution channels that historically captured 25-30 point margins on converter sales.
Ethernet Converters Market Segmentation
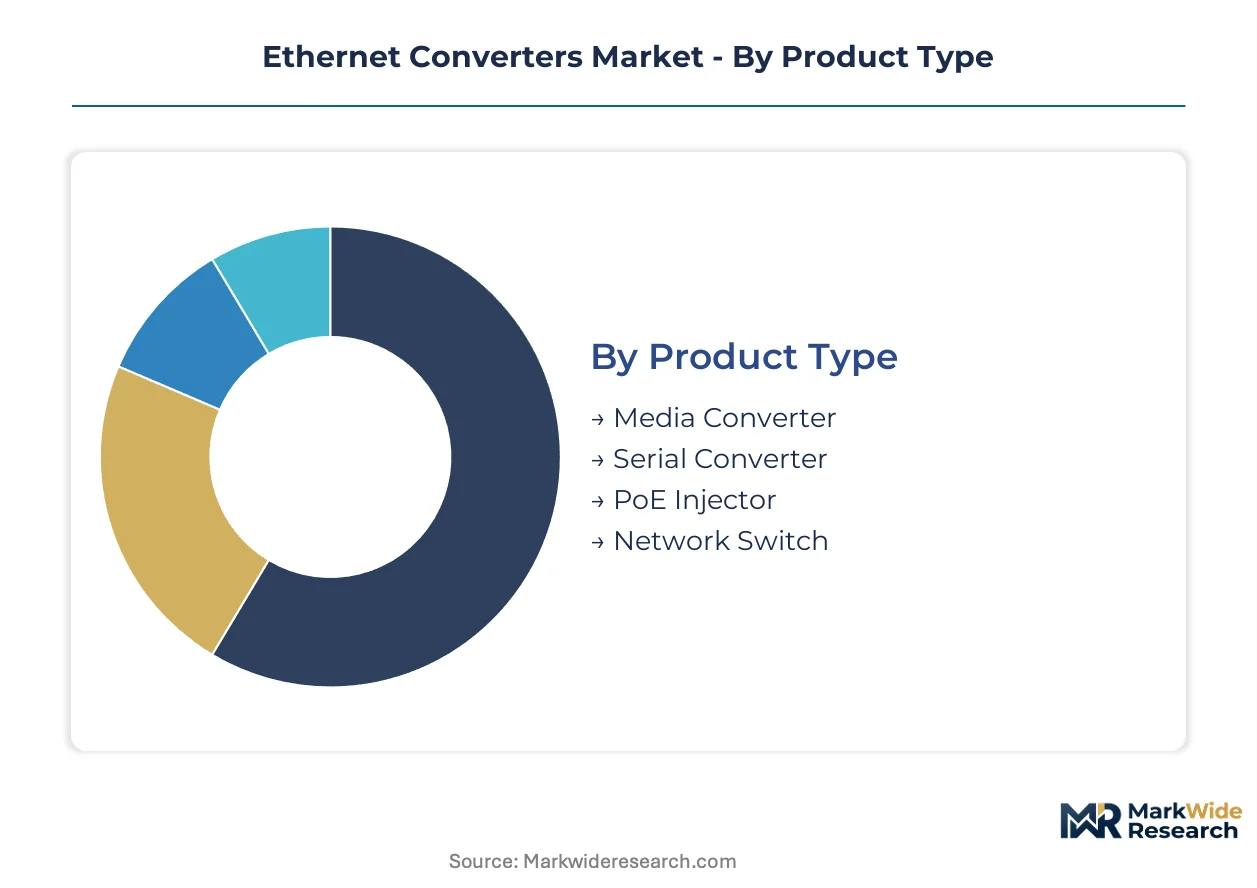
Ethernet converter purchasing decisions hinge on environmental hardening requirements, protocol translation complexity, and power delivery specifications. Buyers in heavy industrial settings prioritize electromagnetic immunity and temperature tolerance over port density, while building automation contractors optimize for PoE budget and physical form factor.
Product Type:
Procurement teams segment converter investments by integration depth—standalone protocol bridges versus power-delivery-integrated units—reflecting divergent IT/OT ownership structures across end-use environments.
- Media Converter:These devices bridge disparate physical layer standards, typically translating between copper twisted-pair and fibre optic interfaces. Mining operations in Germany specify these units for electromagnetic immunity in high-noise environments where ground-loop failures disable copper-based alternatives. Signal integrity requirements in Japanese steel mills reinforce this specification pattern.
- PoE Injector:Midspan power insertion devices enable IEEE 802.3bt high-power delivery to remote cameras, access points, and building automation endpoints without dedicated electrical runs. China's eastern manufacturing corridor deploys these aggressively during smart factory retrofits where legacy serial equipment requires both protocol translation and remote power.
- Serial Converter:RS-232/485-to-Ethernet bridges preserve investment in legacy field devices while enabling modern backbone connectivity. Brownfield facilities demand custom baud-rate mapping.
- Network Switch:Multi-port aggregation devices with embedded conversion logic reduce cabinet footprint in space-constrained electrical enclosures. Data center edge applications favor these.
Media converters lead on scale; PoE injectors lead on momentum.
Technology:
Physical layer selection follows interference exposure and reach requirements rather than cost optimization alone.
- Fibre Optic:Glass or plastic core transmission eliminates electromagnetic susceptibility and enables kilometer-scale distances between network nodes. German automotive production lines and Japanese precision manufacturing floors have standardized on these interfaces to prevent signal corruption from welding equipment and variable frequency drives.
- Copper:Twisted-pair implementations dominate cost-sensitive installations with short reach requirements and controlled electromagnetic environments. Commercial building retrofits in China leverage existing Cat5e infrastructure.
- Wireless:Radio-based bridges serve temporary installations and mobile equipment where physical cabling proves impractical. 5G private networks are displacing some legacy applications.
- Hybrid:Multi-physical-layer devices combine copper, fibre, and wireless interfaces in unified enclosures for heterogeneous plant architectures. Process industries with multi-generational equipment favor these.
Fibre optic deployments anchor industrial-grade revenue; hybrid configurations are gaining share fastest.
End User:
Budget ownership and technical specification authority vary sharply across verticals, with industrial automation teams demanding hardened certifications that telecommunications buyers rarely require.
- Industrial Automation:Factory-floor networks integrate legacy serial equipment with modern Ethernet backbones under IEC 62443 cybersecurity mandates. Germany and Japan drive specification intensity here.
- Security Systems:Video surveillance and access control networks prioritize PoE budget aggregation and remote management capabilities. China's urban infrastructure projects scale these deployments.
- Telecommunications:Carrier backhaul and central office applications emphasize port density and hot-swappable redundancy. These buyers drive volume but compress margins.
- IT & Networking:Enterprise data center edge and campus distribution applications balance performance with administrative simplicity. Standardized management protocols dominate specifications.
Industrial automation commands premium pricing; security systems show steepest expansion trajectory.
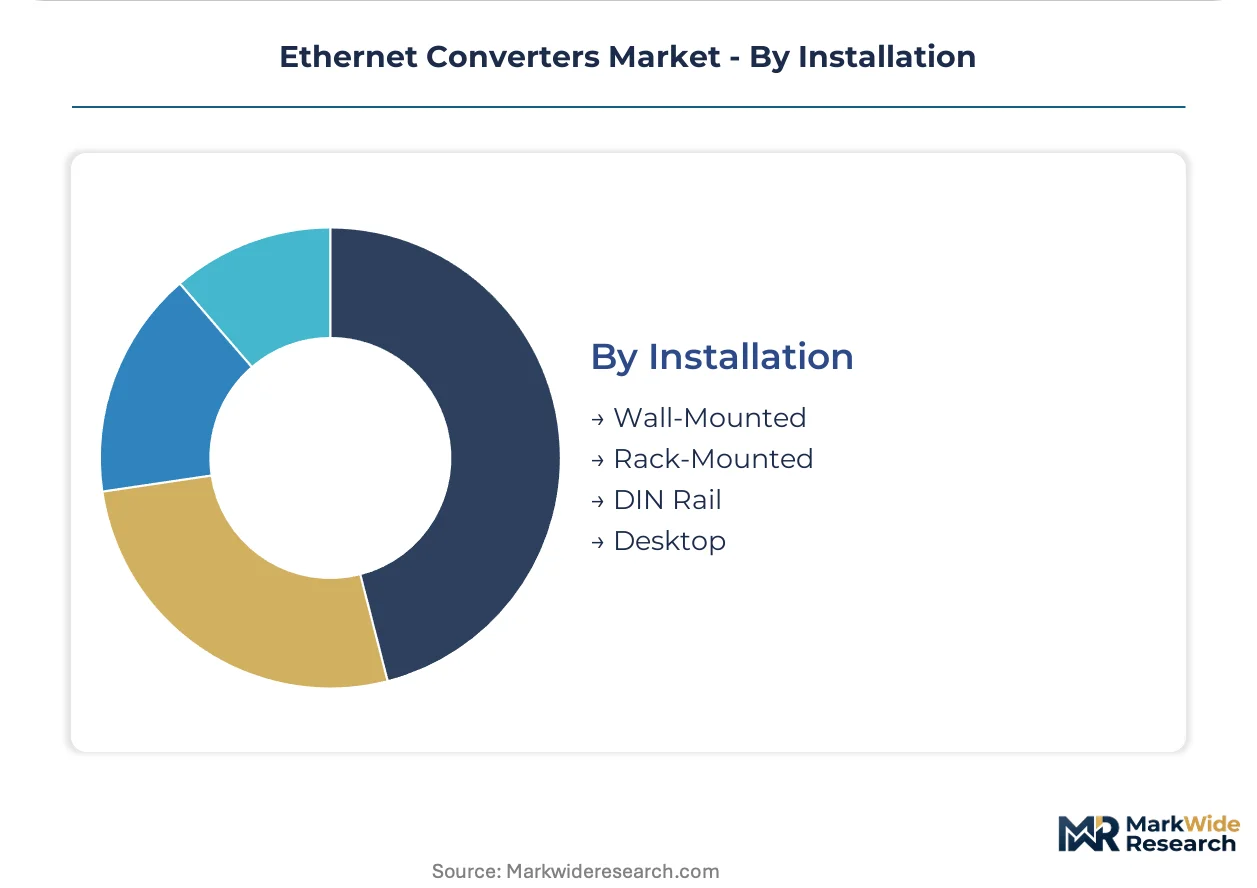
Installation:
Mechanical form factor determines enclosure compatibility and thermal management approach, with electrical cabinet integration requirements filtering vendor selection.
- DIN Rail:Standardized 35mm rail mounting dominates controlled-environment electrical enclosures in European and Asian industrial facilities. REACH and RoHS 3 compliance documentation now gates supplier qualification.
- Rack-Mounted:19-inch EIA standard chassis serve telecommunications and data center environments where port density and cable management drive design. These installations emphasize hot-swap serviceability.
- Wall-Mounted:Bracket-fixed units serve building automation and security applications with distributed, low-density endpoint requirements. Aesthetic enclosure design influences selection.
- Desktop:Standalone powered devices address laboratory, test, and temporary configuration scenarios. These carry lowest specification burden and highest price sensitivity.
DIN rail formats capture strongest margin pools; rack-mounted units dominate volume in telecommunications infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation density contrasts sharply with India's emerging factory digitization, creating divergent converter specification profiles across manufacturing economies.
Germany
Automotive production lines in Stuttgart and Wolfsburg drive fibre optic converter deployment for electromagnetic immunity against welding interference. IEC 62443 cybersecurity mandates from BSI tighten firmware requirements for factory-floor networks. The Ruhr industrial corridor accelerates brownfield retrofits integrating legacy serial equipment with modern Ethernet backbones.
China
Smart factory initiatives across the eastern manufacturing corridor multiply serial-to-Ethernet bridge demand for legacy equipment integration. GB/T standards enforced by SAMR dictate electromagnetic compatibility compliance for domestic and export shipments. Shenzhen and Shanghai clusters concentrate converter procurement for automation upgrades in electronics and automotive assembly.
United States
Oil and gas infrastructure in Texas and the Gulf Coast expands hybrid converter deployment for multi-generational equipment integration. FCC Part 15 emissions rules extend product launch timelines for cross-border shipments. The Permian Basin drives specification intensity for hardened units in high-temperature, high-vibration environments.
Japan
Precision manufacturing floors in Nagoya and Osaka standardize on fibre-to-Ethernet bridges to prevent signal corruption from variable frequency drives. METI industrial policy incentivizes cybersecurity-hardened converter adoption under national digitization frameworks. The Chubu region concentrates demand from automotive and robotics OEMs requiring extended temperature-range designs.
India
Electronics manufacturing incentives under the PLI scheme attract converter assembly investments serving domestic automation demand. BIS certification requirements tighten for industrial networking equipment deployed in government-backed smart city projects. Gujarat and Maharashtra industrial corridors scale deployment for textile and pharmaceutical facility upgrades.
Ethernet Converters Market Competitive Landscape
Top-tier vendors anchor the premium industrial tier with extended temperature certifications and rail-specific designs, while cost-focused commodity suppliers compete on port density and raw throughput. The vendor base stratifies across three capability layers: hardened industrial specialists, embedded computing integrators, and telecommunications volume suppliers. Strategic moves concentrate on edge gateway convergence bundling and regional certification pre-qualification to accelerate specification capture.
Within the industrial-grade tier, Moxa Inc. and Advantech Co., Ltd. exemplify divergent positioning strategies—Moxa anchoring pure-play converter specialization, Advantech leveraging embedded computing heritage for gateway bundling. Belden Inc. occupies a position in North American factory-floor demand through cable-to-converter integration approaches. These three entities represent the archetype spectrum from component purity to system integration that defines competitive differentiation.
| Leading Market Players |
|---|
| Moxa Inc. |
| Advantech Co., Ltd. |
| Cisco Systems Inc. |
| Belden Inc. |
| PLANET Technology |
| Allied Telesis |
| Antaira |
| Omnitron Systems |
| Versa Technology |
| Others |
Supply & Pricing Matrix
Industrial-grade FPGA and PHY chip price indices from Taiwan semiconductor foundries cascade through three converter pricing tiers, compressing margins for mid-range suppliers while hardening premium positions for IEC 62443-certified vendors serving German and Japanese factory floors.
Pricing Analysis
Capacity additions in China's eastern manufacturing corridor are reshaping price floors for standard-grade serial converters, forcing a three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture margin through IEC 62443-4-2 certification and extended temperature-range designs for German automotive lines. Price differentiation hinges on cybersecurity compliance depth and DIN rail enclosure material declarations under REACH. Cost compression in economy-tier copper units intensifies because of wireless substitution threats from Wi-Fi 6E. Building automation contractors in China exhibit highest price sensitivity; process industry buyers in Texas oil and gas fields show lowest.
Supply Chain Analysis
Industrial-grade FPGA supply rests on Taiwanese specialty semiconductor foundries, with secondary sourcing from South Korean memory suppliers and Japanese precision component manufacturers. Converter assembly draws from China for PCB fabrication, Mexico for North American logistics proximity, and Vietnam for cost-sensitive consumer-grade units. Raw material dependencies include copper-clad laminates, fibre optic transceivers, and DIN rail aluminum extrusions. Single-source vulnerability concentrates in Taiwan for industrial PHY chips. Distribution runs through industrial automation distributors in Europe, direct manufacturer relationships in North American oil and gas, and systems integrators in Chinese smart factory corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ethernet Converters Market functions as a regulatory compounder where IEC 62443 cybersecurity mandates from Germany's BSI and Japan's METI continuously tighten entry barriers and sustain pricing power for compliant vendors.
For Market Incumbents: Lock in specification capture by pre-certifying component libraries for REACH and RoHS 3 compliance, eliminating cadmium-plated connectors before EU enforcement tightens. Deepen backward integration into fibre optic termination capabilities to capture margin compression from copper-centric competitors. Defend against wireless substitution threats by bundling protocol converters with edge gateway analytics engines for IT/OT integration budgets in process industries. For New Entrants and Emerging Players: Enter via India's PLI scheme electronics manufacturing subsidies, establishing assembly capacity for domestic automation demand in Gujarat and Maharashtra corridors. Target white-space in Single-Pair Ethernet converter designs for IEEE 802.3cg 10BASE-T1L oil and gas sensor networks previously served by serial buses. Pursue direct relationships with North American system integrators disintermediating traditional distribution channels. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap industrial networking specialists possessing pre-certified DIN rail component libraries and IEC 62443 secure development lifecycle capabilities. Long-term viability favors vendors with firmware-hardening engineering benches and regional certification pre-qualification across Germany, Japan, and China. Watch for inflection when brownfield retrofit timelines in China's eastern manufacturing corridor accelerate beyond greenfield deployment rates.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Gateway Convergence | Bundling protocol converters with local analytics engines captures IT/OT integration budgets in German process industries. |
| IEC 62443 Certification Investment | Firmware-hardening capabilities under BSI mandates create sustainable differentiation against commodity vendors. |
| Fibre Optic Integration | In-house termination capabilities reward suppliers as German steel mills standardize on electromagnetic-immune bridges. |
| Regional Assembly Localization | India PLI scheme subsidies attract converter investments serving domestic textile and pharmaceutical automation demand. |
| Direct Channel Disintermediation | Manufacturer relationships with Texas oil and gas integrators bypass 25-30 point distributor margin capture. |
Research Methodology
Coverage spans Germany, China, the United States, Japan, and India, with primary inputs from each region combining structured interviews with plant engineers, OEM procurement teams, systems integrators, and aftermarket service heads alongside secondary validation. Primary research incorporated technical discussions with industrial automation specification committees and brownfield retrofit project managers. Secondary sources included customs and trade flow data, SEC 10-K filings from listed networking equipment vendors, IEEE standards documentation, and national regulatory filings with Germany's BSI and Japan's METI. Bottom-up unit shipment estimates triangulated against top-down industrial automation capex allocations.
Granularity-level modeling disaggregated volume and value across product type, physical layer technology, end-use vertical, and installation form factor dimensions throughout the forecast period. Segment-level CAGRs derived from regression analysis against industrial production indices and factory digitization investment rates. Industry-specific forecast inputs included smart factory retrofit pipeline data from China's eastern manufacturing corridor and IEC 62443 adoption timelines from German automotive OEMs.
Inputs from IEEE standards committees and national cybersecurity regulators were available through the study window; gaps in private brownfield facility deployment schedules introduce uncertainty bands around China retrofit velocity assumptions. Forecasts reflect documented assumptions regarding semiconductor supply normalization and certification timeline friction persistence. A small set of triggers warrants ongoing watch: Taiwan FPGA supply disruption, 5G private network substitution acceleration, and REACH substance restriction enforcement tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Network Cable Tester Market
Cables
Audio and Video Cables Market
Cables
Low Voltage Cable Accessories Market
Cables
Premise Cable Market
Cables
Copper Cable Market
Cables
Wire and Cable Label Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Global Wires and Cables Market
Cables
Cable Fault Locator Market
Cables
Downhole Cables Market
Cables
Europe Wire and Cable Market
Cables
Flexible Cables Market
Cables
North America Wire and Cable Market
Cables
Polyurethane Cable Market
Cables
Europe Cable Management Market
Cables
UK Cables Market