
 Electrical Measuring Instrument Market | 2026-2036
Electrical Measuring Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Measuring Instrument Market Analytics
Southeast Asian contract manufacturers are expanding test-equipment assembly lines to serve automotive electronics suppliers. Yokogawa Electric Corporation leverages deep vertical integration in precision ADC fabrication to dominate high-end oscilloscope segments. Keysight Technologies sustains R&D intensity across 5G and automotive radar test portfolios. Rohde & Schwarz anchors European defense and aerospace calibration demand through accredited laboratories in Germany.
An electrical measuring instrument quantifies voltage, current, resistance, frequency, or power quality with specified accuracy classes, typically employing 24-bit sigma-delta analog-to-digital converters and isolated input stages rated to CAT IV 600V safety standards. These devices enable conformance verification, fault isolation, and process control across power generation, electronics manufacturing, and telecommunications infrastructure. Oscilloscopes and spectrum analyzers lead value pools due to RF bandwidth escalation in 5G and automotive radar development, while smart-connected instruments with IoT telemetry represent the fastest-expanding technology tier. Clamp meters occupy a mature, price-sensitive segment where Asian producers compete on manufacturing scale. Digital technology now dominates unit shipments, though hybrid architectures persist in legacy industrial environments requiring analog trace visualization.
FDA oversight of medical-grade electrical safety analyzers, FCC Part 15 emissions rules for wireless-enabled instruments, and IEC 61010-1 third-edition safety standards collectively shape product design cycles and market access barriers. NHTSA calibration protocols for EV battery test equipment add compliance layers for automotive suppliers. Stakeholders must monitor evolving cybersecurity requirements for networked smart instruments as grid digitization accelerates.
Market Dynamics
Smart grid digitization is compressing instrument replacement cycles as utilities replace analog meters with networked analyzers capable of real-time power quality telemetry and predictive fault detection.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of sulfur hexafluoride in switchgear is forcing utilities to procure gas-free insulation test equipment, expanding demand for partial discharge analyzers and dielectric test sets.
- Automotive radar proliferation:77-81 GHz frequency deployment in advanced driver-assistance systems is accelerating spectrum analyzer procurement by Tier-1 suppliers for electromagnetic compliance verification.
- China eastern manufacturing belt:Concentration of EV battery gigafactories in Jiangsu and Zhejiang provinces is driving localized demand for high-precision DC power analyzers and cell cycling test systems.
Market Restraints
- Precision ADC supply concentration:Foundry capacity for 24-bit sigma-delta converters remains concentrated among Taiwanese semiconductor fabricators, creating input bottlenecks for oscilloscope manufacturers.
- IEC 61010-1 third-edition compliance costs:Reinforced isolation and CAT IV 600V certification requirements are extending product development timelines and raising barrier-to-entry for new entrants.
- Clamp meter commoditization:Price erosion in handheld current measurement devices limits margin expansion despite volume growth in electrical contractor channels.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for electronics manufacturing are attracting test-equipment vendors to establish calibration laboratories in Tamil Nadu and Karnataka.
- IoT-enabled predictive maintenance:Convergence of instrument telemetry with cloud analytics platforms creates recurring revenue streams through subscription-based monitoring services.
- NHTSA EV battery protocols:Mandated thermal runaway testing procedures for electric vehicle certification are expanding demand for specialized high-voltage isolation testers and insulation resistance monitors.
Industry Challenges
- Embedded firmware cybersecurity:Grid-connected smart instruments face escalating penetration testing requirements under evolving NERC CIP standards, complicating product release cycles.
- Calibration technician scarcity:Specialized expertise in RF metrology and primary voltage standards is concentrating among aging workforce cohorts in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Measuring Instrument Market |
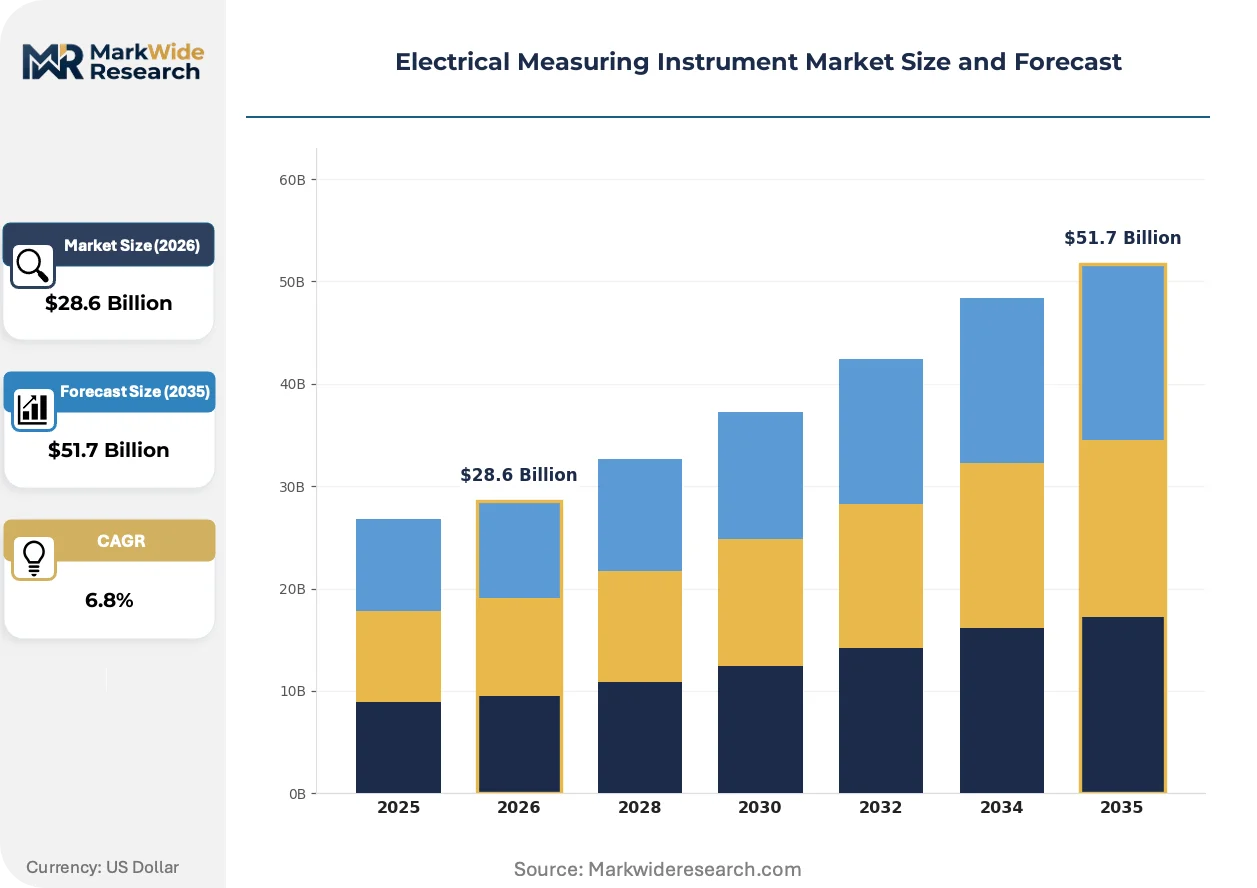
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multimeters, Oscilloscopes, Clamp Meters, Spectrum Analyzers Technology: Analog, Digital, Hybrid, Smart End User: Aerospace, Automotive, Telecommunications, Manufacturing Application: Testing, Calibration, Diagnostics, Monitoring |
| Companies Covered | Yokogawa Electric Corporation, Tektronix, Keysight Technologies, Anritsu Corporation, National Instruments Corporation, Rohde & Schwarz, Hioki E.E. Corporation, Testo SE & Co. KGaA, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Measuring Instrument Market Evolving Landscape
Digital architecture is displacing hybrid analog-digital instrument designs across all price tiers, compressing the remaining installed base of cathode-ray oscilloscopes in legacy industrial environments.
Software-defined instrumentation is converging with FPGA-based real-time processing, enabling single hardware platforms to reconfigure between oscilloscope, spectrum analyzer, and vector network analyzer functions through firmware updates. Semiconductor test houses in South Korea are adopting these flexible architectures to reduce capital equipment footprints. This convergence is compressing traditional category boundaries and forcing vendors to compete on software ecosystem depth rather than dedicated hardware performance alone.
The EU AI Act's risk classification framework for automated decision systems is extending to smart instruments with embedded diagnostic algorithms, requiring conformity assessments for machine-learning-based fault prediction features. Industrial automation suppliers in Germany are restructuring product documentation to satisfy transparency and traceability mandates. High-end power quality analyzer portfolios face the steepest compliance burden as embedded AI for grid anomaly detection triggers higher-risk category obligations.
Buyer consolidation among multinational electronics manufacturers is compressing vendor qualification timelines and demanding consolidated sourcing across multiple instrument categories. Contract manufacturers in Vietnam and Mexico are consolidating test-equipment procurement under global framework agreements with single-source distributors. This concentration is visible most acutely in automotive electronics supply chains, where tier-1 suppliers now mandate unified calibration traceability across all manufacturing locations.
Electrical Measuring Instrument Market Segmentation
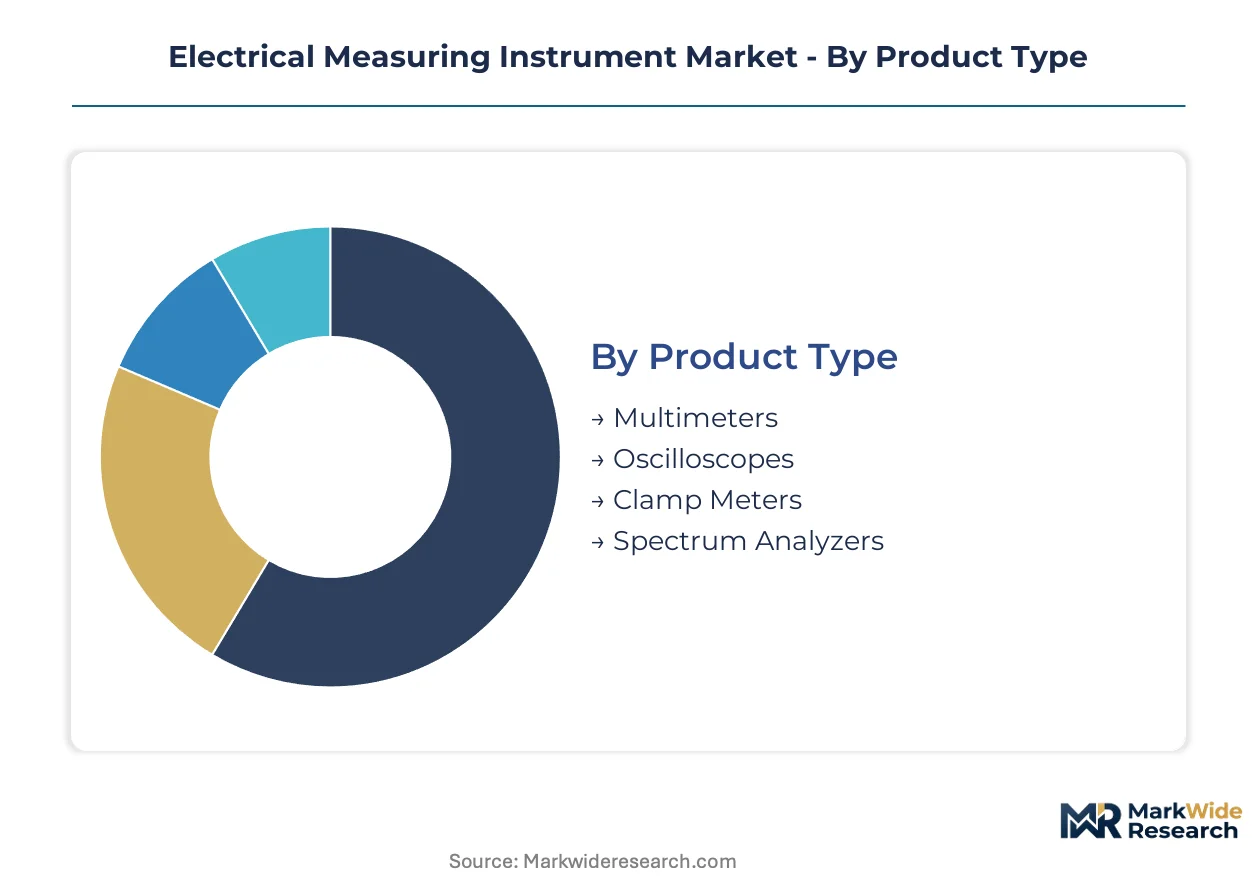
Electrical measuring instrument procurement splits sharply between standardized handheld devices for field technicians and application-engineered systems for laboratory environments. Segment boundaries are blurring as software-defined architectures enable single hardware platforms to serve multiple measurement functions through firmware reconfiguration.
Product Type:
Standardization dominates portable field instruments while oscilloscopes and spectrum analyzers require deep customization for bandwidth and channel density specifications.
- Multimeters:Handheld and benchtop units employ 24-bit sigma-delta ADCs with CAT IV 600V isolation for utility field crews and electronics repair technicians. Demand concentrates in Germany's industrial automation corridor where IEC 61010-1 third-edition certification is mandatory for grid maintenance contracts.
- Oscilloscopes:Real-time and sampling architectures span 100 MHz to 110 GHz bandwidth tiers, with FPGA-based processing enabling protocol decoding and jitter analysis. China's eastern manufacturing belt drives procurement as EV battery gigafactories require precision timing measurements for cell cycling validation.
- Clamp Meters:Current transformers and Hall-effect sensors enable non-invasive AC/DC measurement up to 2000A in confined electrical panels.
- Spectrum Analyzers:Swept-tuned and FFT architectures cover 9 kHz to 110 GHz for EMI compliance and radar signal characterization.
Most installed capacity flows through multimeters. Expansion is steepest in spectrum analyzers.
Technology:
Cost tier separation is pronounced, with analog and hybrid architectures occupying price-sensitive maintenance channels while smart instruments command premium positioning through IoT telemetry subscriptions.
- Analog:Electromechanical movements and cathode-ray tubes persist in legacy industrial environments requiring direct trace visualization without digitization latency. Demand concentrates in mature manufacturing facilities across India's Tamil Nadu industrial corridor where capital replacement cycles extend beyond fifteen years.
- Digital:Microprocessor-based architectures with LCD displays and data logging dominate new procurement across all voltage classes. Automotive electronics suppliers in South Korea drive volume for 4.5-digit benchtop units with USB data export for production line documentation.
- Hybrid:Combined analog-digital designs bridge technician training gaps and legacy compatibility requirements.
- Smart:Networked instruments with cloud connectivity and predictive analytics firmware enable subscription-based monitoring services.
Digital platforms carry the majority of shipment volume. Smart instruments are climbing the fastest as grid digitization accelerates telemetry deployment.
End User:
Application maturity varies dramatically, with aerospace and automotive demanding accredited calibration traceability while telecommunications prioritizes measurement speed over absolute accuracy.
- Aerospace:MIL-STD-461 and DO-160 compliance drives demand for phase-coherent multi-channel spectrum analysis in electromagnetic interference testing. European defense contractors anchor procurement through Rohde & Schwarz accredited laboratories in Germany.
- Automotive:77-81 GHz radar validation and EV battery thermal runaway testing require specialized high-voltage isolation and fast Fourier transform capabilities. NHTSA calibration protocols mandate documented traceability for Tier-1 supplier qualification.
- Telecommunications:5G NR and millimeter-wave base station deployment accelerates vector signal analyzer procurement for modulation quality verification.
- Manufacturing:Process control and quality assurance applications span the full instrument portfolio from handheld verification to automated test systems.
Aerospace maintains the most stringent certification requirements. Automotive is expanding most quickly as electrification multiplies test points per vehicle platform.
Application:
Margin structure inverts between high-volume testing workflows and specialized calibration services where labor scarcity creates pricing power.
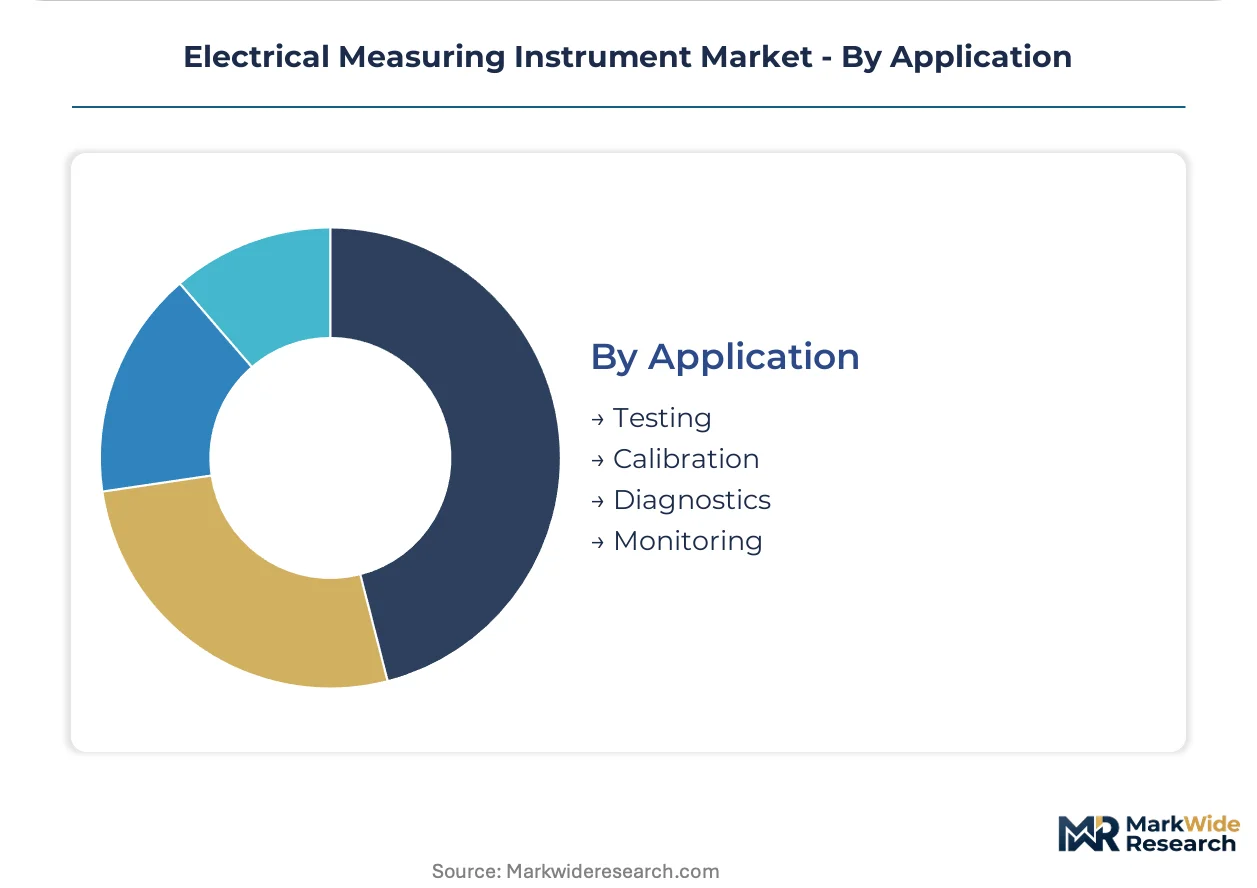
- Testing:Production line verification and R&D characterization consume the majority of instrument operating hours. Semiconductor fabrication facilities in South Korea deploy automated probe stations with integrated parametric analyzers for wafer-level device qualification.
- Calibration:Primary and secondary standards laboratories maintain traceability chains to national metrology institutes. Aging workforce demographics in Germany and Japan constrain capacity expansion despite escalating demand from smart grid deployments.
- Diagnostics:Fault isolation and repair verification in field service applications prioritize portability and rapid measurement acquisition.
- Monitoring:Continuous power quality and equipment health surveillance enables predictive maintenance in critical infrastructure.
Testing absorbs the largest share of instrument utilization. Monitoring is gaining share fastest as utilities deploy networked analyzers for real-time grid telemetry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation corridor demands precision instruments with IEC 61010 certification, while China's eastern manufacturing belt absorbs high-volume test equipment for EV battery production. Japan maintains calibration expertise concentration, and the United States anchors aerospace and defense instrumentation demand. India's electronics manufacturing incentives are redrawing procurement geography.
United States
NHTSA protocols for EV battery thermal runaway testing drive specialized high-voltage isolation tester procurement. The FAA and FCC maintain stringent electromagnetic compliance standards for aerospace and telecommunications equipment. California's Silicon Valley semiconductor test houses deploy automated parametric analyzers for wafer-level device qualification.
Germany
EU F-Gas Regulation phase-down of sulfur hexafluoride expands demand for gas-free insulation test equipment and partial discharge analyzers. The country's national metrology institute anchors European calibration traceability chains. Bavaria's industrial automation corridor concentrates precision multimeter procurement for grid maintenance contracts.
China
MIIT dual carbon goals accelerate smart grid analyzer deployment for real-time power quality telemetry. GB standards and SAMR certification requirements shape import compliance for foreign instrument vendors. Jiangsu and Zhejiang provinces host EV battery gigafactories driving localized DC power analyzer demand.
Japan
METI industrial policy supports domestic precision ADC fabrication for oscilloscope and spectrum analyzer production. JIS standards and PMDA oversight apply to medical-grade electrical safety analyzers. Tokyo and Osaka metropolitan areas concentrate aging RF metrology expertise in accredited calibration laboratories.
India
CEA grid modernization mandates and PLI scheme incentives attract test-equipment vendors to establish calibration infrastructure. BIS certification requirements tighten for imported electrical measuring instruments. Tamil Nadu and Karnataka industrial corridors expand contract manufacturer test-equipment assembly lines.
Electrical Measuring Instrument Market Competitive Landscape
German and Japanese producers anchor the premium calibration tier; Chinese and Southeast Asian fabricators hold volume manufacturing positions. The vendor structure organizes around three strategic archetypes: vertically integrated precision component manufacturers, software-defined instrumentation platforms, and specialized calibration service providers. Consolidation pressures intensify as buyer framework agreements demand unified multi-category sourcing. Technology licensing partnerships and captive ADC supply arrangements represent dominant competitive moves.
Among precision instrumentation specialists, Yokogawa Electric Corporation exemplifies the vertically integrated archetype through in-house ADC fabrication capabilities. Keysight Technologies occupies a position representing software-defined platform convergence across oscilloscope and spectrum analyzer functions. Rohde & Schwarz anchors European defense and aerospace calibration demand through accredited laboratory infrastructure in Germany.
| Leading Market Players |
|---|
| Yokogawa Electric Corporation |
| Tektronix |
| Keysight Technologies |
| Anritsu Corporation |
| National Instruments Corporation |
| Rohde & Schwarz |
| Hioki E.E. Corporation |
| Testo SE & Co. KGaA |
| Fluke Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between IEC 61010-1 third-edition compliant instruments and uncertified commodity units manifests in both pricing power and supply chain sourcing strategies across the electrical measuring instrument landscape. Premium-tier vendors command margin protection through captive ADC fabrication and accredited laboratory infrastructure, while commodity producers compete on scale economics concentrated in Southeast Asian assembly corridors.
Pricing Analysis
Distributor margin layers in the electrical measuring instrument channel typically absorb 15-25 points between factory gate and end-user invoice, with direct-to-OEM framework agreements compressing this spread for high-volume automotive electronics suppliers. Three-tier pricing structure across premium, standard, and economy levels separates CAT IV 600V certified units from commercial-grade handheld devices and unbranded clamp meters. Pricing pressure stems from Hall-effect sensor commoditization in current measurement devices, eroding margins despite volume expansion in electrical contractor channels. Field service technicians exhibit highest price sensitivity, while aerospace and defense procurement prioritizes calibration traceability over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke fulfillment patterns for precision instrumentation, with Southeast Asian nodes handling high-volume handheld device logistics. Manufacturing concentration centers on Taiwan for 24-bit sigma-delta ADC foundry output, Japan for precision assembly of oscilloscope front-ends, and China for clamp meter and multimeter final integration. Raw material dependencies include rare-earth magnets for Hall-effect sensors, high-purity copper for precision resistors, and specialized ceramics for isolated input stages. Single-source vulnerability in Taiwanese semiconductor fabrication creates input bottlenecks for oscilloscope manufacturers. Distribution runs through authorized distributor networks for premium tiers and direct e-commerce platforms for economy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrical measuring instrument market functions as a geographic-arbitrage play where calibration labor scarcity in Germany and Japan supports premium pricing, while Southeast Asian manufacturing scale enables cost-competitive field instrument production.
For Market Incumbents: Extend firmware subscription ecosystems to capture recurring revenue from smart grid telemetry deployments, countering margin compression in hardware-only transactions. Deepen backward integration into precision ADC supply through foundry partnerships or captive wafer capacity, mitigating Taiwanese concentration risk. Fortify accredited laboratory networks in Bavaria and Tokyo to defend against emerging calibration service competitors in India. For New Entrants and Emerging Players: E-commerce direct channels offer the lowest barrier to entry for standardized handheld multimeters and clamp meters, bypassing entrenched distributor relationships. White-space concentration sits in NHTSA-compliant EV battery test equipment for North American automotive suppliers, where certification requirements have slowed incumbent response. Target Tamil Nadu and Karnataka industrial corridors with localized calibration services, exploiting PLI scheme infrastructure incentives and CEA grid modernization procurement windows. For Investors and Strategic Acquirers: Consolidation pressure builds where buyer framework agreements demand unified multi-category sourcing across oscilloscope, spectrum analyzer, and power quality analyzer portfolios. Long-term viability favors vendors with software-defined architectures capable of firmware-reconfiguration across measurement functions. Acquisition target archetype: mid-tier calibration service providers with accredited laboratory infrastructure in aging-workforce geographies. Watch for NERC CIP cybersecurity compliance costs as inflection indicator for smart instrument vendor profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Instrument Platform | FPGA-based reconfiguration between oscilloscope and spectrum analyzer functions reduces capital equipment footprint for semiconductor test houses in South Korea. |
| Calibration Laboratory Expansion | Accredited facilities in Tamil Nadu and Karnataka capture PLI scheme-driven demand from contract manufacturers serving automotive electronics supply chains. |
| IoT Telemetry Subscription Service | Cloud-connected power quality analyzers enable recurring revenue streams from utility predictive maintenance contracts under CEA grid modernization mandates. |
| ADC Foundry Partnership | Captive supply arrangements for 24-bit sigma-delta converters mitigate Taiwanese fabrication concentration risk for oscilloscope bandwidth escalation requirements. |
| NHTSA Compliance Certification | Documented traceability for high-voltage isolation testers qualifies vendors for Tier-1 supplier procurement under mandated EV battery thermal runaway protocols. |
Research Methodology
Multiple input streams — executive interviews with test-equipment vendor product managers, procurement directors at Tier-1 automotive electronics suppliers, and calibration laboratory technical leads — were reconciled against secondary validation from IEC standards documentation, MIIT dual carbon policy filings, and NHTSA EV battery protocol releases. Bottom-up unit shipment estimates by product category and geography were cross-checked against top-down value projections derived from distributor channel revenue disclosures and OEM framework agreement values.
Historical shipment trajectories were cross-referenced against expert panel assessments of smart grid deployment timelines and automotive radar frequency allocation schedules across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user industry, and application function, with additional granularity on certification grade and channel structure. CAGRs were derived from slope-consistency checks against utility capital expenditure cycles and electronics manufacturing capacity expansion announcements. Industry-specific forecast inputs encompassed 5G base station deployment schedules and EV battery gigafactory commissioning timelines.
Semiconductor foundry capacity constraints, regulatory certification timeline extensions, and cybersecurity standard evolution are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Smart Heater Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
United States Electric Insulator Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Fiberglass Electrical Enclosure Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Global Busbar Trunking Market
Electrical Equipment
Porcelain Insulators Market
Electrical Equipment
Medium Voltage Circuit Breakers Market
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Industrial Plugs and Sockets Market