
 China Integrated Circuit (IC) Market | 2026-2036
China Integrated Circuit (IC) Market Size, Share, and Industry Trends Forecast 2026-2036
China Integrated Circuit (IC) Market Insights
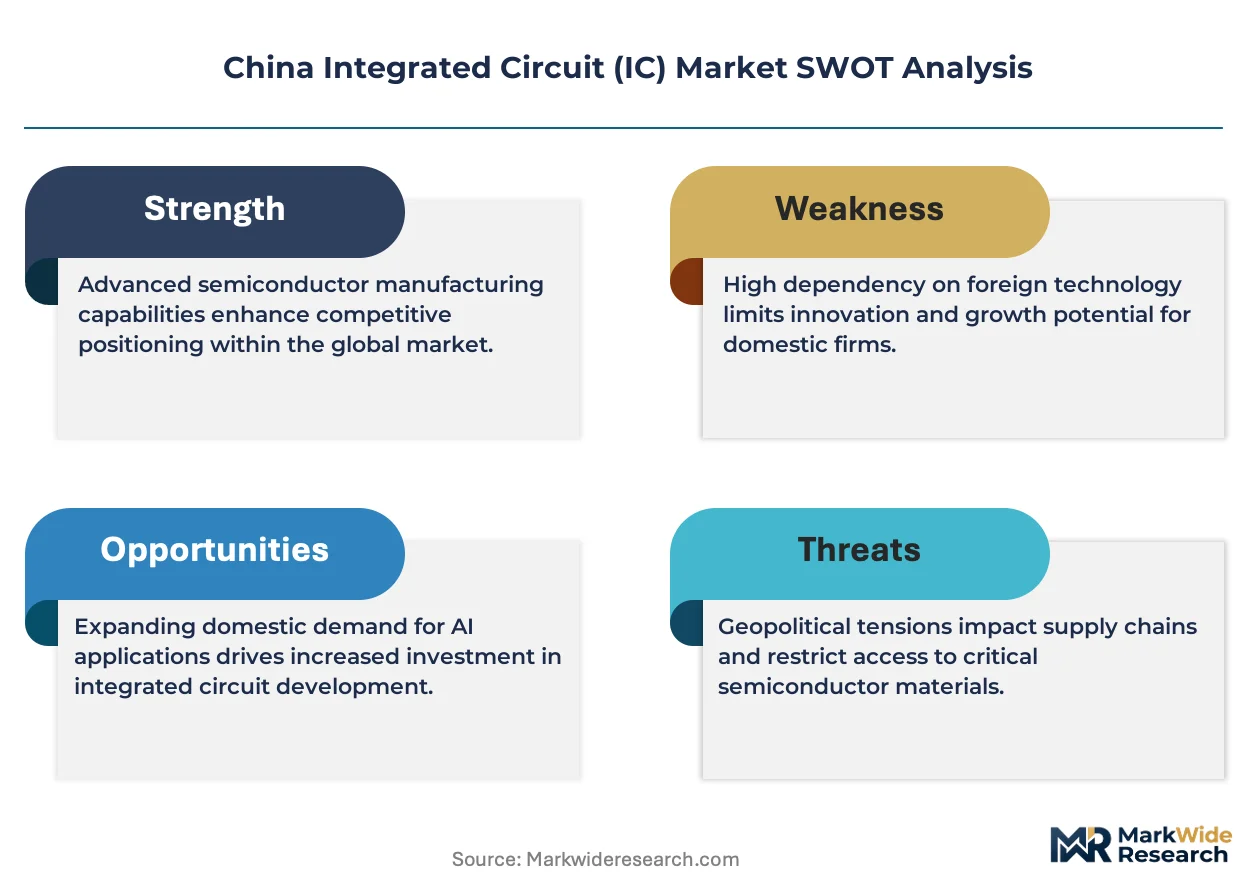
Buyer concentration across China's automotive and telecommunications sectors is rebalancing as domestic EV makers and 5G infrastructure deployers diversify supplier bases beyond traditional import dependence. Semiconductor Manufacturing International Corporation leverages mature-node capacity to anchor industrial and automotive contract flows. HiSilicon sustains in-house design capabilities despite foundry access constraints. Yangtze Memory Technologies specializes in NAND flash production, occupying a critical position in storage semiconductor localization.
Integrated circuits are miniaturized electronic assemblies fabricated on semiconductor substrates, typically silicon, through photolithography, etching, and deposition processes to create interconnected transistors, resistors, and capacitors that perform computational, memory, or signal processing functions. These devices serve as the foundational processing and control elements across virtually all modern electronic systems. Digital IC categories dominate volume consumption in consumer-facing applications, while analog and power management IC segments capture differentiated margin pools in automotive and industrial end uses where voltage regulation and signal fidelity requirements intensify. CMOS technology leads fabrication adoption, though GaN processes are gaining traction in power electronics for electric vehicle inverters and fast-charging infrastructure.
MIIT sets domestic content ratio targets and funds advanced packaging research through national semiconductor programs, while SAMR enforces antitrust and quality standards that shape market entry for foreign-designed chips. GB standards administered by the Standardization Administration of China define electromagnetic compatibility and reliability benchmarks for IC deployment in critical infrastructure. Stakeholders must monitor how export control alignments between China's regulator stack and counterpart agencies in supplier nations reshape equipment access and process technology licensing timelines.
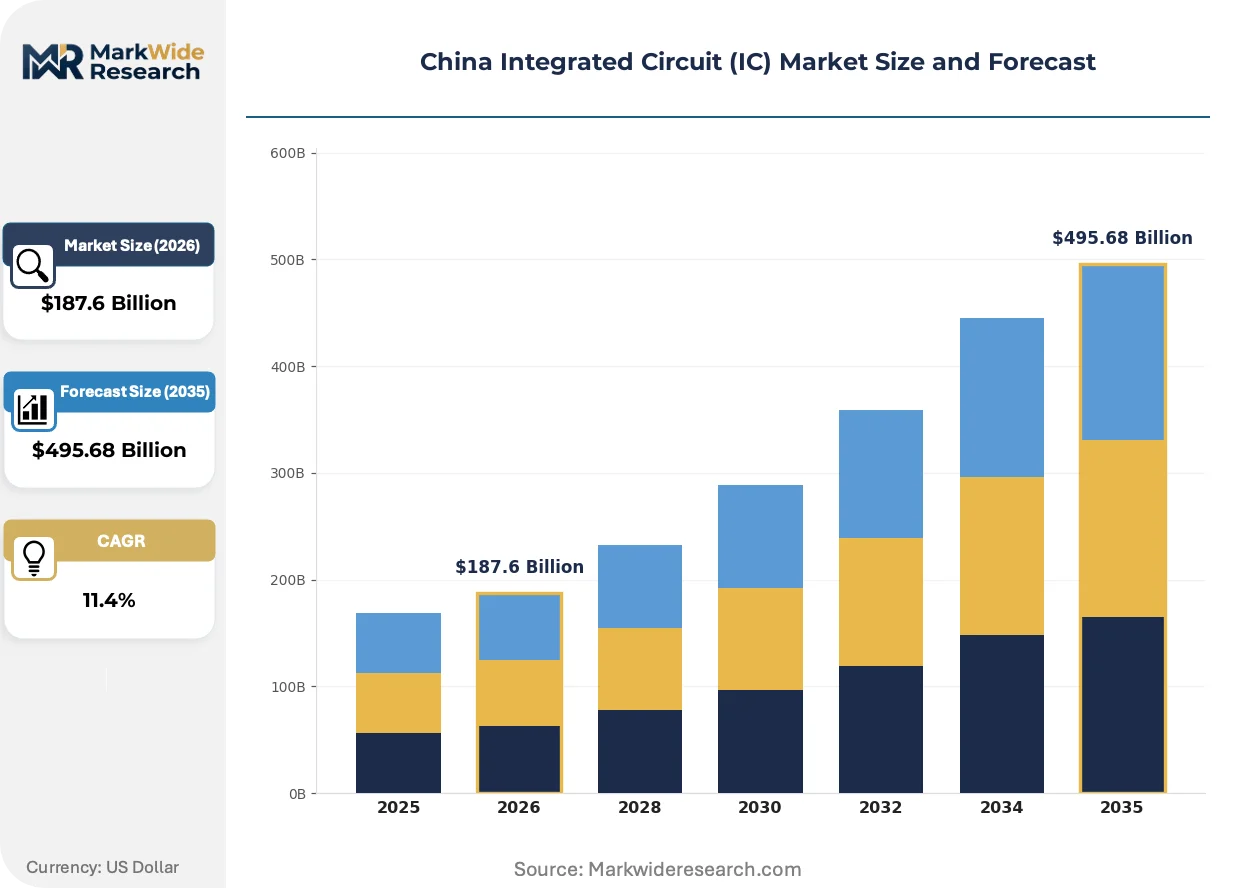
Market Dynamics
MIIT localization mandates and SAMR quality certification requirements are redirecting semiconductor procurement toward domestic foundries, compressing traditional import channels while elevating Yangtze River Delta manufacturing clusters.
Growth Catalysts
- Automotive electronics procurement:Domestic EV manufacturers are expanding chip sourcing for power management and battery control systems, creating sustained demand for mature-node fabrication capacity.
- MIIT domestic content targets:National semiconductor programs mandate minimum localization ratios for critical infrastructure deployments, accelerating foundry partnerships with state-backed design houses.
- GaN process adoption:Gallium nitride fabrication is penetrating electric vehicle inverters and fast-charging stations, opening new process technology licensing pathways for power electronics specialists.
Market Restraints
- Equipment access constraints:Export control alignments between supplier nations and China's regulator stack are restricting lithography tool availability, extending advanced node development timelines.
- Wafer substrate cost volatility:Silicon carbide and sapphire substrate prices fluctuate with raw material supply from concentrated mining geographies, compressing margin pools for power device manufacturers.
- Foundry capacity concentration:Mature-node production concentrates in Shanghai and surrounding Jiangsu province, creating geographic vulnerability to localized disruptions or energy rationing events.
Strategic Opportunities
- Zhejiang packaging expansion:Advanced packaging research funded through national programs is establishing new substrate and interconnect capacity outside traditional Shanghai-Jiangsu concentration zones.
- Industrial automation integration:Smart manufacturing mandates in heavy industry are generating demand for edge computing chips with extended temperature specifications, a segment with limited domestic competition.
- Dual carbon policy alignment:MEE emissions standards and MIIT energy efficiency benchmarks are favoring domestic chip designs optimized for low-power industrial controllers and renewable energy systems.
Industry Challenges
- Photolithography engineering talent scarcity:Domestic universities produce insufficient process engineers with hands-on experience in sub-28nm patterning techniques, forcing reliance on expatriate specialists.
- GB standard certification timelines:Electromagnetic compatibility testing for critical infrastructure deployment requires 12-18 month validation cycles, delaying revenue recognition for new product introductions.
- Legacy system integration friction:Industrial controllers using foreign-designed chips require costly redesign cycles to accommodate domestic alternatives with different pin configurations and thermal profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Integrated Circuit (IC) Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog IC, Digital IC, Mixed Signal IC, Power Management IC End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Technology: CMOS, BiCMOS, GaN, SiGe Application: Smartphones, Tablets, Wearables, IoT Devices |
| Companies Covered | Semiconductor Manufacturing International Corporation (SMIC), HiSilicon (Huawei Technologies), Yangtze Memory Technologies (YMTC), UNISOC, Hua Hong Semiconductor, ChangXin Memory Technologies (CXMT), Will Semiconductor, Naura Technology Group, GigaDevice Semiconductor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Integrated Circuit (IC) Market Trends and Innovations
Process technology evolution and procurement model restructuring are compressing traditional supply hierarchies while elevating domestic design-to-fabrication integration capabilities.
Chiplets are modular semiconductor dies that interconnect via advanced packaging to function as unified processors. Domestic automotive Tier 1 suppliers are adopting chiplet architectures for domain controller designs at accelerating pace. This modular approach is converging with domestic advanced packaging capacity expansion to reduce dependence on monolithic foreign-sourced processors.
GB standards administered by the Standardization Administration of China now mandate electromagnetic compatibility benchmarks for IC deployment in critical infrastructure. These certification requirements are extending validation timelines and elevating testing facility utilization rates. Automotive and telecommunications segments are responding by embedding compliance engineering earlier in product development cycles.
Direct foundry contracting is displacing traditional distribution channels for high-volume automotive and telecommunications buyers. Tier 1 EV manufacturers and 5G infrastructure deployers are establishing dedicated capacity allocation agreements with domestic foundries. This channel restructuring is most visible in the Yangtze River Delta cluster where proximity enables just-in-time wafer starts and reduced inventory carrying costs.
China Integrated Circuit (IC) Market Segmentation
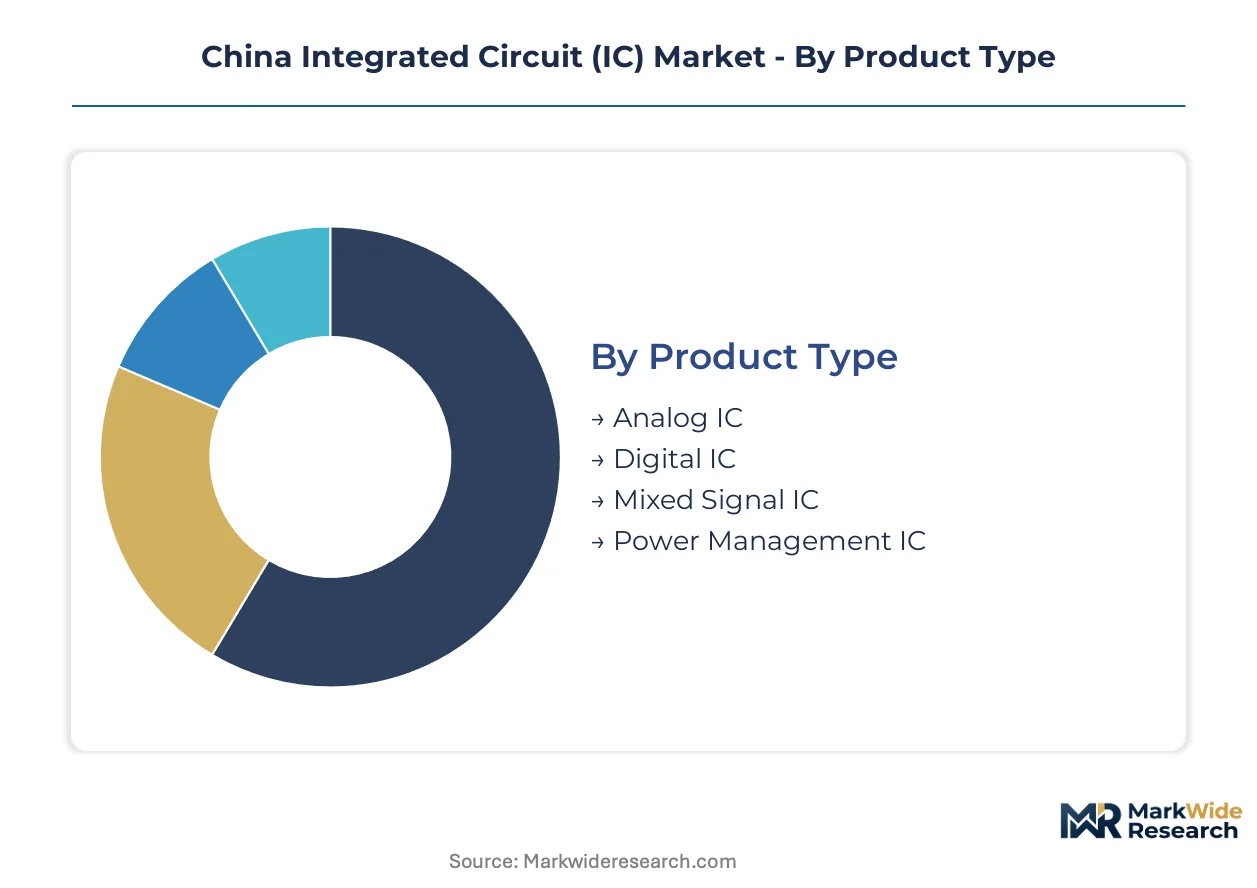
China's IC market exhibits pronounced segmentation asymmetry between high-volume consumer applications and premium automotive-grade specifications. Domestic foundry capacity allocation and MIIT localization mandates are reshaping which segments capture priority investment.
Product Type:
Volume concentration favors commodity digital devices, while premium margin pools sit with specialized power and analog categories requiring extended temperature certification.
- Digital IC:Binary logic processors fabricated on CMOS nodes from 28nm to mature 90nm+ geometries. Consumer electronics procurement in the Yangtze River Delta absorbs the majority of wafer starts, though automotive domain controllers are redirecting some capacity toward AEC-Q100 qualified flows.
- Power Management IC:Voltage regulators, battery management units, and DC-DC converters operating across wide input ranges. Domestic EV manufacturers in Shanghai and Shenzhen are expanding dedicated sourcing for battery control subsystems, tightening foundry allocation timelines.
- Analog IC:Signal conditioning and conversion devices with continuous voltage operation. Industrial automation deployers favor these for sensor interface circuits.
- Mixed Signal IC:Combined analog-digital architectures for data conversion and RF front-ends. Telecommunications infrastructure builds consume significant volumes.
Mature deployment sits with Digital IC. Newer deployment is concentrated in Power Management IC.
End User:
Customer procurement patterns diverge sharply between price-sensitive consumer OEMs and automotive buyers demanding multi-year supply guarantees.
- Automotive:ADAS processors, battery management systems, and domain controllers requiring ISO 26262 functional safety certification. Jiangsu province foundries are prioritizing these contracts under MIIT localization directives, though AEC-Q100 validation cycles extend delivery timelines.
- Consumer Electronics:Mobile handsets, PCs, and home appliances driving the highest absolute wafer volume. Zhejiang and Guangdong assembly plants pull mature-node digital and mixed-signal devices at scale.
- Telecommunications:5G baseband processors and RF transceivers for infrastructure deployment. State-backed carriers mandate domestic content ratios.
- Industrial Equipment:Programmable logic controllers and motor drives with extended temperature specifications. Edge computing mandates in heavy industry are accelerating uptake.
Procurement scale concentrates in Consumer Electronics. Fastest margin expansion is appearing in Automotive.
Technology:
Process node selection tracks application power requirements, with wide-bandgap materials gaining share in high-voltage switching applications.
- CMOS:Dominant planar and FinFET fabrication for digital logic and low-power analog. Shanghai-based foundries anchor global supply for 28nm and above nodes.
- GaN:Gallium nitride epitaxy for 650V+ power switching. EV inverter and fast-charging station manufacturers are expanding sourcing as domestic substrate supply matures.
- BiCMOS:Bipolar-CMOS integration for high-frequency analog and RF circuits. Telecommunications infrastructure deployers favor these for base station signal chains.
- SiGe:Silicon-germanium heterojunction devices for millimeter-wave applications. 5G mmWave module producers represent the primary demand concentration.
Established production centers on CMOS. Capacity expansion is concentrating in GaN.
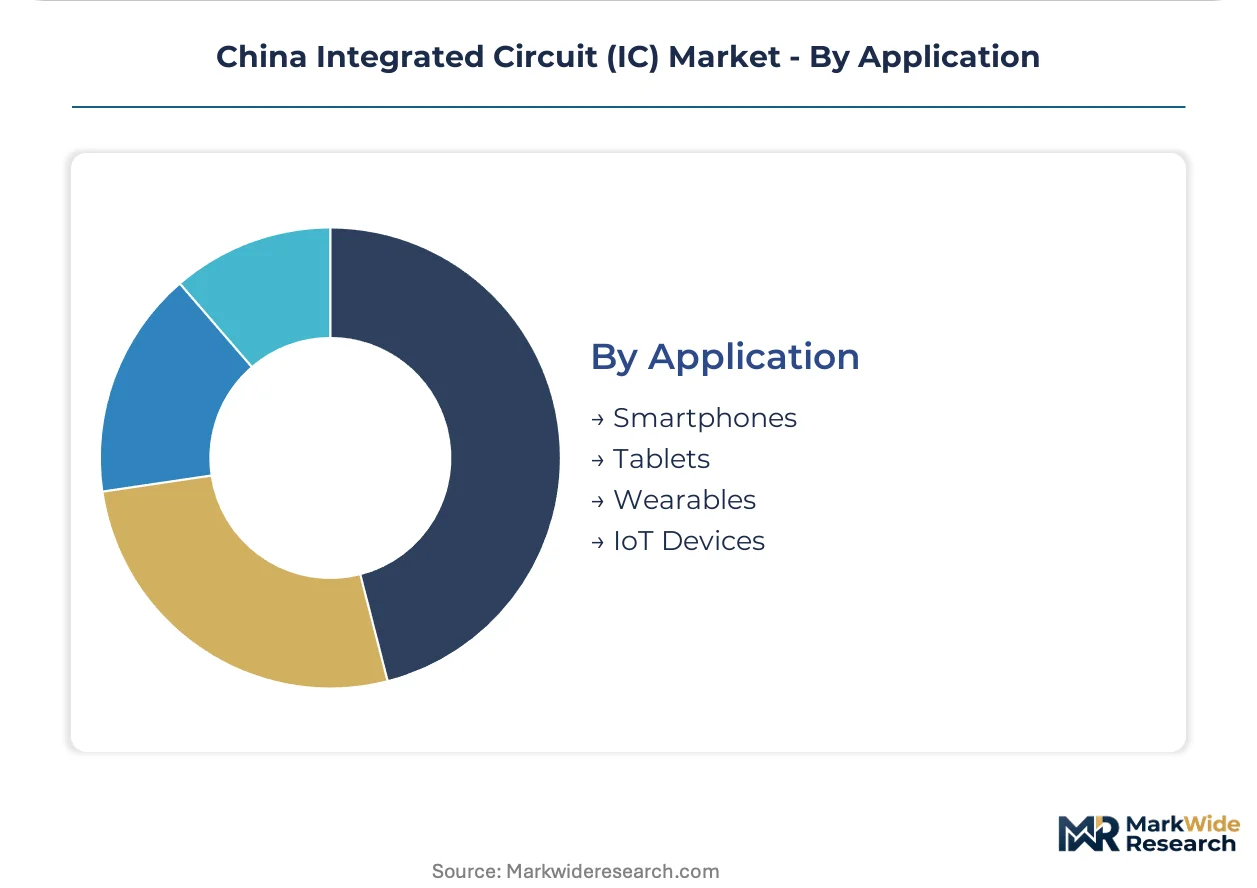
Application:
Device form factors dictate package type and thermal design, with wearables imposing the most stringent size constraints.
- Smartphones:Application processors, modem chipsets, and camera ISPs in BGA and WLCSP packages. Domestic brands are qualifying domestic-designed alternatives for mid-tier models.
- Wearables:Ultra-low-power microcontrollers and sensor hubs in compact fan-out packages. Health monitoring feature proliferation is expanding analog front-end content per device.
- Tablets:Display driver ICs and touch controllers. Education sector procurement cycles create demand volatility.
- IoT Devices:Connectivity modules combining MCU and RF in SiP configurations. Smart home and industrial sensor networks are scaling deployment.
Unit volume concentrates in Smartphones. Design activity is accelerating fastest in Wearables.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for integrated circuits concentrates in manufacturing clusters where automotive electrification and telecommunications infrastructure deployment intersect with domestic content mandates.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang provinces anchor wafer fabrication and advanced packaging capacity. MIIT localization directives prioritize foundry partnerships with state-backed design houses in this corridor. SMIC and Hua Hong Semiconductor operate mature-node facilities across Shanghai and Wuxi, supplying power management ICs to domestic EV manufacturers.
Pearl River Delta
Guangdong province drives consumer electronics assembly and smartphone chipset consumption. Shenzhen-based OEMs pull significant volumes of digital and mixed-signal devices from Yangtze River Delta foundries. SAMR quality certification requirements extend validation timelines for chips deployed in telecommunications infrastructure across the province.
Beijing-Tianjin-Hebei
State-backed semiconductor research programs concentrate design engineering talent in the capital region. HiSilicon maintains in-house architecture capabilities despite foundry access constraints. GB standards for electromagnetic compatibility are administered through Standardization Administration of China offices in Beijing, shaping certification workflows for critical infrastructure deployments.
Sichuan-Chongqing
Western China manufacturing bases are expanding mature-node capacity to reduce geographic concentration risk. Chongqing's automotive electronics cluster consumes power management and battery control ICs for domestic EV production lines. MEE emissions standards and MIIT energy efficiency benchmarks favor low-power chip designs optimized for industrial controllers in this region.
China Integrated Circuit (IC) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue advanced packaging and wide-bandgap material specializations. The vendor base stratifies across state-backed foundry operators, captive design houses, and memory specialists. Three archetypes dominate: scale-driven mature-node fabricators, vertically integrated IDM-style memory producers, and fabless design houses with government-supported access. Competitive moves concentrate on capacity expansion in Zhejiang packaging corridors and strategic partnerships for GaN process technology licensing.
Within the scale-driven tier, Semiconductor Manufacturing International Corporation and Hua Hong Semiconductor occupy positions as anchor foundries for automotive and industrial contract flows. Among memory specialists, Yangtze Memory Technologies exemplifies the vertically integrated archetype for NAND flash localization. HiSilicon represents the captive design house model, sustaining architecture capabilities despite external foundry constraints. These three entities collectively illustrate how government-backed capital allocation and MIIT procurement mandates are restructuring competitive positioning away from traditional import channels.
| Leading Market Players |
|---|
| Semiconductor Manufacturing International Corporation (SMIC) |
| HiSilicon (Huawei Technologies) |
| Yangtze Memory Technologies (YMTC) |
| UNISOC |
| Hua Hong Semiconductor |
| ChangXin Memory Technologies (CXMT) |
| Will Semiconductor |
| Naura Technology Group |
| GigaDevice Semiconductor |
| Others |
Pricing and Supply Chain Analysis
Silicon wafer substrate costs flow from concentrated mining geographies through foundry processing tiers to downstream automotive and consumer electronics buyers, with price stratification tracking certification grade and volume commitment scale. MIIT localization mandates compress import channel premiums while elevating domestic foundry contract pricing power in the Yangtze River Delta cluster.
Pricing Analysis
High-volume consumer digital IC contracts trade at thin margins, while automotive-grade power management and analog devices capture premium spreads through AEC-Q100 and ISO 26262 certification requirements. Price differentiation separates AEC-Q100 qualified flows from commercial-temperature commercial parts, with volume scale and multi-year supply guarantees as secondary tiering factors. Cost compression in mature-node digital segments is intensifying as domestic foundries expand 28nm and above capacity. Consumer electronics OEMs in Guangdong exhibit highest price sensitivity; automotive Tier 1 suppliers accept extended validation timelines for supply security.
Supply Chain Analysis
Dual-sourcing qualification requirements from domestic EV manufacturers and state-backed telecommunications deployers are forcing design houses to validate second-source foundry partnerships beyond traditional single-source dependencies. Wafer fabrication concentrates in Taiwan, South Korea, and mainland China, with advanced lithography equipment anchored in Dutch, Japanese, and American supplier bases. Silicon carbide substrates, high-purity gases, and photoresist chemicals feed from concentrated upstream supply points. Single-source vulnerability in extreme ultraviolet lithography tools creates bottleneck risk for sub-7nm development. Distribution runs through direct foundry contracting for high-volume buyers, with specialized distributors serving fragmented industrial and automotive mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment access constraints and MIIT localization mandates are consolidating competitive position around state-capitalized foundry operators, forcing undercapitalized design houses toward acquisition or exit.
For Market Incumbents: Deploy advanced packaging capacity expansion in Zhejiang corridors to capture chiplet architecture demand from automotive domain controller designers. SMIC and Hua Hong Semiconductor should deepen GaN process engineering partnerships to defend against emerging wide-bandgap specialists. Certification investment in GB standard electromagnetic compliance testing accelerates revenue recognition timelines against foreign competitors facing extended validation cycles. For New Entrants and Emerging Players: Industrial automation deployers with extended temperature specifications represent the most penetrable buyer archetype, as this segment suffers limited domestic competition and MIIT smart manufacturing mandates expand addressable demand. Target Sichuan-Chongqing automotive electronics clusters for power management IC qualification, where geographic diversification incentives from buyers reduce incumbent concentration advantages. Go-to-market through direct foundry contracting with capacity reservation agreements bypasses traditional distribution channel barriers. For Investors and Strategic Acquirers: Foundry access restoration for previously sanctioned design houses is the leading indicator that captive architecture capabilities will re-rate toward full vertical integration value. Five-to-ten year viability favors vertically integrated memory producers with NAND flash localization mandates and advanced packaging specialists with substrate-level interconnect IP. Watch for MIIT procurement directive revisions expanding domestic content ratio minimums as the inflection signal for foundry valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Process Technology Licensing | Domestic substrate supply maturation enables EV inverter and fast-charging station market capture. |
| Advanced Packaging Capacity Expansion | Zhejiang corridor investments reduce monolithic processor dependence through chiplet architecture adoption. |
| Dual-Source Foundry Qualification | Automotive Tier 1 mandates create contract migration opportunities from single-source incumbents. |
| GB Standard Certification Pre-Investment | Early electromagnetic compliance engineering compresses 12-18 month validation cycles for critical infrastructure. |
| Industrial Edge Computing Design Partnerships | Heavy industry automation mandates generate demand for extended-temperature specification devices with limited competition. |
Research Methodology
MIIT policy filings, SAMR certification registries, and foundry capacity announcements formed the secondary backbone, cross-referenced against primary interviews with fabless design house executives, automotive Tier 1 procurement directors, and industrial automation system integrators. SEC 10-K disclosures from equipment suppliers and customs trade data on silicon carbide substrate flows provided additional validation points. Bottom-up wafer start projections and top-down end-use demand estimates were triangulated to reconcile volume figures.
Historical trendline analysis across mature-node utilization rates, domestic content ratio compliance trajectories, and automotive electronics bill-of-materials expansion established baseline growth parameters. The analytical framework modeled product type, end user vertical, process technology node, and geographic manufacturing cluster dimensions across the projection horizon. CAGRs were derived from regression against foundry capacity buildout schedules and EV production ramp assumptions. Forecast inputs incorporated GaN substrate supply elasticity and photolithography equipment delivery timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to export control alignment shifts between supplier nations and China's regulator stack. Forecasts reflect assumptions on localization mandate enforcement intensity and advanced packaging yield maturation. Deviation in lithography tool access permissions or raw material supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Motor Control IC Market
IC (Integrated Circuits)
Bluetooth IC Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Americas Logic IC Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Global Linear Regulator Power Management IC Market
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market