
 Polymer Core Solder Ball Market | 2026-2036
Polymer Core Solder Ball Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Core Solder Ball Market Insights
Specialized metallurgical engineering talent is bifurcating the competitive landscape as advanced packaging complexity outpaces workforce development. Senju Metal Industry Co., Ltd. leverages decades of solder alloy expertise to dominate high-reliability automotive applications. Indium Corporation differentiates through vertically controlled indium sourcing and proprietary flux-core formulations. Nihon Superior Co., Ltd. anchors Asia-Pacific supply chains with lead-free alloy innovations tailored to polymer core architectures.
Polymer core solder balls consist of a thermoset polymer sphere encapsulated by conductive solder alloy layers, typically measuring 50–500 micrometers in diameter, engineered to absorb thermal expansion mismatch between silicon dies and organic substrates in flip-chip interconnections. Lead-free formulations command expanding share as OEMs and contract manufacturers phase out tin-lead compositions under environmental mandates. High-temperature variants retain margin concentration in aerospace and automotive under-hood segments where thermal resilience overrides cost sensitivity. Microelectronics applications absorb the dominant procurement volumes as chiplet-based architectures multiply interconnect counts per package.
RoHS restrictions in Europe, EPA hazardous substance guidelines in the United States, and China's GB standards collectively constrain permissible lead content while accelerating qualification of alternative alloy systems. REACH substance-of-very-high-concern listings further complicate flux chemistry selections for European electronics assemblers. Stakeholders must monitor evolving MEE enforcement in China and ECHA candidate list expansions that could disqualify incumbent polymer resin chemistries mid-cycle.
Market Dynamics
Chiplet-based packaging architectures are multiplying interconnect counts per device, forcing solder ball specifications toward tighter diameter tolerances and enhanced thermal cycling endurance. This structural shift concentrates procurement leverage among advanced packaging foundries in Taiwan, South Korea, and Japan.
Growth Catalysts
- EU RoHS Directive:Lead-free mandate compliance is accelerating qualification of alternative alloy systems across European electronics assemblers, expanding addressable market for polymer core formulations.
- High-performance computing:AI accelerator and data center processor demand is pulling advanced flip-chip interconnection volumes at Taiwan Semiconductor Manufacturing and Samsung Foundry.
- Thermal cycling resilience:Automotive under-hood electronics specifications now require solder joints surviving 1,000+ thermal cycles between -40°C and 150°C.
Market Restraints
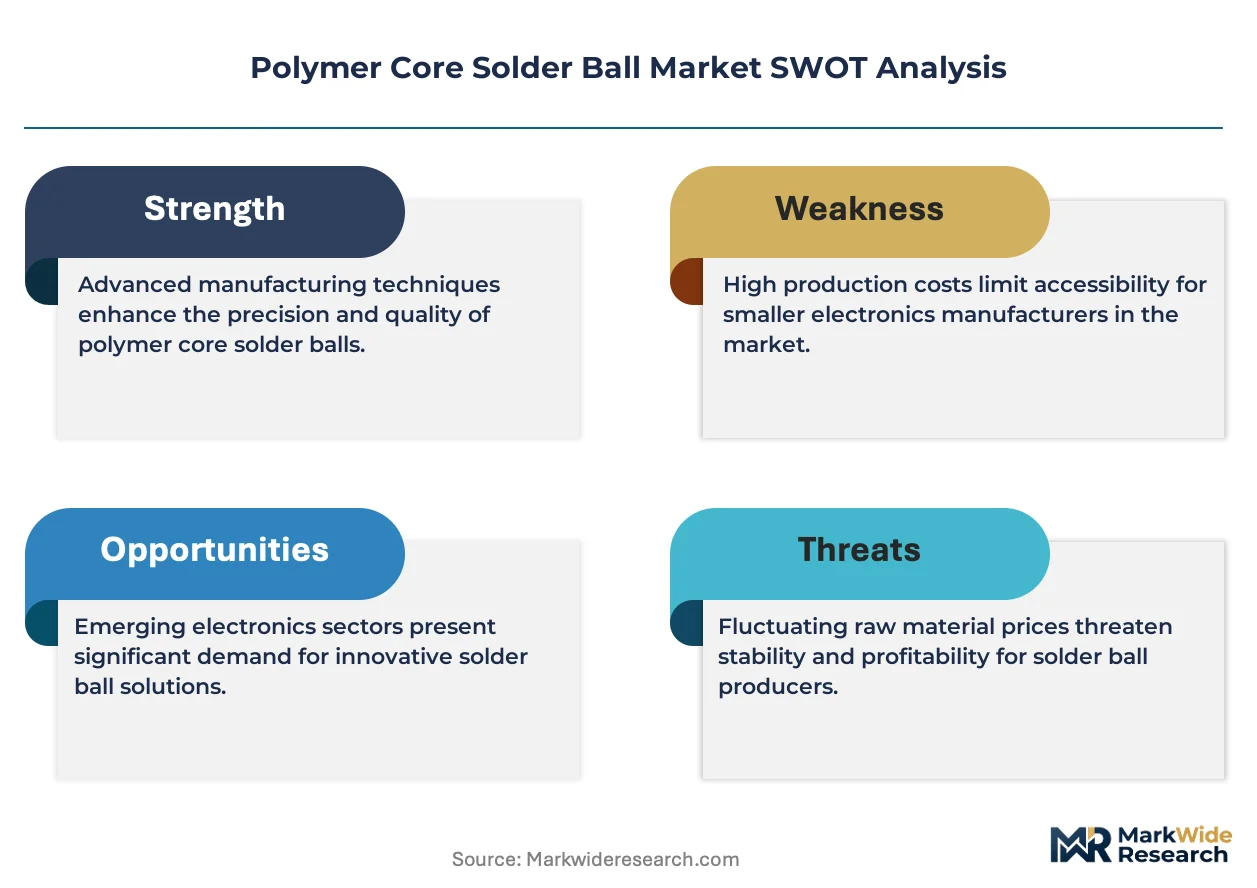
- Indium supply concentration:Over 50% of refined indium originates from Chinese smelters, exposing alloy cost volatility to export quota fluctuations.
- Polymer resin chemistry constraints:REACH substance-of-very-high-concern listings threaten disqualification of incumbent thermoset formulations mid-product lifecycle.
- Technical limitation in ultra-fine pitch:Below 40-micrometer ball diameters, polymer core sphericity tolerances degrade, capping penetration in next-generation 2.5D/3D stacking.
Strategic Opportunities
- India semiconductor packaging:PLI scheme incentives for OSAT investments create first-mover positioning for polymer core qualification at emerging Gujarat and Tamil Nadu facilities.
- Space-qualified interconnects:Satellite constellation deployments are opening radiation-hardened solder ball specifications with 10-year operational reliability requirements.
- Flux-core convergence:Integration of no-clean flux chemistries directly into polymer core architectures eliminates separate flux deposition steps.
Industry Challenges
- Metallurgical engineering scarcity:Workforce pipelines for solder alloy formulation and thermal-mechanical modeling lag behind advanced packaging complexity expansion.
- Multi-jurisdictional certification timelines:Simultaneous qualification under AEC-Q100 automotive, MIL-STD-883 military, and JEDEC standards extends product launch cycles 18-24 months.
- Legacy tin-lead infrastructure:Contract manufacturers maintaining dual alloy systems face contamination control and changeover efficiency penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Core Solder Ball Market |
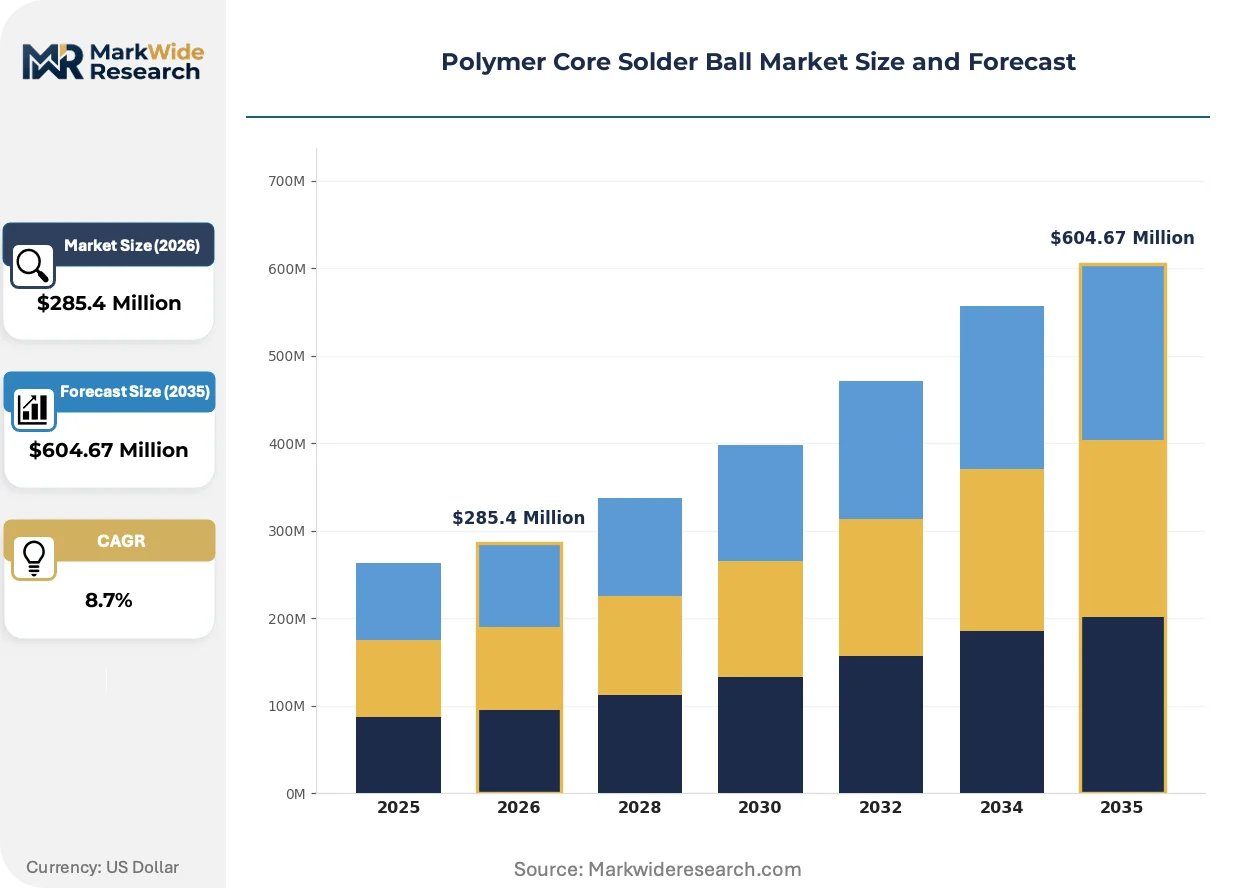
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Temperature, Low-Temperature, Lead-Free, Flux Coated Application: Microelectronics, Automotive, Consumer Electronics, Industrial Equipment End User: OEMs, Aftermarket Providers, Contract Manufacturers, Electronics Assemblers Material: Metallic Alloys, Polymer Composites, Adhesives, Ceramics |
| Companies Covered | AMTECH, Inc., Nihon Superior Co., Ltd., Senju Metal Industry Co., Ltd., Mitsubishi Materials, Nippon Micrometal Corporation, Indium Corporation, Alpha Assembly Solutions, Sekisui Chemical, YINCAE Advanced Materials, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Core Solder Ball Market Trends and Innovations
Material science breakthroughs and regulatory chemistry constraints are converging to redefine polymer core specifications. Three developments are compressing traditional product lifecycles and reshaping supplier qualification protocols.
Copper-core polymer hybrid architectures are miniaturizing interconnect pitches below 50 micrometers while maintaining collapse control during reflow. Apple and NVIDIA procurement specifications now prioritize these structures for M-series and H100 packaging. The technology is miniaturizing die-to-substrate spacing without sacrificing thermal expansion absorption, enabling denser memory stacking in high-bandwidth modules.
REACH candidate list expansions by ECHA are forcing reformulation of epoxy-based polymer cores before 2027 sunset dates. German automotive suppliers through KBA certification pathways are rejecting legacy resin systems containing bisphenol derivatives. European OSATs are responding with accelerated biobased thermoset qualifications using lignin-derived hardeners.
Consolidated procurement through foundry-direct models is displacing traditional distributor channels for high-volume polymer core volumes. Taiwan Semiconductor Manufacturing and Intel Foundry Services now negotiate alloy specifications directly with Senju Metal and Indium Corporation, bypassing regional electronics distributors. This channel compression is most visible in Hsinchu and Taichung packaging corridors where captive supplier programs lock in 3-year alloy supply agreements.
Polymer Core Solder Ball Market Segmentation
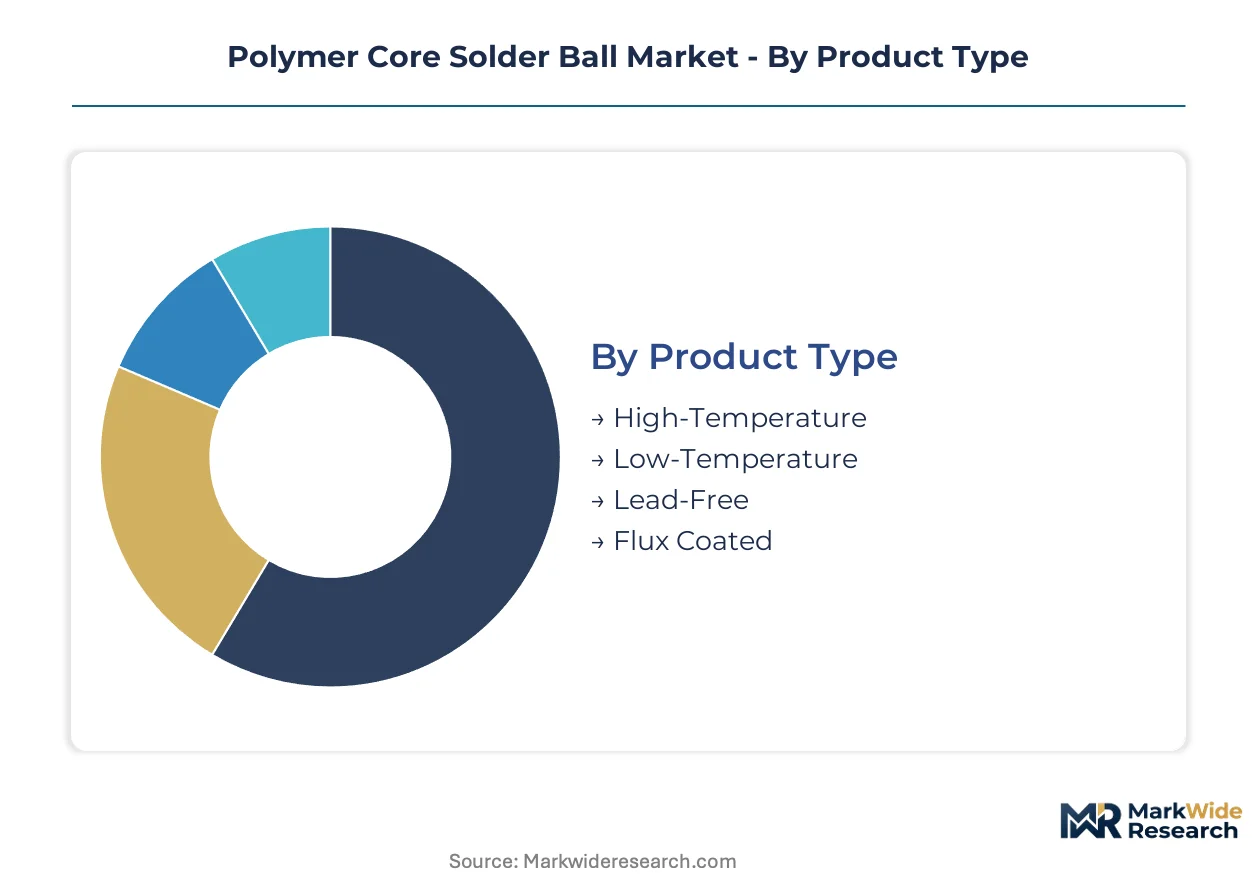
Polymer core solder ball specifications diverge sharply across thermal performance tiers and regulatory compliance zones, creating distinct procurement clusters that resist standardization. Material composition and end-use reliability requirements partition the addressable market into non-substitutable segments with specialized qualification protocols.
Product Type:
Low-temperature formulations face the strongest substitution pressure from copper-core hybrid architectures as miniaturization demands exceed polymer sphericity tolerances below 40 micrometers.
- Lead-Free:Tin-silver-copper (SAC) alloy systems encapsulating thermoset polymer cores dominate procurement volumes under EU RoHS Directive and China's GB standards. Taiwan Semiconductor Manufacturing and Samsung Foundry specifications now mandate lead-free formulations for all new flip-chip designs, compressing tin-lead conversion timelines at OSATs.
- High-Temperature:Gold-tin and bismuth-bearing compositions engineered for automotive under-hood segments survive 1,000+ thermal cycles between -40°C and 150°C. German KBA certification pathways prioritize these formulations for powertrain control modules where thermal resilience overrides cost sensitivity.
- Low-Temperature:Indium-rich alloys and bismuth-tin systems enable processing on temperature-sensitive organic substrates. Indium supply concentration from Chinese smelters exposes alloy cost volatility to export quota fluctuations.
- Flux Coated:No-clean flux chemistries integrated directly into polymer core architectures eliminate separate deposition steps. Apple and NVIDIA procurement specifications prioritize flux-core convergence for M-series and H100 packaging.
Lead-Free anchors the volume base while Flux Coated gains share at the steepest rate.
Application:
Chiplet-based packaging architectures are multiplying interconnect counts per device, concentrating procurement leverage among advanced packaging foundries.
- Microelectronics:AI accelerator and data center processor demand pulls advanced flip-chip interconnection volumes at Taiwan Semiconductor Manufacturing and Intel Foundry Services. High-bandwidth memory stacking in H100 modules requires 50-500 micrometer diameter spheres with tight collapse control.
- Automotive:Under-hood electronics specifications from German OEMs through KBA pathways require solder joints surviving extended thermal cycling. Electrification trends multiply sensor and control module counts per vehicle.
- Consumer Electronics:Smartphone and wearable device miniaturization drives demand for sub-100 micrometer polymer core solutions. REACH candidate list expansions force reformulation of epoxy-based polymer cores before sunset dates.
- Industrial Equipment:Factory automation and power electronics applications prioritize long-term joint reliability over pitch miniaturization. Extended operational lifecycles favor conservative alloy selections with established field performance.
Microelectronics commands the dominant procurement position while Automotive expands most quickly on electrification pull-through.
End User:
Consolidated procurement through foundry-direct models is displacing traditional distributor channels for high-volume segments.
- OEMs:Apple, NVIDIA, and AMD negotiate alloy specifications directly with Senju Metal and Indium Corporation, bypassing regional distributors. Captive supplier programs lock in multi-year agreements at Hsinchu and Taichung packaging corridors.
- Contract Manufacturers:Foxconn and Pegatron maintain dual alloy systems for legacy tin-lead and lead-free production lines. Contamination control and changeover efficiency penalties compress margin structures.
- Electronics Assemblers:European OSATs accelerate biobased thermoset qualifications using lignin-derived hardeners under REACH pressure. ECHA substance-of-very-high-concern listings complicate flux chemistry selections.
- Aftermarket Providers:Repair and refurbishment operations favor tin-lead formulations for compatibility with legacy board assemblies. RoHS exemptions for spare parts maintain residual demand.
OEMs concentrate procurement leverage while Contract Manufacturers face the steepest margin compression.
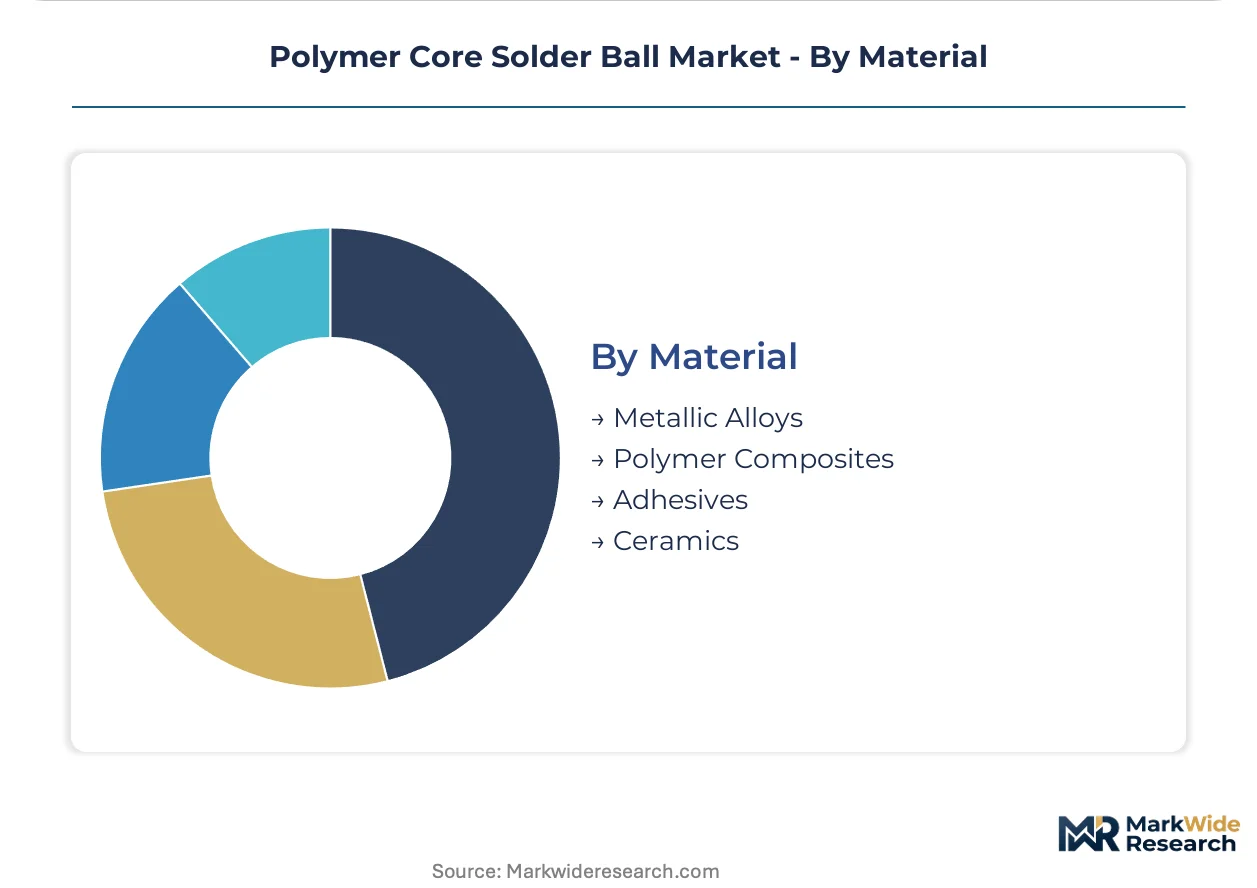
Material:
Polymer resin chemistry constraints from EMEA regulatory expansion are forcing qualification of alternative thermoset systems.
- Metallic Alloys:SAC305, SnAgCu, and specialized gold-tin compositions form the conductive encapsulation layers. Indium Corporation's vertically controlled indium sourcing anchors supply security for high-reliability segments.
- Polymer Composites:Thermoset epoxy and emerging biobased formulations provide thermal expansion absorption between silicon dies and organic substrates. German automotive suppliers reject legacy resin systems containing bisphenol derivatives.
- Adhesives:Underfill and edge-bond materials complement solder ball interconnections in advanced packaging stacks. Capillary flow characteristics determine process compatibility.
- Ceramics:Alumina and zirconia-filled polymer hybrids enhance thermal conductivity for power device applications. Cost premiums limit penetration to aerospace and military specifications.
Metallic Alloys anchor the value chain while Polymer Composites face the steepest reformulation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer core solder ball consumption patterns diverge sharply across geographies. Taiwan and South Korea absorb the dominant procurement volumes for advanced packaging foundries, while Germany and Japan concentrate automotive reliability specifications. The United States splits demand between defense-aerospace heritage programs and emerging domestic packaging investments.
Taiwan
Advanced packaging foundries at Taiwan Semiconductor Manufacturing and United Microelectronics drive the steepest procurement volumes for flip-chip interconnects. The National Development Council's semiconductor initiative accelerates local OSAT capacity expansion. Hsinchu and Taichung packaging corridors host captive supplier programs that lock in multi-year alloy supply agreements.
South Korea
Samsung Foundry and SK Hynix pull polymer core volumes for high-bandwidth memory stacking in AI accelerators. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt program channels investment into packaging infrastructure. Pyeongtaek and Yongin semiconductor clusters concentrate next-generation interconnect qualification activity.
Japan
Automotive under-hood electronics specifications from Denso and Renesas prioritize thermal cycling resilience over cost sensitivity. METI's Green Transformation policy accelerates lead-free alloy qualification timelines. Kyoto-Osaka industrial corridors anchor metallurgical engineering expertise for high-reliability formulations.
Germany
Bosch and Continental procurement specifications mandate solder joints surviving 1,000+ thermal cycles for powertrain control modules. KBA certification pathways reject legacy resin systems containing bisphenol derivatives. Bavaria and Baden-Württemberg automotive supplier clusters drive reformulation toward biobased thermoset hardeners.
United States
Intel Foundry Services and AMD negotiate alloy specifications directly with material suppliers for domestic advanced packaging. EPA hazardous substance guidelines constrain permissible lead content in electronics assemblies. Arizona and Oregon semiconductor manufacturing zones attract polymer core qualification for reshoring supply chains.
Polymer Core Solder Ball Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in polymer core solder ball supply. Consolidated procurement through foundry-direct models compresses margins for regional distributors while rewarding alloy formulation expertise. Three archetypes dominate: vertically integrated metal refiners with captive indium sourcing, Japanese metallurgical houses with decades of automotive qualification heritage, and Korean-Japanese chemical conglomerates with polymer resin integration. Capacity expansion and strategic partnerships represent the dominant competitive moves as packaging complexity outpaces workforce development.
Among Japanese metallurgical specialists, Senju Metal Industry Co., Ltd. and Nihon Superior Co., Ltd. occupy positions anchored by automotive reliability qualifications and lead-free alloy innovations. Indium Corporation represents the vertically integrated archetype through controlled sourcing of critical raw materials. These three entities exemplify how technical specialization and supply security determine positioning in advanced packaging procurement channels.
| Leading Market Players |
|---|
| AMTECH, Inc. |
| Nihon Superior Co., Ltd. |
| Senju Metal Industry Co., Ltd. |
| Mitsubishi Materials |
| Nippon Micrometal Corporation |
| Indium Corporation |
| Alpha Assembly Solutions |
| Sekisui Chemical |
| YINCAE Advanced Materials, LLC |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Taiwan Semiconductor Manufacturing and Senju Metal Industry lock in three-year alloy supply commitments while insulating procurement teams from indium spot market volatility driven by Chinese export quota fluctuations. These contract structures simultaneously secure supply access for high-volume flip-chip packaging and provide price visibility across the thermal cycling qualification cycle.
Pricing Analysis
Contract-based long-term offtake dominates procurement for advanced packaging foundries, with spot transactions limited to aftermarket repair operations and small-batch industrial applications. Price differentiation separates AEC-Q100 automotive certified alloys from standard commercial grades, while volume scale and captive indium sourcing anchor tier positioning. Cost compression in low-temperature indium-rich formulations is intensifying because Chinese smelter export quotas expose alloy costs to political leverage. Contract manufacturers maintaining dual tin-lead and lead-free systems exhibit the highest price sensitivity, whereas German automotive suppliers through KBA pathways demonstrate minimal elasticity as thermal resilience overrides cost considerations.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication and advanced packaging capacity, while Japan concentrates metallurgical engineering expertise for high-reliability alloy formulations. Raw material flows draw from Chinese indium smelters, German epoxy resin suppliers, and Japanese thermoset hardener producers. Single-source vulnerability concentrates in refined indium supply, where over half of global output originates from Chinese state-influenced producers. Distribution runs through foundry-direct channels that displace regional electronics distributors for high-volume polymer core procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as chiplet-based packaging architectures multiply interconnect specifications beyond standardized product portfolios, creating niche qualification pathways for specialized alloy formulations.
For Market Incumbents: Shield market position by deepening backward integration into indium sourcing to offset Chinese export quota volatility, and accelerate biobased thermoset qualifications ahead of ECHA candidate list expansions. The REACH substance-of-very-high-concern threat to legacy epoxy formulations demands preemptive resin chemistry investment. Captive supplier programs at Hsinchu and Taichung packaging corridors provide channel control leverage against distributor displacement. For New Entrants and Emerging Players: Lead with flux-core convergence technology as the primary differentiation vector, targeting India's Gujarat and Tamil Nadu OSAT facilities where PLI scheme incentives create first-mover positioning without entrenched incumbent relationships. Space-qualified interconnect specifications for satellite constellation deployments represent the most penetrable white-space segment, with radiation-hardened requirements favoring specialized entrants over commodity producers. Direct qualification partnerships with emerging packaging foundries bypass traditional distributor gatekeeping. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated alloy formulators with captive indium sourcing and established automotive qualification heritage, as these archetypes command durable pricing power through supply security and regulatory compliance capabilities. Long-term viability over the coming decade rests on REACH chemistry adaptation and workforce pipeline development for metallurgical engineering scarcity. The signal to watch is ECHA candidate list expansion velocity, which could trigger accelerated incumbent write-downs and create distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indium Sourcing | Indium Corporation's captive supply model insulates alloy cost volatility from Chinese export quota fluctuations. |
| Biobased Thermoset Qualification | Lignin-derived hardener formulations address German KBA rejection of bisphenol-containing legacy resin systems. |
| Flux-Core Convergence Development | Apple and NVIDIA procurement specifications prioritize no-clean flux integration for M-series and H100 packaging. |
| India OSAT Partnership Formation | PLI scheme incentives at Gujarat and Tamil Nadu facilities create first-mover positioning without incumbent entrenchment. |
| Space-Qualified Interconnect Certification | Satellite constellation deployments demand radiation-hardened solder balls with decade-long operational reliability. |
Research Methodology
Initial hypotheses were tested against primary input from advanced packaging procurement directors, metallurgical engineering leads at alloy formulators, automotive electronics qualification managers, and semiconductor foundry supply chain executives, and refined through secondary validation against SEC 10-K filings, Taiwan Stock Exchange semiconductor sector disclosures, ECHA substance registry updates, and customs trade flow databases. Bottom-up alloy consumption estimates triangulated with top-down packaging equipment deployment data.
Variance decomposition across the projection horizon isolates volume drivers by product type, application reliability tier, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from segmented growth rate modeling incorporating flip-chip interconnect density trends, thermal cycling specification evolution, and lead-free conversion timelines. Indium price volatility scenarios and REACH chemistry sunset dates inform sensitivity boundaries.
The analysis sits within stated boundaries; outcomes outside sustained advanced packaging capital expenditure cycles or accelerated ECHA candidate list expansion would require recalibration. Forecasts reflect documented assumptions regarding alloy qualification timelines and foundry capacity ramp schedules. Recalibration cycles align with material shifts in regulatory chemistry constraints and semiconductor manufacturing equipment deployment patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Field Effect Transistor Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Global Bipolar Small Signal Transistor Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
Reachers Market