
 Power and Control Cable Market | 2026-2036
Power and Control Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Power and Control Cable Market Analysis
Software-defined cable monitoring and predictive maintenance subscriptions are restructuring how utilities and industrial buyers procure power and control cable systems over asset life cycles. Prysmian Group leverages its integrated energy cable and telecom portfolio to anchor large-scale interconnection projects across European and North American transmission networks. Southwire Company sustains manufacturing scale advantages in copper and aluminum building wire through vertical control of its rod production facilities. Nexans differentiates through specialized high voltage subsea cable capabilities and digital service layers for grid operators.
Power and control cables are insulated electrical conductors engineered to transmit electrical energy and signal commands across industrial, commercial, and utility infrastructure, typically rated by voltage class from low voltage up through extra-high voltage thresholds exceeding 220 kV with insulation systems comprising cross-linked polyethylene or ethylene propylene rubber compounds. Their primary purpose is to ensure reliable power delivery and operational control in environments where mechanical stress, thermal cycling, and chemical exposure demand engineered protection. Specialty cables command premium positioning due to fire resistance, halogen-free formulations, and extreme temperature performance requirements in nuclear, mining, and mass transit installations. Medium voltage segments are expanding fastest as distribution utilities replace aging grid segments and integrate distributed generation interconnections. Copper conductor material retains structural dominance in high-reliability applications despite aluminum penetration in cost-sensitive overhead and residential deployments.
The U.S. Department of Energy and the Federal Energy Regulatory Commission shape transmission investment timelines through interconnection queue reforms and grid resilience funding mechanisms, while the EU Green Deal and REACH chemical compliance frameworks mandate material traceability and restricted substance thresholds for cable insulation compounds sold into European markets. China's National Energy Administration and GB standards bodies enforce localized testing and certification requirements that condition market access for imported cable systems. Stakeholders must monitor evolving carbon border adjustment mechanisms and domestic content incentives as these regulatory instruments increasingly determine competitive positioning in procurement decisions.
Market Dynamics
Grid interconnection queues are compressing project timelines and forcing cable manufacturers to pre-position inventory near substation clusters before final regulatory approvals clear. This inventory positioning dynamic is restructuring working capital requirements across the supply base.
Growth Catalysts
- EU Green Deal implementation:The F-Gas Regulation and carbon border adjustment mechanisms are mandating low-carbon cable insulation compounds. European utilities are accelerating procurement of compliant medium voltage systems for distribution network upgrades.
- Offshore wind interconnection:Developers in the North Sea and Baltic regions are expanding high voltage subsea cable orders. These projects require specialized three-core extruded insulation systems rated above 66 kV.
- Industrial electrification:Aluminum conductor penetration in commercial building wire is displacing copper in cost-sensitive residential and overhead applications. Chinese and Indian manufacturing clusters are scaling continuous casting and rolling capacity to serve this substitution.
Market Restraints
- Copper price volatility:London Metal Exchange copper pricing swings above 15% annually are compressing margin predictability for conductor-dependent product lines. Hedging costs now represent 3-4% of raw material spend for non-integrated manufacturers.
- REACH compliance complexity:ECHA substance of very high concern listings are forcing reformulation of legacy PVC and halogenated flame retardant compounds. Reformulation cycles extend 18-24 months and require recertification under IEC 60502.
- Submarine cable supply concentration:Installation vessel availability and specialized laying capacity cluster with North European contractors. Queue times for vessel charter now exceed 24 months for deep-water projects.
Strategic Opportunities
- Digital service layer attachment:Distributed acoustic sensing and temperature monitoring systems are automating predictive maintenance for grid operators. Cable manufacturers with embedded fiber capabilities can capture recurring software subscription revenue.
- India transmission buildout:The country's Central Electricity Authority has approved 27 green energy corridors requiring 765 kV and 400 kV overhead and underground systems. Local content requirements under the PLI scheme favor domestic manufacturing partnerships.
- Halogen-free compound substitution:Mass transit and nuclear certification standards in Germany and France are mandating low-smoke zero-halogen insulation. Compound suppliers with pre-certified material libraries can command specification lock-in.
Industry Challenges
- High voltage testing certification backlog:Accredited laboratories for long-duration AC and impulse testing face 6-9 month queue times. This delays new product introductions for 220 kV+ extruded cable systems.
- Compound formulation talent scarcity:Polymer scientists with cross-linked polyethylene and EPR compounding expertise are concentrating with incumbent material suppliers. Cable manufacturers face recruitment competition from battery and automotive sealant sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power and Control Cable Market |
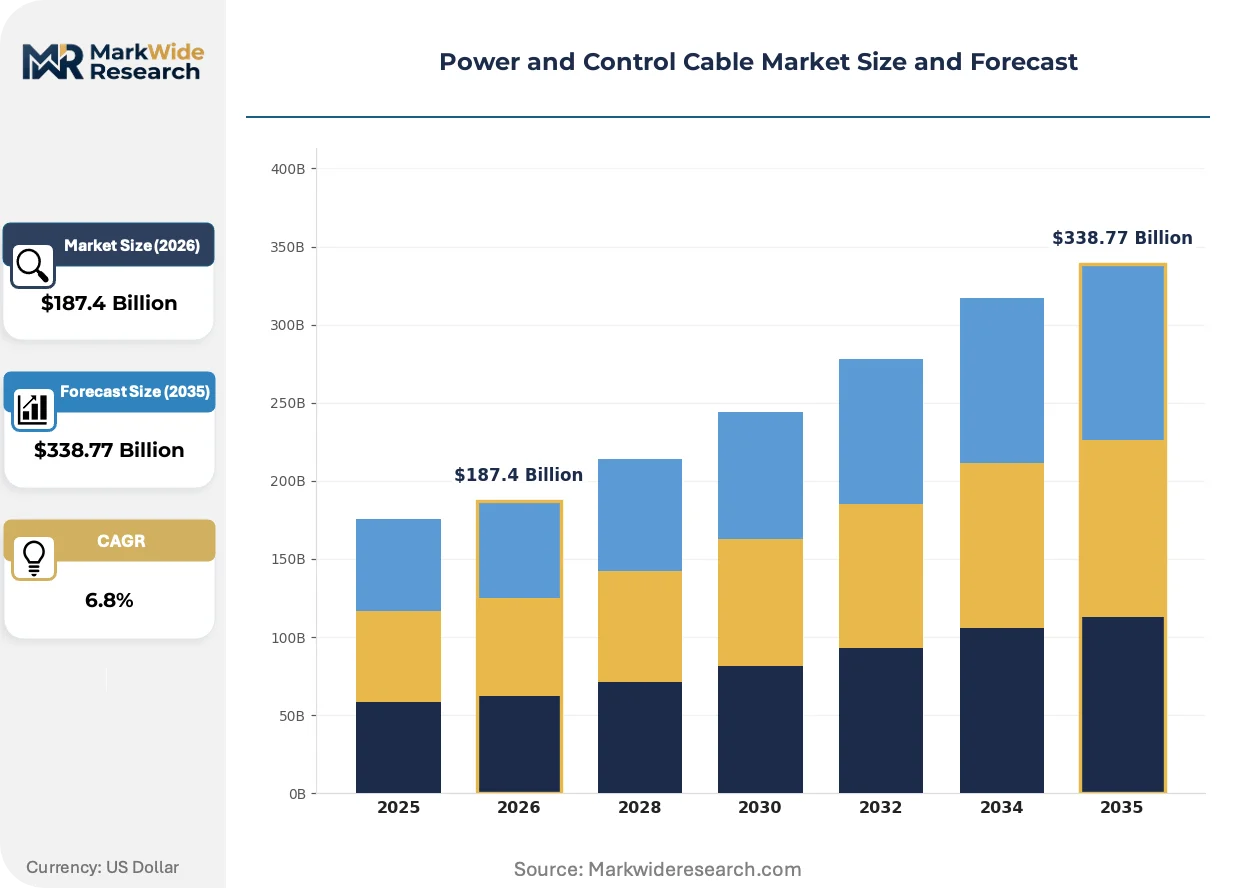
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Specialty Cables Application: Power Distribution, Control Systems, Communication, Renewable Energy End User: Utilities, Industrial, Residential, Commercial Material: Copper, Aluminum, Fiber Optic, PVC |
| Companies Covered | Belden Inc., Southwire Company, Prysmian Group, Fujikura Ltd., LS Cable & System, Nexans, NKT A/S, Polycab, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power and Control Cable Market Emerging Trajectories
Real-time cable condition monitoring is migrating from pilot installations to standard procurement specifications. This instrumentation shift is enabling predictive maintenance business models and reshaping manufacturer-customer relationships toward lifecycle service partnerships.
Artificial intelligence-driven thermal load forecasting is automating dynamic rating calculations for underground transmission circuits. Grid operators in Germany and the Netherlands are deploying these systems to defer capital-intensive reconductoring projects. The technology is compressing traditional static ampacity safety margins by 15-20% while maintaining reliability.
The EU F-Gas Regulation and accompanying delegated acts are phasing down hydrofluorocarbon use in cable manufacturing auxiliary processes. Compound producers are retrofitting extrusion cooling systems with ammonia-based alternatives. Medium voltage product lines with documented fluorine-free process chains are gaining preferential specification status in French and Benelux utility tenders.
Utility procurement departments are unbundling cable supply from installation and commissioning services. This disintermediation is fragmenting vendor relationships and forcing pure-play manufacturers to develop direct field engineering capabilities. The shift is most visible in United States municipal utility segments where cooperative purchasing agreements now separate material and labor line items.
Power and Control Cable Market Segmentation
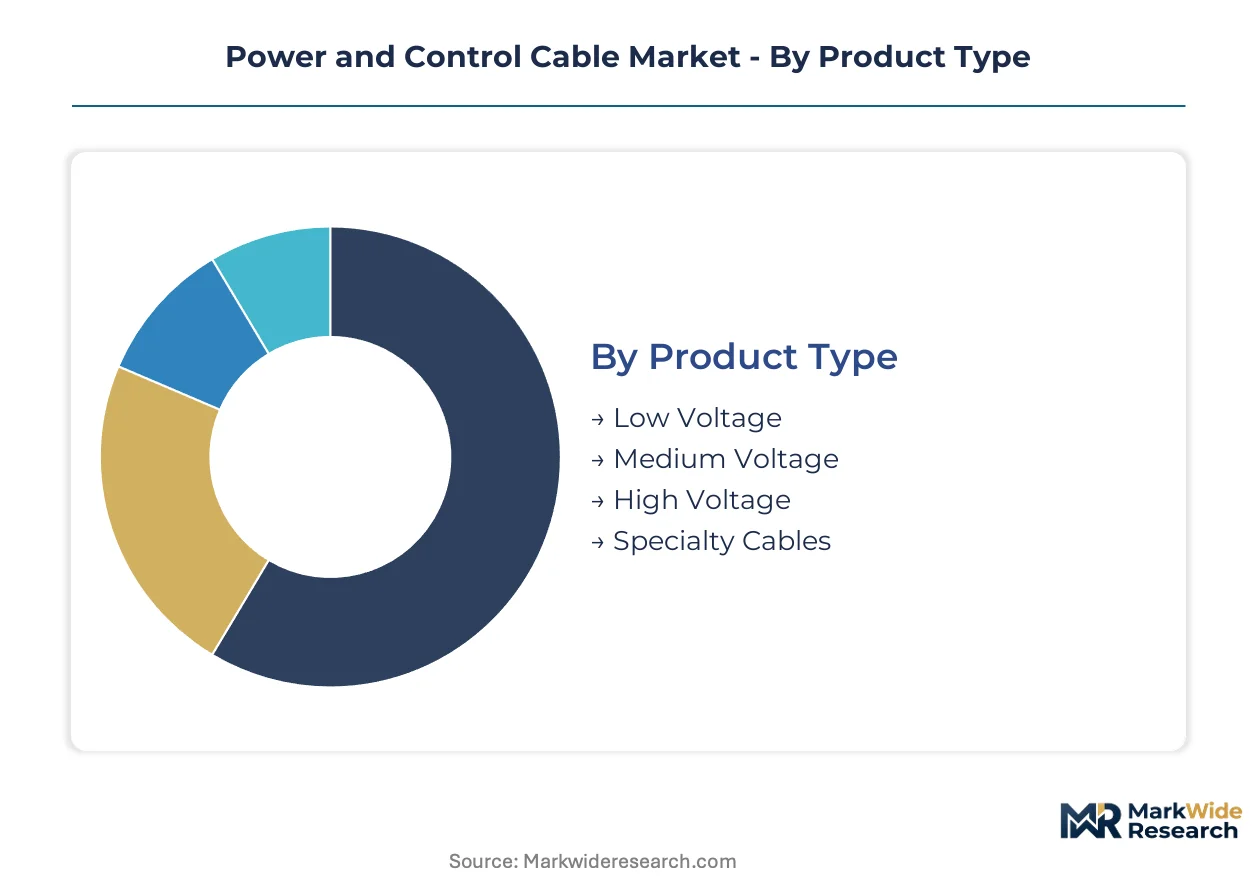
Voltage class and insulation specifications determine procurement workflows, testing protocols, and margin structures across power and control cable manufacturing. Segmentation clarity enables buyers to match conductor materials and shielding systems to specific load profiles and environmental exposures.
Product Type:
Supply concentration clusters around extruded insulation compound formulators with captive compounding facilities in Germany, China, and the United States.
- Low Voltage:Cross-linked polyethylene and PVC-insulated conductors rated below 1 kV serve building wire and appliance cordage applications. Residential electrification programs in India and Brazil are absorbing continuous casting rod output from integrated copper producers.
- Medium Voltage:Three-core or single-core designs with XLPE insulation rated 1 kV to 33 kV connect distribution substations to industrial loads. German utilities are replacing aging paper-insulated cables with dry-cure extruded systems under EU Green Deal procurement mandates.
- High Voltage:Extruded insulation systems rated 66 kV to 220 kV require clean-room manufacturing and long-duration testing accreditation. Subsea interconnection projects in the North Sea and Baltic regions are pre-positioning order queues with specialized manufacturers.
- Specialty Cables:Fire-resistant, halogen-free, and extreme-temperature formulations serve nuclear containment, mining, and mass transit installations. French and German transit authorities are mandating low-smoke zero-halogen specifications for underground tunnel networks.
Low voltage absorbs the bulk of installed capacity; medium voltage is expanding most quickly.
Application:
Cost tier stratification separates premium-specified grid interconnection projects from standardized building wire procurement.
- Power Distribution:Overhead and underground transmission circuits rated through 765 kV deliver bulk power across utility territories. India's Central Electricity Authority has approved green energy corridors requiring 765 kV and 400 kV systems with localized content requirements.
- Control Systems:Multi-conductor shielded cables transmit instrumentation and automation signals in process industries. Petrochemical complexes along the US Gulf Coast are specifying armored control cables with enhanced oil resistance ratings.
- Communication:Hybrid power-fiber designs integrate electrical conductors with optical fiber for smart grid monitoring. German distribution operators are embedding distributed acoustic sensing fibers in new medium voltage installations.
- Renewable Energy:Subsea export cables and solar farm collector systems require UV-resistant and salt-spray-rated jacketing. Offshore wind developers in the North Sea are contracting specialized three-core 66 kV+ extruded systems with 25-year service warranties.
Power distribution commands the largest revenue pool; renewable energy is climbing the fastest.
End User:
Customer type determines specification complexity, with utilities demanding full lifecycle documentation and residential channels prioritizing cost-per-meter metrics.
- Utilities:Transmission and distribution operators specify IEC 60502-compliant systems with factory acceptance testing and installation supervision. US municipal cooperatives are unbundling material procurement from installation services in revised purchasing agreements.
- Industrial:Manufacturing and process facilities require armored, flexible, and chemically resistant cable configurations. Chinese heavy industry clusters are scaling medium voltage procurement for electrification of steel and cement production lines.
- Residential:Building wire in 12 AWG through 4/0 gauges serves single-family and multi-unit construction. Aluminum conductor penetration is displacing copper in cost-sensitive North American residential overhead drops.
- Commercial:Office, retail, and institutional installations specify plenum-rated and halogen-free compounds for code compliance. German commercial construction is mandating enhanced fire performance under updated building safety regulations.
Utilities absorb the bulk of high-value procurement; industrial segments are expanding most quickly.
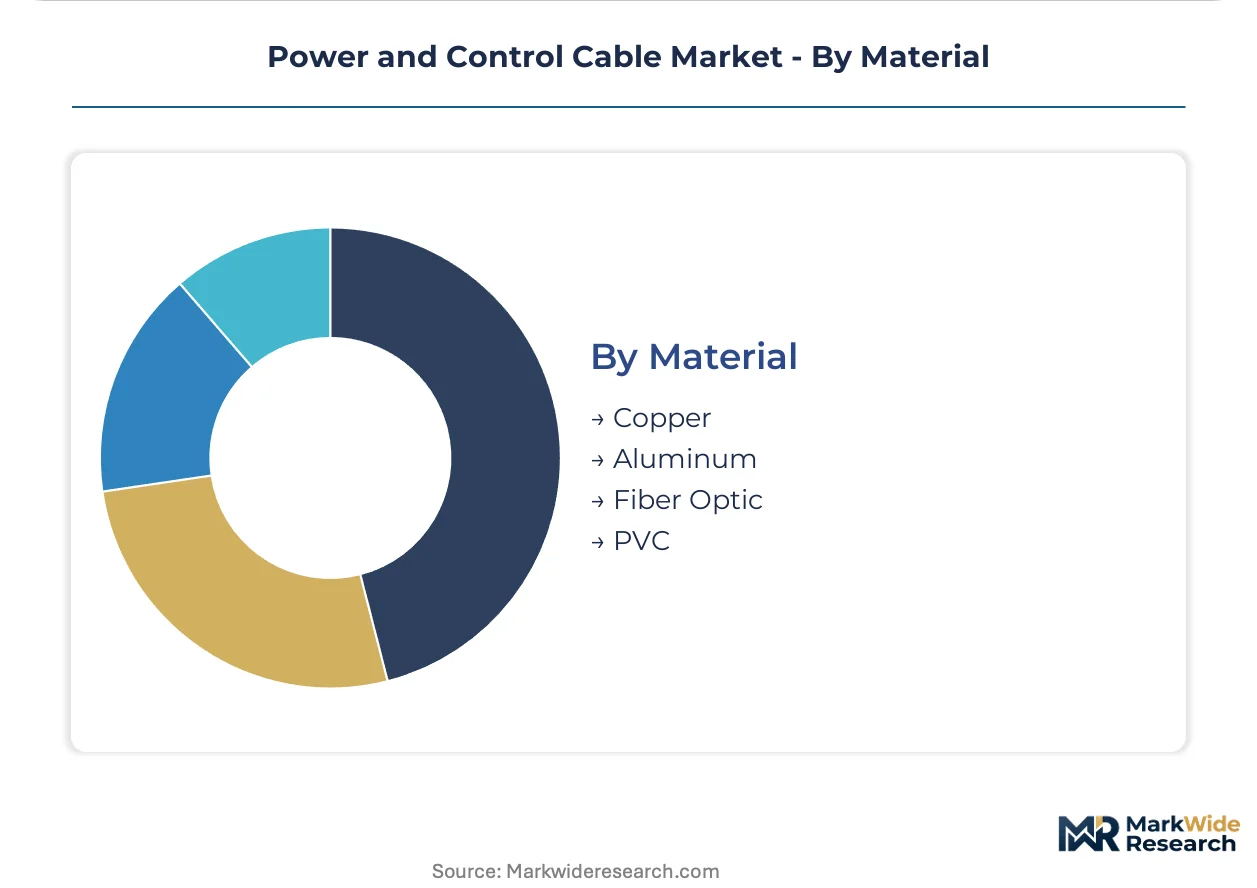
Material:
Volume concentration tilts toward copper rod producers with integrated mining and refining positions, though aluminum is gaining share in weight-sensitive applications.
- Copper:Electrolytic tough pitch and oxygen-free high-conductivity grades deliver maximum ampacity in confined installations. London Metal Exchange price volatility above 15% annually is compressing margin predictability for non-integrated cable manufacturers.
- Aluminum:1350 and 8000 series alloys reduce weight and cost in overhead transmission and large-gauge building wire. Chinese and Indian continuous casting and rolling capacity is scaling to serve aluminum substitution demand.
- Fiber Optic:Single-mode and multimode glass fibers enable distributed temperature and acoustic sensing in smart grid cables. Embedded fiber capabilities allow manufacturers to attach recurring software subscription revenue streams.
- PVC:Polyvinyl chloride compounds provide cost-effective insulation and jacketing for low voltage building wire. ECHA substance of very high concern listings are forcing 18-24 month reformulation cycles for legacy halogenated flame retardant formulations.
Copper retains structural dominance in high-reliability applications; aluminum is gaining share fastest in cost-sensitive deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial corridor cable manufacturers are scaling medium voltage production lines to serve German grid modernization tenders under EU Green Deal procurement mandates.
United States
Texas and California utilities are accelerating transmission buildouts to clear interconnection queues for solar and storage projects. FERC Order 2023 reforms are compressing project approval timelines and forcing cable pre-positioning near substation clusters. Gulf Coast petrochemical complexes in Louisiana and Texas are specifying armored control cables with enhanced oil resistance ratings for process automation upgrades.
Germany
Distribution operators in Bavaria and North Rhine-Westphalia are replacing aging paper-insulated cables with dry-cure XLPE systems. EU F-Gas Regulation compliance is mandating fluorine-free extrusion processes for medium voltage product lines. Berlin-Brandenburg transit authorities are mandating low-smoke zero-halogen specifications for underground tunnel network expansions.
China
Shandong and Jiangsu province cable manufacturers are scaling continuous casting capacity for aluminum conductor substitution in building wire. GB standards bodies are enforcing localized testing and certification requirements that condition market access for imported systems. Yangtze River Delta industrial clusters are absorbing medium voltage procurement for steel and cement production line electrification.
India
Gujarat and Maharashtra manufacturing hubs are expanding domestic capacity under PLI scheme local content requirements. Central Electricity Authority green energy corridors are driving 765 kV and 400 kV overhead and underground system demand. Tamil Nadu renewable energy zones are contracting specialized collector system cables for solar farm interconnections.
Power and Control Cable Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a market that clusters around integrated compound formulators and specialized installation service providers. Supply concentration tilts toward manufacturers with captive polymer compounding facilities and long-duration testing accreditations. Two strategic archetypes dominate: vertically integrated energy-to-telecom conglomerates with project anchoring capabilities, and pure-play cable specialists with deep subsea or high-voltage extrusion expertise. Competitive moves center on pre-positioning inventory near substation clusters before regulatory clearances, and attaching digital monitoring service layers to hardware procurement contracts.
Within the integrated conglomerate tier, Prysmian Group and Nexans occupy positions that span transmission network anchoring through specialized subsea capabilities. Southwire Company exemplifies the scale-driven North American fabricator archetype with vertical control over conductor production. LS Cable & System represents the Asia-Pacific diversified manufacturer positioning across voltage classes and export markets.
| Leading Market Players |
|---|
| Belden Inc. |
| Southwire Company |
| Prysmian Group |
| Fujikura Ltd. |
| LS Cable & System |
| Nexans |
| NKT A/S |
| Polycab |
| Sumitomo Electric Industries |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap compound specialists in Germany and Japan anchor supply discipline through multi-decade customer relationships and captive polymer formulation libraries, translating material scarcity into premium pricing power for halogen-free and fire-resistant cable grades.
Pricing Analysis
Value-based pricing anchored to grid uptime guarantees and 25-year service warranties commands 30-40% premiums over transactional spot procurement in offshore wind interconnection projects. Three-tier pricing structure across premium certified, standard IEC-compliant, and economy-grade building wire segments stratifies buyer access, with German utilities least price-sensitive due to EU Green Deal compliance mandates and Indian residential channels most sensitive to per-meter copper cost fluctuations. Pricing pressure stems from London Metal Exchange copper volatility above 15% annually, compressing margin predictability for non-integrated manufacturers lacking captive rod production.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale transmission procurement, while distributor networks serve fragmented residential and commercial building wire demand across North American and European markets. Geographic supply concentration clusters in Germany for specialty compound formulation, China for continuous casting aluminum capacity, and the United States for integrated copper rod production. Raw material dependencies center on electrolytic copper cathode, cross-linked polyethylene resin, and halogen-free flame retardant additives. Single-source vulnerability in subsea cable installation vessel availability poses structural risk, with North European contractor queues extending beyond 24 months for deep-water projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU F-Gas Regulation and REACH substance restrictions erect barrier-to-entry moats favoring incumbent compound formulators with pre-certified material libraries and established ECHA registration workflows.
For Market Incumbents: Hedge copper price exposure through London Metal Exchange futures positions or backward integration into rod production, mirroring Southwire's vertical control model. Accelerate fluorine-free extrusion process certification under EU delegated acts to lock in French and Benelux utility specification preference. Defend against aluminum substitution threats by embedding fiber optic sensing capabilities that create switching costs for grid operator accounts.
For New Entrants and Emerging Players: The 25-30% price-point gap between premium subsea interconnection cables and standard medium voltage distribution products creates entry space for specialized high-voltage testing laboratories and compound formulation services. Target India's PLI scheme-favored domestic manufacturing partnerships for 765 kV transmission corridor buildouts, where local content requirements disadvantage pure imports. Pursue joint development agreements with state-owned utilities in Gujarat and Maharashtra to bypass established procurement relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European compound specialists with stranded halogenated formulation assets seeking recapitalization for LSZH transition. Long-term viability hinges on 5-10 year electrification capex trajectories in heavy industry and renewable interconnection. Monitor FERC interconnection queue clearance rates as the inflection signal for North American transmission cable demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Production | Captive supply of electrolytic tough pitch rod insulates margin from London Metal Exchange volatility for building wire manufacturers. |
| Fluorine-Free Extrusion Process Certification | EU F-Gas Regulation compliance unlocks preferential specification status in French and Benelux utility tender processes. |
| Embedded Fiber Optic Capability Development | Distributed acoustic sensing integration enables recurring software subscription revenue attachment to hardware procurement contracts. |
| Halogen-Free Compound Library Expansion | Pre-certified low-smoke zero-halogen formulations command specification lock-in for German and French mass transit infrastructure projects. |
| Installation Vessel Charter Partnerships | Long-term vessel access agreements with North European contractors secure project execution capacity for subsea interconnection developers. |
Methodological Framework
Multi-period observation of copper price volatility patterns, interconnection queue clearance rates, and compound formulation certification timelines anchored the trend analysis, supplemented by interviews with utility procurement directors, cable manufacturing plant managers, polymer R&D leads, and EPC contractor project developers. Secondary validation drew from IEC standards documentation, ECHA substance registry filings, FERC interconnection queue databases, and customs trade data for copper rod and cable imports. Bottom-up segment sizing triangulated against top-down macroeconomic electrification forecasts to ensure consistency across voltage class and application dimensions.
Segment-weighting approaches distributed value estimates across voltage class, insulation material, end-user category, and geographic procurement cluster dimensions. CAGRs were derived from regression analysis of historical installation volumes against projected green energy corridor buildouts, industrial electrification programs, and grid modernization capex schedules. Industry-specific forecast inputs included offshore wind lease award timelines, PLI scheme capacity addition announcements, and REACH substance restriction implementation phases.
Inputs from utility procurement databases and compound supplier order backlogs were available through the study window; gaps in real-time vessel charter rate transparency and long-duration testing laboratory queue lengths introduce uncertainty bands around subsea project timing assumptions. Forecasts reflect documented assumptions regarding regulatory implementation schedules and commodity price trajectory stability. Periodic stress-testing of base assumptions against FERC Order 2023 reform implementation pace and EU carbon border adjustment mechanism expansion is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Power Cable Accessories Market
Cables
Downhole Cables Market
Cables
Ethernet Converters Market
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
XLPE Cables Market
Cables
Active Optical Cable Market
Cables
Coaxial Cable Market
Cables
GCC Cable Accessories Market
Cables
SATA Power Cable Market
Cables
Medium Voltage Cables Accessories Market
Cables
Twisted Pair Cable Market
Cables
HVDC Cables Market
Cables
Global Cable Gland Market
Cables
Instrumentation Cables Market
Cables
Submarine Optical Fiber Cables Market
Cables
Cable Material Market