
 Direct Attach Cable Market | 2026-2036
Direct Attach Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Attach Cable Market Analytics
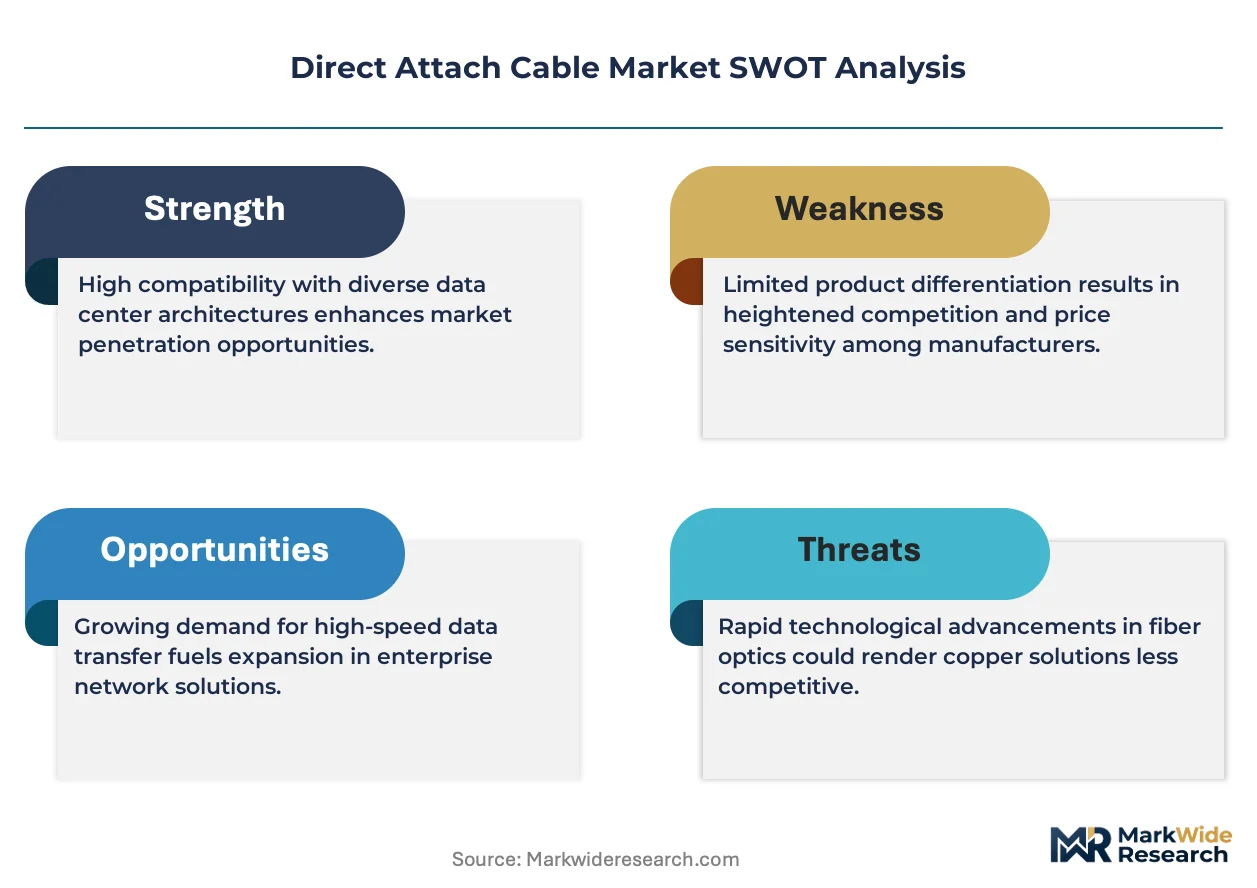
Aftermarket service revenue from cable testing, certification, and field replacement is tilting margin pools away from pure hardware sales toward lifecycle support contracts. Amphenol leverages its vertical integration into connector and cable assembly manufacturing to capture value across the stack. Molex sustains R&D intensity in high-speed copper signaling to defend its position in passive interconnects. TE Connectivity anchors North American supply relationships with hyperscale operators through direct qualification programs.
A direct attach cable is a fixed-length, factory-terminated interconnect assembly that integrates transceiver electronics directly into the cable housing, eliminating separate pluggable modules and supporting data rates from 10 Gbps to 800 Gbps over copper or optical media. Its primary purpose is to reduce power consumption, latency, and cost in short-reach applications within data centers and high-performance computing environments. Passive copper assemblies dominate unit volume in top-of-rack deployments where reach stays under three meters, while active optical cables command premium positioning in spine-layer and distributed computing fabrics requiring longer spans. QSFP-DD and OSFP connector form factors are capturing share from legacy QSFP+ as 400G and 800G port densities become standard in cloud infrastructure.
The Federal Communications Commission and the U.S. Food and Drug Administration govern electromagnetic emissions and laser safety in optical transmitters, while the European Telecommunications Standards Institute and China's Ministry of Industry and Information Technology set electrical and environmental compliance benchmarks for equipment sold into their respective jurisdictions. These frameworks shape product roadmaps by mandating specific test protocols, efficiency thresholds, and documentation requirements before market authorization. Stakeholders must monitor evolving IEEE physical layer standards and regional efficiency mandates to align certification timelines with procurement cycles.
Market Dynamics
The transition from 400G to 800G switching architectures is compressing replacement cycles and forcing interconnect suppliers to synchronize roadmaps with hyperscale procurement calendars. IEEE 802.3ck electrical standards and regional efficiency mandates are simultaneously tightening signal integrity thresholds and power consumption ceilings.
Growth Catalysts
- Hyperscale Data Center Buildouts:Cloud operators in the United States are standardizing 800G spine-layer deployments, creating pull-through demand for active optical cable assemblies with integrated signal conditioning.
- China's Computing Cluster Initiative:Government-backed infrastructure projects are driving volume procurement of passive copper assemblies for top-of-rack interconnects under three meters.
- EU Energy Efficiency Directive:Binding power consumption thresholds for data center equipment are accelerating displacement of legacy interconnects with lower-loss alternatives.
Market Restraints
- Copper Raw Material Volatility:Electromagnetic-grade copper pricing fluctuations compress margin stability for passive cable manufacturers serving cost-sensitive rack-scale deployments.
- Optical Component Supply Concentration:VCSEL and photodetector sourcing remains concentrated among East Asian foundries, exposing lead time risk for active cable assemblers.
- Signal Integrity Limitations:Passive copper assemblies face hard distance constraints at 800G PAM4 signaling, restricting addressable reach in distributed computing fabrics.
Strategic Opportunities
- India Data Center Expansion:Domestic cloud service providers are greenfielding facilities with 400G-ready infrastructure, creating first-mover positioning for qualified interconnect suppliers.
- Edge Computing Micro-Clusters:Telecom operators are deploying containerized compute nodes requiring ruggedized active optical cables with extended temperature tolerance.
- RoHS and REACH Compliance Premium:European environmental material mandates are creating pricing separation for halogen-free cable assemblies with full substance documentation.
Industry Challenges
- High-Speed Signal Integrity Engineering Talent:Scarcity of engineers experienced in 112 Gbps PAM4 channel modeling is extending product development timelines for 800G cable assemblies.
- IEEE Standards Certification Lag:Interoperability testing against draft 802.3ck specifications is creating uncertainty in procurement commitments ahead of final standard ratification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Attach Cable Market |
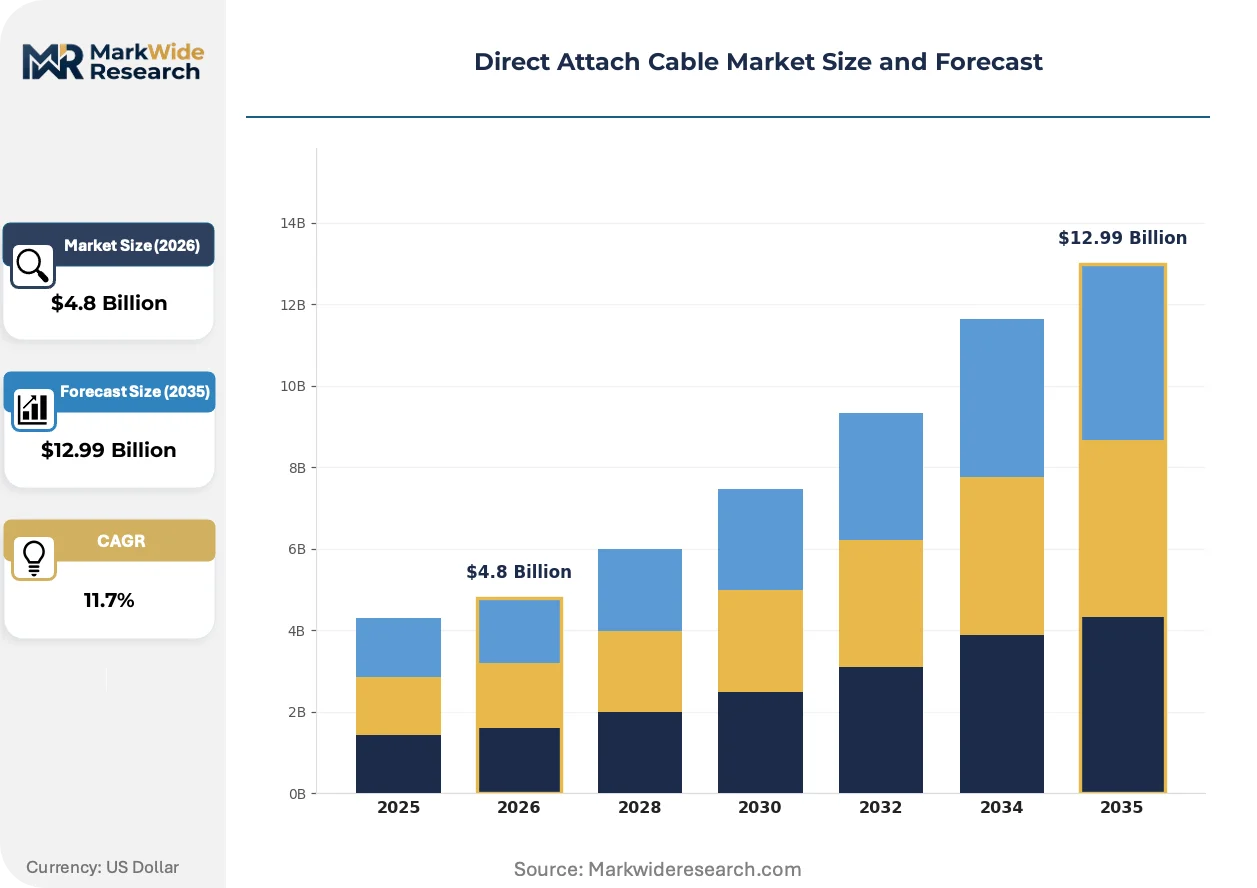
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Copper, Active Optical, Hybrid, Module-Based Installation Type: Fixed, Mobile, Rack-Mounted, Wall-Mounted Connector Type: SFP, SFP+, QSFP, QSFP+ Application: Data Centers, Telecommunication, Enterprise Networks, Broadcast |
| Companies Covered | Amphenol, Molex, TE Connectivity, Luxshare, Arista Networks, Cisco Systems, Juniper Networks, Sumitomo Electric Industries, Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Attach Cable Market Evolving Landscape
Physical layer interconnects are undergoing forced obsolescence as port densities double every generation and power budgets tighten. Three concurrent developments are compressing supplier response windows and reshaping qualification protocols.
Linear-drive optical engines are digitizing signal processing functions previously handled by discrete DSP chips, collapsing power consumption and latency in active optical cables. Hyperscale operators in the United States are piloting these assemblies in 800G spine switches ahead of broader deployment. This integration is digitizing the traditional boundary between transceiver and cable assembly, enabling new form factors that bypass pluggable module standards.
China's MIIT is enforcing GB standards for electromagnetic compatibility and energy efficiency in data center equipment sold domestically, creating a parallel certification track from FCC and ETSI pathways. Domestic cloud providers must demonstrate compliance with these benchmarks to qualify for government procurement tenders. Equipment vendors are responding by establishing in-country test facilities to accelerate market authorization timelines.
Hyperscale operators are consolidating supplier relationships around direct qualification programs that bypass traditional distribution channels. Cable assemblers with captive connector manufacturing and in-house signal integrity testing are capturing preferred vendor status in North American and Chinese procurement cycles. This concentration is most visible in the United States, where three cloud operators account for the majority of 400G and 800G port demand.
Direct Attach Cable Market Segmentation
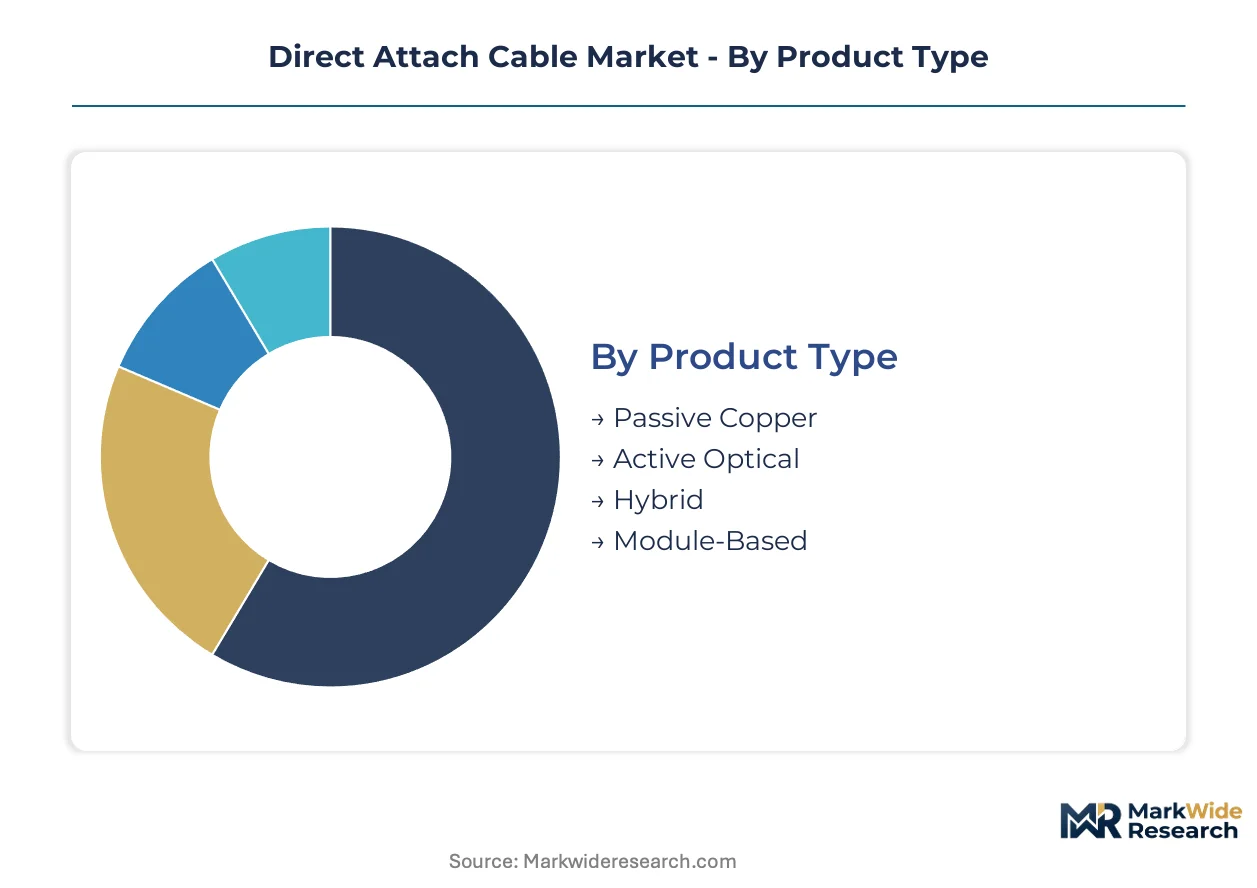
Segmentation in the direct attach cable market reflects divergent physics and procurement economics. Copper and optical variants serve distinct reach requirements, while connector form factors and installation methods align with specific rack architectures and signal integrity demands.
Product Type:
Cost tier separates passive assemblies from active alternatives, with hybrid architectures emerging at boundary conditions.
- Passive Copper:Twinax copper construction with no signal conditioning electronics. Top-of-rack deployments under three meters in hyperscale facilities concentrate procurement volume, though 800G PAM4 signaling hardens distance constraints.
- Active Optical:Integrated VCSEL or silicon photonic engines with linear-drive DSP architectures. Spine-layer switching in United States cloud infrastructure pulls demand for 400G and 800G assemblies with sub-10W power budgets.
- Hybrid:Copper front-haul with optical back-haul in single jacket construction.
- Module-Based:Pluggable transceiver modules factory-terminated to cable assemblies.
Passive copper holds installed capacity. Active optical is rotating up the share rankings.
Installation Type:
Application environment dictates mechanical robustness and accessibility requirements across deployment scenarios.
- Fixed:Permanent infrastructure runs with strain relief and bend-radius management. Data center white space in China and the United States standardizes fixed-length factory-terminated assemblies to reduce field termination errors.
- Mobile:Temporary interconnects for equipment staging and disaster recovery. Broadcast production trucks and mobile edge compute nodes require rapid-deployment cabling with reinforced jacketing.
- Rack-Mounted:Top-of-rack and middle-of-row patch fields with structured cable management.
- Wall-Mounted:Vertical distribution points in enterprise wiring closets and telecom central offices.
Fixed installations anchor procurement volume. Mobile configurations are climbing the fastest as edge compute expands.
Connector Type:
Port density and backward compatibility drive form factor selection across generational transitions.
- SFP:Legacy 1G and 10G form factor with single-lane electrical interface. Enterprise network refresh cycles in Europe sustain residual demand for SFP-terminated passive copper in access-layer switches.
- SFP+:Enhanced 10G density with improved thermal characteristics. Telecom central office modernization in India leverages SFP+ DACs for cost-sensitive aggregation layer upgrades.
- QSFP:Quad-lane 40G and 100G density with integrated heat spreader.
- QSFP+:100G and 200G evolution with doubled lane count and improved signal integrity.
QSFP+ dominates new port shipments. SFP retains residual replacement demand.
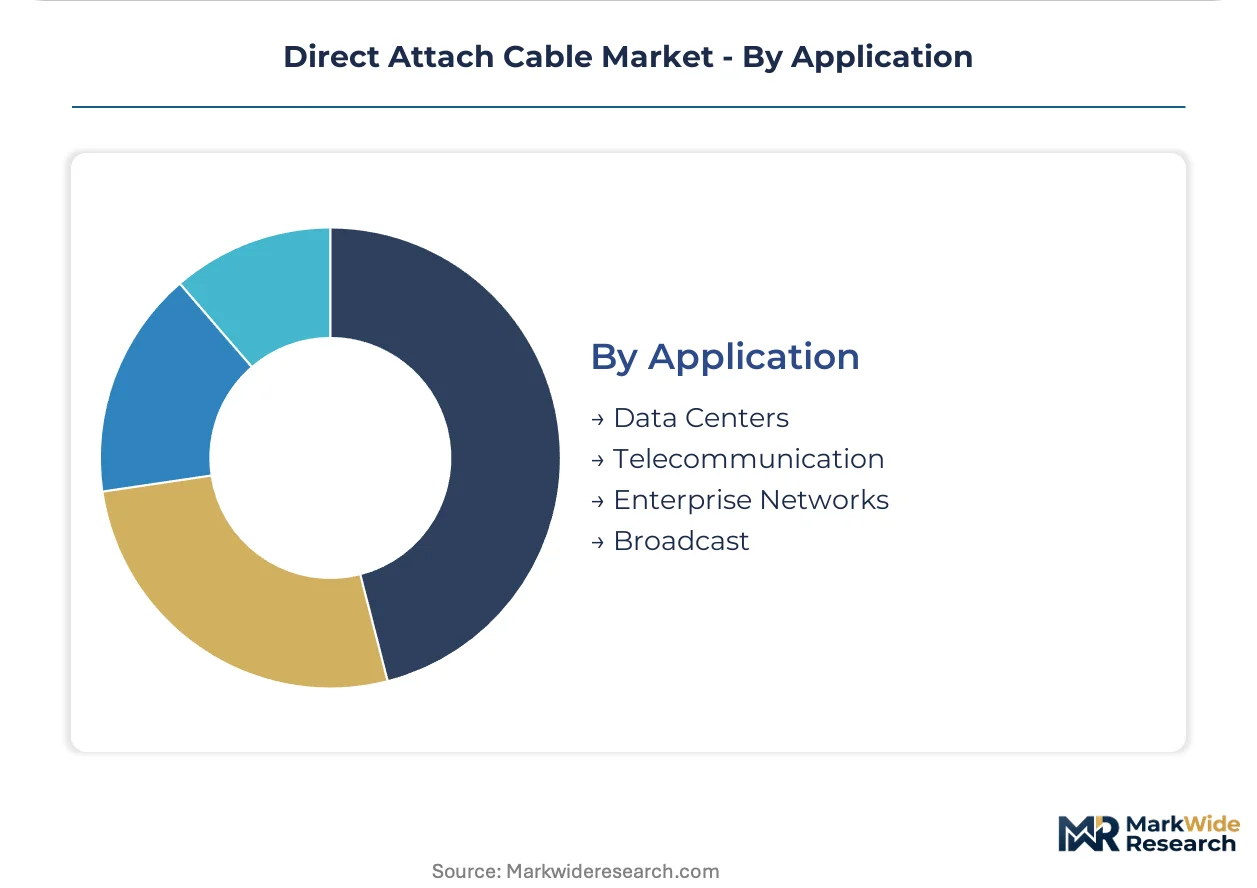
Application:
Customer type and traffic pattern intensity create divergent performance and reliability specifications.
- Data Centers:Hyperscale, colocation, and enterprise facilities with 24/7 availability requirements. United States cloud operators specify 800G active optical cables with <3ns latency for AI training clusters.
- Telecommunication:5G fronthaul, midhaul, and backhaul with extended temperature tolerance. Chinese mobile network operators deploy QSFP-DD active optical cables in C-RAN architectures.
- Enterprise Networks:Campus and branch infrastructure with 5-7 year depreciation cycles.
- Broadcast:Professional video with uncompressed 4K/8K SDI-over-IP transport.
Data centers command premium positioning. Telecommunication is expanding most quickly as 5G standalone cores deploy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian foundries dominate VCSEL and photodetector sourcing for active cable assemblies, while North American hyperscale operators drive qualification protocols for 800G spine-layer deployments. Regulatory fragmentation across the FCC, ETSI, and MIIT creates parallel certification tracks that shape regional product roadmaps.
United States
Hyperscale cloud operators in Ashburn, Virginia and Hillsboro, Oregon are standardizing 800G active optical cables for AI training clusters with sub-3 nanosecond latency requirements. The FCC governs electromagnetic emissions for these assemblies through Part 15 rules. Dallas-Fort Worth data center campuses concentrate procurement volume for passive copper top-of-rack interconnects under three meters.
China
Domestic cloud service providers and government-backed computing clusters in Guiyang and Ulanqab are driving volume procurement of QSFP-DD passive copper assemblies. MIIT enforces GB standards for electromagnetic compatibility and energy efficiency that diverge from FCC and ETSI pathways. The Yangtze River Delta manufacturing corridor houses captive connector production for cable assemblers serving state procurement tenders.
Germany
Automotive and industrial data center operators in Munich and Stuttgart specify halogen-free cable assemblies with full REACH substance documentation. ETSI electrical compliance benchmarks govern equipment sold into German infrastructure, while the EU Energy Efficiency Directive mandates binding power consumption thresholds. Frankfurt's financial services colocation facilities anchor premium-tier demand for fixed-length factory-terminated assemblies.
India
Domestic cloud service providers are greenfielding 400G-ready facilities in Mumbai and Hyderabad, creating first-mover positioning for qualified interconnect suppliers. BIS certification requirements for data center equipment create a formal compliance layer beyond importer quality checks. Chennai's electronics manufacturing cluster is scaling cable assembly capacity to serve telecom central office modernization programs.
Japan
Telecom operators deploying 5G standalone cores in Tokyo and Osaka are sourcing QSFP-DD active optical cables with extended temperature tolerance for C-RAN architectures. METI oversees industrial standards alignment with international IEEE physical layer specifications. The Kansai region's precision manufacturing base supplies high-reliability connector components for submarine cable landing stations.
Direct Attach Cable Market Competitive Landscape
Vertically integrated connector manufacturers and specialized cable assemblers split the market along the passive-active product boundary. The vendor base concentrates around three strategic archetypes: captive connector producers with backward integration into cable assembly, pure-play signal integrity specialists, and networking equipment vendors with captive interconnect programs. Competitive moves center on direct qualification programs with hyperscale operators and in-country test facility establishment for MIIT and ETSI parallel certification.
Among North American connector and cable manufacturers, Amphenol, Molex, and TE Connectivity occupy positions spanning the passive copper to active optical product spectrum. Amphenol exemplifies the captive manufacturing archetype through in-house connector and cable assembly production. Molex anchors the signal integrity engineering tier with sustained R&D intensity in high-speed copper signaling. TE Connectivity sits within the direct qualification program tier, leveraging North American supply relationships with hyperscale operators. These three entities collectively represent the competitive positioning available to vendors seeking preferred supplier status in United States and Chinese procurement cycles.
| Leading Market Players |
|---|
| Amphenol |
| Molex |
| TE Connectivity |
| Luxshare |
| Arista Networks |
| Cisco Systems |
| Juniper Networks |
| Sumitomo Electric Industries |
| Broadcom |
| Others |
Value Network & Pricing Analysis
Copper raw material volatility compresses margin stability for passive cable manufacturers while simultaneously widening pricing tier spreads between electromagnetic-grade and standard-grade assemblies. This input-cost uncertainty forces procurement teams toward long-term offtake contracts with Yangtze River Delta smelters, reshaping inventory-holding patterns across rack-scale deployment supply chains.
Pricing Analysis
The EU Energy Efficiency Directive dictates the pricing tier structure across European procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates halogen-free assemblies with full REACH documentation from basic copper constructions. Price differentiation hinges on certification grade and volume scale, with hyperscale operators commanding double-digit discounts on 800G active optical cable commitments. Cost compression in passive copper assemblies is intensifying because electromagnetic-grade copper spot markets remain volatile. Enterprise network refresh cycles in Europe exhibit highest price sensitivity, while United States cloud operators demonstrate lowest sensitivity due to latency-performance tradeoffs.
Supply Chain Analysis
Extended payment terms from hyperscale operators force cable assemblers to utilize supply-chain finance facilities with East Asian component distributors. Manufacturing concentrates in China, Vietnam, and Malaysia, with Yangtze River Delta housing captive connector production for state procurement tenders. Raw material dependencies center on electromagnetic-grade copper, VCSEL arrays from Taiwanese foundries, and halogen-free jacketing compounds. Single-source vulnerability persists in silicon photonic engine sourcing. Distribution runs through direct qualification programs that bypass traditional channel partners for North American cloud infrastructure procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue from cable testing, certification, and field replacement is expanding faster than hardware sales, converting one-time equipment transactions into recurring lifecycle support contracts. This service-attach layer rewards suppliers with captive technical field forces and diagnostic equipment deployed at customer sites.
For Market Incumbents: Insulate margin pools by deepening backward integration into connector manufacturing and establishing in-country test facilities for MIIT parallel certification. Active optical cable assemblies face substitution risk from linear-drive optical engines that collapse traditional transceiver-cable boundaries. R&D intensity in 112 Gbps PAM4 channel modeling serves as the priority defensive lever. For New Entrants and Emerging Players: Establish a beachhead in India's greenfield 400G-ready data center infrastructure, where BIS certification requirements create qualification barriers for unestablished suppliers. Edge computing micro-clusters for telecom operators represent the most penetrable application layer. A certification-first go-to-market angle accelerates trust formation with domestic cloud service providers in Mumbai and Hyderabad. For Investors and Strategic Acquirers: Signal integrity engineering boutiques with proven 800G interoperability testing capabilities represent the highest-conviction acquisition archetype for this market. Long-term viability across the projection horizon rests on sustained hyperscale capex cycles and generational port density transitions. The inflection indicator to monitor is IEEE 802.3ck final standard ratification timing against procurement commitment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Qualification Program Establishment | Bypasses distribution channels for preferred vendor status with United States hyperscale operators. |
| In-Country Test Facility Deployment | Accelerates MIIT market authorization timelines for Chinese government procurement tenders. |
| Linear-Drive Optical Engine Integration | Collapses power consumption and latency in 800G spine-layer active cable assemblies. |
| Lifecycle Support Contract Expansion | Captures aftermarket revenue from field replacement and certification services. |
| Halogen-Free Material Transition | Meets REACH substance documentation requirements for European environmental mandates. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hyperscale data center procurement officers, cable assembly plant managers, and signal integrity engineering directors; and secondary validation through IEEE standards documentation, SEC hyperscaler capex disclosures, and MIIT certification registries. Bottom-up unit economics triangulated against top-down infrastructure spending forecasts anchored the market sizing.
Forecast inputs considered product type segmentation across passive copper, active optical, and hybrid architectures; connector form factor transitions from QSFP+ to QSFP-DD and OSFP; and application intensity across data center, telecommunications, and enterprise network deployments. CAGRs derived from generational port density roadmaps and replacement cycle compression patterns. Hyperscale operator 800G deployment timelines and China's computing cluster initiative procurement calendars served as volume anchors.
Sensitivities concentrate around IEEE 802.3ck ratification delays, copper commodity price spikes, and VCSEL foundry capacity constraints. Forecasts reflect assumptions on hyperscale capex continuity and regional regulatory alignment timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Flange Market
Cables
Cable Management System Market
Cables
North America Copper Wire and Cable Market
Cables
Global Cable Tie Market
Cables
Middle East and Africa Submarine Cable System Market
Cables
South Africa Wire and Cable Market
Cables
Submarine Cable System Market
Cables
Premise Cable Market
Cables
Medium Voltage Cables Accessories Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Global Wires and Cables Market
Cables
Aluminium Battery Cable Market
Cables
Fiber Optic Cable Materials Market
Cables
Cable Detector Market
Cables
Anti-Static Space Wires Market
Cables
Medium Voltage Cables Market