
 Cable Clamp Market | 2026-2036
Cable Clamp Market Size, Share, and Industry Trends Forecast 2026-2036
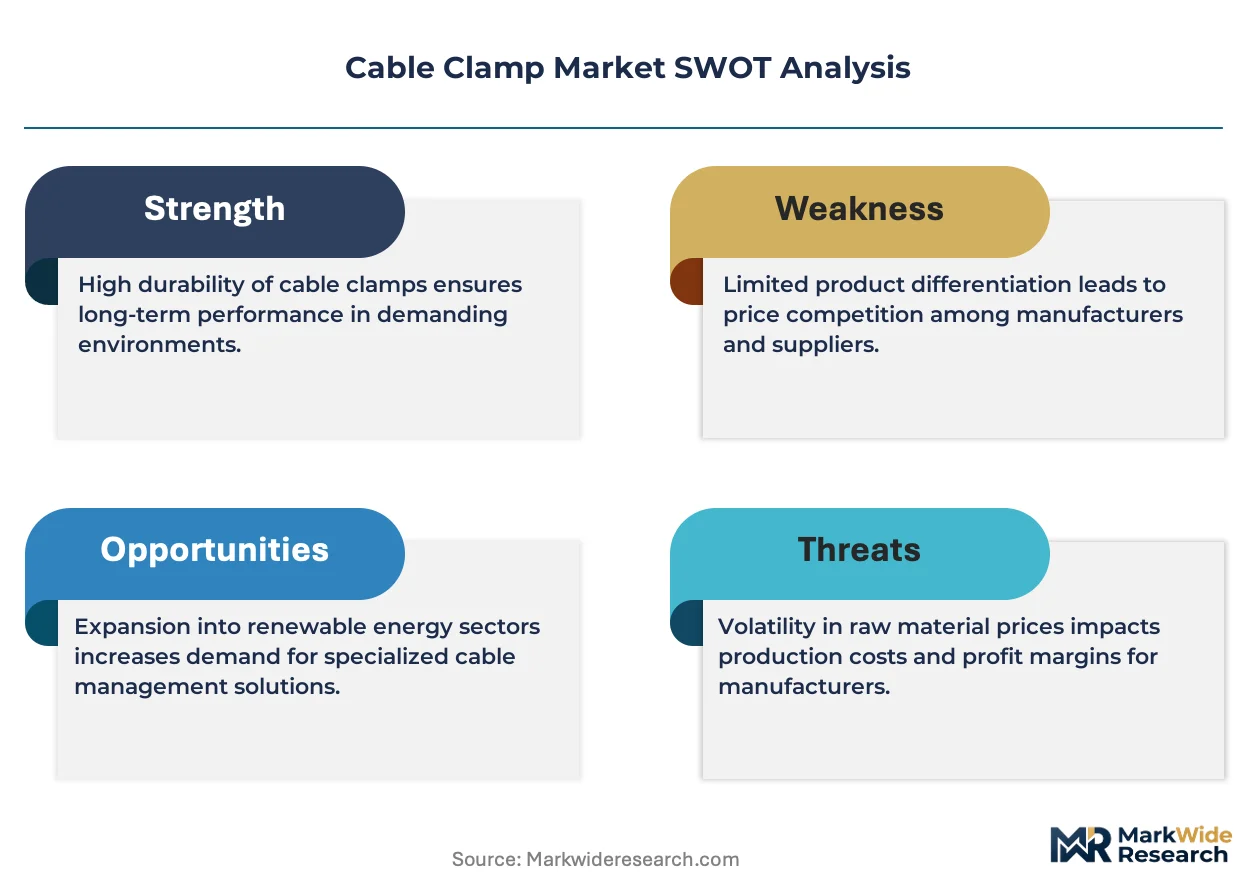
Cable Clamp Market Analysis
Modular bundling of cable clamps with pre-assembled routing hardware is repositioning buyer choice toward integrated solutions rather than standalone components. Eaton leverages its electrical infrastructure footprint to anchor demand across utility-scale installations. Panduit competes through channel control in data center and network cabling verticals. CMP Products specializes in marine and hazardous-environment clamp specifications that command premium positioning.
A cable clamp is a mechanical fastening device, typically fabricated from metal alloys or engineered polymers, designed to secure, route, and strain-relieve electrical cables and wire bundles within enclosures, conduits, or structural frameworks. Metal clamps stamped from stainless or galvanized steel deliver tensile strength for heavy-duty industrial applications, while nylon formulations offer corrosion resistance and electrical insulation for sensitive environments. Fixed-type clamps dominate mature electrical infrastructure replacement cycles, whereas adjustable configurations capture growth in dynamic telecommunications and renewable energy installations where cable diameters vary across deployment phases. Application demand in automotive wiring harnesses concentrates margin pools around vibration-resistant locking mechanisms that meet OEM durability standards.
RoHS and REACH compliance frameworks in Europe restrict cadmium and lead content in metal clamp platings, compelling reformulation of corrosion-resistant coatings across the supply base. OSHA cable-support standards in the United States mandate load-rated fastening in commercial construction, directly shaping product certification requirements and market access conditions. ISO 9001 quality management benchmarks filter supplier eligibility for utility and transportation procurement channels. Stakeholders must monitor evolving material compliance thresholds and building electrification codes to align R&D allocation with regulatory trajectories.
Market Dynamics
Data center power distribution buildouts are pulling cable clamp procurement toward integrated routing systems rather than discrete fastening components, compressing supplier margins on standalone hardware while rewarding bundling capabilities.
Growth Catalysts
- EU RoHS directive:Hazardous substance restrictions in electrical accessories are accelerating compliant material reformulation across European manufacturing bases, expanding addressable market for certified suppliers.
- Automotive wiring harnesses:OEM durability standards for vibration-resistant locking mechanisms are concentrating specification authority around clamp designs that survive thermal cycling and mechanical stress testing.
- Germany's industrial corridor:Infrastructure upgrade cycles across manufacturing clusters in Bavaria and North Rhine-Westphalia are generating concentrated demand for heavy-duty metal clamp configurations.
Market Restraints
- Stainless steel input volatility:Alloy pricing fluctuations directly compress margin pools on stamped metal clamp production, forcing inventory hedging or material substitution trade-offs.
- REACH compliance costs:European chemical registration requirements for corrosion-resistant coatings add fixed regulatory overhead that disadvantages smaller plating shops.
- Nylon 6,6 supply concentration:Engineered polymer feedstock for insulated clamp variants depends on limited regional resin production, creating vulnerability to force majeure disruptions.
Strategic Opportunities
- Offshore wind installations:Marine-rated clamp specifications for subsea cable management represent uncaptured premium positioning beyond traditional industrial applications.
- OSHA load-rated mandate expansion:U.S. commercial construction code tightening creates certification-driven preference shifts toward pre-certified fastening systems.
- Renewable energy phase variability:Adjustable clamp configurations for dynamic cable diameter changes across solar and wind deployment stages capture growth outside fixed-infrastructure replacement cycles.
Industry Challenges
- ISO 9001 certification timelines:Quality management benchmark compliance creates 12-18 month supplier qualification delays for utility and transportation procurement channels.
- Legacy electrical enclosure compatibility:New clamp geometries must interface with decades-old conduit standards, constraining design freedom and testing burden.
- Cross-functional engineering talent scarcity:Combined mechanical fastening and polymer chemistry expertise required for advanced material development concentrates in limited geographic pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Clamp Market |
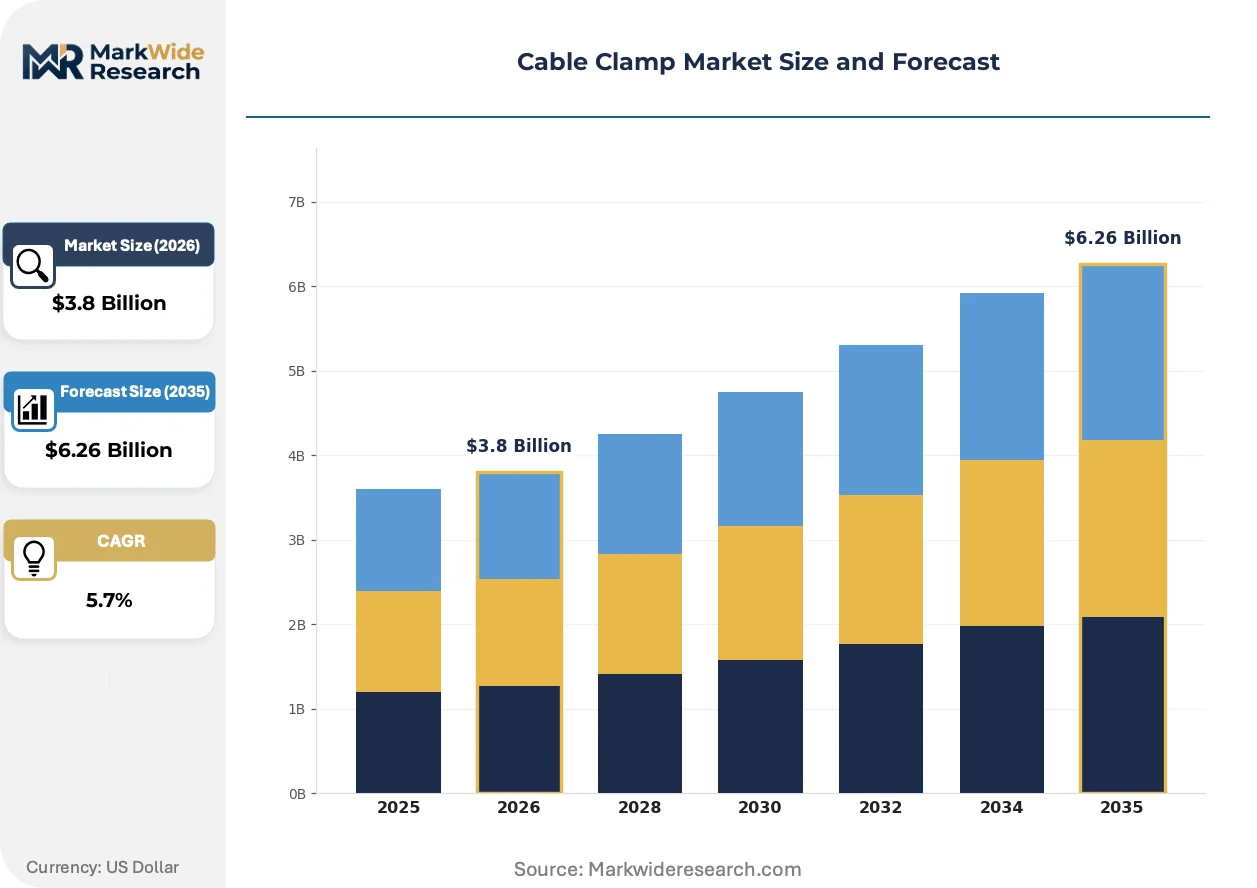
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Metal, Nylon, Rubber Type: Fixed, Adjustable, Locking, Clip Application: Electrical, Automotive, Telecommunications, Construction Size: Small, Medium, Large, Extra Large |
| Companies Covered | 3M, Eaton, CMP Products, Nexans, Hilti, Ellis Patents, Prysmian Group, ABB, Panduit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Clamp Market Emerging Trajectories
Material science advances and procurement model compression are restructuring how cable management hardware reaches end-use installations, with implications for supplier competitive posture and channel economics.
Glass-reinforced polyamide formulations are absorbing mechanical load requirements previously reserved for metal stampings in medium-duty industrial environments. Data center operators deploying these polymer clamps at scale are reducing installation weight and eliminating galvanic corrosion risks in humid rack environments. The technology is absorbing share from stainless steel in applications below 50-pound cable bundle loads, compressing metal supplier volume in telecommunications infrastructure.
REACH substance restrictions on cadmium and lead platings are forcing corrosion-resistant coating reformulation across European supply bases. Manufacturers substituting zinc-nickel or organic coating chemistries face 18-24 month requalification cycles with industrial OEMs. Marine and hazardous-environment clamp specifications in the EU are experiencing the most acute compliance-driven supplier consolidation.
Integrated cable management procurement is consolidating purchasing authority around electrical contractors and systems integrators rather than maintenance departments. Pre-assembled routing hardware bundles containing clamps, trays, and fasteners are displacing component-level sourcing in German industrial and data center verticals. This concentration is most visible in utility-scale renewable installations where EPC contractors specify complete subsystem packages.
Cable Clamp Market Segmentation
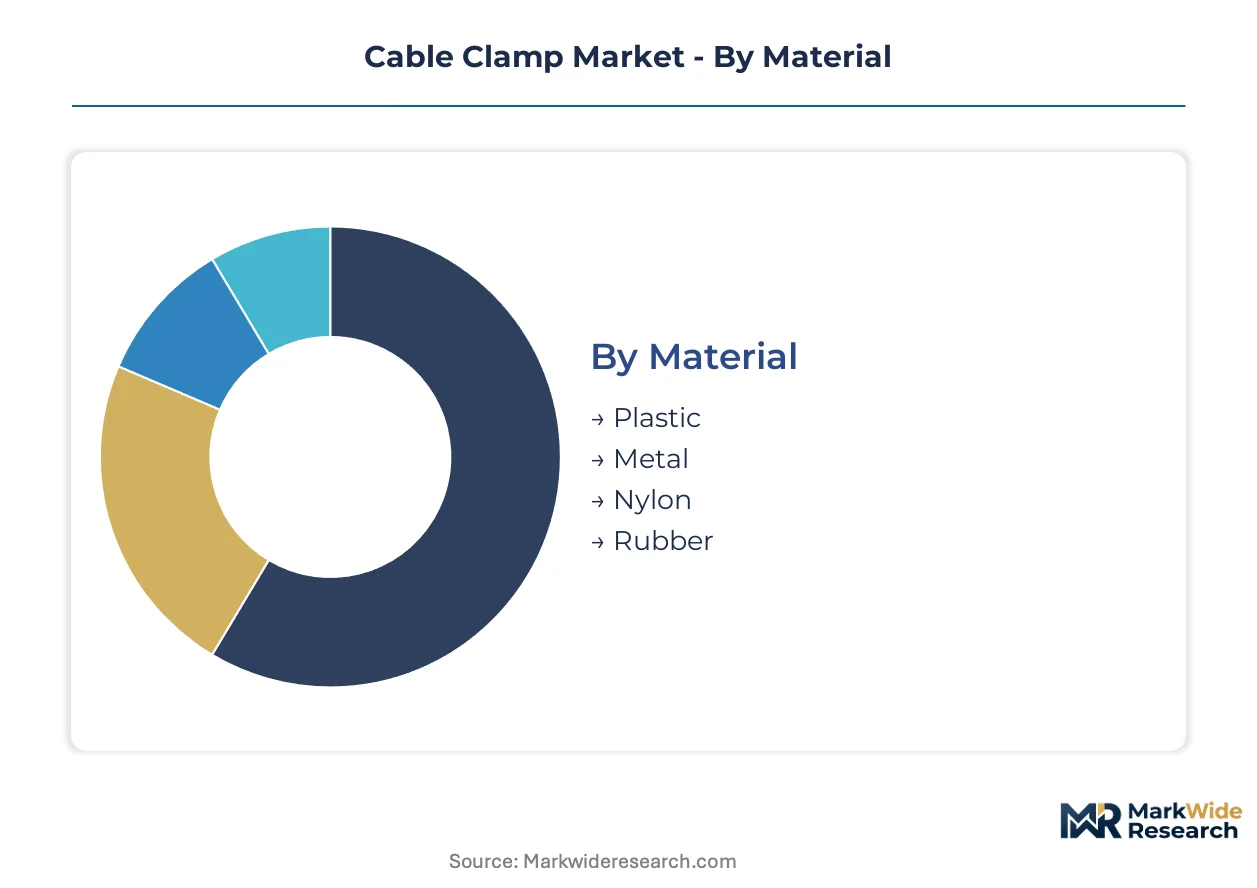
Cable clamp procurement patterns fragment sharply across material chemistry, mechanical configuration, and end-use environment. Specification authority concentrates differently in each dimension, forcing suppliers to anchor capabilities in multiple segmentation layers simultaneously.
Material:
Supply concentration in engineered polymer feedstock and alloy processing creates divergent margin structures across material categories. Resin producers and metal stampers command asymmetric leverage depending on end-use certification requirements.
- Plastic:Glass-reinforced polyamide formulations absorb mechanical loads previously reserved for metal in medium-duty industrial settings. Data center operators in humid rack environments reduce installation weight and eliminate galvanic corrosion risks through polymer deployment.
- Metal:Stainless and galvanized steel stampings deliver tensile strength for heavy-duty infrastructure applications. Germany's industrial corridor in Bavaria and North Rhine-Westphalia generates concentrated demand for corrosion-resistant metal configurations in manufacturing cluster upgrades.
- Nylon:Nylon 6,6 supply concentration in limited regional resin production creates force majeure vulnerability for insulated clamp variants.
- Rubber:Elastomer formulations provide vibration damping and environmental sealing for automotive and marine specifications.
Today's leader: Metal. Tomorrow's challenger: Plastic.
Type:
Cost tier differentiation separates premium adjustable mechanisms from commodity fixed configurations. OEM durability testing and requalification cycles erect barriers between pricing strata.
- Fixed:Stamped configurations dominate mature electrical infrastructure replacement cycles with minimal design variation. Utility procurement channels favor fixed-type clamps for standardized conduit installations where cable diameters remain constant.
- Adjustable:Dynamic diameter accommodation captures growth in renewable energy deployments where cable bundles vary across construction phases. Solar and wind installations in early-stage markets favor adjustable mechanisms to reduce inventory complexity.
- Locking:Vibration-resistant mechanisms concentrate margin pools in automotive wiring harnesses where OEM thermal cycling standards apply.
- Clip:Snap-fit designs target rapid-installation telecommunications and network cabling verticals with tool-free deployment requirements.
Fixed clamps anchor current volume. Adjustable configurations gain share fastest in emerging application verticals.
Application:
Customer type concentration around electrical contractors and systems integrators reshapes how application segments access procurement authority. Pre-assembled subsystem bundles displace component-level sourcing in consolidated channels.
- Electrical:Commercial and industrial power distribution infrastructure generates baseline demand for RoHS-compliant metal and polymer configurations. OSHA load-rated mandates in U.S. construction tighten certification requirements for fastening systems.
- Automotive:OEM wiring harness specifications concentrate authority around vibration-resistant locking mechanisms that survive durability testing. Thermal cycling and mechanical stress standards filter supplier eligibility.
- Telecommunications:Data center power distribution buildouts pull procurement toward integrated routing systems rather than discrete fastening components.
- Construction:Commercial building electrification codes drive specification shifts toward pre-certified fastening systems in utility-scale installations.
Electrical applications command current revenue concentration. Automotive specifications offer the steepest expansion trajectory through electrification-driven harness complexity.
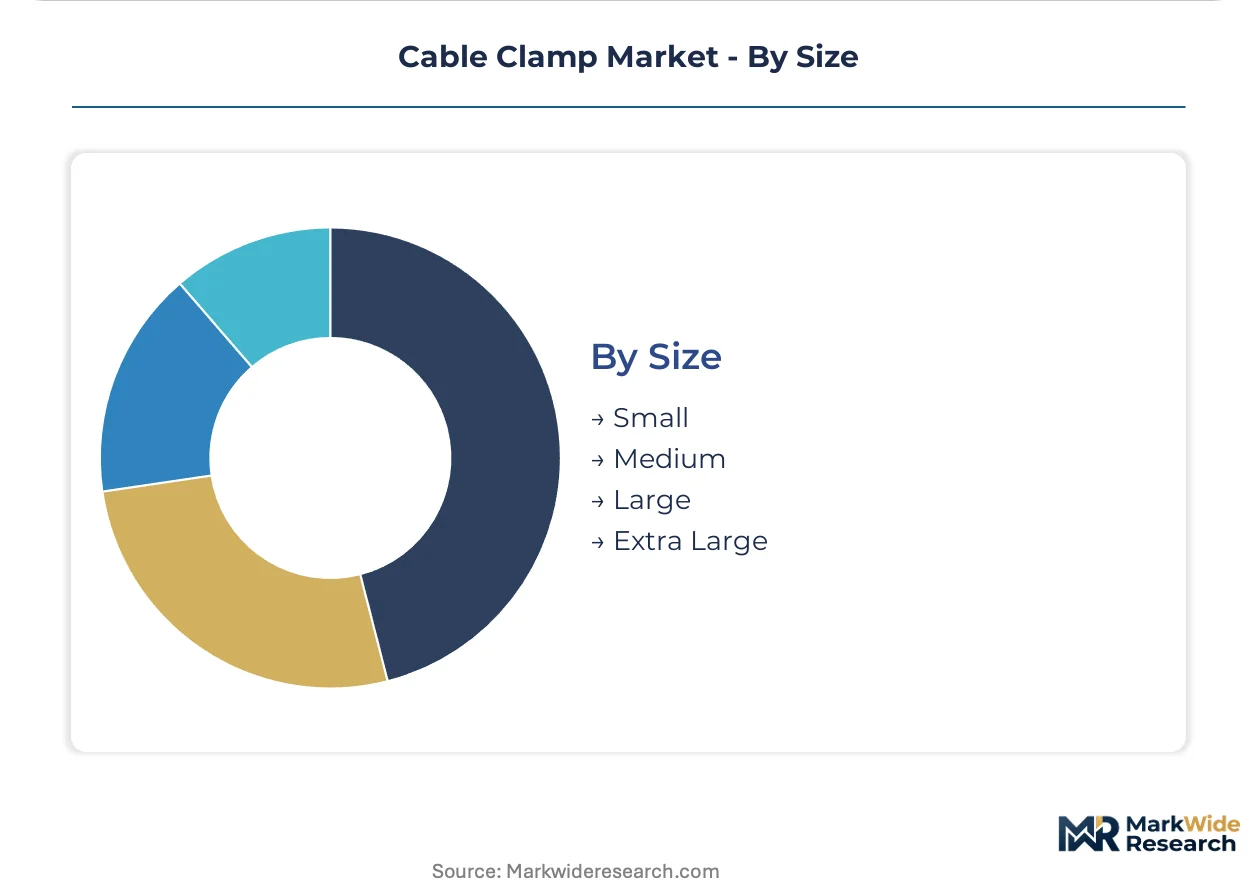
Size:
Volume distribution across size bands reflects infrastructure scale rather than unit economics, with large-format clamps carrying disproportionate margin contribution despite lower shipment frequency.
- Small:Compact configurations serve electronics enclosures and control panel applications with space-constrained routing requirements.
- Medium:General-purpose industrial and commercial installations absorb the highest unit volumes across replacement cycles.
- Large:Heavy-duty infrastructure and utility-scale renewable installations require load-rated fastening for substantial cable bundles.
- Extra Large:Subsea cable management and offshore wind specifications command premium positioning for marine-rated configurations.
Medium sizes dominate shipment volume. Extra large formats capture the most acute premium positioning in specialized environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial cable management hardware traces its commercial origins to early 20th-century electrical infrastructure buildouts in Germany and the United States, where standardized fastening systems emerged alongside electrification of manufacturing corridors.
Germany
RoHS-compliant material reformulation dominates supplier priorities as REACH substance restrictions tighten cadmium and lead plating limits across Bavaria and North Rhine-Westphalia manufacturing clusters. The KBA enforces durability standards for automotive wiring harness applications. Heavy-duty metal clamp procurement concentrates in Stuttgart's automotive corridor and Düsseldorf's industrial belt for infrastructure upgrade cycles.
United States
OSHA load-rated fastening mandates in commercial construction reshape certification requirements for electrical contractors deploying power distribution systems. The EPA coordinates with state regulators on hazardous substance thresholds in corrosion-resistant coatings. Data center buildouts in Northern Virginia and Dallas-Fort Worth pull procurement toward integrated routing hardware bundles.
China
GB standards for electrical accessories accelerate domestic supplier consolidation as MIIT tightens material compliance frameworks for export-oriented production. Dual carbon goals drive polymer substitution in medium-duty industrial applications. Manufacturing gravity concentrates in Yangtze River Delta electronics clusters and Pearl River Delta export processing zones for telecommunications hardware.
India
BIS certification requirements filter supplier eligibility for utility and transportation infrastructure procurement as CEA mandates strain-relief standards in power distribution installations. PLI scheme incentives attract polymer resin production for insulated clamp variants. Demand clusters in Maharashtra's automotive belt and Gujarat's industrial corridor for manufacturing facility electrification.
Japan
METI industrial standards for vibration-resistant fastening mechanisms concentrate specification authority around automotive OEM thermal cycling requirements. JIS benchmarks shape export competitiveness for marine-rated clamp configurations. Production concentrates in Aichi Prefecture's automotive supplier ecosystem and Osaka's electrical equipment manufacturing base.
Cable Clamp Market Vendor Landscape
The competitive structure tilts toward diversified electrical infrastructure conglomerates with captive distribution channels. Tiered specialization separates premium marine and hazardous-environment specifications from commodity stamped metal configurations. Strategic archetypes include integrated electrical systems providers, channel-dominant cable management specialists, and marine-rated niche fabricators. Capacity expansion in polymer formulation and strategic partnerships with EPC contractors represent dominant competitive moves.
Among diversified electrical infrastructure providers, Eaton and ABB exemplify scale-driven positioning across utility-scale installations. Panduit occupies a position within the channel-control archetype for data center and network cabling verticals. CMP Products anchors the premium-specialist tier for marine and hazardous-environment specifications.
| Leading Market Players |
|---|
| 3M |
| Eaton |
| CMP Products |
| Nexans |
| Hilti |
| Ellis Patents |
| Prysmian Group |
| ABB |
| Panduit |
| Others |
Supply Flow & Price Mechanics
Glass-reinforced polyamide substitution for metal stampings is simultaneously compressing per-unit manufacturing costs and redistributing supplier power toward resin compounders with formulation IP. This materials transition concentrates margin capture among polymer specialists while forcing legacy metal stampers into price competition or vertical integration into compounding.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates RoHS-certified marine-rated clamps from commodity fixed-type configurations. Price differentiation rests on ISO 9001 certification status and REACH-compliant coating chemistry. Cost compression in standard-tier metal clamps is intensifying because stainless steel input volatility forces inventory hedging costs onto smaller stampers. Data center systems integrators exhibit lowest price sensitivity due to bundled procurement authority, while maintenance departments in mature electrical infrastructure remain most price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with Nylon 6,6 resin production concentrated in Germany, the United States, and Japan. Raw material dependencies draw from glass fiber additives, corrosion-resistant coating platings, and high-grade stainless steel alloys. Supply chain risk centers on force majeure disruptions in regional resin production that would cascade through insulated clamp variants. Distribution runs through electrical distributors and EPC contractor procurement channels rather than direct OEM supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH compliance costs in Europe and MIIT material framework advantages in China, where domestic resin production under dual carbon goals lowers polymer input costs for export-oriented manufacturers.
For Market Incumbents: To counter glass-reinforced polyamide substitution eroding metal clamp volumes, secure backward integration into polymer compounding capabilities in Yangtze River Delta clusters. Anchor channel control through pre-assembled routing hardware bundles that lock in electrical contractor specification authority.
For New Entrants and Emerging Players: The price-point gap between marine-rated premium clamps and commodity stamped metal configurations offers entry into adjustable-type mechanisms for renewable energy phase variability. Target solar and wind EPC contractors in early-stage markets with tool-free clip designs that reduce installation labor costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among ISO 9001-certified metal stampers without polymer formulation capabilities, as material transition risk discounts their asset base. Long-term viability favors suppliers with dual material competencies across glass-reinforced polyamide and corrosion-resistant steel. Watch REACH substance restriction expansion as the inflection signal for accelerated coating chemistry requalification cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captures margin pools shifting from metal stampers to resin formulators with formulation IP. |
| Pre-assembled Routing Hardware Bundles | Locks in electrical contractor specification authority and displaces component-level sourcing. |
| Marine-rated Coating Chemistry Requalification | Positions suppliers for REACH-compliant premium positioning in offshore wind installations. |
| Adjustable-type Mechanism Capacity Expansion | Captures renewable energy phase variability demand outside fixed-infrastructure replacement cycles. |
| Channel Partnership with EPC Contractors | Consolidates procurement authority in utility-scale data center and renewable buildouts. |
Methodological Framework
Multiple input streams — procurement managers at data center operators, plant engineers in Germany's automotive corridor, resin compounders in the Yangtze River Delta, and EPC contractor specification leads — were reconciled against customs trade data, SEC filings from diversified electrical infrastructure providers, MIIT material compliance announcements, and REACH substance restriction updates. Bottom-up unit shipment estimates across material, type, and application segments were triangulated against top-down market value reconstruction from supplier revenue disclosures.
Data-stream reconciliation anchored volume and value outputs across the analysis window through segmented demand modeling by material chemistry, mechanical configuration, end-use environment, and regional regulatory cluster. CAGRs were derived from deployment pipeline analysis in data center power distribution, automotive wiring harness electrification, and renewable energy infrastructure buildouts. Industry-specific forecast inputs included OSHA load-rated mandate expansion timelines and RoHS directive substance threshold evolution.
Caveats apply where stainless steel alloy price volatility, REACH coating chemistry requalification delays, or Nylon 6,6 force majeure disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory trajectory continuity and procurement model consolidation toward bundled subsystem sourcing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Europe Cable Joints Market
Cables
Network Cable Tester Market
Cables
HVDC Cables Market
Cables
Cable Fault Locator Market
Cables
Submarine Optical Fiber Cables Market
Cables
India Optic Fiber Cable and Accessories Market
Cables
Cable Management System Market
Cables
Fiber Optic Cable Materials Market
Cables
Cable Management Accessories Market
Cables
Shipboard Cable Market
Cables
Hybrid Cables Market
Cables
Cable Detector Market
Cables
Coaxial Cable Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
EDM Wires Market