
 Fiber Optic Cable Market | 2026-2036
Fiber Optic Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Cable Market Intelligence
The performance gap between specialized, high-bandwidth cables for subsea and data center use versus commodity-grade terrestrial cables for last-mile access is consolidating supply power. Corning leverages its deep material science expertise to dominate the premium single-mode fiber segment. Prysmian competes across a broad portfolio, including specialized energy and subsea applications. Meanwhile, YOFC anchors its position through massive production scale primarily serving the Chinese domestic market.
A fiber optic cable is a network cable containing one or more optical fibers used to carry light. Each fiber consists of a glass core surrounded by a cladding layer, designed to transmit data as light pulses over long distances with minimal signal loss. Single-mode fiber continues to lead in long-haul telecommunications and subsea routes due to its superior bandwidth and distance capabilities. The data centers segment represents the fastest-growing end-user category, driving demand for both single-mode and high-density multi-mode cables for internal networking.
Regulatory frameworks directly influence cable specifications and market access. In Europe, the EU's Construction Products Regulation (CPR) mandates specific fire safety ratings for indoor installations, while in China, adherence to national GB standards is essential. National broadband plans, such as those funded by the US BEAD program, set deployment and performance criteria. Navigating these varied regional standards and securing supply of preform materials are critical strategic priorities for manufacturers.
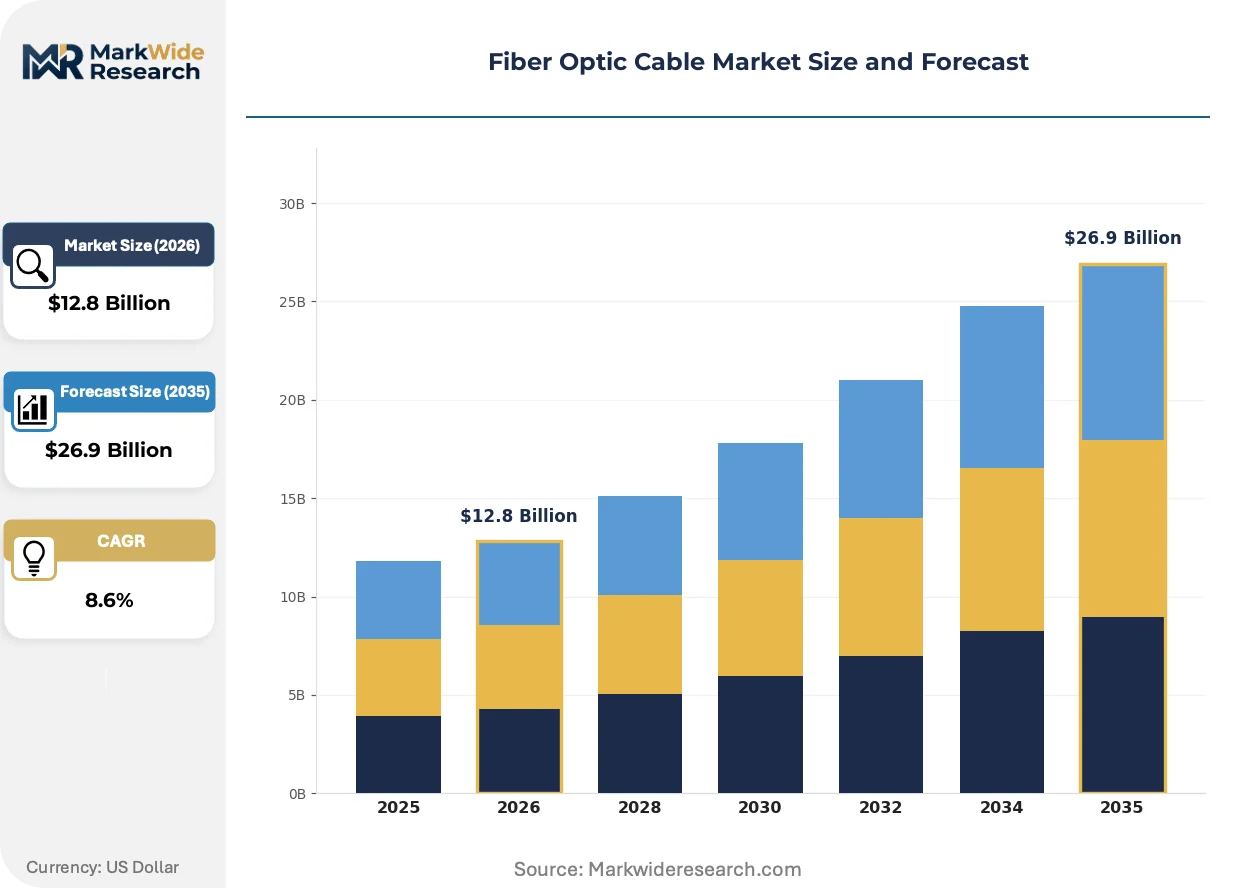
Market Dynamics
The fundamental market dynamic is a performance and price divergence between specialized, high-margin cables for subsea and data center applications and commoditized cables for terrestrial broadband. This bifurcation concentrates manufacturing power with firms capable of both material science innovation and massive production scale.
Growth Catalysts
- Government Broadband Mandates:National digital infrastructure programs, including the US BEAD program and similar initiatives in Indonesia, are creating substantial, long-term demand for terrestrial fiber optic cable deployment to connect underserved communities.
- Hyperscale Data Center Expansion:The ongoing global construction of hyperscale data centers by cloud service providers drives continuous demand for high-density single-mode and multi-mode fiber to support immense internal data traffic.
- 5G Network Densification:Mobile network operators require extensive fiber-to-the-antenna (FTTA) and backhaul networks to support the high-bandwidth, low-latency performance characteristics of 5G and future wireless technologies.
Market Restraints
- Optical Preform Scarcity:The global supply of high-purity glass preforms, the core raw material for optical fiber, is concentrated among a few key producers, creating potential bottlenecks and price volatility for cable manufacturers.
- High Installation Costs:The civil engineering work associated with deploying terrestrial cable, including trenching and securing rights-of-way, constitutes a significant portion of total project cost and can slow deployment schedules.
- Skilled Labor Shortages:A deficit of trained fiber optic technicians and splicers creates a critical bottleneck, limiting the pace at which network operators can physically build out and connect new fiber infrastructure.
Strategic Opportunities
- Hollow-Core Fiber Technology:The development of hollow-core fibers, which transmit light through air, offers a pathway to ultra-low latency connections for niche applications like high-frequency trading and scientific research.
- Fiber Sensing Applications:Expanding use of optical fibers as distributed sensors for monitoring temperature, strain, and acoustics in pipelines, railways, and critical infrastructure opens a new industrial market segment. * Rural African Connectivity: Underpenetrated markets across sub-Saharan Africa present a long-term opportunity for building foundational digital infrastructure, leapfrogging older copper-based technologies with direct fiber-to-the-home rollouts.
Industry Challenges
- Navigating Divergent Standards:Manufacturers must manage production and inventory for multiple regional standards, such as the fire safety requirements of the EU's CPR and China's distinct GB standards, increasing operational complexity.
- Capex for Capacity Expansion:Building new optical fiber and preform manufacturing facilities requires massive capital investment, presenting a high barrier to entry and a significant financial risk for incumbents planning expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Cable Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode, Multi-Mode, Armored, Loose Tube Installation Type: Indoor, Outdoor, Aerial, Burial End User: Telecommunications, Data Centers, Enterprises, Government Technology: FTTH, FTTB, FTTX, PON |
| Companies Covered | YOFC, CommScope, Prysmian, Hengtong Group, Nexans, Corning, Furukawa Electric, LS Cable & System, Sumitomo Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Cable Market Strategic Shifts & Innovations
Industrialization is redefining fiber deployment, as automated design and mass-produced components replace bespoke engineering. This shift prioritizes scalability and speed to meet the unprecedented demand from national broadband plans and data center construction, favoring suppliers who can deliver standardized solutions at volume.
Advanced network planning software incorporates GIS data, material costs, and demand modeling to generate optimal cable routes. Hyperscale data center operators and large telecoms are the primary adopters of this technology. This software is automating the complex and time-intensive engineering work required for large-scale network design, compressing project timelines from months to weeks.
European Union regulations like the Construction Products Regulation (CPR) impose strict fire safety classifications on cables installed within buildings. This forces manufacturers to develop, test, and certify specific product variants with low-smoke, zero-halogen jackets for market access. The data center and enterprise LAN segments are most impacted, requiring verifiable CPR compliance for all indoor cabling.
A shift toward open-access network models is altering infrastructure ownership and procurement. Specialized infrastructure companies now build and own the physical fiber layer, leasing dark fiber or wholesale bandwidth to multiple retail service providers. This model, gaining traction in Europe and North America, separates physical asset ownership from service delivery, disrupting traditional integrated telecommunication carriers.
Fiber Optic Cable Market Segmentation
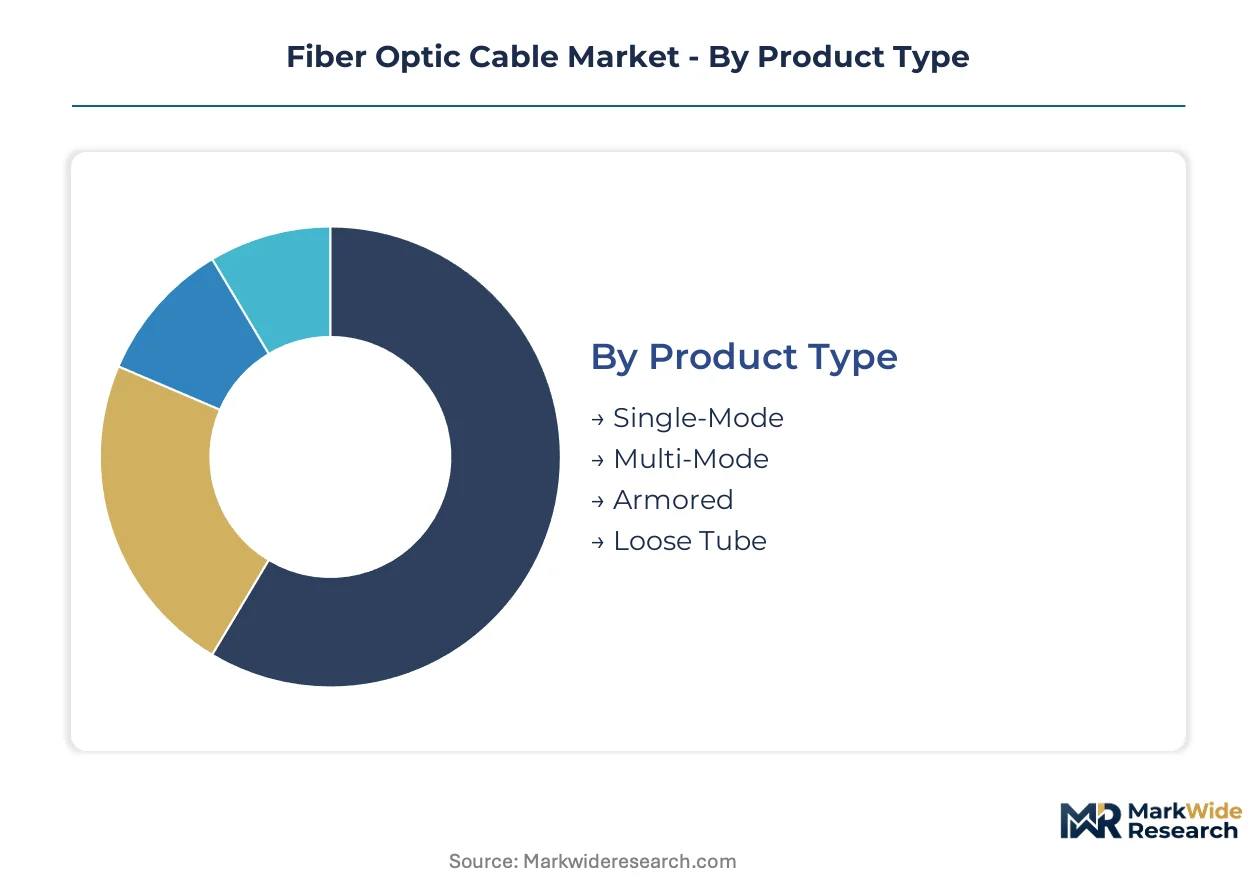
Fiber optic cable segmentation provides a crucial framework for understanding market dynamics, guiding product development, and addressing specific end-user requirements. This granular analysis highlights where specialized performance attributes and regulatory compliance drive distinct demand patterns.
Product Type:
Manufacturers must navigate specific certification burdens for different product types, particularly concerning performance characteristics and material composition for diverse deployment environments.
- Single-Mode:This fiber type features a small glass core that allows a single light path, enabling data transmission over very long distances with minimal signal dispersion. Demand concentrates in long-haul telecommunications and subsea routes, driven by the need for superior bandwidth and extended reach capabilities.
- Multi-Mode:Characterized by a larger core, multi-mode fiber allows multiple light paths, making it suitable for shorter distances and high-bandwidth applications within confined spaces. Hyperscale data centers and enterprise LANs represent significant demand, supporting immense internal data traffic requirements.
- Armored:These cables incorporate a protective outer layer, often steel, to shield the optical fibers from physical damage and rodent intrusion. Deployment in harsh industrial environments or direct burial applications benefits from its enhanced durability.
- Loose Tube:Fibers are housed within gel-filled plastic tubes, providing protection from water ingress and temperature fluctuations. This design is widely adopted for outdoor aerial and duct installations where environmental resilience is critical.
Leading the category by volume: Single-Mode. Growing fastest: Multi-Mode.
Installation Type:
Installation type dictates the specific environmental and structural performance requirements for fiber optic cables, influencing material choices and regulatory compliance.
- Indoor:Cables designed for indoor use prioritize fire safety, often featuring low-smoke, zero-halogen jackets to meet stringent building codes like the EU's CPR. Data centers and commercial enterprise networks require these specialized cables for internal connectivity.
- Outdoor:These cables are engineered to withstand environmental stressors such as UV radiation, moisture, and extreme temperatures, crucial for backbone infrastructure. Telecommunications providers deploying national broadband networks in Indonesia and the US BEAD program extensively utilize outdoor cables.
- Aerial:Cables suspended from utility poles or structures require high tensile strength and resistance to wind and ice loading. Rural connectivity projects in underserved communities often rely on aerial installations for cost-effective deployment.
- Burial:Designed for direct underground placement, burial cables feature robust jacketing and often armor to protect against soil pressure, moisture, and excavation damage. Extensive civil engineering work is associated with these deployments.
This category highlights the diverse physical deployment methods required for fiber optic infrastructure.
End User:
End-user segments define the specific network architectures and performance demands placed upon fiber optic cable solutions, driving specialization in product design.
- Telecommunications:This segment encompasses long-haul, metropolitan, and access networks for voice, data, and video services, demanding vast quantities of fiber for backhaul and FTTH deployments. 5G network densification and national broadband initiatives globally are significant drivers.
- Data Centers:Hyperscale and enterprise data centers require high-density, high-bandwidth fiber optic cables for inter-rack, inter-cabinet, and inter-building connectivity. The continuous expansion of cloud services by providers like Google and Amazon fuels this segment's demand.
- Enterprises:Corporate campuses, office buildings, and industrial facilities utilize fiber optic cables for local area networks (LANs) and secure internal communications. This segment requires reliable, fire-safe cabling solutions.
- Government:Public sector applications include critical infrastructure monitoring, defense networks, smart city initiatives, and public safety communications. These deployments often prioritize security and long-term reliability.
The varied requirements of these end-user groups drive innovation in fiber optic cable design and deployment.
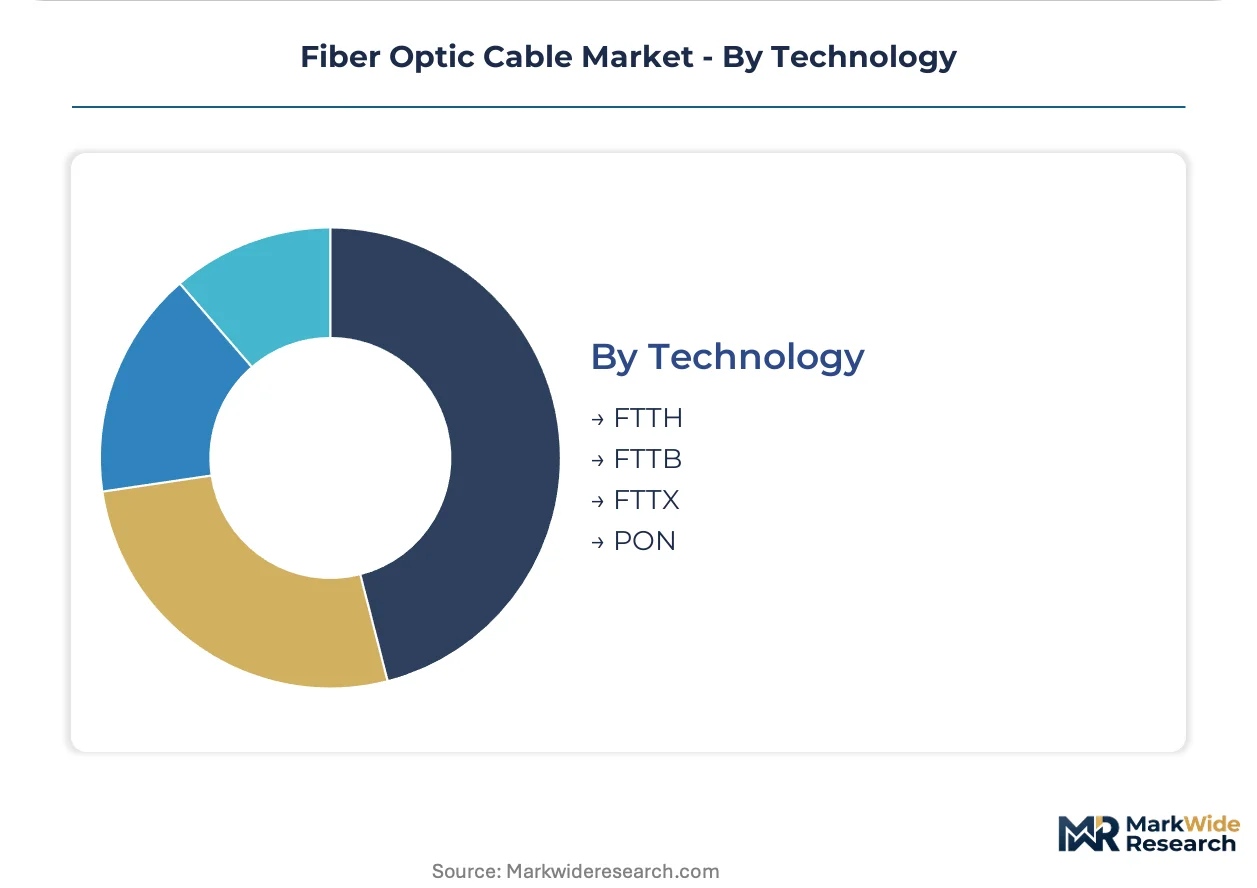
Technology:
The technology segment reflects the architectural approaches employed for delivering fiber optic connectivity to end-points, impacting deployment efficiency and service delivery models.
- FTTH:Fiber-to-the-Home delivers optical fiber directly to individual residences, providing the highest bandwidth and most reliable internet connection. National broadband programs, including those in the US and Indonesia, are accelerating FTTH rollouts.
- FTTB:Fiber-to-the-Building extends fiber optic cables to the basement or communication room of a multi-dwelling unit or commercial building. This approach serves multiple users within a single structure efficiently.
- FTTX:This is a generic term encompassing various fiber deployment architectures where 'X' denotes the specific termination point, such as home, building, curb, or node. It offers flexibility in network design and deployment strategy.
- PON:Passive Optical Network technology uses a single optical fiber to serve multiple endpoints without active electronic components between the central office and the customer. This cost-effective solution is gaining share fastest for residential and small business deployments.
Technological advancements in this segment are continuously improving the efficiency and reach of fiber optic networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta, Indonesia, leads regional investment in foundational digital infrastructure, driven by ambitious national broadband initiatives. These programs aim to bridge the digital divide and connect underserved populations across the archipelago. The significant government spending on fiber deployment creates sustained demand for outdoor and burial cable solutions.
Indonesia
National digital infrastructure programs are creating substantial, long-term demand for terrestrial fiber optic cable deployment to connect underserved communities. The country's Ministry of Communication and Information Technology supports extensive fiber rollouts. Major cities like Surabaya and Bandung are experiencing rapid expansion of FTTH networks to meet urban connectivity needs.
United States
Hyperscale data center expansion and the BEAD program are driving significant demand for both single-mode and multi-mode fiber. The US BEAD program mandates extensive fiber deployment, setting performance criteria for new infrastructure. Key technology hubs such as Silicon Valley and Northern Virginia continue to see robust fiber infrastructure build-outs for cloud services.
China
Massive production scale primarily serves the Chinese domestic market, with substantial fiber deployment for 5G network densification and FTTH. Adherence to national GB standards is essential for all fiber optic cable products. Major manufacturing centers like Wuhan anchor global fiber preform and cable production.
Germany
Data center growth and industrial automation initiatives are fueling demand for high-performance fiber optic cables. The EU's Construction Products Regulation (CPR) mandates specific fire safety ratings for indoor installations. Frankfurt, a major European data center hub, requires continuous fiber upgrades to support its digital economy.
India
National broadband initiatives and 5G network densification are accelerating fiber optic cable deployment across urban and rural areas. The National Broadband Mission aims to provide universal broadband access, supporting extensive FTTH rollouts. Bengaluru, a significant IT hub, drives demand for high-density fiber within its enterprise and data center segments.
Fiber Optic Cable Market Key Industry Players
Premium-margin players sit above commodity-margin players across material science innovation and production scale. The market structure exhibits a tiered consolidation, with a few integrated giants dominating high-value segments. Strategic archetypes include specialized technology leaders, broad portfolio providers, and mass-market producers. Capacity expansion and portfolio diversification represent dominant competitive moves.
Corning Incorporated exemplifies a specialized technology leader, leveraging deep material science expertise to dominate the premium single-mode fiber segment. Prysmian S.p.A. occupies a position as a broad portfolio provider, competing across energy, telecom, and subsea applications. YOFC (Yangtze Optical Fibre and Cable Joint Stock Limited Company) anchors the mass-market production archetype, primarily serving the Chinese domestic market with massive scale.
| Leading Market Players |
|---|
| YOFC |
| CommScope |
| Prysmian |
| Hengtong Group |
| Nexans |
| Corning |
| Furukawa Electric |
| LS Cable & System |
| Sumitomo Electric |
| Others |
Cost & Logistics Intelligence
Optical preform prices, a critical raw material for fiber optic cables, directly influence manufacturing costs. This foundational material cost impacts final tiered pricing structures for both specialized and commodity-grade cables.
Pricing Analysis
Throughput and uptime guarantees anchor pricing for premium fiber optic cables, particularly in data center and subsea applications. The market exhibits a three-tier pricing structure across premium, standard, and economy levels, driven by performance specifications like single-mode capability and adherence to regulatory certifications such as the EU's CPR. Pricing softness affects commodity-grade terrestrial cables due to massive production scale from players like YOFC. Hyperscale data centers demonstrate lower price sensitivity for high-density solutions, while government-led broadband initiatives prioritize cost-effectiveness for extensive terrestrial deployments.
Supply Chain Analysis
Logistics and freight costs significantly influence the final delivered price of fiber optic cables, especially for bulk terrestrial deployments. The global supply of optical preforms, a critical raw material, concentrates heavily in China, the United States, and Japan. This concentration creates a structural risk of optical preform scarcity and price volatility for cable manufacturers worldwide. Distribution runs primarily through direct sales channels to major telecommunications providers and hyperscale data center operators, supplemented by regional distributor networks for enterprise clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fiber Optic Cable Market is increasingly a cost-of-compliance story, with regulations like the EU's Construction Products Regulation (CPR) creating significant barriers to entry. This regulatory moat favors manufacturers capable of extensive product certification and testing.
For Market Incumbents: Anticipate continued optical preform scarcity by deepening vertical integration into preform manufacturing. Expand production capacity strategically in high-growth developing economies like Indonesia to meet national broadband mandates. Invest in R&D for advanced fiber types such as hollow-core fiber to counter commoditization pressure in standard segments. Prioritize certification investments to navigate divergent regional standards like China's GB standards, maintaining market access and differentiation.
For New Entrants and Emerging Players: Rural African communities represent an underserved buyer archetype with significant long-term potential for foundational digital infrastructure. Target niche markets like fiber sensing applications for industrial monitoring or ultra-low latency hollow-core fiber for financial trading. Focus on Sub-Saharan Africa for direct fiber-to-the-home rollouts, leveraging cost-effective aerial deployment methods. Develop robust, environmentally resilient cable solutions tailored for challenging deployment conditions in these regions.
For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated manufacturers in China with massive production scale, or specialized technology leaders in the United States. The long-term viability of digital infrastructure underpins sustained demand for fiber optic cable over the next decade. Target mid-sized firms with proprietary material science capabilities or strong regional market access in high-growth areas like India. The signal to watch is further consolidation among optical preform producers, indicating potential supply chain control opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Indonesia | Meets substantial, long-term demand from national broadband initiatives in Southeast Asia. |
| R&D in Hollow-Core Fiber | Enables ultra-low latency connections for high-frequency trading and scientific research applications. |
| Vertical Integration into Preforms | Secures critical raw material supply against scarcity and price volatility from key producers. |
| Certification for EU CPR | Ensures market access and compliance for indoor installations within the European Union. |
| Targeted M&A of Regional Specialists | Acquires niche expertise or strengthens distribution networks in specific geographic markets. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, which were then validated through primary interviews. This approach combined insights from telecommunications executives, data center architects, and cable manufacturers' R&D leads. Secondary sources included EU CPR guidelines, US BEAD program documentation, and national GB standards. A rigorous bottom-up and top-down triangulation process ensured data accuracy and market sizing.
Granular modeling across product type, installation type, end-user, and technology segments formed the analytical framework over the projection horizon. This included detailed breakdowns for single-mode versus multi-mode fiber and indoor versus outdoor installations. Compound annual growth rates were derived from historical trends and projected demand drivers. Key industry-specific forecast inputs included hyperscale data center capacity additions and national broadband deployment targets from programs like the US BEAD.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to optical preform supply disruptions and shifts in government broadband funding. These forecasts reflect a set of underlying assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Photonic Crystals Market
Optics
Fiber Optic Receiver Market
Optics
Optical Telephoto Lens Market
Optics
Beam Expanders Market
Optics
Fiber Optic Preform Market
Optics
Asia-Pacific Optical Imaging Market
Optics
India Laser Market
Optics
Global Super Hi Vision Market
Optics
Smartphone Lenses Market
Optics
Optical Measuring Systems Market
Optics
Quartz Glass Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Optical Fiber Market
Optics
Beam Combining Optics Market
Optics
Photonics Market
Optics
Excimer Lasers for DUV Lithography Market