
 Cable Drum Market | 2026-2036
Cable Drum Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Drum Market Intelligence
Direct-to-contractor sales through online platforms is reconfiguring traditional wholesale distribution networks. This shift allows for greater customization and faster delivery for large-scale infrastructure projects. Hildebrandt Group leverages its extensive manufacturing scale to serve large utility clients directly. Conductix-Wampfler differentiates through its integrated systems for mobile electrification, while Hannay Reels specializes in custom-engineered solutions for niche applications in the marine and mining sectors.
A cable drum is a cylindrical spool, often constructed with steel flanges and a barrel, designed for the transportation and storage of electrical wires, fiber optic cables, and ropes. Its primary purpose is to prevent twisting and damage during deployment and handling in industrial environments. Steel cable drums dominate the power transmission application due to their durability and high load capacity. In contrast, wooden and plastic drums represent a significant share in telecommunications and construction projects, where lower weight and cost are prioritized.
International trade in wooden drums is governed by the ISPM 15 standard, requiring heat treatment or fumigation to prevent pest spread. In Europe, the REACH regulation scrutinizes the chemical substances used in plastic drum manufacturing, impacting material selection. Quality and durability standards are often guided by ISO 9001 certification for manufacturers. Navigating the trade-offs between material sustainability, durability, and compliance costs remains a central strategic decision for all market participants.
Market Dynamics
The central dynamic in the cable drum market is the structural tension between the demand for high-durability steel drums for power infrastructure and the escalating pressure for sustainable, lightweight alternatives driven by regulations like the EU's RoHS and corporate ESG mandates.
Growth Catalysts
- Renewable Energy Infrastructure:Global expansion of offshore wind and solar farms necessitates vast quantities of high-voltage cables, directly spurring demand for large-diameter steel and composite drums for transport and installation.
- Grid Modernization in Asia:Power grid upgrades and expansions, particularly in China and India, are a primary demand driver for a high volume of power cable drums to support urbanization and industrial development.
- Fiber Optic Deployment:The rollout of 5G and fiber-to-the-home (FTTH) networks worldwide requires millions of kilometers of fiber optic cable, sustaining demand for smaller, cost-effective plywood and plastic drums.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the price of steel and high-quality timber directly impact manufacturing costs and gross margins, creating pricing instability for both producers and end-users.
- International Trade Regulations:The ISPM 15 standard for wood treatment adds logistical complexity and cost to the cross-border shipment of wooden drums, acting as a friction point in global supply chains.
- Substitution from Reel-less Packaging:For certain low-voltage and communications wires, the adoption of reel-in-box or coiled packaging solutions eliminates the need for a drum, eroding market share in specific segments.
Strategic Opportunities
- Circular Economy Models:Developing drum rental, refurbishment, and buy-back programs creates new revenue streams while addressing customer demand for waste reduction and sustainable asset management.
- Advanced Composite Materials:Investment in R&D for fiber-reinforced plastic or hybrid steel-composite drums can create premium products that offer superior strength-to-weight ratios for niche applications.
- Grid Development in Africa:Emerging national and regional power infrastructure projects across Africa represent a significant, long-term opportunity for drum suppliers as electrification efforts accelerate.
Industry Challenges
- Reverse Logistics Complexity:Managing the efficient and cost-effective collection, return, and storage of large, empty drums from geographically dispersed project sites remains a significant operational hurdle for suppliers.
- Navigating Multi-Regional Compliance:Manufacturers selling globally must harmonize product designs and material choices to meet divergent chemical regulations like Europe's REACH and various national environmental standards.
- Lack of Size Standardization:A persistent lack of universal standards for drum dimensions and arbor hole sizes can lead to equipment incompatibility on job sites, creating friction for contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Drum Market |
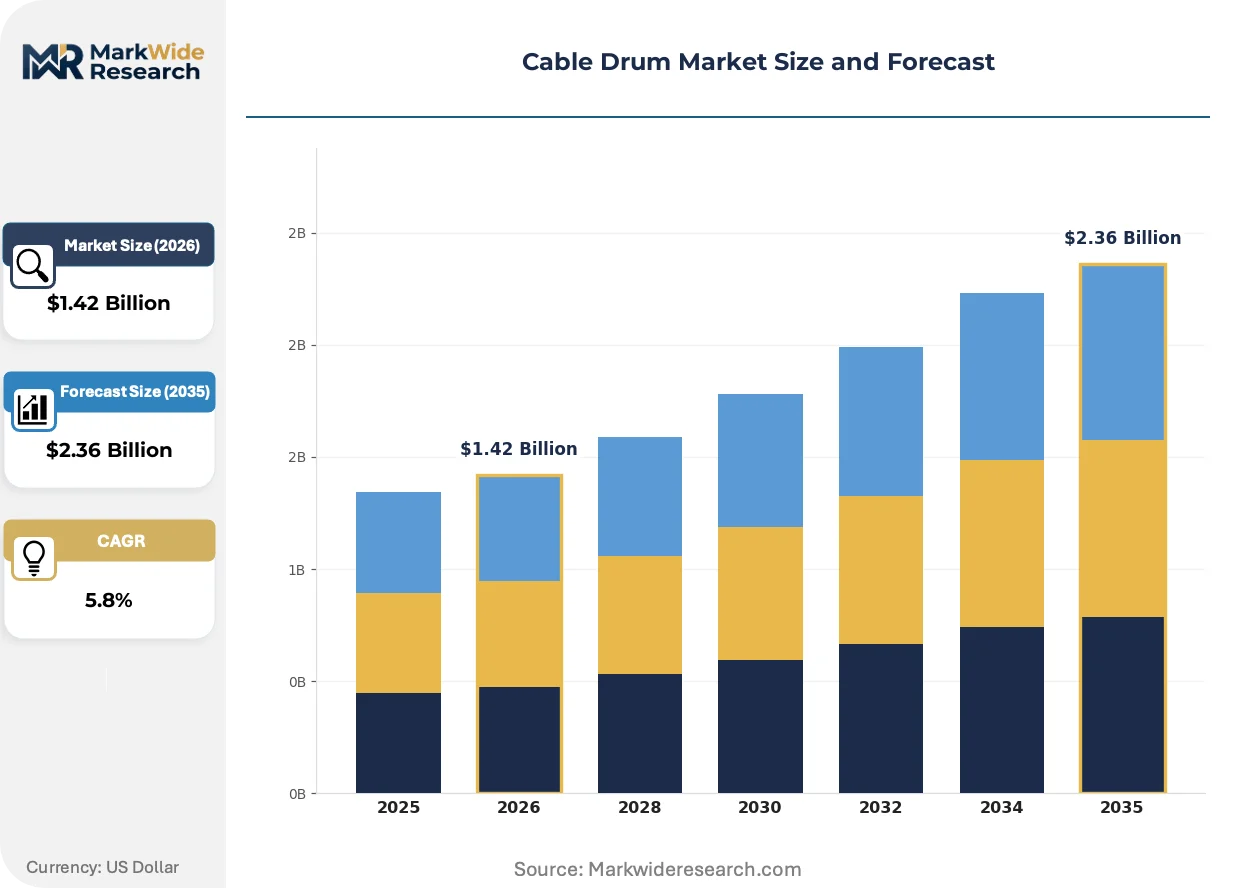
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Cable Drums, Wooden Cable Drums, Plastic Cable Drums, Fiberboard Cable Drums Application: Telecommunications, Power Transmission, Construction Projects, Marine Operations, Renewable Energy Industry Vertical: Utilities, Infrastructure Development, Oil & Gas, Mining, Maritime Transport Distribution Channel: Direct Sales, Distributors, Online Platforms, Wholesalers, OEM Partnerships |
| Companies Covered | Coxreels, Bryant Unlimited, Hildebrandt Group, Cable Equipments, Schwabe GmbH, Schill GmbH & Co. KG, Hannay Reels, Svenssongroup, Conductix-Wampfler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Drum Market Strategic Shifts & Innovations
Material science and business model innovation are concurrently reshaping the market. A pronounced shift toward circularity is compelling manufacturers to rethink product lifecycles, moving from disposable assets to managed, reusable systems in response to regulatory and customer pressures.
Hybrid drums combine materials like steel for structural integrity with recycled plastic or engineered wood for the barrel. Telecommunications and utility contractors are adopting these drums to balance the need for durability during transport with demands for lower weight for easier handling on site. This development is hybridizing the market's distinct material categories, creating a new performance tier between heavy-duty steel and lightweight plastic.
The EU's Corporate Sustainability Reporting Directive (CSRD) is forcing greater transparency in supply chains. This directive requires large companies to report on the environmental impact of their operations, including procured goods like cable drums. This affects wooden drum producers most directly, as they must now provide verifiable data on sustainable sourcing to their clients in the construction and energy sectors.
Large-scale contractors are increasingly favoring rental and asset-management services over the outright purchase of drums for major projects. This shift disrupts traditional distribution channels, creating an advantage for manufacturers that can provide integrated logistics, including drum tracking, collection, and maintenance. This service-based model is gaining traction in North America and Europe, especially for large-scale renewable energy and data center construction.
Cable Drum Market Segmentation
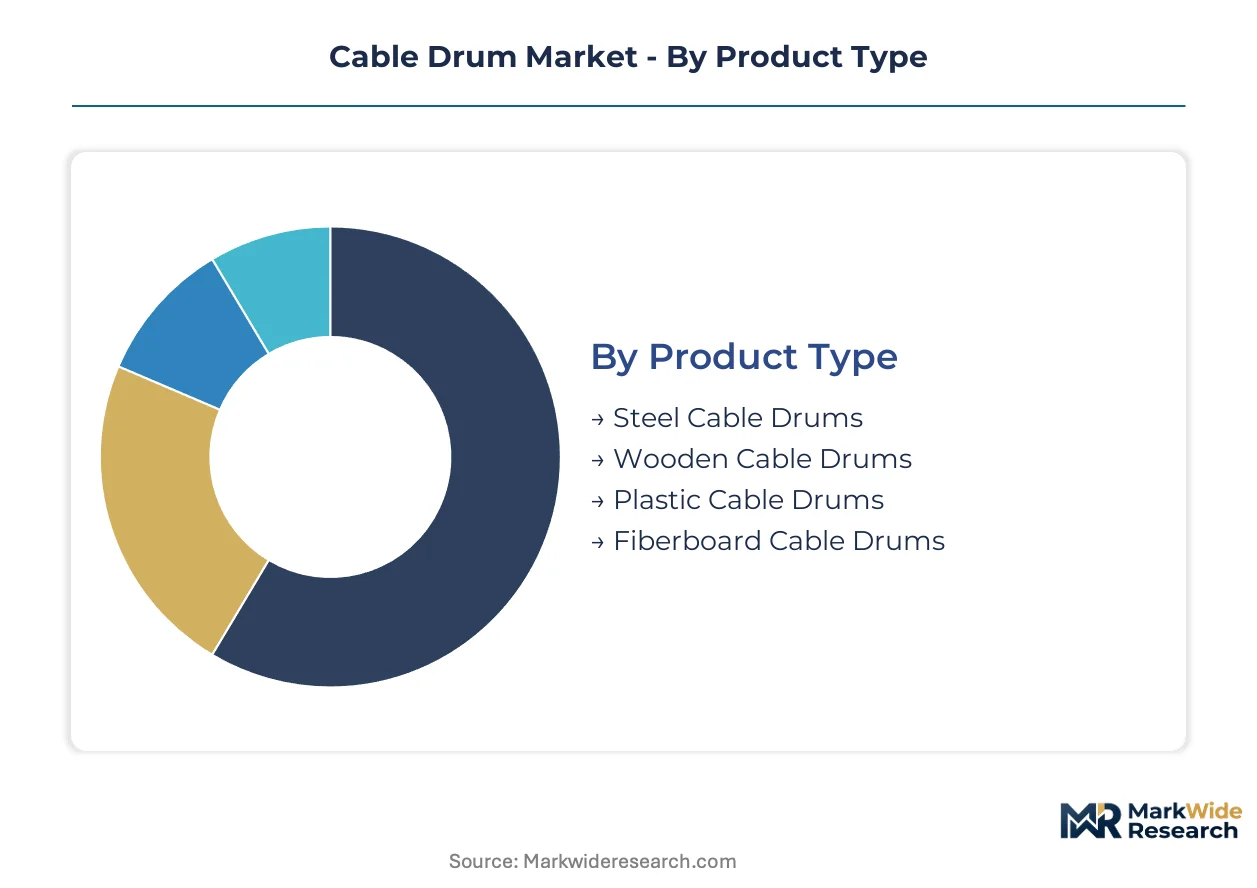
The cable drum market segmentation provides a detailed framework for understanding specific demand patterns and operational requirements across diverse applications. Analyzing these segments clarifies where value accumulates and how different material and distribution choices impact market dynamics. This granular view assists manufacturers in optimizing their product portfolios and refining market entry strategies.
Product Type:
The after-sales service intensity for cable drums varies significantly by product type, reflecting their reusability, repairability, and return logistics. High-durability steel drums require less frequent replacement but more complex reverse logistics, while single-use types have simpler end-of-life considerations.
- Steel Cable Drums:These drums feature robust steel flanges and barrels, providing exceptional durability and high load capacity essential for heavy electrical cables. Demand concentrates in power transmission projects across China and India, driven by extensive grid upgrades requiring long-term infrastructure.
- Wooden Cable Drums:Constructed from timber, these drums offer a cost-effective and lighter solution compared to steel, often used for single-trip applications. Telecommunications and construction projects in Europe prioritize these drums, balancing cost efficiency with material handling requirements.
- Plastic Cable Drums:Lightweight and resistant to moisture, plastic drums are favored for fiber optic deployments and smaller electrical wires.
- Fiberboard Cable Drums:These drums provide an economical option for lighter cables and short-distance transport, minimizing material costs for manufacturers.
Steel Cable Drums hold the largest share; momentum sits with Plastic Cable Drums.
Application:
Cost tiering across cable drum applications reflects the required durability, size, and material specifications for different deployment environments. High-stress applications, such as subsea installations, demand premium-priced, high-performance drums.
- Power Transmission:This segment demands large-diameter, high-durability steel drums for transporting heavy, high-voltage electrical cables over long distances. Grid modernization efforts in Asia, particularly China, represent a substantial driver for these robust drums.
- Renewable Energy:Offshore wind farms and large-scale solar installations necessitate specialized, often composite, drums for vast quantities of high-voltage inter-array and export cables. European projects, such as those in the North Sea, drive specific demand for these heavy-duty solutions.
- Telecommunications:Fiber optic cable rollouts worldwide sustain demand for smaller, lighter wooden and plastic drums.
- Construction Projects:General construction requires a mix of wooden and plastic drums for various electrical and data cabling needs on job sites.
- Marine Operations:Specialized drums support subsea cable laying and retrieval in offshore energy and communication projects.
Power Transmission consistently drives the highest volume; Renewable Energy is expanding most quickly.
Industry Vertical:
Volume requirements for cable drums differ significantly across industry verticals, influenced by project scale and cable infrastructure density. Utilities consistently require high volumes for widespread network development, while mining has more localized but intensive needs.
- Utilities:Power utilities require vast quantities of steel drums for grid expansion, maintenance, and high-voltage transmission lines. National grid operators in Germany and the US frequently procure large drum orders for their infrastructure projects.
- Infrastructure Development:This vertical encompasses telecommunications, transportation, and urban development projects, driving demand for diverse drum types, including wooden and plastic. Major fiber-to-the-home initiatives in France and the UK contribute significantly to this segment.
- Oil & Gas:Offshore platforms and pipeline projects utilize specialized drums for power and control cables in harsh environments.
- Mining:Mining operations demand robust drums for heavy-duty power cables used in excavation and material handling equipment.
- Maritime Transport:Shipping companies and port operators use drums for various onboard electrical and mooring cable applications.
Utilities represent the largest consumer base; Infrastructure Development shows consistent, high-volume procurement.
Distribution Channel:
Customer type dictates the preferred distribution channels, with large-scale clients often favoring direct engagement while smaller buyers use intermediaries. Project complexity and order volume also influence channel selection.
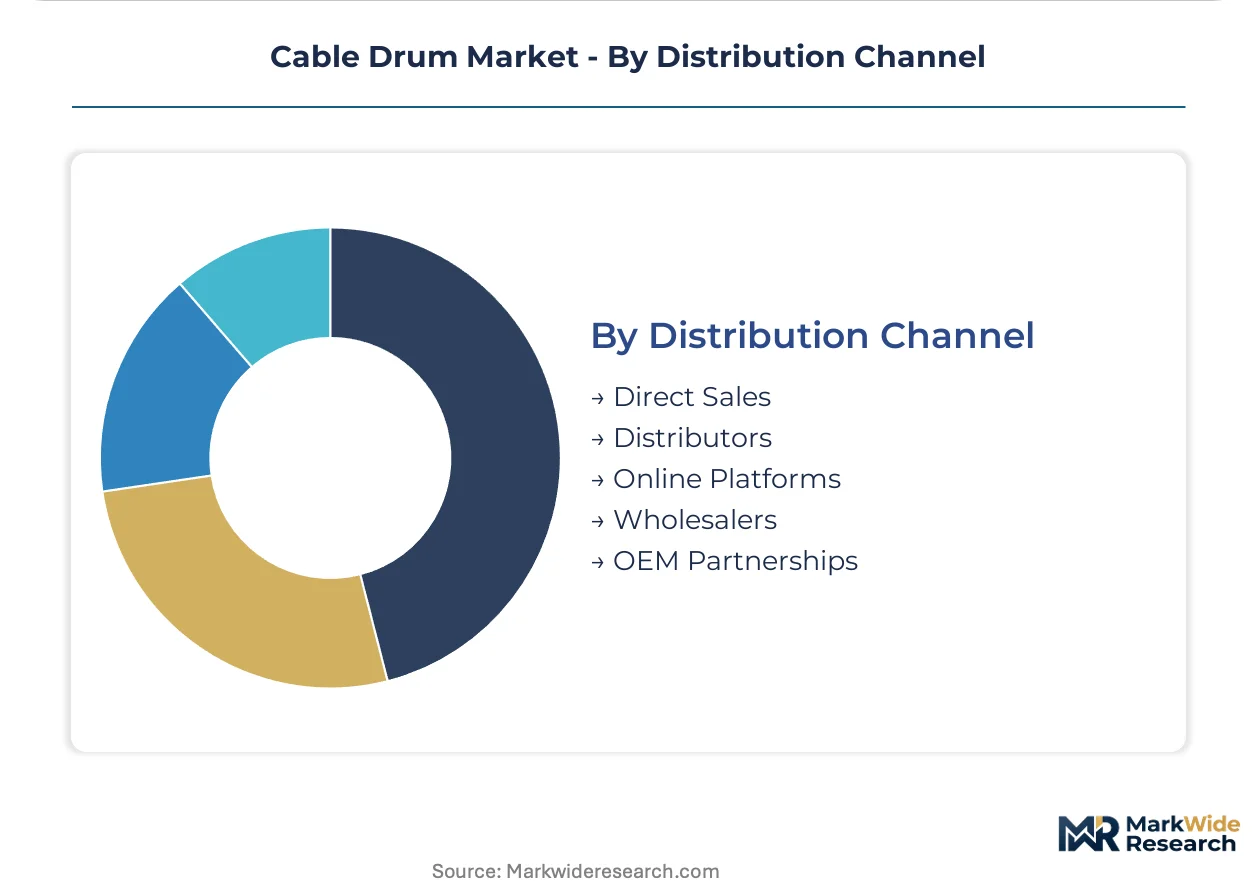
- Direct Sales:Manufacturers engage directly with large utility companies and major infrastructure contractors for customized solutions and high-volume orders. Hildebrandt Group exemplifies this model by serving significant utility clients without intermediaries.
- Online Platforms:E-commerce platforms facilitate direct-to-contractor sales, offering customization and faster delivery for specific project needs. This channel is gaining traction in North America for construction and telecommunications contractors.
- Distributors:Regional distributors serve a broad base of smaller contractors and local projects, providing inventory and logistical support.
- Wholesalers:Wholesalers aggregate products from multiple manufacturers, offering a wide selection to retailers and smaller industrial buyers.
- OEM Partnerships:Drum manufacturers collaborate with cable producers as original equipment manufacturers, integrating drums into the cable supply chain.
Direct Sales account for the majority of high-value transactions; Online Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global grid interconnects and renewable energy pipelines significantly influence regional cable drum demand. Extensive power infrastructure projects in China and India drive high-volume procurement of robust steel drums. European offshore wind installations necessitate specialized composite drums for vast cable quantities.
China
China's extensive power grid upgrades and urbanization projects spur demand for steel cable drums. The national GB standards mandate specific quality and safety requirements for all electrical infrastructure components. Industrial zones like the Yangtze River Delta concentrate manufacturing and deployment activities for power transmission lines.
India
India's rapid industrial development and ambitious electrification efforts create sustained demand for power cable drums. The Central Electricity Authority (CEA) guidelines shape procurement specifications for utility-scale projects. Major infrastructure hubs such as Mumbai and Delhi drive significant demand for both power and telecommunication cable drums.
Germany
German offshore wind farm development and advanced telecommunications networks require high-performance cable drums. European Union directives like RoHS influence material selection for plastic and composite drum manufacturing. The North Sea coastal regions are central to the deployment of specialized drums for subsea power cables.
United States
Utility modernization programs and widespread fiber optic deployments drive substantial cable drum consumption across the United States. Federal Energy Regulatory Commission (FERC) regulations impact the handling and installation of high-voltage transmission cables. Major urban centers like New York and Los Angeles exhibit high demand for diverse drum types.
Australia
Australia's growing renewable energy sector and mining operations generate demand for durable cable drums. The national TGA standards sometimes apply to materials used in industrial equipment, including drums. Western Australia's mining regions are significant consumers of heavy-duty drums for power and control cables.
Cable Drum Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing essential drum solutions. The cable drum market exhibits a tiered structure, ranging from generalist manufacturers to highly specialized solution providers. Key archetypes include large-scale producers leveraging manufacturing scale and niche players focusing on custom-engineered solutions. Competitive moves primarily involve strategic partnerships with cable manufacturers and continuous investment in advanced material R&D.
Specialists in custom-engineered solutions occupy a significant market position, exemplified by Hannay Reels, which provides tailored offerings for niche marine and mining applications. These companies leverage deep domain expertise to meet precise customer requirements. Hildebrandt Group, with its extensive manufacturing scale, represents a model for serving large utility clients directly, bypassing traditional intermediaries and managing high-volume orders efficiently. Conductix-Wampfler further differentiates itself through integrated systems for mobile electrification, showcasing a focus on application-specific drum designs and comprehensive solutions for complex industrial environments.
| Leading Market Players |
|---|
| Coxreels |
| Bryant Unlimited |
| Hildebrandt Group |
| Cable Equipments |
| Schwabe GmbH |
| Schill GmbH & Co. KG |
| Hannay Reels |
| Svenssongroup |
| Conductix-Wampfler |
| Others |
Cost & Logistics Intelligence
China's extensive steel and timber production for cable drums directly influences where margin pools accumulate across various downstream applications. This concentration affects pricing power for both producers and end-users.
Pricing Analysis
Volume-based discounts significantly shape pricing dynamics, with large utility clients securing more favorable rates through long-term contracts. Price differentiation stems from material quality certifications like ISO 9001 and the level of customization required for specialized drums. Pricing softness affects standard wooden and plastic drums due to raw material price volatility for timber and plastics. Telecommunications and construction contractors exhibit higher price sensitivity compared to power transmission and renewable energy project developers.
Supply Chain Analysis
International trade regulations, such as the ISPM 15 standard for wood treatment, introduce logistical friction and cost to cross-border drum shipments. Geographic supply concentration centers on China and India for steel drums and Europe for specialized plastic and composite drums. The market draws from raw material dependencies including steel, high-quality timber, and recycled plastics. Commodity price volatility for these inputs represents a structural supply chain risk. Distribution runs through direct sales channels for major clients and online platforms gaining traction for direct-to-contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cable drum market is a defensive moat story, primarily due to the regulatory entrenchment of product standards and the high switching costs associated with equipment compatibility on job sites.
For Market Incumbents:Harden existing client relationships by expanding circular economy initiatives, offering drum rental, refurbishment, and buy-back programs. Invest in advanced composite materials R&D to counter substitution from reel-less packaging in specific segments. Strengthen direct sales and logistics capabilities to serve large utility clients efficiently, leveraging ISO 9001 certification for quality assurance. Enhance sustainable sourcing practices to meet directives like the EU's CSRD, mitigating regulatory threats.
For New Entrants and Emerging Players:Pursue white-space opportunities in emerging markets, particularly focusing on grid development projects across Africa. Target the telecommunications and construction segments with lighter, cost-effective plywood and plastic drums. Differentiate through specialized online platforms offering enhanced customization and faster delivery for specific project needs. Focus on niche applications requiring custom-engineered solutions, such as those in the marine and mining sectors.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-sized specialists in advanced materials or logistics-integrated service providers. The market exhibits long-term viability, underpinned by global infrastructure development and renewable energy expansion. Seek acquisition targets with strong intellectual property in composite drum technology or established circular economy models. A significant uptick in patents for fiber-reinforced plastic drums or widespread adoption of drum rental services would signal a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Circular Economy Programs | Creates new revenue streams while addressing customer demand for waste reduction. |
| Invest in Composite Material R&D | Develops premium products offering superior strength-to-weight ratios for niche applications. |
| Deepen Direct-to-Client Logistics | Enhances service for large utility clients, bypassing traditional distribution intermediaries. |
| Standardize Drum Dimensions | Reduces equipment incompatibility on job sites, improving contractor efficiency. |
| Strengthen Sustainable Sourcing | Meets EU's CSRD requirements, ensuring verifiable data on environmental impact. |
Research Approach
The analysis maps critical sub-sectors including power transmission, telecommunications, and construction, each validated through primary interviews with utility procurement managers, cable manufacturers, and construction project leads. Secondary data sources, such as national energy reports from the EIA and CEA, telecom infrastructure plans, and trade association data, provided comprehensive market insights. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency.
Assumptions regarding global infrastructure spending and renewable energy deployment targets were held constant across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, industry vertical, and regional demand drivers. Compound Annual Growth Rates were derived through a combination of regression analysis and expert consensus. Key forecast inputs included projected global urbanization rates and fiber-to-the-home rollout schedules.
Sensitivities concentrate around raw material price volatility and shifts in international trade regulations. Forecasts reflect these underlying assumptions, acknowledging potential impacts from geopolitical shifts or global economic downturns. Material shifts in global trade policies or significant material science breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Ethernet Converters Market
Cables
Cable Organisers Market
Cables
Underground Cable Market
Cables
Europe HVAC Cables Market
Cables
Magnetic Charging Cable Market
Cables
Mexico Wires and Cables Market
Cables
Data Center Wire and Cable Market
Cables
Cable Market
Cables
Coaxial Cable Market
Cables
LASER Light Cables Market
Cables
Cable Lugs Market
Cables
Hybrid Cables Market
Cables
Fire Resistance Cable Market
Cables
FFC/FPC Jumper Cables Market
Cables
Cable Tags Market
Cables
Cable Management Accessories Market