
 Fiber Optic Preform Market | 2026-2036
Fiber Optic Preform Market Size, Share, and Industry Trends Forecast 2026-2036
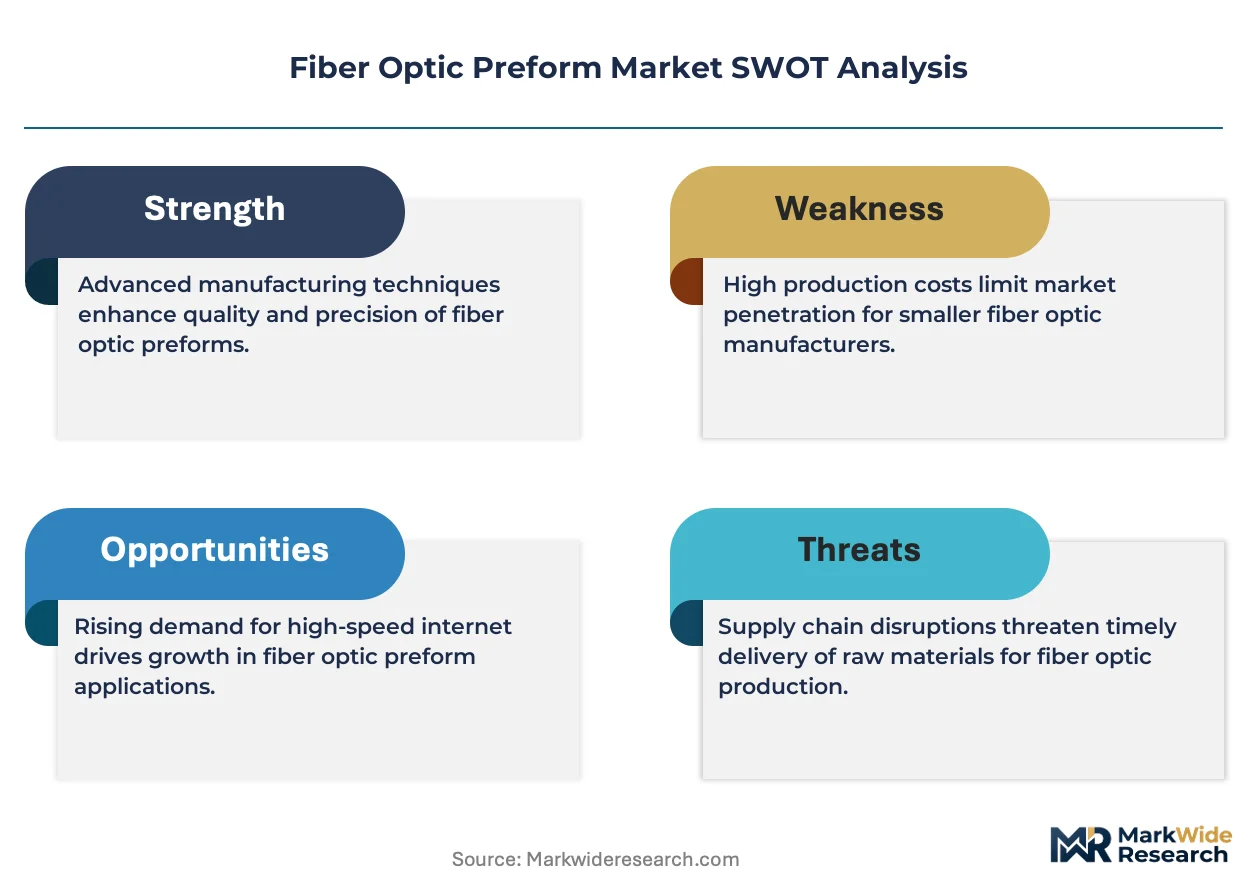
Fiber Optic Preform Market Analysis
Subscription-based fiber network monitoring and software-defined optical layer management is hardening the commercial model around preform supply. Corning Incorporated leverages its captive silica refining and draw tower integration to sustain margin control across the value chain. Furukawa Electric Co., Ltd. anchors Japanese domestic demand while competing aggressively in Southeast Asian submarine cable projects. Hengtong Group Co., Ltd. dominates Chinese state-backed broadband buildouts through massive Wuhan-area manufacturing scale.
A fiber optic preform is a cylindrical glass structure, typically synthesized from high-purity synthetic silica via chemical vapor deposition, that serves as the feedstock for drawing optical fibers with precise refractive index profiles. Specialty preforms command premium positioning due to stringent geometric tolerances required for submarine and aerospace applications, while standard preforms face commoditization pressure despite volume dominance. Material type segmentation reveals silica's entrenched position in long-haul networks, with polymer alternatives carving niche roles in medical and short-reach sensing.
FDA oversight of fiber-based medical devices and China's GB standards enforced by SAMR shape product certification pathways, while REACH compliance in Europe restricts certain dopant chemistries used in preform fabrication. The EU AI Act and CSRD disclosure rules will increasingly govern how automated preform inspection systems are deployed and reported. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's embodied carbon tracking requirements, as these frameworks will reshape supplier qualification criteria and capital allocation decisions across the preform supply base.
Market Dynamics
Telecom carriers in Southeast Asia are accelerating submarine cable deployments while China's MIIT enforces stricter optical fiber quality standards, creating simultaneous demand pull and compliance pressure across the preform supply base.
Growth Catalysts
- Submarine cable infrastructure:Telecom carriers across Southeast Asia are commissioning new undersea routes linking Singapore, Indonesia, and the Philippines. These projects require specialty preforms with ultra-precise geometric tolerances.
- GB standard enforcement:China's SAMR and MIIT implementation of revised GB specifications for optical fiber quality is forcing network operators to source certified preforms, eliminating sub-tier suppliers.
- Silica deposition advances:Modified chemical vapor deposition and plasma chemical vapor deposition processes are reducing defect rates in large-diameter preforms, extending yield economics for long-haul fiber production.
Market Restraints
- High-purity silica feedstock concentration:Synthetic silica supply concentrates among a handful of specialized chemical refiners, creating input cost volatility when semiconductor and optical markets compete for the same material grades.
- Capital intensity barrier:Preform manufacturing requires chemical vapor deposition systems and precision draw towers that demand significant upfront investment, limiting new entrant participation.
- REACH dopant restrictions:ECHA regulations in Europe constrain certain germanium and fluorine dopant chemistries used in refractive index profiling, complicating formulation for EU-bound preform shipments.
Strategic Opportunities
- Medical fiber sensing:Polymer-based preforms for short-reach medical and industrial sensing applications remain underdeveloped relative to silica dominance, offering niche premium positioning.
- EU Green Deal alignment:Preform suppliers demonstrating embodied carbon tracking and low-chemical deposition processes can qualify for preferential procurement under the EU Green Deal's supplier qualification frameworks.
- Software-defined optical layer integration:Preform-to-fiber vendors bundling network monitoring subscriptions with physical supply are capturing recurring revenue streams beyond commodity fiber sales.
Industry Challenges
- Specialized deposition technician scarcity:Chemical vapor deposition process engineering and plasma control expertise pools remain shallow relative to expansion needs, particularly for large-diameter preform production.
- Multi-jurisdiction certification lag:Preform suppliers must simultaneously satisfy FDA 510(k) pathways for medical fiber devices, MIIT GB compliance for China telecom networks, and REACH dossier requirements for European chemical registration.
- Legacy draw tower integration:Fiber drawing facilities with aging tower infrastructure face compatibility constraints when upgrading to next-generation preform geometries, forcing phased capital replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Preform Market |
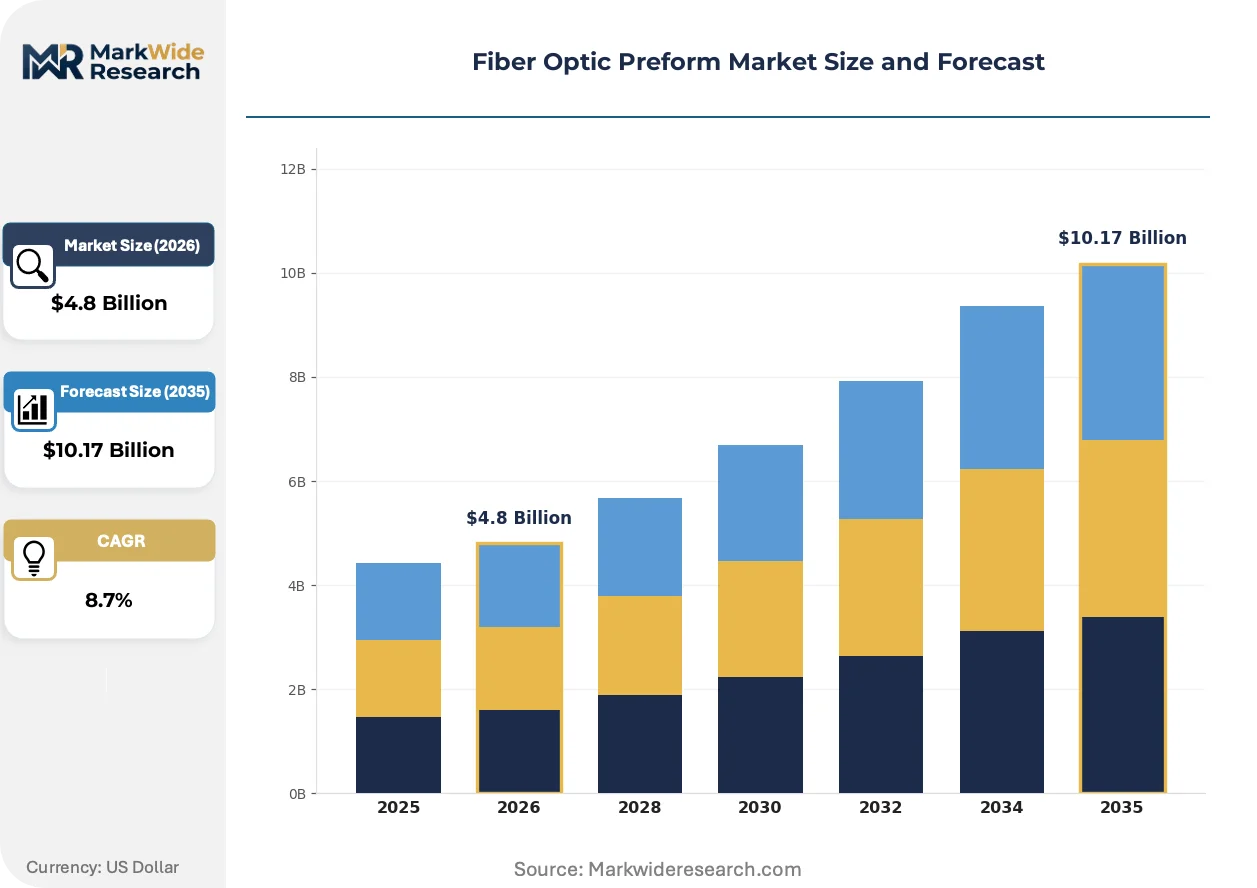
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Preform, Cladding Preform, Specialty Preform, Standard Preform Material Type: Silica, Plastic, Glass, Polymer Manufacturing Process: MCVD, OVD, VAD, Rod-to-Preform End User: Telecommunication, Data Centers, Military, Healthcare |
| Companies Covered | Yangtze Optical Fibre and Cable Joint Stock Limited Company, Furukawa Electric Co., Ltd., Corning Incorporated, Sterlite Technologies Limited, Sumitomo Electric Industries, Ltd., Prysmian Group, Fujikura Ltd., Heraeus Holding, Hengtong Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Preform Market Emerging Trajectories
Automation of preform inspection and deposition control is compressing defect rates while regulatory frameworks in Europe and Asia reshape chemical compliance and carbon disclosure obligations across the supply chain.
AI-driven optical inspection systems are automating defect detection in preform manufacturing. Tier-one fiber producers in Japan and Germany are deploying machine vision at deposition and draw stages to catch refractive index anomalies before fiber drawing. This technology is automating quality assurance labor while enabling real-time process adjustment that reduces material waste.
REACH compliance in Europe and China's dual carbon goals are converging to restrict traditional dopant chemistries and energy-intensive deposition methods. The EU AI Act and CSRD disclosure rules now govern how automated inspection data is reported and audited. Submarine cable preform suppliers serving European routes face the steepest compliance burden as they must satisfy both chemical registration and AI system transparency requirements.
Subscription-based network monitoring is unbundling from hardware procurement in telecom carrier relationships. Buyers in Southeast Asia and coastal China are shifting from capital-intensive fiber purchases toward service contracts bundling preform supply with performance guarantees. This model concentrates purchasing power among carriers with scale to negotiate multi-year monitoring agreements, pressuring smaller fiber producers to adopt similar service architectures or exit tier-one supplier lists.
Fiber Optic Preform Market Segmentation
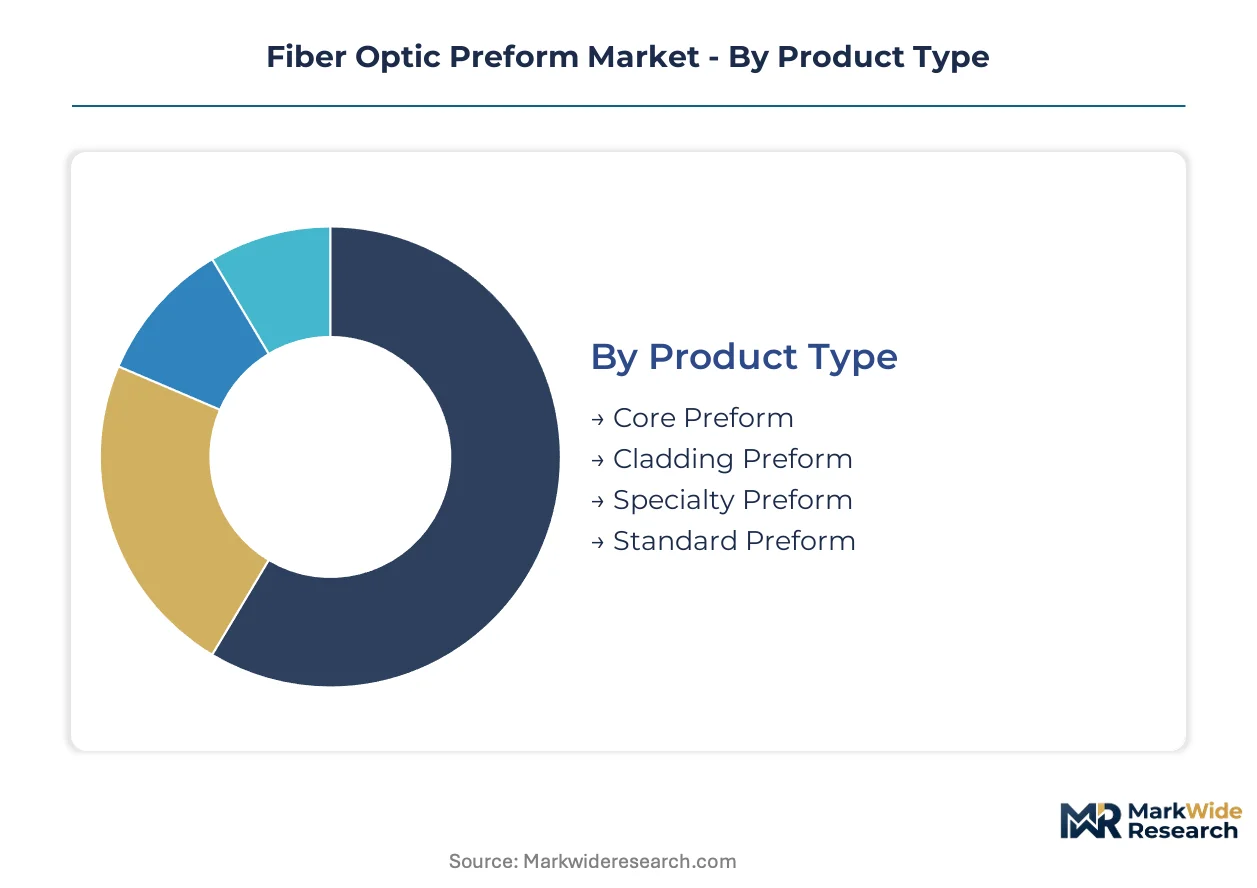
Preform segmentation reveals how supply chain configuration, deposition technology maturity, and end-use certification requirements fragment manufacturing economics. Each category channels capital toward distinct capability investments and regulatory compliance pathways.
Product Type:
Supply concentration in specialty and core preforms concentrates margin capture among deposition specialists with captive silica refining, while standard and cladding variants face commoditization from Chinese volume producers.
- Specialty Preform:Engineered for ultra-precise geometric tolerances through modified chemical vapor deposition with dopant gradient control. Submarine cable projects linking Singapore, Indonesia, and the Philippines absorb the bulk of output, with MIIT GB certification now mandatory for China telecom networks. Demand concentrates in coastal Chinese manufacturing clusters where preform-to-fiber vertical integration dominates supply.
- Core Preform:The central glass structure defining refractive index profiles via germanium or fluorine doping. Telecom carriers in Southeast Asia commission new undersea routes requiring certified core geometries, while REACH compliance in Europe constrains certain dopant chemistries for EU-bound shipments.
- Cladding Preform:Surrounds the core with lower-index glass to enable total internal reflection. Volume production concentrates in Wuhan-area facilities serving domestic Chinese broadband buildouts.
- Standard Preform:Generic cylindrical structures for conventional fiber drawing. Price pressure intensifies as deposition yield improvements compress manufacturing economics.
Today's leader: Specialty Preform. Tomorrow's challenger: Core Preform.
Material Type:
Cost tier stratification separates high-purity silica commanding premium positioning from polymer alternatives carving niche medical applications.
- Silica:Synthetic silica synthesized via chemical vapor deposition dominates long-haul networks with entrenched performance credentials. Semiconductor and optical markets compete for identical material grades from specialized chemical refiners, amplifying input cost volatility.
- Polymer:Flexible substrates for short-reach medical and industrial sensing applications. FDA 510(k) pathways for fiber-based medical devices shape product certification timelines.
- Plastic:Lower-cost alternatives for disposable sensing configurations with limited thermal tolerance.
- Glass:Borosilicate formulations for specialized optical components outside telecom mainstream.
Silica retains volume dominance. Polymer climbs fastest in medical fiber sensing.
Manufacturing Process:
Volume scale and yield economics concentrate investment in vapor deposition variants, while rod-to-preform methods serve legacy infrastructure constraints.
- MCVD:Modified chemical vapor deposition deposits silica layers inside a rotating quartz tube with precise dopant control. Japanese and German tier-one producers deploy machine vision at deposition stages to catch refractive index anomalies before fiber drawing.
- VAD:Vapor-phase axial deposition builds preforms from the bottom upward, enabling large-diameter production with reduced defect rates. Southeast Asian submarine cable suppliers favor VAD for specialty preform geometries requiring ultra-precise tolerances.
- OVD:Outside vapor deposition deposits soot layers externally before sintering into solid glass.
- Rod-to-Preform:Legacy method combining separate core and cladding rods, constrained by aging draw tower infrastructure compatibility.
MCVD anchors current capacity. VAD gains share in submarine cable qualification.
End User:
Customer type fragmentation channels preform supply toward distinct certification regimes: telecom carriers negotiate service contracts while military and healthcare buyers demand traceable quality documentation.
- Telecommunication:Carriers across Southeast Asia shift from capital-intensive fiber purchases toward subscription-based network monitoring bundled with preform supply. China's MIIT enforces stricter GB specifications, eliminating sub-tier suppliers from state-backed broadband buildouts.
- Data Centers:Hyperscale facilities in Singapore and coastal China drive demand for high-fiber-count cables requiring precise preform geometries.
- Military:Hardened fiber for aerospace and defense applications commands premium positioning through stringent geometric tolerances.
- Healthcare:Fiber-based medical devices face FDA oversight with 510(k) pathways shaping product certification timelines.
Telecommunication captures current volume. Healthcare represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands manufacturing scale advantages while Japan maintains deposition technology leadership, creating divergent competitive positions across the preform supply base.
China
State-backed broadband buildouts drive volume absorption through coastal manufacturing clusters. MIIT enforces revised GB specifications for optical fiber quality, eliminating uncertified suppliers from procurement lists. Wuhan-area facilities anchor domestic production capacity with preform-to-fiber integration serving state-owned carriers.
Japan
Domestic telecom infrastructure and submarine cable exports sustain specialty preform demand. METI oversees industrial standards alignment with international submarine project requirements. Nagoya and Osaka metropolitan areas concentrate deposition technology development with machine vision integration at manufacturing stages.
United States
Hyperscale data center expansion and defense aerospace applications command premium preform positioning. FDA oversees fiber-based medical device pathways while FCC regulations govern telecom network equipment certification. Corning, New York anchors captive silica refining with integrated draw tower operations.
Germany
Industrial automation and automotive fiber sensing create niche demand for precision preform geometries. ECHA REACH regulations constrain germanium and fluorine dopant formulations for EU-bound shipments. Bavarian and Baden-Württemberg industrial corridors host tier-one producers deploying automated inspection systems.
South Korea
Semiconductor manufacturing proximity drives demand for high-purity silica feedstock competing with optical applications. MFDS regulates medical device fiber components while national broadband initiatives sustain telecom preform consumption. Seoul Capital Area concentrates deposition equipment engineering talent pools.
Fiber Optic Preform Market Vendor Landscape
Top-tier vendors anchor premium specialty preform supply, while mid-scale fabricators compete on volume throughput for standard geometries. The market exhibits tiered concentration with deposition technology specialists commanding margin capture against commodity-oriented volume producers. Strategic archetypes separate captive silica refiners with backward integration, pure-play deposition houses, and diversified cable manufacturers with in-house preform capacity. Competitive moves center on M&A consolidation of specialty deposition assets and strategic partnerships bundling preform supply with network monitoring subscriptions.
Among Japanese and American diversified industrials, Furukawa Electric Co., Ltd., Corning Incorporated, and Sumitomo Electric Industries, Ltd. exemplify tier-one positioning through integrated value chain control. Yangtze Optical Fibre and Cable Joint Stock Limited Company and Hengtong Group Co., Ltd. represent Chinese state-aligned scale producers competing on domestic volume capture. Sterlite Technologies Limited and Prysmian Group occupy positions as cable-centric manufacturers with selective preform backward integration strategies.
| Leading Market Players |
|---|
| Yangtze Optical Fibre and Cable Joint Stock Limited Company |
| Furukawa Electric Co., Ltd. |
| Corning Incorporated |
| Sterlite Technologies Limited |
| Sumitomo Electric Industries, Ltd. |
| Prysmian Group |
| Fujikura Ltd. |
| Heraeus Holding |
| Hengtong Group Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
High-purity synthetic silica feedstock moves from specialized chemical refiners through three pricing tiers shaped by deposition yield, certification grade, and captive integration depth. Semiconductor and optical market competition for identical material grades amplifies input cost volatility that compresses margins at standard preform tiers while preserving premium positioning for specialty geometries.
Pricing Analysis
Capacity additions in Wuhan-area manufacturing clusters are reshaping price floors for standard preform geometries while specialty tiers hold firm. Three-tier pricing structure across premium, standard, and economy levels separates MIIT GB-certified submarine cable preforms from domestic broadband variants and undifferentiated commodity supply. Pricing pressure stems from yield improvements in VAD and MCVD processes that extend manufacturing economics to larger-diameter formats. Telecom carriers with scale to negotiate multi-year monitoring bundles exhibit lowest price sensitivity, while small fiber producers without backward integration face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with synthetic silica refiners concentrated in Germany, Japan, and coastal China where semiconductor and optical demand compete for identical grades. Preform fabrication draws from high-purity silica, germanium dopants, and fluorine compounds subject to ECHA REACH restrictions on EU-bound shipments. Regulatory restriction on dopant chemistries compounds tariff exposure from equipment imports. Distribution runs through preform-to-fiber integrated facilities serving state-owned carriers and submarine cable consortiums directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's state-backed broadband buildouts and Europe's carbon disclosure requirements, with compliance cost differentials exceeding manufacturing labor spreads.
For Market Incumbents: Lock in silica refining capacity through long-term offtake agreements with German and Japanese chemical refiners before semiconductor demand tightens feedstock allocation. Defend position by accelerating MIIT GB certification for Wuhan-area capacity additions that eliminate sub-tier Chinese competitors from state procurement lists. Backward integration into captive deposition equipment engineering pools in Nagoya and Seoul Capital Area deepens technician scarcity barriers against emerging entrants. For New Entrants and Emerging Players: Capture polymer-based preform white space in FDA 510(k) medical fiber pathways where silica dominance has left short-reach sensing applications underdeveloped. Medical fiber sensing represents the most penetrable segment given shallow incumbent R&D investment and premium pricing tolerance from device manufacturers. A go-to-market angle bundling preform supply with sterilization-compatible packaging and regulatory submission support differentiates against commodity silica suppliers lacking healthcare certification expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale deposition houses lack captive silica refining and face REACH compliance cost escalation without the scale to absorb chemical registration burdens. Long-term viability favors specialists with dual certification in MIIT GB and FDA 510(k) pathways that unlock both Chinese telecom and US medical device demand pools. Acquisition target archetype: Japanese or German tier-two MCVD specialists with machine vision integration and dormant EU customer relationships. Watch submarine cable project award announcements linking Singapore, Indonesia, and Philippines as inflection indicator for specialty preform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silica Refining Expansion | Secures feedstock allocation against semiconductor demand competition from Heraeus and Corning New York operations. |
| MCVD Machine Vision Deployment | Japanese tier-one producers in Nagoya reduce defect rates through AI-driven deposition control that automates quality assurance labor. |
| GB Certification Acceleration | Eliminates uncertified Wuhan-area competitors from China state-backed broadband procurement lists under MIIT enforcement. |
| Polymer Preform FDA Pathway | Unlocks medical fiber sensing premiums through 510(k) submission support that silica incumbents underinvest in. |
| Submarine Cable Consortium Partnership | Furukawa and Sumitomo anchor Southeast Asian route awards through ultra-precise geometric tolerance guarantees. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CVD process engineers, telecom carrier procurement directors, submarine cable project managers, and medical device regulatory affairs leads with secondary validation. Primary fieldwork drew from SEC filings of listed fiber producers, MIIT GB standard documentation, ECHA REACH dossiers, and hyperscale data center capex disclosures. Bottom-up preform volume estimates by manufacturing process and geography triangulated against top-down telecom infrastructure investment forecasts.
Historical reference periods anchored the projection horizon to observed deposition yield improvements, certification timeline compression, and silica feedstock price volatility patterns. Segmentation dimensions modeled include product type tier, material purity grade, manufacturing process variant, and end-use certification regime. CAGRs derived from installed base replacement cycles and greenfield submarine cable commissioning schedules. Industry-specific forecast inputs incorporated MIIT broadband buildout targets and EU Green Deal embodied carbon tracking implementation pace.
Submarine cable project delays, REACH dopant restriction expansion, and semiconductor market silica demand spikes are the dominant revision risks that could compress or extend the projected trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Photonic Crystals Market
Optics
Global Fiber Optic Components Market
Optics
Electro Optics Market
Optics
Europe Laser Interferometer Market
Optics
Optical Imaging Market
Optics
Optical Telephoto Lens Market
Optics
Global Semiconductor Lasers Market
Optics
Fiber Optic Cable Market
Optics
Lasers Market
Optics
Laser Transmitter Market
Optics
Optical Measuring Systems Market
Optics
EUV Pellicle Market
Optics
Photonics Sensor Market
Optics
Collimating Lens Market
Optics
Anomaloscope Market
Optics
Optical Sensing Market