
 United States Cable Accessories Market | 2026-2036
United States Cable Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cable Accessories Market Intelligence
Modular connector-and-termination kits is broadening procurement flexibility for utilities and EPC contractors. Southwire Company leverages its integrated wire-to-accessory manufacturing footprint to control lead times across the Southeast. Prysmian Group anchors its position through deep specialization in high-voltage extruded cable systems. Nexans competes on European-tested polymer formulations adapted to NEMA thermal cycling requirements.
United States cable accessories comprise electrical and mechanical components—joints, terminations, connectors, and sealing systems—engineered to maintain dielectric integrity across rated voltage classes from 600V through 500kV, typically manufactured from cross-linked polyethylene, EPDM, or silicone rubber with conductive or stress-grading layers. These components ensure safe power continuity in utility, industrial, and infrastructure networks by managing electric field distribution and environmental sealing. Heat shrink tubing and pre-molded terminations lead product-type revenue due to standardized utility specifications, while junction boxes represent the fastest-growing configuration as distributed solar and battery interconnection multiplies AC/DC conversion nodes. Copper material segments sustain premium positioning through conductivity requirements in substation and heavy industrial applications, though aluminum gains share in aerial installations where weight reduction drives total installed cost.
FERC Order 2023 interconnection reforms and IEEE 404/622 testing standards shape product qualification pathways, compelling manufacturers to certify thermal-mechanical performance under accelerated aging protocols. OSHA 1910.269 electrical safety rules and state-level renewable portfolio standards collectively expand demand for arc-resistant and flame-retardant accessory designs in utility and construction channels. Stakeholders must monitor FERC rulemakings on transmission cost allocation and state siting reforms, as these will determine which interconnection backlogs convert to firm accessory procurement commitments.
Market Dynamics
Grid modernization mandates from FERC and state utility commissions are compressing procurement cycles for high-voltage accessories, forcing manufacturers to pre-certify polymer formulations under accelerated IEEE 404 aging protocols before bid submission.
Growth Catalysts
- Transmission buildout corridors:Texas ERCOT interconnection queues and California ISO backlogs are converting to firm procurement orders for 138kV through 345kV termination systems.
- FERC Order 2023 reforms:Standardized interconnection study timelines are accelerating accessory deployment schedules for utility-scale solar and battery storage projects.
- Polymer compound advances:Silicone rubber stress-grading layers rated for 500kV thermal cycling are displacing oil-filled terminations in coastal substations.
Market Restraints
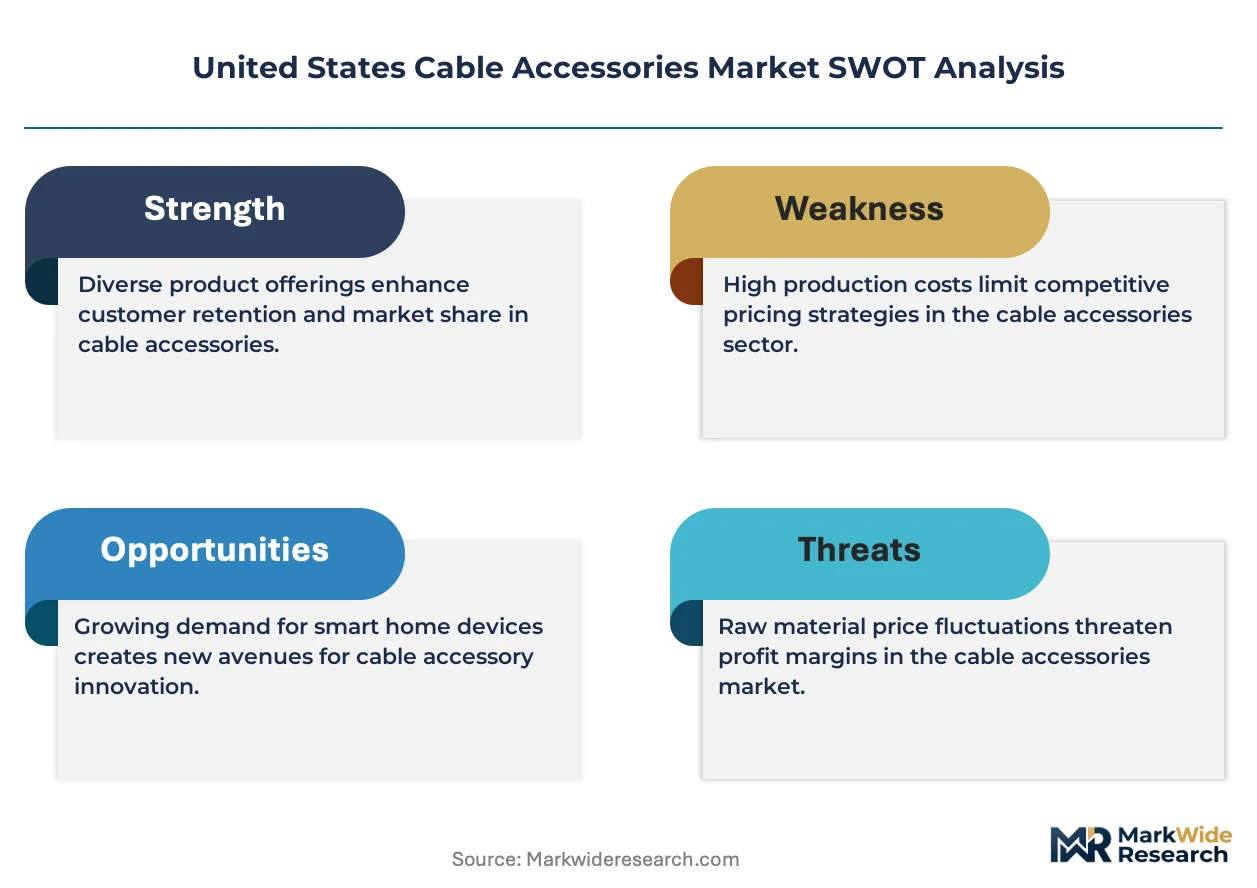
- Copper price volatility:LME copper fluctuations above historical baselines are compressing margin structures for connector manufacturers serving heavy industrial channels.
- Specialized compound supply concentration:Domestic production of cross-linked polyethylene with tree-retardant additives concentrates among three Gulf Coast petrochemical complexes.
- NEMA voltage class fragmentation:Inconsistent state-level adoption timelines for revised IEEE 622 test standards create inventory stranding risks for distributors.
Strategic Opportunities
- Offshore wind interconnection:Atlantic Coast lease areas require subsea-rated jointing systems with dry-type terminations at onshore converter stations.
- OSHA 1910.269 arc-flash compliance:Flame-retardant accessory specifications in utility construction contracts are expanding addressable market for arc-resistant designs.
- Direct-to-utility digital procurement:EPC contractors are bypassing traditional distribution layers through integrated supplier portals for standardized termination kits.
Industry Challenges
- Field technician certification gaps:Medium-voltage jointing competency shortages in the Southeast are extending installation timelines and warranty exposure.
- Legacy system integration friction:Pre-molded silicone terminations face fit incompatibility with aged PILC cable infrastructure in urban underground networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cable Accessories Market |
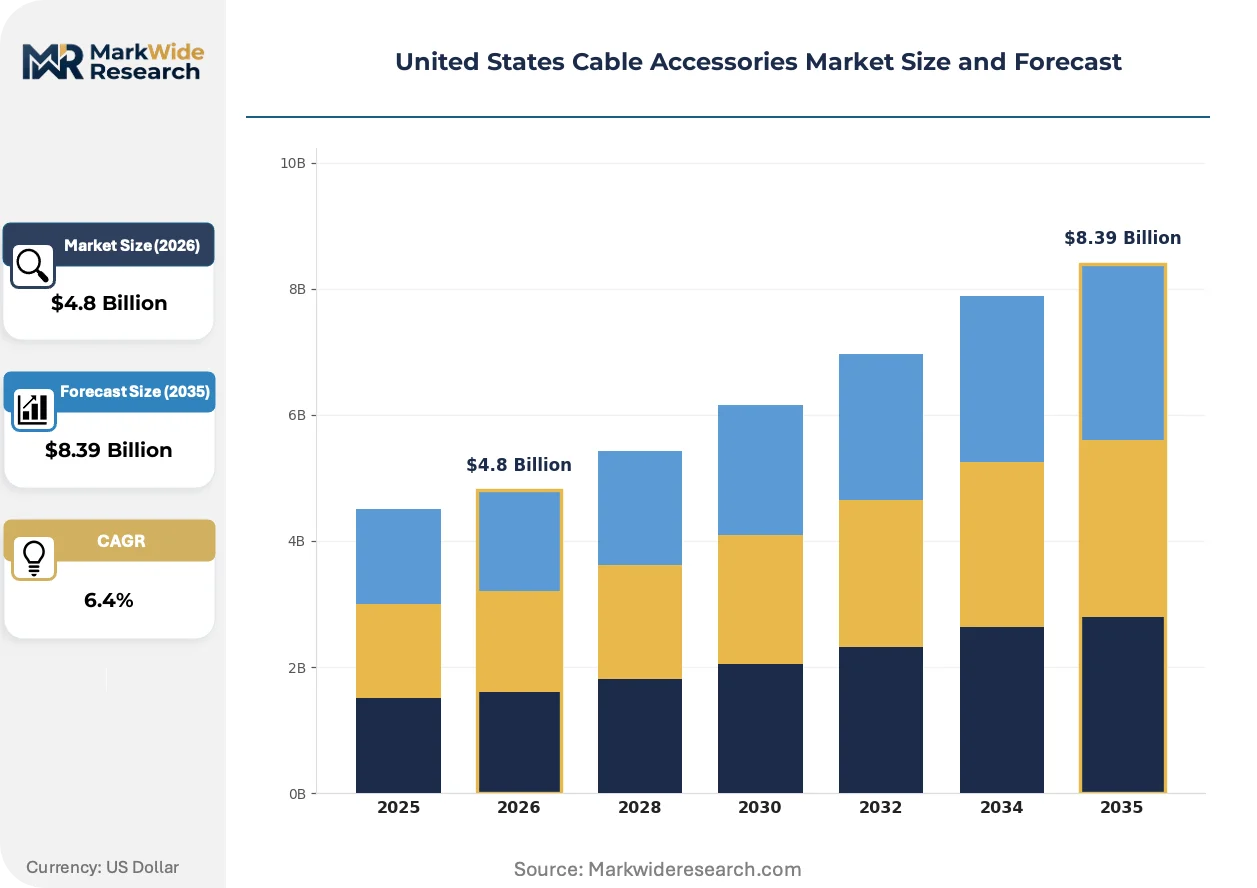
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connectors, Terminals, Junction Boxes, Heat Shrink Tubing End User: Telecommunications, Power Utilities, Construction, Transportation Material: Copper, Aluminum, Plastic, Rubber Installation Type: Indoor, Outdoor, Underground, Aerial |
| Companies Covered | Southwire Company, Prysmian Group, Nexans, ABB Ltd, Belden Inc., 3M, Encore Wire Corporation, LS Cable & System Ltd., NKT A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cable Accessories Market Strategic Shifts & Innovations
Digital monitoring integration and cold-shrink material advances are redefining accessory lifecycle economics, while procurement centralization among national EPCs is compressing supplier qualification windows.
Cold-shrink silicone rubber terminations with integrated partial discharge sensors are decentralizing condition-based maintenance models across municipal utility fleets. Rural cooperatives in the Midwest are piloting these sensor-embedded kits to eliminate scheduled climbing inspections. The technology is decentralizing workforce deployment patterns by enabling remote diagnostic triage before truck rolls.
FERC transmission cost allocation rulemakings are forcing regional transmission organizations to standardize accessory specifications across multi-state procurement zones. PJM Interconnection members must now harmonize termination kit voltage ratings and polymer grades to qualify for cost-shared buildouts. Heavy industrial buyers in the corridor are consolidating vendor lists to meet these harmonized material standards.
Utility procurement departments are consolidating annual accessory spend into multi-year framework agreements with integrated wire-and-cable suppliers. Traditional electrical distributors serving the construction channel are losing specification influence as engineering-procurement firms embed accessory selection into turnkey substation contracts. This consolidation is most visible in Texas, where ERCOT interconnection deadlines favor single-source accountability over component-level bidding.
United States Cable Accessories Market Segmentation
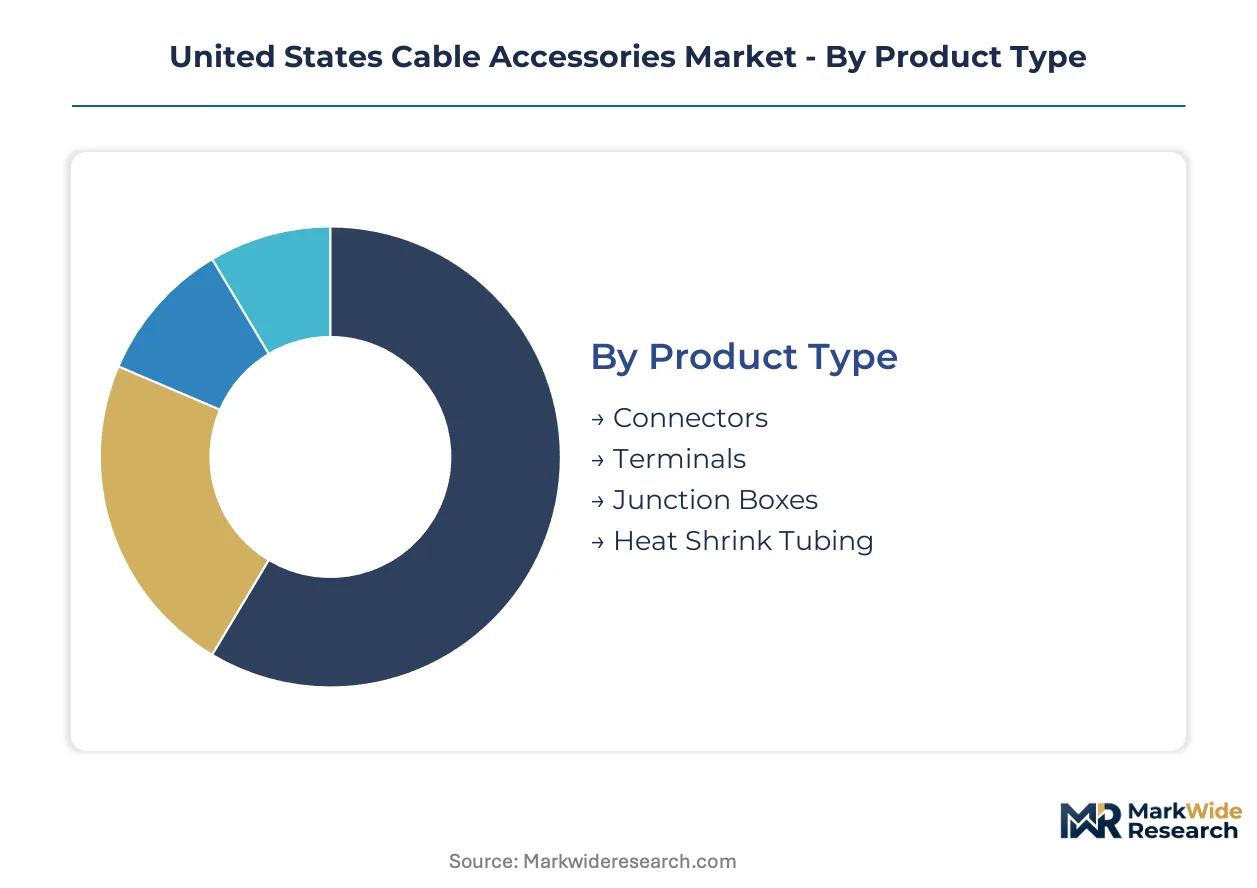
Segmentation in cable accessories reveals how voltage ratings, environmental exposure, and conductor materials shape procurement patterns across utility and industrial channels. Buyers prioritize dielectric performance, installation speed, and total lifecycle cost depending on application criticality and grid location.
Product Type:
Procurement teams differentiate accessories by field installation complexity and factory pre-molding depth.
- Connectors:Compression and mechanical designs terminate conductor ends with specified contact resistance values. ERCOT interconnection deadlines in Texas favor quick-install compression lugs over bolted alternatives. Demand concentrates in substation expansion corridors where 138kV through 345kV ratings dominate procurement specifications.
- Terminals:Pre-molded silicone rubber and heat-shrink designs manage electric field distribution at cable ends. California ISO backlogs are accelerating orders for 500kV-rated polymer terminations with integrated stress-grading layers. Coastal substations specify these for salt-fog resistance.
- Junction Boxes:Enclosures housing splice connections for AC/DC conversion nodes in solar and battery installations. Distributed generation interconnection multiplies node count.
- Heat Shrink Tubing:Cross-linked polyolefin sleeves providing environmental sealing and insulation recovery. Standardized utility specifications sustain volume.
Terminals lead volumes today; junction boxes are gaining share fastest.
End User:
Each vertical imposes distinct qualification protocols and thermal-mechanical performance thresholds.
- Power Utilities:Investor-owned and municipal operators specify IEEE 404-tested accessories for transmission and distribution networks. PJM Interconnection members harmonize polymer grades across multi-state procurement zones to qualify for cost-shared buildouts. Grid modernization mandates compress certification timelines.
- Construction:Commercial and residential electrical contractors procure termination kits through distributor channels. OSHA 1910.269 arc-flash rules expand flame-retardant specifications in utility construction contracts.
- Telecommunications:Fiber and coaxial cable sealing systems for data center and last-mile networks. 5G densification drives small cell power cable accessory demand.
- Transportation:Electrified rail and EV charging infrastructure specify vibration-resistant connectors. Federal infrastructure funding accelerates procurement.
Power utilities anchor current demand; transportation infrastructure shows the steepest expansion trajectory.
Material:
Conductivity requirements and weight constraints split procurement between premium and cost-optimized conductor choices.
- Copper:Oxygen-free and electrolytic tough-pitch grades deliver conductivity for substation and heavy industrial terminations. LME price volatility above historical baselines compresses margin structures for connector manufacturers. Premium positioning persists where ampacity margins are non-negotiable.
- Aluminum:Alloy 1350 and 6201 formulations reduce installed weight in aerial installations. Texas and Plains states favor these for long-span transmission where structural loading drives total project cost.
- Plastic:Polycarbonate and ABS housings for junction boxes and enclosures. UV stabilization differentiates outdoor grades.
- Rubber:EPDM and silicone compounds for cold-shrink and pre-molded terminations. Tree-retardant additive formulations concentrate among Gulf Coast petrochemical suppliers.
Copper dominates revenue today; aluminum is climbing the fastest in aerial applications.
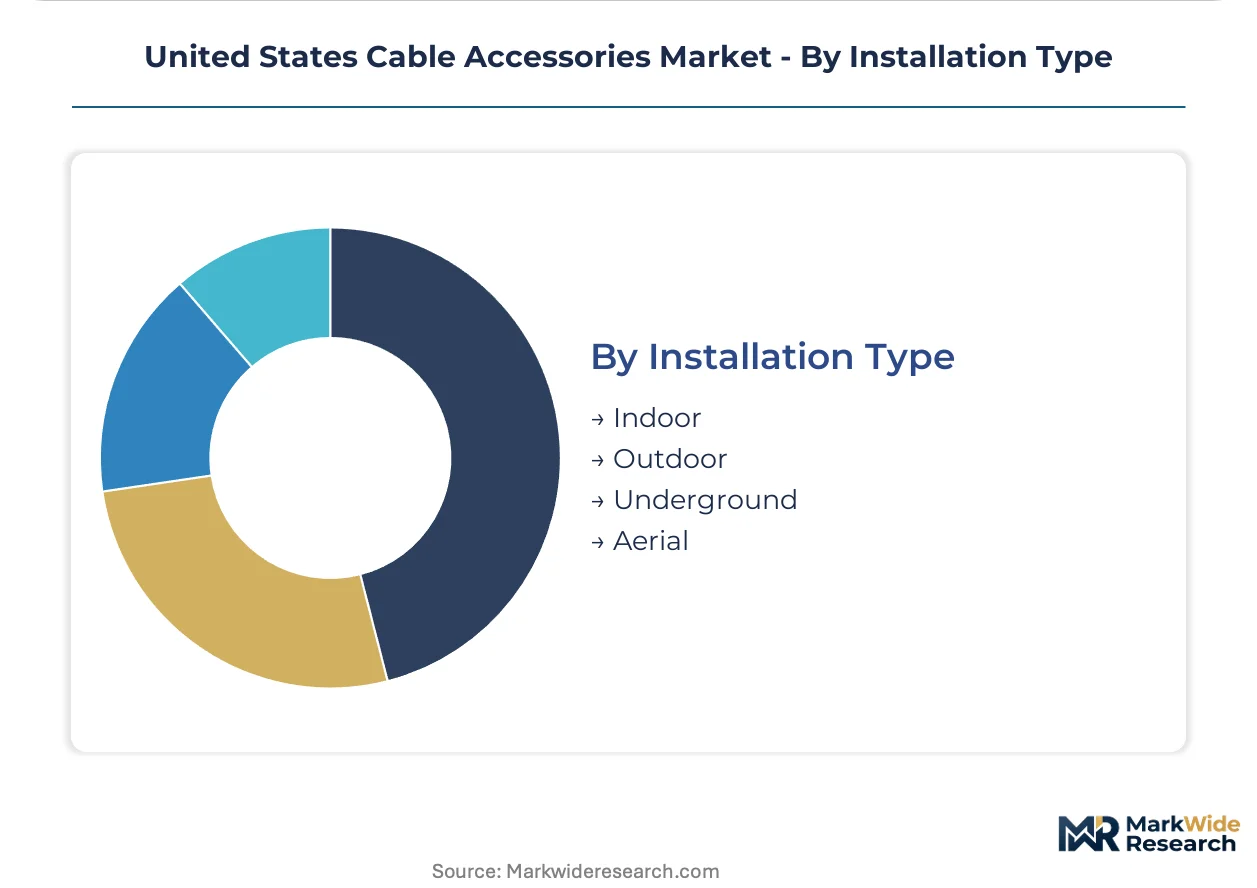
Installation Type:
Environmental exposure determines sealing system complexity and polymer grade selection.
- Outdoor:UV-resistant and moisture-sealed terminations for substation yards and pole-mounted transformers. NEMA 3R and 4X ratings specify gasket and housing integrity.
- Underground:Direct-buried and duct-bank installations requiring water-blocking and mechanical protection. Urban networks in the Northeast specify these for PILC cable replacement compatibility.
- Indoor:Switchgear and control room terminations with reduced environmental sealing requirements. Faster installation cycles favor pre-molded designs.
- Aerial:Messenger-supported and spacer cable systems for overhead distribution. Weight reduction drives aluminum conductor preference.
Outdoor installations command the largest addressable market; underground configurations are expanding most quickly in coastal resilience projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States cable accessories industry traces its modern scale to post-war electrification and the 1965 Northeast blackout, which triggered federal reliability mandates that standardized termination and jointing specifications across utility territories.
Texas
ERCOT interconnection queues and transmission buildouts drive procurement of 138kV through 345kV termination systems. FERC Order 2023 reforms compress study timelines for utility-scale solar and battery storage projects. Houston and Dallas-Fort Worth anchor manufacturing and distribution clusters where petrochemical suppliers produce tree-retardant cross-linked polyethylene compounds.
California
California ISO backlogs and coastal resilience requirements accelerate orders for 500kV-rated polymer terminations with salt-fog resistance. State renewable portfolio standards mandate arc-resistant accessory designs in utility construction contracts. The Los Angeles Basin and Bay Area concentrate engineering-procurement firms embedding accessory selection into turnkey substation contracts.
PJM Interconnection Corridor
Multi-state transmission cost allocation rulemakings force harmonization of termination kit voltage ratings and polymer grades across Pennsylvania, Ohio, and Illinois. FERC transmission cost allocation reforms determine which interconnection backlogs convert to firm procurement commitments. Philadelphia and Pittsburgh serve as procurement coordination hubs for cost-shared buildouts.
Southeast
Municipal utility fleets and rural cooperatives pilot cold-shrink silicone rubber terminations with integrated partial discharge sensors. OSHA 1910.269 electrical safety rules expand flame-retardant specifications in utility construction contracts. Atlanta and Charlotte concentrate field technician training programs addressing medium-voltage jointing competency shortages.
Northeast
Urban underground networks require pre-molded silicone terminations compatible with aged PILC cable infrastructure replacement. State siting reforms and coastal resilience projects expand underground installation specifications. Boston and New York City anchor legacy system integration corridors where fit compatibility drives procurement decisions.
United States Cable Accessories Market Key Industry Players
Premium-margin players sit above commodity-margin players across voltage rating specialization and polymer formulation depth. The market exhibits tiered concentration with integrated wire-to-accessory manufacturers controlling lead times alongside pure-play termination specialists competing on technical qualification speed. Three archetypes dominate: integrated cable-accessory manufacturers, high-voltage extruded system specialists, and European polymer formulation adapters. Capacity expansion and pre-certification partnerships represent the dominant competitive moves as procurement cycles compress.
Within the integrated manufacturing tier, Southwire Company exemplifies captive supply chain control across the Southeast. Prysmian Group S.p.A. and Nexans S.A. occupy positions bridging European polymer expertise with NEMA thermal cycling requirements. These three anchors illustrate how geographic manufacturing footprint and formulation adaptation speed separate premium-tier positioning from commodity competition.
| Leading Market Players |
|---|
| Southwire Company |
| Prysmian Group |
| Nexans |
| ABB Ltd |
| Belden Inc. |
| 3M |
| Encore Wire Corporation |
| LS Cable & System Ltd. |
| NKT A/S |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between IEEE 622-compliant polymer terminations and commodity heat-shrink kits manifests in both margin structures and raw material sourcing strategies across the United States. Premium-tier manufacturers captive-produce tree-retardant cross-linked polyethylene at Gulf Coast petrochemical complexes while commodity distributors rely on spot-market silicone rubber imports, creating divergent cost bases that reshape competitive positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the United States cable accessories market by voltage rating and polymer formulation depth. Price differentiation hinges on IEEE 404 thermal cycling certification tier and volume-scale procurement commitments from national EPC contractors. Cost compression in the commodity heat-shrink segment is intensifying because LME copper volatility above historical baselines squeezes connector manufacturer margins. Construction channel distributors exhibit the highest price sensitivity, while investor-owned utilities prioritize dielectric performance over unit cost in substation applications.
Supply Chain Analysis
Field technician certification gaps in the Southeast and Gulf Coast petrochemical workforce constraints are tightening production timelines for specialized EPDM and silicone rubber compounds. Domestic manufacturing of cross-linked polyethylene with tree-retardant additives concentrates among three Gulf Coast complexes, while conductive layer materials draw from specialty chemical suppliers in Germany and Japan. Single-source vulnerability in Gulf Coast petrochemical production creates exposure to hurricane-season disruptions. Distribution runs through integrated wire-and-cable supplier portals that bypass traditional electrical distributor layers for utility-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States cable accessories market functions as a regulatory compounder where FERC Order 2023 interconnection reforms are accelerating procurement velocity and compressing supplier qualification windows.
For Market Incumbents: Deepen captive supply chain control over tree-retardant polymer formulations at Gulf Coast manufacturing complexes to defend against European formulation specialists adapting to NEMA thermal cycling requirements. Accelerate pre-certification partnerships with regional transmission organizations to secure framework agreement positioning before harmonized procurement standards finalize. For New Entrants and Emerging Players: Capture medium-voltage jointing competency shortages in the Southeast through targeted field technician training programs bundled with cold-shrink termination kits. The rural cooperative segment offers the most penetrable entry point, with sensor-embedded diagnostic accessories representing a distinct go-to-market angle against incumbent commodity suppliers. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented distributor networks lose specification influence to integrated wire-and-cable manufacturers with captive accessory production. Long-term viability favors acquisition targets with IEEE 622 pre-certification capabilities and established EPC contractor relationships. The signal to watch is FERC transmission cost allocation rulemaking outcomes that determine which interconnection backlogs convert to firm procurement commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Partnership | Early IEEE 404/622 testing completion secures preferred supplier status with PJM Interconnection members. |
| Backward Integration into Polymers | Gulf Coast captive production of tree-retardant cross-linked polyethylene insulates margin structures from petrochemical price volatility. |
| Field Technician Certification Program | Medium-voltage jointing training addresses Southeast competency gaps while locking in aftermarket service revenue. |
| Sensor-Embedded Product Launch | Integrated partial discharge monitoring differentiates cold-shrink terminations for rural cooperative pilot programs. |
| Direct-to-Utility Portal Development | Bypassing electrical distributors captures specification influence as EPC contractors consolidate vendor lists. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility procurement officers, EPC contractor project managers, polymer compound R&D directors, and electrical distributor category buyers with secondary validation. Regulatory filings from FERC, IEEE standards documentation, and utility interconnection queue databases anchored demand-side modeling. SEC 10-K disclosures from listed cable manufacturers and petrochemical supplier trade data completed supply-side triangulation through bottom-up and top-down approaches.
Historical reference periods spanning transmission buildout cycles and renewable interconnection waves anchored the projection horizon across voltage rating tiers, installation type categories, and regional regulatory clusters. Segmentation dimensions modeled include product type complexity, end-user procurement protocol stringency, material conductivity requirements, and environmental exposure specifications. CAGRs were derived from utility capital expenditure trajectories and renewable portfolio standard mandates, with FERC rulemaking timelines and copper futures curves serving as key forecast inputs.
Regulatory reversal on transmission cost allocation, prolonged IEEE 622 standard adoption delays, and Gulf Coast petrochemical supply disruptions are the dominant revision risks to modeled accessory demand. Forecasts reflect assumptions regarding interconnection queue conversion rates and polymer formulation certification timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Active Optical Cable Market
Cables
Sensor Cable Market
Cables
US Medium Voltage Cable Accessories Market
Cables
Europe Cable Joints Market
Cables
Electric Vehicle Cables Market
Cables
Instrumentation Cables Market
Cables
Global Cable Blowing Equipment Market
Cables
Type TC and Type TC-ER Cable (600 V) Market
Cables
Water Leak Sensing Cable Market
Cables
Cable Testing Market
Cables
Shipboard Cable Market
Cables
Latin America Wire and Cable Market
Cables
Global Wires and Cables Market
Cables
Low-Temperature Cable Market
Cables
Electric Submersible Cable Sales Market
Cables
Asia-Pacific Premise Cable Market