
 Smartphone Type-C Charging and Data Cable Market | 2026-2036
Smartphone Type-C Charging and Data Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Smartphone Type-C Charging and Data Cable Market Insights
Buyer fragmentation across emerging-market smartphone OEMs is repositioning procurement power toward volume-tier cable suppliers. Anker Innovations leverages its Amazon-native distribution infrastructure to sustain pricing flexibility across multiple connector configurations. Samsung Electronics anchors premium fast-charging cable demand through Galaxy ecosystem lock-in, while UGREEN competes aggressively on cross-platform compatibility.
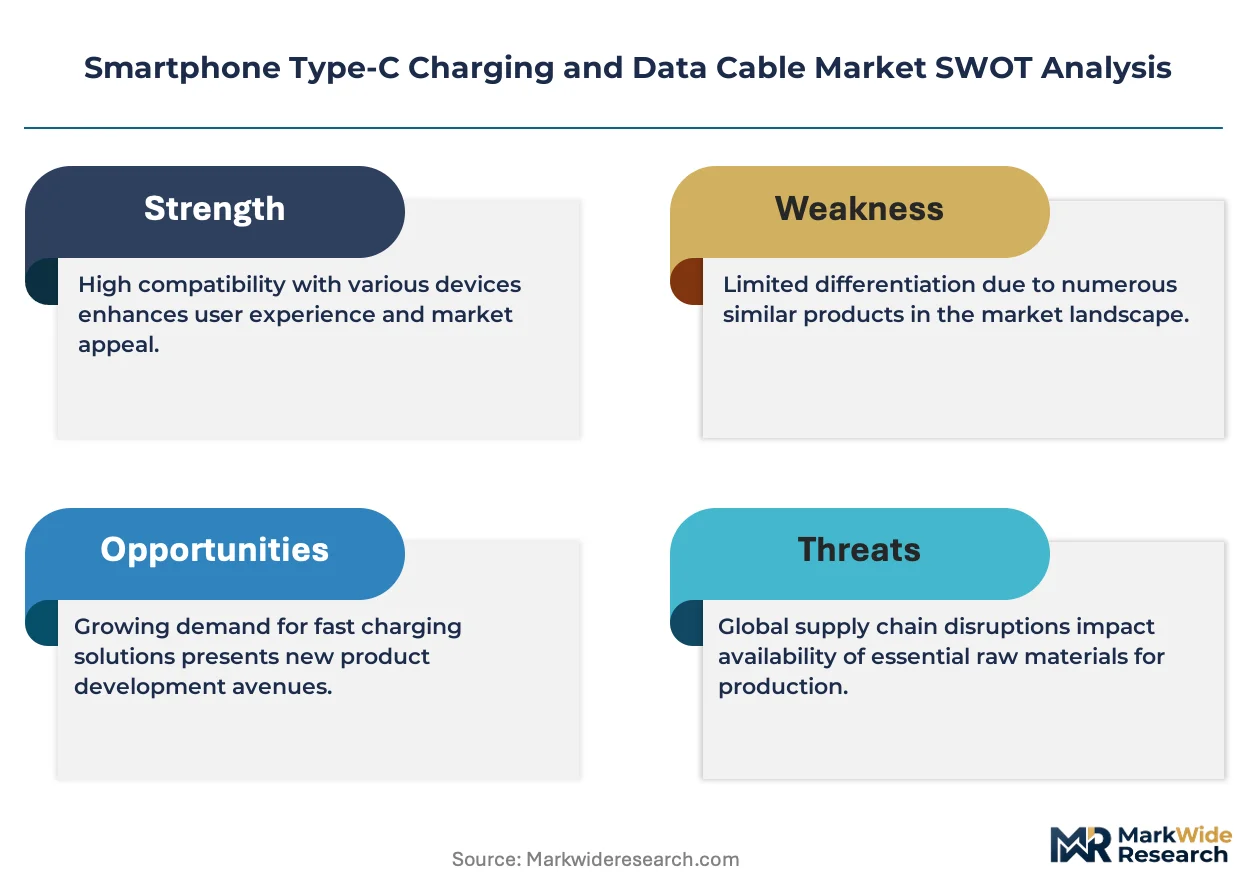
Smartphone Type-C charging and data cables transmit power and digital signals through twisted copper conductor pairs shielded by thermoplastic elastomer jackets, with USB Power Delivery 3.1 enabling up to 240W throughput over certified USB-C to USB-C configurations. Their primary commercial purpose centers on universal interoperability across smartphones, tablets, laptops, and peripheral ecosystems. Braided nylon sheathing commands durable-goods positioning in personal use segments where cable replacement cycles stretch beyond eighteen months, while fast charging variants concentrate margin pools in professional use applications where wattage throughput determines purchasing criteria. Standard PVC-jacketed cables occupy cost-driven commercial use channels with thinner overhead absorption.
USB Implementers Forum certification programs and IEC 62680 harmonization standards govern connector dimensional tolerances and power handshake protocols, with EU common charger directives mandating USB-C as the universal charging interface across member states. India's BIS compulsory registration scheme filters non-compliant imports from Southeast Asian manufacturing hubs, tightening market access for uncertified suppliers. Stakeholders must monitor regulatory divergence between EU interoperability mandates and regional certification fragmentation as the decisive variable for cross-border inventory deployment.
Market Dynamics
USB Power Delivery 3.1 certification requirements are compressing supplier margins while fragmenting procurement authority across smartphone OEMs, cable assemblers, and third-party accessory brands. The shift from bundled to retail-channel distribution is redistributing volume concentration toward Amazon-native and direct-to-consumer platforms.
Growth Catalysts
- EU Common Charger Directive:Mandates USB-C as the universal charging interface across all member states, eliminating proprietary connector fragmentation and standardizing procurement specifications for cable manufacturers.
- India BIS Compulsory Registration:Filters non-compliant imports from Southeast Asian manufacturing hubs, creating certified-supplier scarcity that rewards early compliance investments by domestic and established foreign producers.
- Braided Nylon Sheathing:Extends replacement cycles beyond eighteen months in personal use segments, commanding durable-goods positioning and premium shelf pricing in retail channels.
Market Restraints
- Copper Price Volatility:Twisted conductor pairs constitute the primary raw material cost input, with LME copper fluctuations compressing assembler margins on fixed-price retail contracts.
- Dongguan-Shenzhen Supply Concentration:Over seventy percent of global USB-C cable assembly capacity clusters in China's Pearl River Delta, exposing buyers to single-geography disruption risk from logistics or policy shocks.
- Wireless Charging Substitution:Qi2 magnetic alignment and 50W+ wireless throughput in flagship smartphones threaten to displace cable demand in premium device ecosystems.
Strategic Opportunities
- Vietnam Manufacturing Migration:Labor cost arbitrage and tariff diversification are drawing cable assembly investment to Hai Phong and Bac Ninh industrial zones, creating alternative supply bases outside China.
- Automotive USB-C Integration:In-vehicle infotainment and charging ports are adopting USB-C for data and power, opening a new end-use vertical with stringent temperature and vibration specifications.
- Amazon Direct-to-Consumer Channels:Platform-native brands bypass distributor markups and capture real-time demand signals, enabling rapid SKU rotation across connector configurations and length variants.
Industry Challenges
- USB-IF Certification Timelines:Power Delivery 3.1 and EPR cable certification cycles extend four to six months, delaying product launches and freezing working capital in pre-certified inventory.
- EMI Shielding Engineering Talent:High-wattage cable design requires specialized radio-frequency engineering expertise that concentrates in Shenzhen and Taipei, creating recruitment bottlenecks for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smartphone Type-C Charging and Data Cable Market |
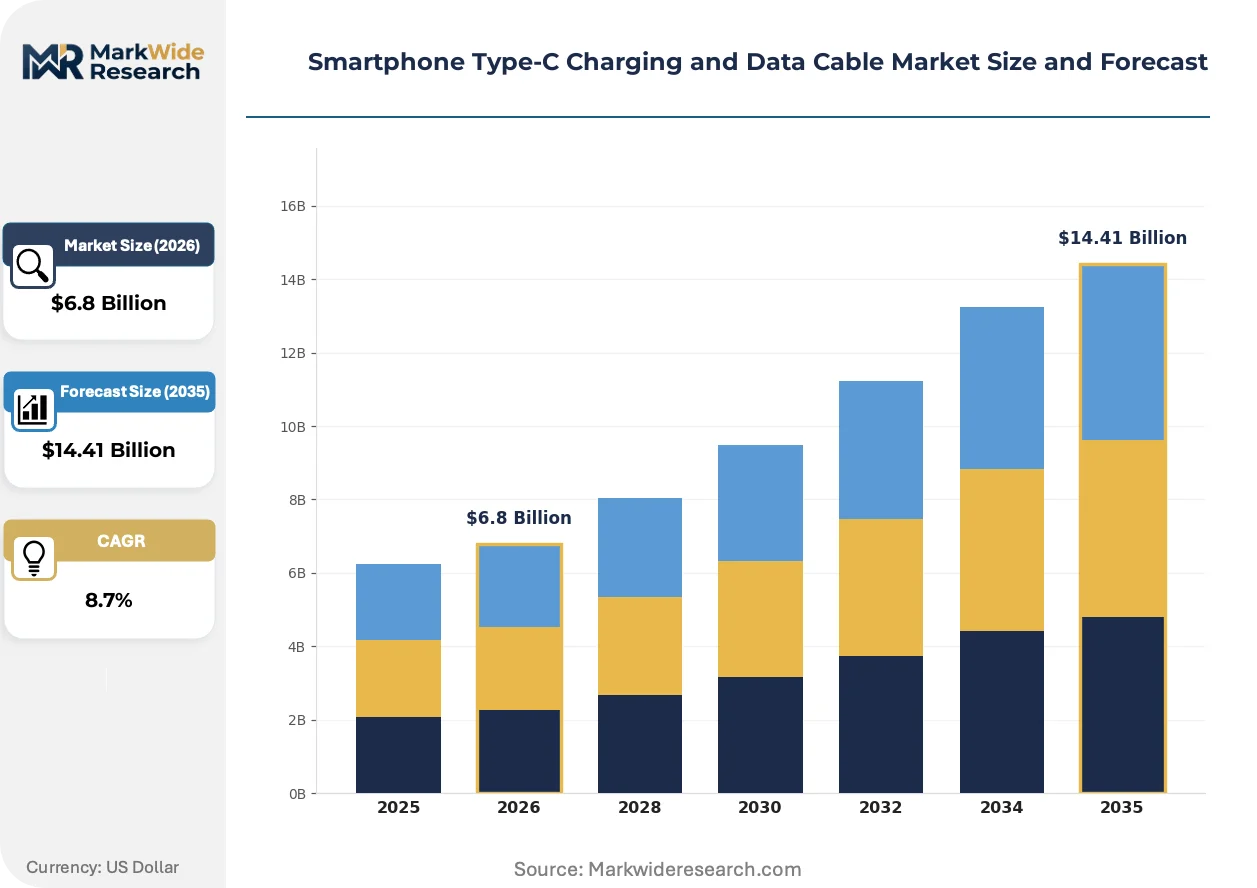
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cable, Fast Charging Cable, Braided Cable, Retractable Cable Material: Plastic, Nylon, Aluminum, PVC Connector Type: USB-C to USB-A, USB-C to USB-C, USB-C to Lightning, Multi-Port Connector Application: Personal Use, Professional Use, Commercial Use, Industrial Use |
| Companies Covered | Anker Innovations, Belkin International, UGREEN, Samsung Electronics, Apple Inc., Aukey, Satechi, Native Union, Nomad Goods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smartphone Type-C Charging and Data Cable Market Trends and Innovations
Active optical cable technology and gallium nitride power electronics are compressing form factors while extending throughput limits. Regulatory harmonization efforts are converging on USB-C as the single interface standard across consumer, automotive, and industrial applications.
Silicon carbide power controllers are overtaking traditional silicon MOSFETs in high-wattage cable assemblies. Premium laptop and gaming peripheral manufacturers are adopting these controllers to manage thermal loads above 100W. The technology is overtaking conventional designs in professional use segments where sustained power delivery determines purchasing decisions.
India's BIS compulsory registration scheme is tightening import filters for USB-C cables and chargers. The regulation requires third-party laboratory testing and factory audits before market entry. Mid-tier smartphone brands are decoupling chargers from retail packaging to comply, shifting volume toward certified aftermarket suppliers.
Enterprise procurement teams are consolidating cable sourcing through managed service contracts rather than transactional spot purchases. IT departments at financial services and healthcare firms are replacing ad-hoc retail buying with vendor-managed inventory programs. This pattern is most visible in North American and Western European corporate technology refresh cycles.
Smartphone Type-C Charging and Data Cable Market Segmentation
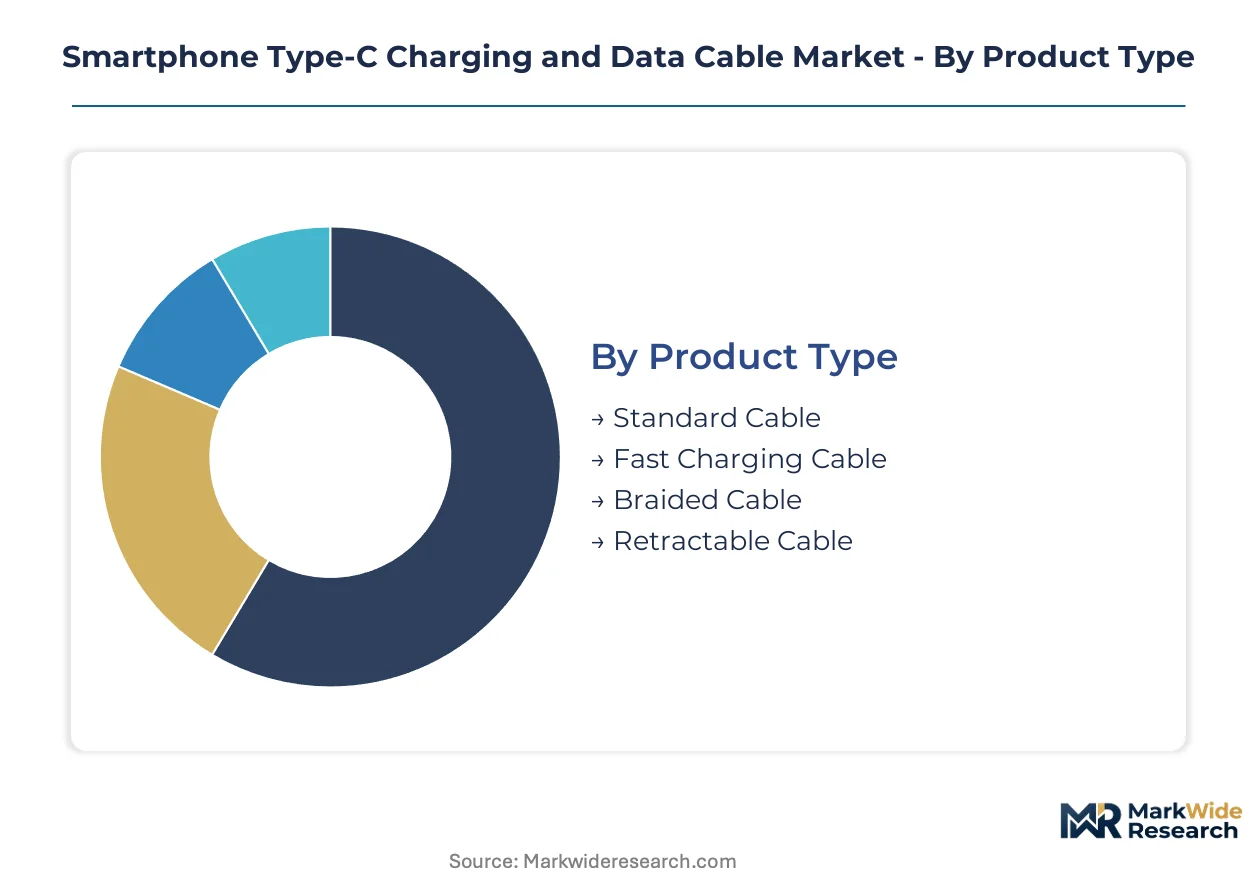
Smartphone Type-C cable procurement splits across four structural dimensions, each imposing distinct certification burdens and margin profiles. USB-IF Power Delivery validation requirements fragment supplier capabilities unevenly across product tiers, while material and connector specifications determine regional market access under divergent national standards.
Product Type:
USB-IF certification intensity varies sharply across this dimension: Fast Charging Cable and Braided Cable variants require full Power Delivery 3.1 and EPR compliance testing cycles, while Standard Cable and Retractable Cable face lighter protocol verification.
- Standard Cable:PVC-jacketed twisted copper conductor assemblies without active power negotiation chips. Demand concentrates in India's aftermarket retail channels where BIS compulsory registration filters uncertified imports, compressing margins for non-compliant suppliers.
- Fast Charging Cable:E-marker chip-equipped assemblies supporting 100W-240W USB Power Delivery 3.1 throughput over shielded twisted pairs. Samsung Electronics and flagship Android OEMs anchor procurement in South Korea and Vietnam manufacturing corridors, with certification timelines freezing working capital for four to six months.
- Bided Cable:Nylon or polyester woven sheathing over TPE jackets extending mechanical flex cycles beyond ten thousand bends. Amazon-native brands command premium shelf positioning in North American and Western European direct-to-consumer channels.
- Retractable Cable:Spring-loaded reel mechanisms housing coiled conductor assemblies in compact form factors. Automotive USB-C integration programs in Germany and Japan specify these for center console applications with severe space constraints.
Gaining share fastest: Fast Charging Cable. Leading by absolute volume: Standard Cable.
Material:
Raw material cost exposure and environmental compliance obligations reshape competitive positioning across this dimension, with aluminum and nylon variants facing divergent REACH and RoHS substance restrictions in European markets.
- Plastic:Thermoplastic elastomer and polycarbonate jacketing compounds dominate high-volume OEM bundling programs. India's decoupling trend shifts this segment toward certified aftermarket suppliers as mid-tier brands remove chargers from retail packaging.
- Nylon:Braided polyethylene terephthalate and aramid fiber sheathing commands eighteen-month-plus replacement cycles in personal use segments. Southeast Asian consumer electronics corridors concentrate demand for durable-goods positioning.
- Aluminum:Extruded alloy connector housings and braided shielding layers manage thermal dissipation in 100W-plus assemblies. Gaming peripheral manufacturers in Taiwan and South Korea specify these for sustained power delivery applications.
- PVC:Polyvinyl chloride remains the cost-optimized baseline for commercial bulk procurement and enterprise managed service contracts. Financial services and healthcare IT departments in the United States consolidate sourcing through vendor-managed inventory programs.
Climbing the fastest: Nylon. Dominating procurement scale: PVC.
Connector Type:
Protocol handshake complexity and cross-platform interoperability requirements fragment this dimension, with USB-C to USB-C configurations facing the most stringent USB-IF certification while legacy adapters navigate transitional compliance windows.
- USB-C to USB-A:Legacy adapter cables maintaining backward compatibility with existing charger installed bases. India's BIS scheme and EU Common Charger Directive create divergent regulatory treatment for this transitional format.
- USB-C to USB-C:Native USB Power Delivery 3.1 configurations supporting full 240W Extended Power Range. UGREEN and Anker Innovations compete aggressively on cross-platform certification coverage across multiple regional approval schemes.
- USB-C to Lightning:Apple ecosystem bridge cables facing MFi program requirements alongside USB-IF validation. Enterprise procurement teams in North America favor these for mixed-device fleet standardization.
- Multi-Port Connector:Hubs and splitter assemblies combining USB-C power input with multiple output protocols. Automotive infotainment system integrators in Japan and Germany specify these for in-vehicle charging port consolidation.
Expanding most quickly: USB-C to USB-C. Anchoring procurement volume: USB-C to USB-A.
Application:
Replacement cycle length and performance specification intensity divide this dimension, with Professional Use and Industrial Use segments demanding extended temperature and vibration tolerances absent from personal consumption tiers.
- Personal Use:Individual consumer replacement purchases through retail and e-commerce channels. Braided nylon variants command premium positioning where replacement cycles stretch beyond eighteen months in Southeast Asian markets.
- Professional Use:Content creators, field technicians, and mobile professionals prioritizing wattage throughput and mechanical durability. Silicon carbide power controllers in 100W-plus assemblies determine purchasing criteria for laptop and gaming peripheral manufacturers.
- Commercial Use:Enterprise and institutional bulk procurement through managed service contracts. IT departments at financial services and healthcare firms in the United States and Western Europe replace ad-hoc retail buying with vendor-managed inventory programs.
- Industrial Use:Harsh-environment deployments requiring IP-rated sealing and extended temperature specifications. Automotive USB-C integration for in-vehicle infotainment and charging ports in Germany and Japan opens this vertical with stringent qualification protocols.
Steepest expansion trajectory: Professional Use. Commanding largest volume base: Personal Use.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper conductor fabrication in China's Pearl River Delta anchors assembly capacity for smartphone Type-C cables, while regulatory divergence across major economies fragments procurement specifications and certification pathways.
China
Dongguan and Shenzhen industrial zones concentrate over seventy percent of global USB-C cable assembly, with OEMs sourcing twisted copper pairs from local smelters. MIIT enforces GB standards for electromagnetic compatibility in domestic shipments. Labor cost pressures are pushing some assembly toward Vietnam, yet the Pearl River Delta retains E-marker chip programming and high-frequency testing capabilities.
United States
Enterprise procurement teams at financial services and healthcare firms consolidate cable sourcing through vendor-managed inventory programs. FCC Part 15 regulations govern electromagnetic interference for imported assemblies. Amazon-native brands leverage direct-to-consumer channels to bypass distributor markups, with fulfillment centers in Texas and California handling rapid SKU rotation.
Germany
Automotive OEMs specify USB-C for in-vehicle infotainment integration, creating demand for temperature-resistant assemblies. KBA qualification protocols and EU Common Charger Directive implementation create dual compliance burdens. Industrial clusters in Bavaria and Baden-Württemberg host testing laboratories for automotive-grade cable validation.
India
BIS compulsory registration filters non-compliant imports, rewarding early compliance investments by domestic and established foreign producers. Mid-tier smartphone brands in Maharashtra and Karnataka decouple chargers from retail packaging, shifting volume toward certified aftermarket suppliers. DGFT import monitoring tightens market access for uncertified Southeast Asian manufacturers.
Vietnam
Hai Phong and Bac Ninh industrial zones attract cable assembly investment seeking labor cost arbitrage and tariff diversification. Factory audits under India's BIS scheme and EU REACH substance restrictions determine export eligibility. Samsung Electronics anchors premium fast-charging procurement through its Vietnamese smartphone assembly operations.
Smartphone Type-C Charging and Data Cable Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue Amazon-native distribution and cross-platform certification coverage. The market structures around three tiers: premium fast-charging specialists, volume-tier OEM bundling suppliers, and direct-to-consumer platform brands. Strategic archetypes include certification-anchored incumbents, logistics-integrated platform natives, and automotive diversification seekers. Competitive moves center on geographic manufacturing migration and USB-IF certification pre-positioning.
Among platform-native specialists, Anker Innovations exemplifies logistics-integrated positioning through Amazon-native infrastructure, while UGREEN occupies a slot emphasizing cross-platform compatibility coverage. Samsung Electronics anchors premium-tier procurement through ecosystem lock-in, representing the OEM-captive archetype. These three sit within distinct competitive vectors—distribution infrastructure, protocol breadth, and vertical integration—without overlapping strategic territory.
| Leading Market Players |
|---|
| Anker Innovations |
| Belkin International |
| UGREEN |
| Samsung Electronics |
| Apple Inc. |
| Aukey |
| Satechi |
| Native Union |
| Nomad Goods |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between USB-IF Power Delivery 3.1 EPR cables and uncertified commodity assemblies manifests in divergent margin structures and sourcing configurations. Premium fast-charging variants command extended supplier qualification timelines that freeze working capital, while standard PVC-jacketed cables flow through spot-market procurement channels with minimal compliance overhead.
Pricing Analysis
Warranty and service bundling separate enterprise managed service contracts from transactional retail purchases. Three-tier pricing structure across premium, standard, and economy levels reflects USB-IF certification intensity and braided material specifications. Price differentiation rests on E-marker chip integration and BIS registration status for Indian market access. Cost compression in standard-tier assemblies intensifies because copper price volatility and Dongguan-Shenzhen supply concentration squeeze fixed-price contract margins. Enterprise IT departments exhibit lowest price sensitivity due to vendor-managed inventory consolidation, while Southeast Asian aftermarket retailers show highest sensitivity to per-unit procurement costs.
Supply Chain Analysis
Dual-sourcing requirements from Samsung Electronics and flagship Android OEMs mandate qualified supplier rosters across both China and Vietnam manufacturing corridors. Geographic supply concentration centers on Dongguan and Shenzhen industrial zones for E-marker programming and high-frequency testing, with Hai Phong and Bac Ninh emerging as alternative assembly bases. Raw material dependencies draw from LME copper smelters, thermoplastic elastomer compounders, and gallium nitride controller foundries. Single-geography disruption risk from Pearl River Delta logistics or policy shocks threatens inventory continuity. Distribution runs through Amazon-native direct-to-consumer channels and enterprise vendor-managed inventory programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into E-marker chip programming and USB-IF certification testing represents the decisive upstream lever as Power Delivery 3.1 timelines extend and working capital requirements intensify.
For Market Incumbents: Cement certification-anchored positioning by acquiring EMI shielding engineering talent in Shenzhen and Taipei, while expanding captive testing laboratory capacity to compress four-to-six-month validation cycles. Wireless charging substitution from Qi2 magnetic alignment threatens premium cable attach rates in flagship smartphone ecosystems. Backward integration into E-marker semiconductor sourcing secures supply continuity against foundry allocation constraints. For New Entrants and Emerging Players: Capture automotive USB-C integration white space in Germany and Japan by qualifying temperature-resistant assemblies for KBA protocols and in-vehicle vibration specifications. Professional use segments for content creators and field technicians offer penetrable entry points where wattage throughput determines purchasing criteria rather than brand legacy. Amazon-native direct-to-consumer distribution bypasses incumbent distributor markups and captures real-time demand signals for rapid SKU rotation. For Investors and Strategic Acquirers: Re-rating potential sits with Vietnam-based assembly specialists with BIS-registered export capacity given India's compulsory registration scheme tightening import filters. Long-term viability over the next decade hinges on diversification beyond smartphone OEM bundling toward automotive and industrial verticals. Monitor USB-IF certification backlog durations as inflection indicator for supplier scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| USB-IF Certification Pre-Positioning | Four-to-six-month validation cycles freeze working capital and reward early compliance investments. |
| Vietnam Manufacturing Migration | Hai Phong and Bac Ninh industrial zones offer labor arbitrage and tariff diversification outside China. |
| Automotive USB-C Integration | KBA qualification protocols in Germany open stringent-temperature vertical beyond consumer electronics. |
| Amazon-Native Channel Buildout | Direct-to-consumer platforms bypass distributor markups and capture real-time demand signals. |
| Silicon Carbide Controller Adoption | Gaming peripheral manufacturers in Taiwan specify these for sustained 100W-plus power delivery. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with USB-IF certification engineers, cable assembly plant managers, smartphone OEM procurement leads, and Amazon-native brand operators. USB Implementers Forum compliance databases, BIS registration manifests, EU Common Charger Directive implementation documents, and LME copper price series provided validation benchmarks. Bottom-up assembly capacity modeling and top-down smartphone shipment projections enabled triangulation across estimation approaches.
Granularity-level modeling disaggregated volume and value across product type, material specification, connector configuration, and application use case throughout the forecast period. Analytical framework approach incorporated USB Power Delivery protocol generation, BIS registration status, and braided versus PVC jacketing as structural segmentation dimensions. CAGRs derived from fitted growth curves applied to certified versus uncertified supplier capacity expansion trajectories. Copper price volatility assumptions and wireless charging penetration scenarios informed sensitivity testing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Common Charger Directive enforcement consistency and India's BIS scheme expansion to additional product categories. Forecasts reflect documented assumptions regarding smartphone OEM bundling decoupling rates and automotive USB-C adoption timelines. Deviation in Qi2 wireless charging power thresholds or Pearl River Delta logistics disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
FFC/FPC Jumper Cables Market
Cables
USB Cable Market
Cables
Flat Flexible Cables Market
Cables
Military Cable Market
Cables
Underground Cable Market
Cables
Wire and Cable Materials Market
Cables
Cable Lugs Market
Cables
Submarine Cables Market
Cables
Fiber Optic Cable Materials Market
Cables
Cable Tags Market
Cables
North America HVAC Cables Market
Cables
Low-Temperature Cable Market
Cables
Asia-Pacific Cable Joints Market
Cables
Shipboard Cable Market
Cables
Solar Cable Market
Cables
Cable Drum Market