
 Vietnam LED Lighting Market | 2026-2036
Vietnam LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam LED Lighting Market Intelligence
Project distribution is tilting toward direct-contractor relationships and e-commerce platforms serving tier-two cities. Dien Quang leverages its domestic manufacturing footprint to anchor pricing power across northern provinces. Rang Dong competes through backward integration into LED chip packaging, while Signify sustains technology leadership in connected lighting systems for commercial installations.
Vietnam LED lighting comprises solid-state luminaires using gallium nitride semiconductor emitters operating at 80-150 lumens per watt, designed to replace legacy fluorescent and incandescent sources in commercial, industrial, and residential environments. Smart lighting technology leads value generation through sensor-integrated controls and IoT connectivity, while retrofit installation dominates volume as existing building stock undergoes efficiency-driven replacement. Bulbs retain mass-market penetration in residential channels, whereas panels and fixtures capture premium positioning in office and retail verticals.
Vietnam's Ministry of Construction enforces building energy codes that mandate LED adoption in new public structures, while the Vietnam Standards and Quality Institute administers QCVN lighting efficiency certifications that gate market access for imported products. The General Department of Energy Efficiency under the Ministry of Industry and Trade coordinates national programs subsidizing industrial facility retrofits. Stakeholders must monitor regulatory tightening on minimum efficacy thresholds and local content requirements that could reshape sourcing strategies for foreign suppliers.
Market Dynamics
Vietnam's LED lighting sector is compressing fixture replacement cycles as commercial real estate developers in Ho Chi Minh City and Hanoi accelerate fluorescent-to-LED retrofits ahead of Ministry of Construction energy code enforcement deadlines.
Growth Catalysts
- QCVN Certification Mandates:The Vietnam Standards and Quality Institute's efficacy thresholds gate market access for imported products, forcing domestic production upgrades and quality standardization across the supply base.
- Industrial Zone Retrofit Programs:Northern provinces including Bac Ninh and Hai Phong host concentrated factory conversion initiatives targeting metal halide and fluorescent replacement in manufacturing facilities.
- Gallium Nitride Chip Efficiency Gains:Solid-state emitter performance reaching 150 lumens per watt enables lumen-for-lumen replacement of legacy high-bay installations with reduced fixture counts.
Market Restraints
- Import Duty Structure:Finished luminaire tariffs exceed component rates, pressuring foreign suppliers to establish local assembly rather than direct shipment of packaged products.
- Substrate Supply Concentration:Sapphire wafer and silicon carbide sourcing dependence on Chinese and Taiwanese foundries creates input cost volatility for domestic packaging operations.
- Incumbent Fluorescent Infrastructure:Existing ballast-compatible fixture stock and maintenance contractor relationships slow conversion velocity in institutional buildings with multi-year maintenance contracts.
Strategic Opportunities
- Central Highlands Commercial Construction:Da Lat and Buon Ma Thuot retail and hospitality development remains underpenetrated by connected lighting systems, creating first-mover positioning for integrated controls vendors.
- Human-Centric Circadian Lighting:Tunable white and melanopic lux management systems converge with workplace wellness programs in Hanoi Grade-A office developments.
- E-Commerce Platform Expansion:Tier-two city electrical distributors in Can Tho and Hue are migrating procurement to B2B marketplaces, disintermediating traditional wholesale channels.
Industry Challenges
- EMC Pre-Compliance Testing:CISPR 15 electromagnetic compatibility certification timelines extend product launch schedules, particularly for wireless-enabled smart luminaires with integrated RF modules.
- Legacy DALI-1 Integration:Existing building automation systems running first-generation digital addressable lighting interface protocols require gateway hardware for seamless LED fixture commissioning.
- Optical Design Talent Scarcity:Secondary optics and thermal management engineering capacity concentrates in Ho Chi Minh City, constraining northern manufacturer R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam LED Lighting Market |
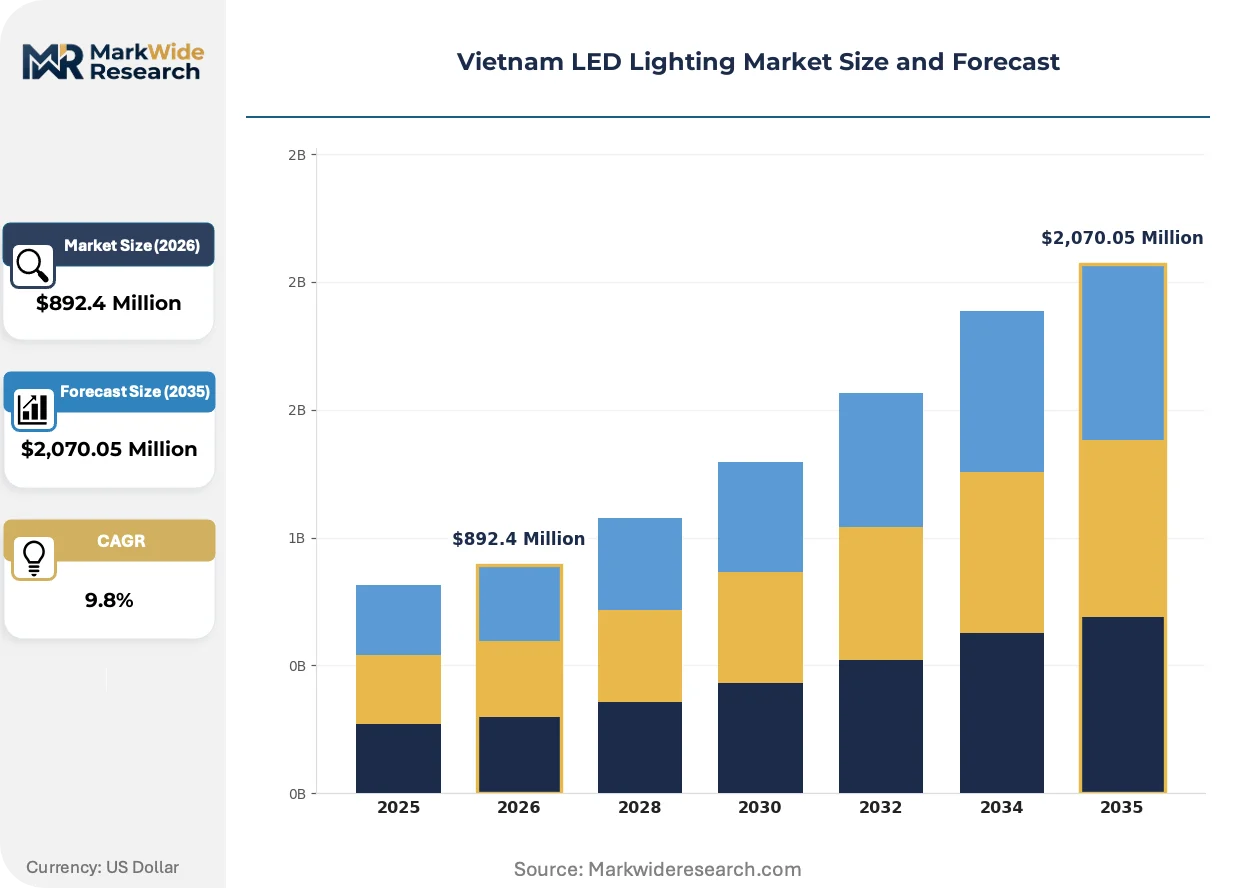
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $2,070.05 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Panels Technology: Smart Lighting, RGB, Tunable White, Dimmable End User: Residential, Commercial, Industrial, Outdoor Installation: New, Retrofit, Integrated, Temporary |
| Companies Covered | Dien Quang, Rang Dong, PARAGON, Signify, Philips, Samsung Electronics, Panasonic, Asled, VINALED, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam LED Lighting Market Strategic Shifts & Innovations
Sensor-integrated controls and IoT connectivity are redefining value capture in Vietnam's LED sector, shifting revenue from hardware shipment to ongoing data services and energy management subscriptions.
Chip-on-board LED modules are collapsing the traditional distinction between lamp and luminaire manufacturing. Commercial contractors in Hanoi office towers specify integrated thermal management and optical systems rather than socketed replacements. This compression eliminates the aftermarket bulb channel for new construction, concentrating margin capture with fixture-integrated suppliers.
The Ministry of Construction's mandatory LED adoption provisions for new public structures are tightening efficacy thresholds for building permit approval. Municipal hospital and school construction in Da Nang and Hai Phong now requires third-party photometric verification. Foreign suppliers without Vietnam-registered testing laboratory partnerships face extended compliance timelines.
Facility managers in northern industrial zones are unbundling lighting maintenance from comprehensive mechanical service contracts. Electronics manufacturers in Bac Giang and Vinh Phuc provinces now source LED retrofit directly through platform procurement rather than general contractor pass-through. This disintermediation compresses pricing transparency and accelerates supplier switching cycles.
Vietnam LED Lighting Market Segmentation
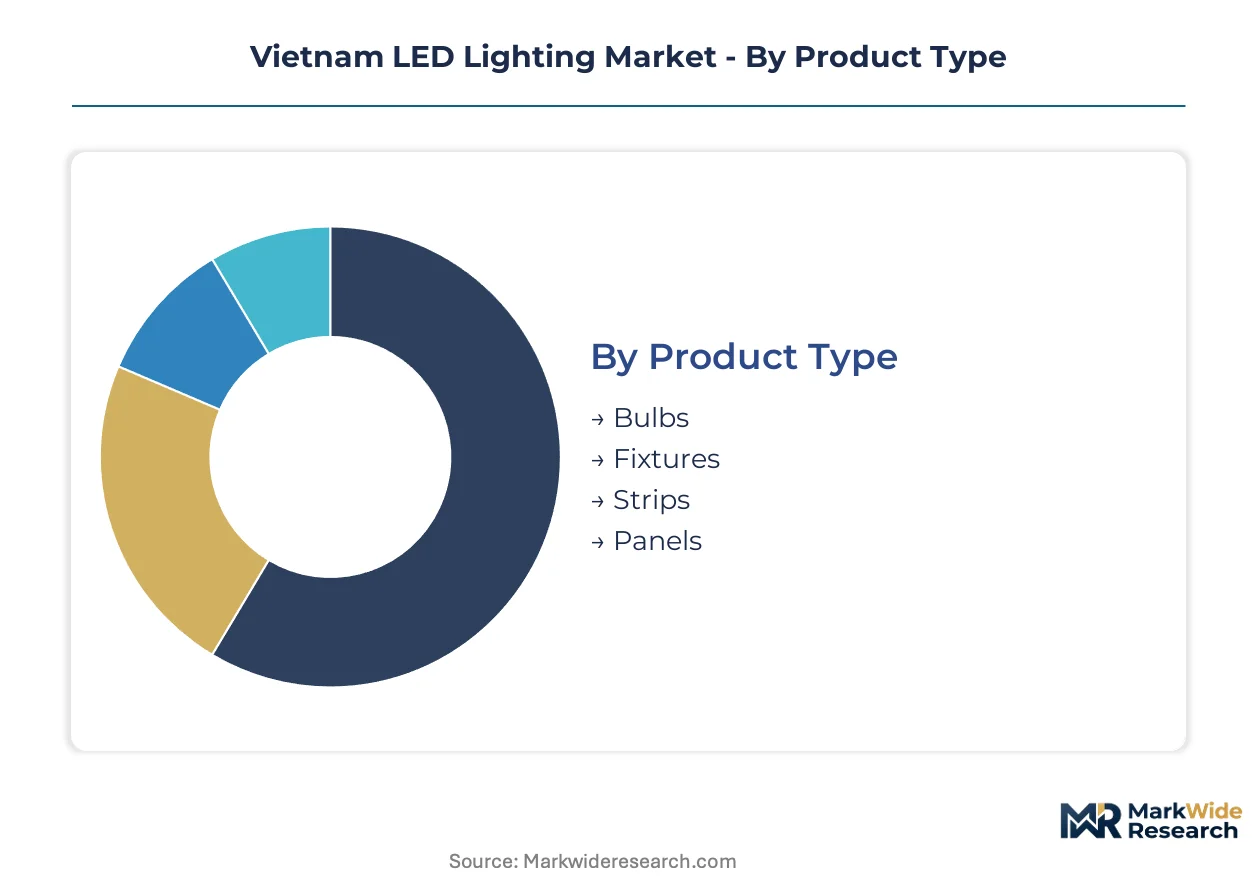
Vietnam's LED lighting market fragments across four dimensions that determine procurement patterns, margin structures, and technology adoption curves. Product type and installation method shape volume distribution, while technology tier and end-user category drive value concentration. Understanding these splits reveals where domestic manufacturers compete on cost versus where foreign suppliers command premium positioning.
Product Type:
Use-case spectrum spans residential socket replacements through commercial integrated systems, with fixture architecture determining supply chain configuration and pricing power.
- Fixtures:Integrated thermal management and optical systems eliminate lamp-luminaire distinction. Commercial contractors in Hanoi Grade-A office towers specify these for new construction, compressing aftermarket bulb channels and concentrating margin with integrated suppliers.
- Panels:Surface-mounted and recessed flat-panel designs dominate office and retail verticals. Da Nang municipal hospital construction now requires third-party photometric verification for these units under Ministry of Construction energy codes.
- Bulbs:Edison and bayonet retrofit lamps retain mass-market penetration in residential channels across tier-two cities. E-commerce platforms serving Can Tho and Hue electrical distributors drive volume here.
- Strips:Flexible PCB-mounted emitters serve architectural accent and cove lighting applications. Hospitality developments in Da Lat and Buon Ma Thuot deploy these for ambient illumination.
The dominant share belongs to Fixtures, while Panels is closing the gap fastest.
Technology:
Cost tier stratification separates commodity emitters from connected systems with recurring service revenue potential.
- Smart Lighting:Sensor-integrated controls with IoT connectivity enable energy management subscriptions and data services. Signify sustains leadership here for commercial installations requiring DALI-2 commissioning and wireless RF modules.
- Tunable White:Melanopic lux management systems converge with workplace wellness programs. Hanoi Grade-A office developments specify these for circadian rhythm optimization.
- Dimmable:Phase-cut and 0-10V control compatibility addresses existing building automation retrofits. Legacy DALI-1 integration challenges require gateway hardware for seamless commissioning.
- RGB:Multi-channel color mixing serves hospitality and entertainment venues. Central Highlands retail development remains underpenetrated here.
Smart Lighting commands the value premium, though Tunable White is expanding most quickly in commercial specifications.
End User:
Customer type determines specification authority, procurement channel, and replacement cycle velocity.
- Commercial:Real estate developers in Ho Chi Minh City and Hanoi accelerate fixture replacement cycles ahead of Ministry of Construction energy code enforcement deadlines. Direct-contractor relationships dominate procurement.
- Industrial:Northern provinces including Bac Ninh and Hai Phong host concentrated factory conversion initiatives targeting metal halide and fluorescent replacement. Facility managers here are unbundling lighting from comprehensive mechanical service contracts.
- Residential:Mass-market bulb demand concentrates in urban households and tier-two city electrical distributors migrating to B2B marketplaces.
- Outdoor:Street and area lighting falls under municipal procurement with efficacy mandates from the Vietnam Standards and Quality Institute.
Commercial holds the installed base leadership, with Industrial gaining share fastest through northern zone retrofit programs.
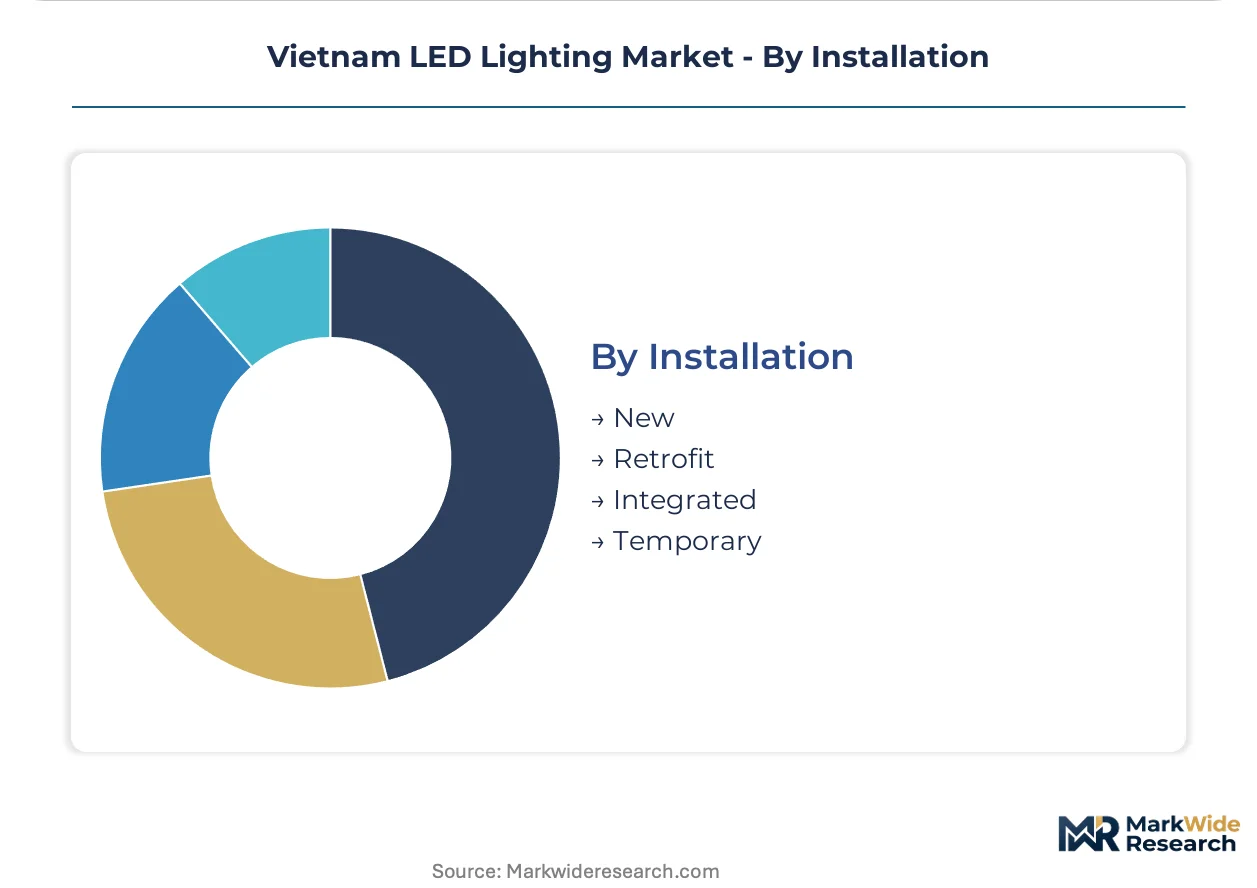
Installation:
Volume-maturity split separates legacy stock replacement from new construction specification opportunities.
- Retrofit:Existing building stock undergoes efficiency-driven fluorescent-to-LED conversion across northern industrial zones. Electronics manufacturers in Bac Giang and Vinh Phuc provinces source these directly through platform procurement.
- New:Construction permit approval now mandates minimum luminous efficacy thresholds for public structures. Municipal school construction in Hai Phong requires QCVN-certified products.
- Integrated:Chip-on-board modules collapse traditional lamp-luminaire boundaries, eliminating socketed replacements for new commercial towers.
- Temporary:Event and construction site lighting represents opportunistic demand with minimal specification barriers.
Retrofit dominates current volume, though Integrated is climbing the fastest as new construction specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in northern industrial provinces where factory retrofit density compresses margins, while southern commercial hubs in Ho Chi Minh City sustain premium fixture specifications. This geographic asymmetry shapes procurement channel configuration and supplier profitability across Vietnam.
Red River Delta
Bac Ninh and Hai Phong electronics manufacturers drive concentrated LED retrofit demand through unbundled lighting procurement. The Ministry of Industry and Trade's national energy efficiency programs subsidize industrial facility conversions here. Vinh Phuc province hosts electronics assembly clusters where facility managers source LED directly through platform procurement rather than mechanical contractor pass-through.
Northern Midlands and Mountain Areas
Thai Nguyen and Phu Tho provinces anchor emerging industrial zone development with new construction permit mandates. The Ministry of Construction enforces minimum luminous efficacy thresholds for public structure approvals in this zone. Bac Giang electronics manufacturing corridors specify chip-on-board modules for new commercial tower construction.
Southeast
Ho Chi Minh City Grade-A office developments accelerate fixture replacement cycles ahead of energy code enforcement deadlines. The Vietnam Standards and Quality Institute administers QCVN certification requirements that gate market access for imported products. Binh Duong and Dong Nai industrial provinces host fluorescent-to-LED conversion programs targeting metal halide replacement in manufacturing facilities.
Red River Delta (Hanoi Metropolitan)
Hanoi commercial real estate developers specify tunable white systems for workplace wellness programs in new office towers. The Ministry of Construction building energy codes mandate LED adoption in new public structures across the capital region. Grade-A developments in Cau Giay and Nam Tu Liem districts require third-party photometric verification for panel installations.
Central Highlands
Da Lat and Buon Ma Thuot hospitality developments deploy LED strips for architectural accent lighting with minimal connected systems penetration. Municipal hospital and school construction in Da Nang requires QCVN-certified products under tightening efficacy thresholds. Retail development across Lam Dong and Dak Lak provinces remains underpenetrated by integrated controls vendors.
Vietnam LED Lighting Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in chip packaging and thermal management. The vendor base organizes around three strategic archetypes: domestic manufacturers with captive assembly footprints, regional electronics conglomerates with backward integration into semiconductor sourcing, and multinational lighting systems providers with connected controls portfolios. Competitive moves concentrate on local assembly establishment to navigate import duty structures and laboratory partnerships to compress QCVN certification timelines.
Among domestic Vietnamese manufacturers, Dien Quang and Rang Dong occupy anchor positions across the supplier landscape. Dien Quang exemplifies the domestic manufacturing archetype with pricing power anchored in northern provincial distribution. Rang Dong represents backward integration into LED chip packaging, a structural position that insulates input cost volatility. Signify sits within the multinational systems tier, exemplifying technology leadership in connected lighting architectures for commercial installations. These three patterns—domestic assembly scale, upstream component control, and systems integration—define competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Dien Quang |
| Rang Dong |
| PARAGON |
| Signify |
| Philips |
| Samsung Electronics |
| Panasonic |
| Asled |
| VINALED |
| Others |
Cost & Logistics Intelligence
Hai Phong Port container freight corridors from Shenzhen and Kaohsiung govern landed cost differentials between imported finished luminaires and component kits, compressing margins for direct shipment while rewarding local assembly operations that exploit the duty spread between packaged products and unpackaged emitters.
Pricing Analysis
Configured-to-order pricing for tunable white and DALI-2 commissioned systems commands a 40-60% premium over standard panel and bulb SKUs in residential channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by QCVN certification grade and photometric verification status, with foreign suppliers bearing extended compliance timelines. Cost compression in the bulb tier intensifies as e-commerce platforms disintermediate wholesale markups in Can Tho and Hue. Industrial facility managers in Bac Ninh exhibit the highest price sensitivity, while Grade-A office developers in Hanoi prioritize performance specifications over unit economics.
Supply Chain Analysis
Supplier-financing facilities from Taiwanese sapphire wafer foundries and Chinese gallium nitride epitaxy houses extend 90-120 day payment terms to domestic Vietnamese packaging operations. Input sourcing concentrates in China, Taiwan, and South Korea for substrates, phosphors, and driver ICs. The supply chain draws from concentrated sapphire wafer and silicon carbide dependencies that create single-source vulnerability during foundry allocation cycles. Distribution runs through direct-contractor relationships in commercial new construction and B2B marketplace platforms for industrial retrofit procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's LED lighting market demands substitution defense against OLED panel technology and human-centric lighting systems that could displace conventional fixture architectures in premium commercial specifications.
For Market Incumbents: Build regulatory certification moats through Vietnam-registered testing laboratory partnerships that compress QCVN compliance timelines for wireless-enabled smart luminaires. Anchor pricing power in northern provincial distribution networks while defending against platform disintermediation through exclusive contractor relationships in Ho Chi Minh City Grade-A developments. Capacity addition in Bac Giang electronics corridors secures proximity to unbundled procurement from facility managers. For New Entrants and Emerging Players: Establish a beachhead in Central Highlands hospitality lighting where Da Lat and Buon Ma Thuot retail developments remain underpenetrated by connected controls vendors. Target tunable white specifications for workplace wellness programs in Hanoi office towers as the fastest-expanding technology tier. Deploy B2B marketplace presence in tier-two city electrical distribution to bypass incumbent wholesale channel control. For Investors and Strategic Acquirers: Domestic fixture-integrated suppliers with captive thermal management engineering capacity in Ho Chi Minh City represent the most defensible acquisition archetype for long-term positioning across the analysis window. Monitor QCVN efficacy threshold tightening announcements from the Ministry of Construction as the primary inflection signal for import-dependent foreign supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Packaging | Rang Dong's sapphire wafer sourcing control insulates margin volatility from Taiwanese foundry allocation cycles. |
| QCVN Certification Laboratory Partnership | Foreign suppliers with Vietnam-registered testing capacity compress photometric verification timelines for municipal hospital construction. |
| B2B Marketplace Platform Expansion | Electrical distributors in Can Tho and Hue migrating procurement online disintermediate traditional wholesale channel markups. |
| Human-Centric Circadian Lighting Development | Tunable white systems with melanopic lux management capture workplace wellness program budgets in Hanoi Grade-A offices. |
| Direct-Contractor Relationship Deepening | Exclusive specification agreements with Ho Chi Minh City commercial developers defend against platform-driven supplier switching. |
Research Approach
Initial hypotheses were tested against primary input from commercial real estate developers, industrial facility managers, electrical distribution channel partners, and Ministry of Construction regulatory affairs specialists, then refined through secondary validation against Vietnam Standards and Quality Institute certification databases, Ministry of Industry and Trade energy efficiency program disclosures, and customs import records for LED component and finished luminaire trade flows. Bottom-up demand modeling from retrofit installation volumes and new construction permit data was triangulated against top-down supply capacity assessments from domestic manufacturer assembly footprints.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, technology tier, end-user category, and installation method. CAGRs were derived from installed base replacement velocity curves and new construction specification hardening trends, incorporating gallium nitride chip efficiency gain assumptions and QCVN regulatory tightening schedules as industry-specific forecast inputs.
Stress conditions across sapphire wafer pricing volatility, QCVN certification timeline extensions, and northern industrial zone retrofit program subsidy levels were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding efficacy threshold enforcement and platform procurement adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Linear LED Strip Fixture Market
LED
LED Panel Light Drivers Market
LED
UK Indoor LED Lighting Market
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
LED Flip Chip Market
LED
LED and OLED Display Market
LED
Global Outdoor LED Lighting Market
LED
Micro LED Display Market
LED
Monochrome Outdoor LED Display Market
LED
Japan Outdoor LED Lighting Market
LED
LED Driver Market
LED
Programmable LED Drivers Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
Architectural LED Products Market
LED
North America LED Packaging Market
LED
Led Video Walls Market