
 Asia Pacific MV and HV Underground Cables and Accessories Market | 2026-2036
Asia Pacific MV and HV Underground Cables and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific MV and HV Underground Cables and Accessories Market Intelligence
India's expanding manufacturing capacity for high-voltage cables is reshaping competitive positioning within the Asia Pacific region. LS Cable & System leverages its scale in South Korea to supply major regional projects. Prysmian Group competes on technology leadership in extra-high voltage applications. Meanwhile, Kei Industries anchors its strategy on serving India's domestic utility and industrial sectors.
MV and HV underground cables are electrical conductors designed for subterranean power transmission, typically insulated with cross-linked polyethylene (XLPE) to handle voltages from 1kV up to 500kV. Their primary purpose is to deliver electricity reliably in densely populated urban areas and for grid interconnections where overhead lines are impractical. The utilities end-user segment commands the largest share, driven by grid expansion and replacement cycles. High voltage cables made with cross-linked polyethylene represent the fastest-growing product and material combination due to superior dielectric properties.
Product standards across Asia Pacific are governed by national bodies such as China's GB standards and India's Bureau of Indian Standards (BIS). These regulations dictate material specifications, fire retardancy, and testing protocols, directly influencing market access and manufacturing costs. Navigating the patchwork of national standards versus adopting broader IEC norms remains a core strategic decision for cable manufacturers.
Market Dynamics
The market's central dynamic is the tension between rapid urbanization driving demand for subterranean power infrastructure and the fragmented regulatory landscape across Asia Pacific, which complicates product development and market access for manufacturers.
Growth Catalysts
- Grid Modernization Mandates:National policies, such as China's dual carbon goals, compel utility operators to invest in high-capacity underground cables to support grid stability and integrate renewable energy sources.
- Urban Infrastructure Expansion:Significant infrastructure development in dense urban centers, particularly in India and Southeast Asia, necessitates the use of underground cables where overhead lines are impractical or unsafe.
- Material and Design Advancement:The adoption of cross-linked polyethylene (XLPE) insulation for high voltage applications provides superior dielectric strength and thermal performance, enabling more efficient and reliable power transmission.
Market Restraints
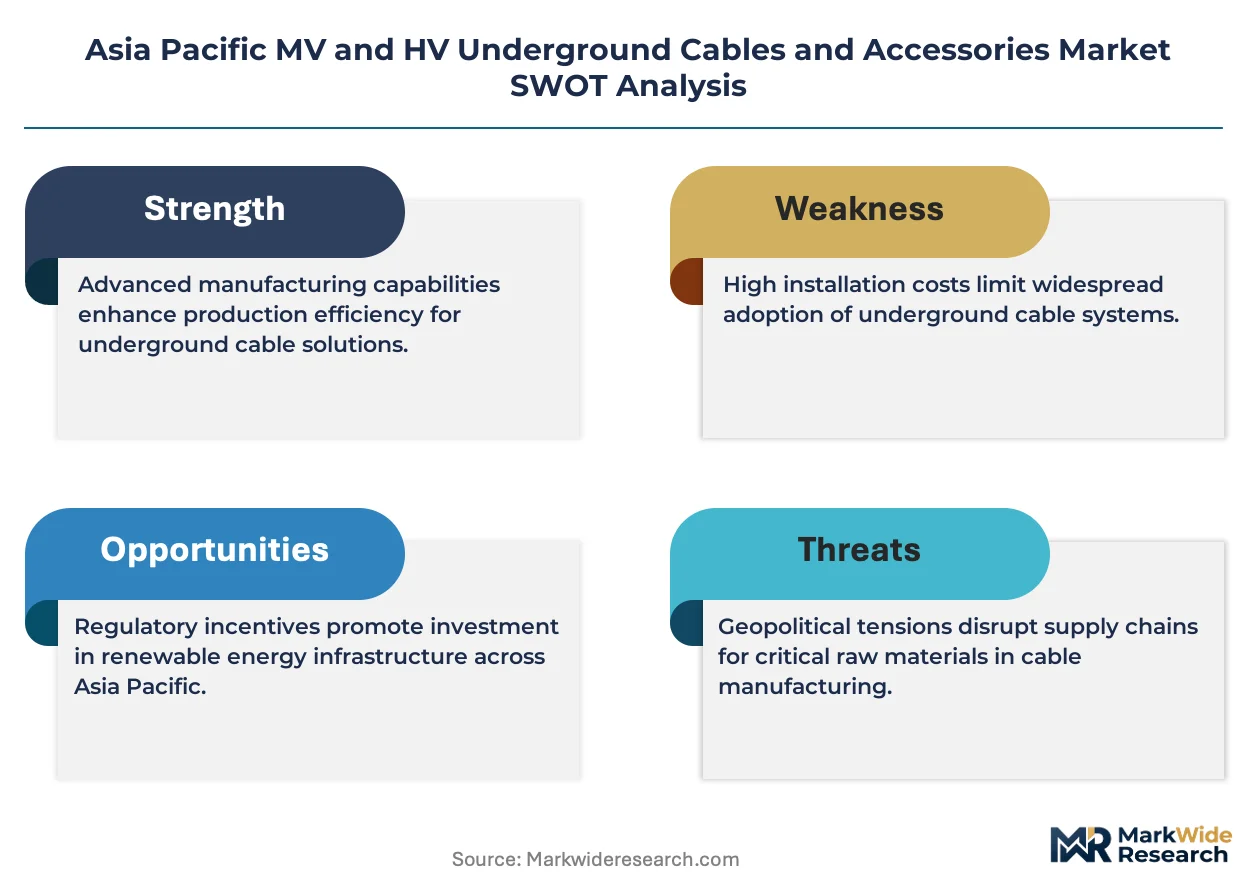
- High Initial Capital Outlay:Underground cable projects involve substantial upfront costs related to civil engineering works, including excavation, trenching, and reinstatement, which can be prohibitive compared to overhead lines.
- Regulatory Fragmentation:The lack of harmonization between national standards, such as China's GB standards and India's BIS, and global IEC norms creates compliance burdens and increases manufacturing costs for regional suppliers.
- Raw Material Price Volatility:The market is exposed to price fluctuations for key raw materials like high-purity copper and aluminum, impacting project costs and manufacturer margins.
Strategic Opportunities
- Offshore Wind Integration:The development of large-scale offshore wind farms across the region, especially in Taiwan and South Korea, creates demand for specialized high-voltage subsea and underground export cables.
- Smart Cable Technologies:Integrating fiber optic sensors into cable designs for real-time temperature and strain monitoring offers a new value proposition centered on predictive maintenance and asset management for utilities.
- Grid Interconnection Projects:Cross-border grid interconnection initiatives, such as those planned within the ASEAN Power Grid, present opportunities for extra-high voltage underground and subsea cable systems.
Industry Challenges
- Installation Complexity:Executing underground cable projects in congested urban environments requires complex logistical planning and coordination with multiple municipal agencies, leading to potential delays and cost overruns.
- Specialized Skill Shortages:A deficit of trained technicians and engineers proficient in the specialized tasks of HV cable jointing, termination, and testing poses a significant operational bottleneck for project execution.
- Lengthy Certification Cycles:The process of obtaining product certification from national bodies like the Bureau of Indian Standards (BIS) can be time-consuming, delaying market entry for new products and technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific MV and HV Underground Cables and Accessories Market |
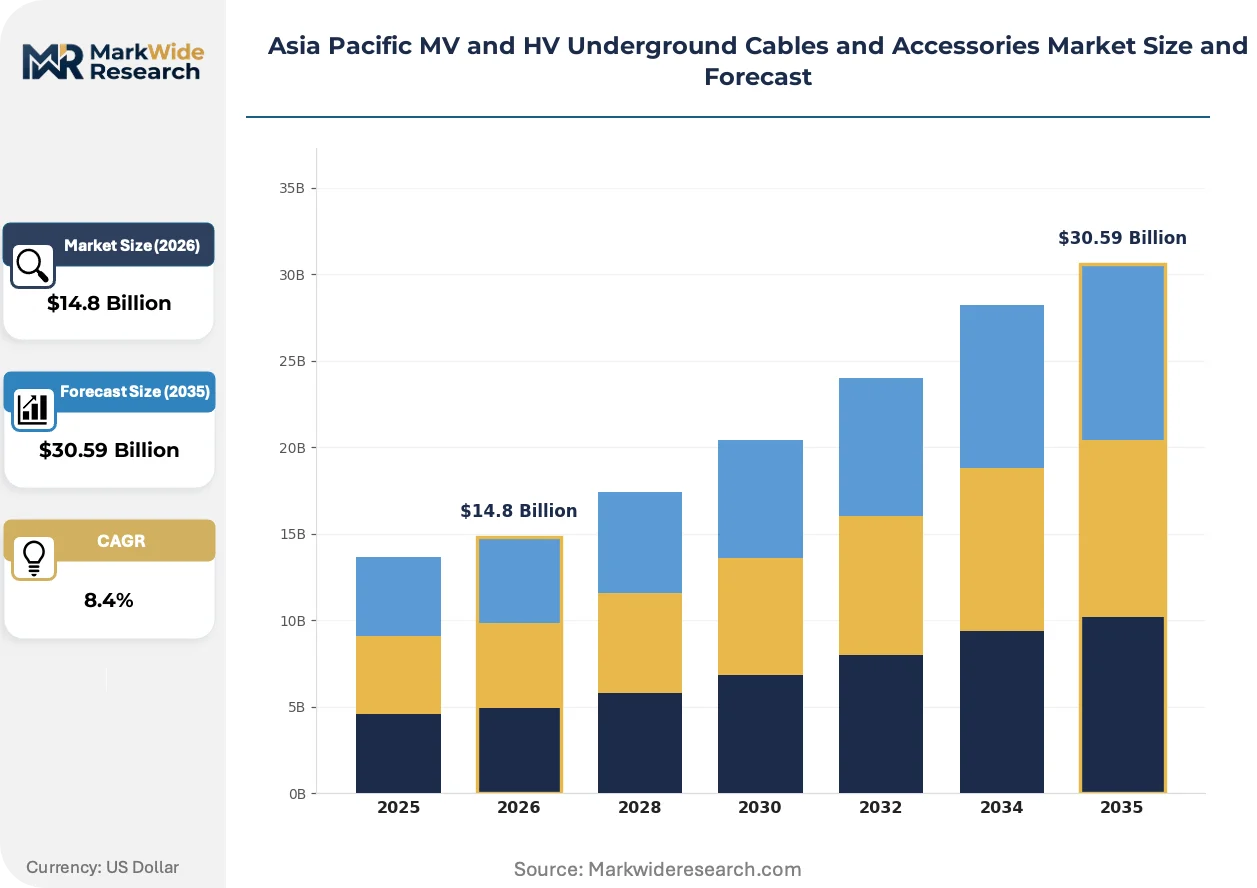
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage Cables, High Voltage Cables, Accessories, Terminations Installation Type: Direct Burial, Trench, Duct, Aerial End User: Utilities, Industrial, Commercial, Residential Material: Copper, Aluminum, PVC, Cross-Linked Polyethylene |
| Companies Covered | LS Cable & System, ABB, Prysmian Group, Tratos Cavi, El Sewedy Electric, Nexans, NKT, Kei Industries, Sumitomo Electric, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific MV and HV Underground Cables and Accessories Market Strategic Shifts & Innovations
Technological advancements in materials and digitalization are transforming cable systems from passive components into intelligent network assets. This shift aligns with utility demands for greater grid visibility, reliability, and operational efficiency in managing complex power flows from renewable sources.
Digital Twin technology, which creates a dynamic virtual model of a physical cable network, is gaining traction. Utility operators and grid asset managers are the primary adopters, using it for scenario planning and operational oversight. This technology is virtualizing the physical infrastructure, enabling predictive failure analysis and optimizing power dispatch without direct physical testing or intervention on the live network.
China's comprehensive "dual carbon" policy framework is a significant regulatory driver. The policy mandates accelerated integration of renewable energy, which in turn requires substantial grid reinforcement and expansion. The high-voltage direct current (HVDC) cable segment is most impacted, as these systems are essential for transmitting power from remote solar and wind installations to major industrial and population centers.
A notable behavioral shift is occurring in how large-scale projects are procured, with utilities moving from component purchasing to awarding full turnkey contracts. This approach displaces the traditional model where the utility managed separate vendors for cables, accessories, installation, and commissioning. This trend is most prominent in major grid upgrades in Australia and India, where clients prioritize transferring project risk to a single engineering, procurement, and construction contractor.
Asia Pacific MV and HV Underground Cables and Accessories Market Segmentation
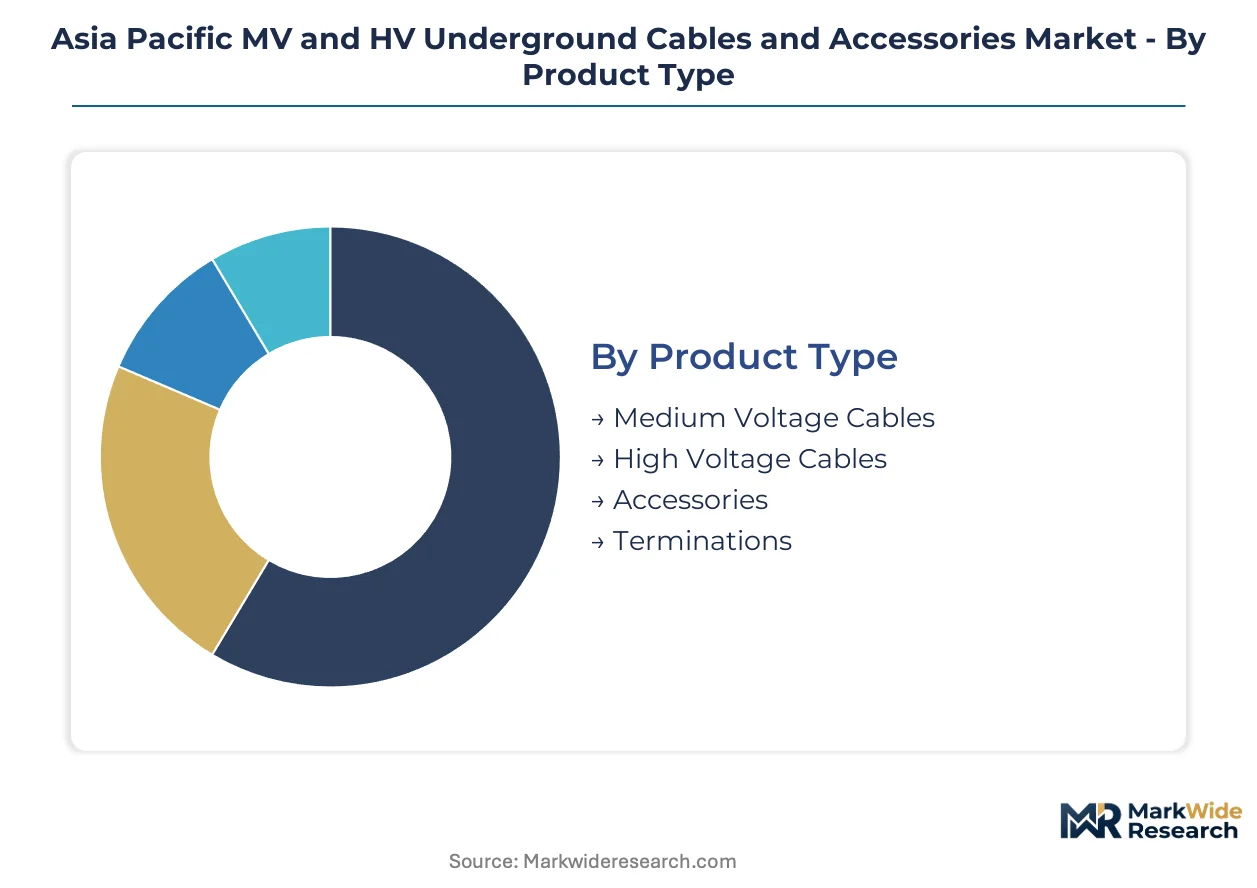
Understanding the segmentation within the Asia Pacific MV and HV Underground Cables and Accessories Market is crucial for identifying precise demand pockets and tailoring product development. Each segment reflects distinct operational requirements, technological preferences, and investment cycles across the region.
Product Type:
The after-sales-service intensity varies significantly across product types, influencing manufacturer support structures and customer engagement models.
- Medium Voltage Cables:These cables transmit electricity at voltages typically between 1kV and 36kV, commonly insulated with XLPE or EPR. Demand concentrates in urban infrastructure expansion projects in India and Southeast Asia, driven by the need for reliable power distribution in densely populated areas.
- High Voltage Cables:Designed for power transmission from 36kV up to 500kV, these cables predominantly utilize XLPE insulation for superior dielectric strength. China’s dual carbon goals and large-scale renewable energy integration projects necessitate high voltage cables for grid reinforcement and long-distance transmission.
- Accessories:This segment includes essential components like joints, connectors, and terminations vital for cable installation and network integrity. Utility operators in Australia and India require robust accessories to ensure seamless integration and long-term reliability of underground networks.
- Terminations:These specialized devices provide reliable sealing and electrical connection points for cables at substations or overhead line transitions. Grid interconnection initiatives within the ASEAN Power Grid demand high-performance terminations for extra-high voltage systems.
Medium Voltage Cables hold the largest share; momentum sits with High Voltage Cables.
Installation Type:
The cost tier associated with different installation types significantly impacts project budgeting and execution timelines across Asia Pacific.
- Direct Burial:This method involves laying cables directly into the ground, often requiring robust sheathing for protection against environmental factors. Rural grid expansion projects in India frequently employ direct burial due to its relatively lower civil engineering costs and faster deployment.
- Trench:Cables are installed within excavated trenches, often with protective layers of sand or concrete, providing enhanced physical protection. Major urban infrastructure developments in China and utility upgrade programs prioritize trench installations for their reliability and ease of future access.
- Duct:This approach utilizes pre-installed conduits or pipes underground, allowing for easier cable replacement or additional installations without extensive re-excavation. Densely populated urban centers in South Korea and Taiwan favor duct systems for their flexibility and minimal disruption.
- Aerial:Cables are suspended overhead on poles or towers, a method typically used in less congested areas or for specific industrial applications. Remote grid connections in parts of Southeast Asia still rely on aerial installations for their cost-effectiveness and simpler deployment.
Trench installations collectively account for the largest volume in urban developments, while Direct Burial methods offer cost advantages in less congested areas.
End User:
Application diversity within the end-user segments dictates specific cable requirements, from voltage ratings to environmental resistances.
- Utilities:This segment encompasses national grid operators and regional distribution companies responsible for power transmission and distribution. China's national policies and India's rapid urbanization compel utilities to invest in high-capacity underground cables for grid stability and renewable energy integration.
- Industrial:Industrial end-users, including manufacturing plants, mining operations, and large commercial complexes, require reliable power supply for their operations. Manufacturing hubs across Southeast Asia demand robust underground cabling to ensure uninterrupted power for heavy machinery and critical processes.
- Commercial:This segment includes office buildings, shopping centers, and data centers that require secure and aesthetic power delivery. Urban development projects in major cities like Singapore and Tokyo utilize underground cables to avoid visual clutter and enhance safety.
- Residential:Housing developments and local community power distribution networks fall under this category, focusing on safety and cost-effectiveness. New residential complexes in rapidly expanding cities across Asia Pacific increasingly opt for underground cabling for improved aesthetics and reliability.
The Utilities segment is heavily influenced by national policies and grid modernization mandates, driving significant capital expenditure.
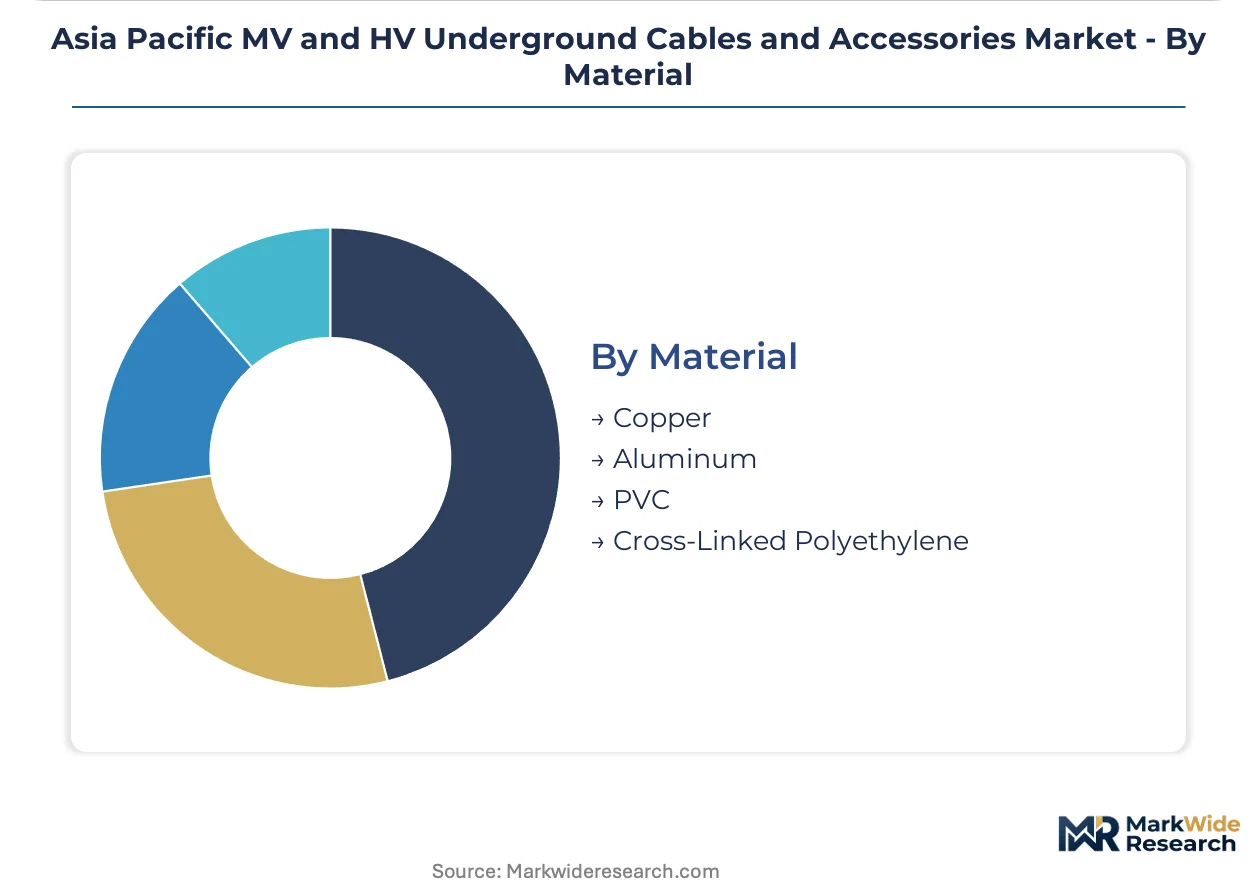
Material:
Supply concentration for key raw materials directly influences manufacturing costs and price stability across the Asia Pacific region.
- Copper:A traditional conductor known for its high electrical conductivity and ductility, copper remains widely used in various cable applications. Established distribution networks and urban redevelopment projects in India continue to rely on copper due to its proven performance and widespread availability.
- Aluminum:Offering a lighter weight and more cost-effective alternative to copper, aluminum is often used for larger cross-section cables and overhead lines. Utility projects in emerging economies across Asia Pacific leverage aluminum for its economic benefits in extensive grid deployments.
- PVC:Polyvinyl chloride is a common insulation material for lower voltage cables due to its cost-effectiveness, flexibility, and good insulation properties. General purpose and residential cabling in various Asia Pacific markets frequently utilize PVC for its balance of performance and price.
- Cross-Linked Polyethylene:XLPE is the fastest-growing insulation material for high voltage applications, valued for its superior dielectric properties, thermal performance, and long operational life. New grid interconnections in Taiwan and offshore wind projects in South Korea extensively use XLPE for efficient and reliable power transmission.
Cross-Linked Polyethylene (XLPE) is driving a technological shift towards more efficient and reliable high-voltage power transmission.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration within the Asia Pacific MV and HV Underground Cables and Accessories market is notable for its diverse manufacturing bases. Key regional manufacturers leverage distinct strengths to meet the expanding infrastructure needs. This market dynamic shapes investment and product development strategies across the region.
China
China's demand for high voltage cables stems from its ambitious dual carbon goals, which necessitate substantial grid reinforcement. The country's GB standards dictate material specifications and testing protocols, influencing manufacturing processes. Major infrastructure projects in the Yangtze River Delta region require extensive underground cabling for urban power distribution and renewable energy integration.
India
India's rapid urbanization drives significant demand for MV and HV underground cables, particularly for modernizing urban power grids. The Bureau of Indian Standards (BIS) regulates product quality and safety, ensuring compliance for market access. Infrastructure development in cities like Mumbai and Delhi fuels the need for reliable subterranean power networks.
South Korea
South Korea's focus on offshore wind integration and grid interconnections generates demand for specialized high-voltage subsea and underground cables. National utility investments prioritize advanced XLPE insulation for enhanced grid stability. Urban centers like Seoul and Busan favor duct systems for their flexibility and minimal disruption during cable installation.
Australia
Australia's grid upgrade programs and renewable energy integration initiatives require robust underground cables and accessories. The country's regulatory environment emphasizes long-term reliability and safety for critical infrastructure projects. Major metropolitan areas such as Sydney and Melbourne are undertaking significant undergrounding projects to improve aesthetic appeal and power delivery.
Asia Pacific MV and HV Underground Cables and Accessories Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the Asia Pacific MV and HV Underground Cables and Accessories market. The competitive landscape shows a tiered structure, with global players alongside regional specialists and local fabricators. Strategic archetypes include large-scale integrators focusing on turnkey solutions, technology-focused innovators pushing extra-high voltage boundaries, and cost-efficient domestic suppliers serving specific national demands. Capacity expansion to meet rising demand and strategic partnerships for technology transfer are dominant competitive moves.
Within the scale-driven segment, LS Cable & System leverages its established South Korean manufacturing scale and extensive product portfolio for major regional projects, representing a global-tier player with significant production capabilities. Prysmian Group, a global entity headquartered in Europe, exemplifies technology leadership in extra-high voltage applications, often competing on specialized product performance, innovation, and project execution capabilities for complex grid infrastructure. Kei Industries anchors its strategy on serving India's domestic utility and industrial sectors, reflecting a strong national focus and deep understanding of local market requirements and regulatory frameworks.
| Leading Market Players |
|---|
| LS Cable & System |
| ABB |
| Prysmian Group |
| Tratos Cavi |
| El Sewedy Electric |
| Nexans |
| NKT |
| Kei Industries |
| Sumitomo Electric |
| Others |
Cost & Logistics Intelligence
Raw material price volatility significantly determines both pricing tier spreads and the fragmented supply chain shape in the Asia Pacific MV and HV underground cables market.
Pricing Analysis
China's GB standards and India's BIS dictate the pricing tier structure for MV and HV cables. The dominant pricing model is project-based, often involving long-term contracts with utilities. Price differentiation stems from certification level, specific customization for extra-high voltage applications, and bundled after-sales service for turnkey solutions. Raw material volatility exerts pricing pressure across all product tiers, though utilities prioritize reliability over cost for critical grid infrastructure, making them less price-sensitive than residential developers.
Supply Chain Analysis
Commodity price volatility for high-purity copper and aluminum dominates the raw material supply chain for MV and HV cables. Geographic supply concentrates in China, South Korea, and India for finished products, but raw material sourcing is global. Key dependencies include cross-linked polyethylene (XLPE) for insulation and specialized components for accessories. Downstream distribution runs through direct sales to utility operators and large engineering, procurement, and construction (EPC) contractors for major infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific MV and HV underground cables market exhibits a buyer power shift, driven by utilities consolidating procurement into full turnkey contracts.
For Market Incumbents: Build technological leadership in extra-high voltage and specialized subsea cables to counter emerging competition in standard MV segments. Investment in advanced XLPE material science and robust testing certifications, particularly for offshore wind projects, creates a strong defensive moat. Expanding turnkey project execution capabilities also mitigates the threat of new entrants offering component-level solutions.
For New Entrants and Emerging Players: Build out specialized offerings in smart cable technologies and integrated fiber optic sensors to address unmet utility needs. The most penetrable segment lies within regional MV distribution projects in rapidly urbanizing areas of Southeast Asia. A focused go-to-market angle emphasizing predictive maintenance and enhanced grid visibility can differentiate smaller players.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialists in HVDC and subsea cable systems. Long-term viability is strong, anchored by sustained grid modernization and renewable energy integration. Acquisition targets should include innovators in smart cable technologies or firms with strong regional certification portfolios. The project pipeline for offshore wind farms in Taiwan and South Korea serves as a key signal to watch for accelerated investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Turnkey Project Capabilities | Addresses utility demand for single-contract project risk transfer in grid upgrades. |
| Invest in XLPE Material R&D | Enhances cable performance and reliability for high-voltage and subsea applications. |
| Develop Smart Cable Integration | Offers utilities real-time monitoring for predictive maintenance and asset management. |
| Strengthen Regional Certification | Ensures market access and compliance with diverse national standards across Asia Pacific. |
| Target Offshore Wind Cable Systems | Capitalizes on growing renewable energy infrastructure needs in specific geographies. |
Research Approach
A standing panel of utility planning officers, EPC contractors, cable manufacturers, and material suppliers provided ongoing calibration of market dynamics. This primary research was triangulated with extensive secondary validation from national standards bodies like India's BIS and China's GB standards, industry associations, and company filings. The approach combined bottom-up data aggregation with top-down market sizing.
Scenario-bracketing framed the analytical framework across the analysis window, considering various growth trajectories. Segmentation dimensions modeled included product type, installation type, end user, material, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected market drivers such as grid modernization mandates, urbanization rates, and renewable energy deployment targets.
Sensitivities concentrate around geopolitical shifts, raw material price volatility, and evolving national regulatory changes. Forecasts reflect assumptions regarding these factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Mineral Insulated (MI) Cable Market
Cables
Cable Organisers Market
Cables
Middle East Cable Market
Cables
Power and Signal Cables Market
Cables
Active Optical Cable Market
Cables
Electric Submersible Cables (ESP) Market
Cables
Electric Submersible Cable Sales Market
Cables
Radio Frequency Cables Market
Cables
Global Cable Blowing Equipment Market
Cables
Patch Cable Market
Cables
Sensing Cable Market
Cables
Cable Management Accessories Market
Cables
Fiber Optic Cable Materials Market
Cables
Copper Stranded Wire Market
Cables
XLPE Cables Market
Cables
Cable Market