
 Power Metering Market | 2026-2036
Power Metering Market Size, Share, and Industry Trends Forecast 2026-2036
Power Metering Market Intelligence
The EU Green Deal is restructuring procurement priorities across European utilities, compelling upgrades from AMR to full AMI architectures. Siemens AG leverages its automation portfolio to dominate integrated substation-to-meter solutions across German distribution networks. Landis+Gyr Group AG anchors the North American smart meter replacement cycle through long-term supply agreements with major investor-owned utilities. Wasion Group specializes in multi-function meters for China's State Grid Corporation, embedding power quality monitoring alongside standard billing functions.
Power metering encompasses devices that measure, record, and communicate electrical energy consumption with accuracy classes typically spanning 0.2S to 2.0 under IEC 62052-11 standards, serving billing reconciliation and grid stability functions. Smart meters now incorporate RF Mesh and cellular communication modules enabling 15-minute interval data transmission for real-time demand response orchestration. Electromechanical meters persist in emerging markets as lowest-first-cost options, though static meters with solid-state measurement cores capture margin pools in commercial and industrial segments where power quality analytics command premium pricing. AMI technology leads technology investment as utilities prioritize two-way communication for remote disconnect and time-of-use rate implementation.
The US Federal Energy Regulatory Commission and state public utility commissions mandate advanced metering infrastructure for demand response participation, while the EU F-Gas Regulation indirectly shapes meter enclosure specifications and communication module thermal design. China's National Energy Administration enforces GB standards for meter communication protocols, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving cybersecurity certification requirements for grid-connected devices as IEC 62351 standards mature and utility procurement specifications harden against network intrusion risks.
Market Dynamics
AMI-enabled smart meters are displacing electromechanical infrastructure as utilities face state-level renewable integration mandates and bidirectional communication requirements for distributed solar and EV load management.
Growth Catalysts
- EU Green Deal energy efficiency targets:The framework accelerates digital metering deployment across Germany, France, and Italy, compelling upgrades from AMR to full AMI architectures.
- China's State Grid Corporation modernization programs:Grid investments prioritize bidirectional communication protocols for distributed solar integration and electric vehicle load management.
- FERC and state public utility commission mandates:US regulations require advanced metering infrastructure for demand response participation, driving replacement cycles.
Market Restraints
- Semiconductor supply concentration:RF Mesh and cellular communication module production clusters in East Asian foundries, creating vulnerability to geopolitical disruption.
- IEC 62351 cybersecurity certification complexity:Evolving grid-connected device standards extend procurement timelines and raise compliance costs for non-domestic suppliers.
- Electromechanical meter substitution in price-sensitive segments:Static meters face cost competition from legacy electromechanical units in emerging markets where lowest-first-cost procurement dominates.
Strategic Opportunities
- Power quality analytics in commercial and industrial segments:Multi-function meters embedding harmonic monitoring and voltage sag detection command premium pricing in manufacturing and data center applications.
- India's smart city and rural electrification initiatives:Central Electricity Authority directives create procurement volume for prepaid metering and remote disconnect capabilities.
- Cellular LPWAN convergence with RF Mesh:Hybrid communication architectures reduce infrastructure deployment costs in low-density service territories.
Industry Challenges
- IEC 62052-11 accuracy class certification timelines:Testing laboratory capacity constraints delay product launches for 0.2S and 0.5S precision tiers.
- Legacy system integration complexity:Head-end system migration from proprietary protocols to DLMS/COSEM standards requires substantial middleware development.
- Field technician skill gaps in RF network commissioning:AMI deployment outpaces training pipeline for mesh network optimization and troubleshooting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Metering Market |
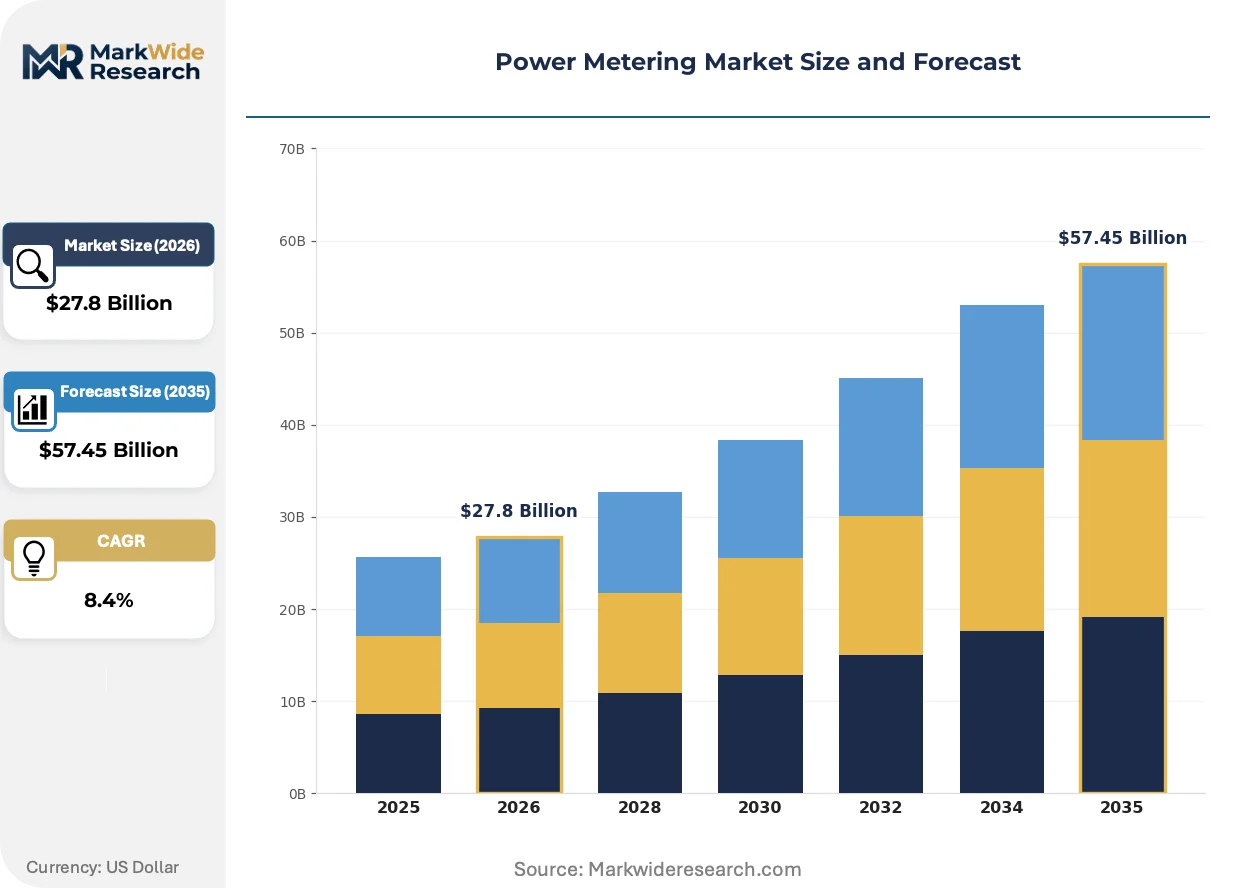
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $57.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meter, Electromechanical Meter, Static Meter, Prepaid Meter, Multi-Function Meter Technology: AMR, AMI, PLC, RF Mesh, Cellular Communication Application: Residential Monitoring, Commercial Billing, Industrial Energy Management, Grid Automation, Demand Response End User: Electric Utilities, Energy Service Companies, Meter Manufacturers, Facility Management Firms |
| Companies Covered | ABB Ltd., Siemens AG, Itron Inc., Aclara Technologies LLC, Kamstrup, Landis+Gyr Group AG, Honeywell International Inc., Wasion Group, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Metering Market Strategic Shifts & Innovations
Solid-state measurement cores with embedded power quality analytics are redefining competitive differentiation as utilities shift from energy-only billing to grid stability monitoring.
Solid-state static meters with Hall-effect sensors and digital signal processors are overtaking electromechanical induction-disk designs in residential deployments. European utilities deploying time-of-use rates require 15-minute interval data capabilities that electromechanical units cannot provide. The transition compresses margin pools for basic billing-grade hardware while expanding software and analytics revenue streams.
The EU F-Gas Regulation is reshaping meter enclosure specifications and communication module thermal design across European distribution networks. Sealed housing requirements for sulfur hexafluoride reduction mandate new material selections and heat dissipation architectures. German and Italian utilities are responding with revised procurement specifications that disqualify legacy enclosure designs.
Utility procurement departments are unbundling meter hardware from communication and data management services. Investor-owned utilities in North America now issue separate RFPs for device supply, network infrastructure, and meter data management platforms. This fragmentation favors specialized vendors over integrated solution providers in competitive bidding processes.
Power Metering Market Segmentation
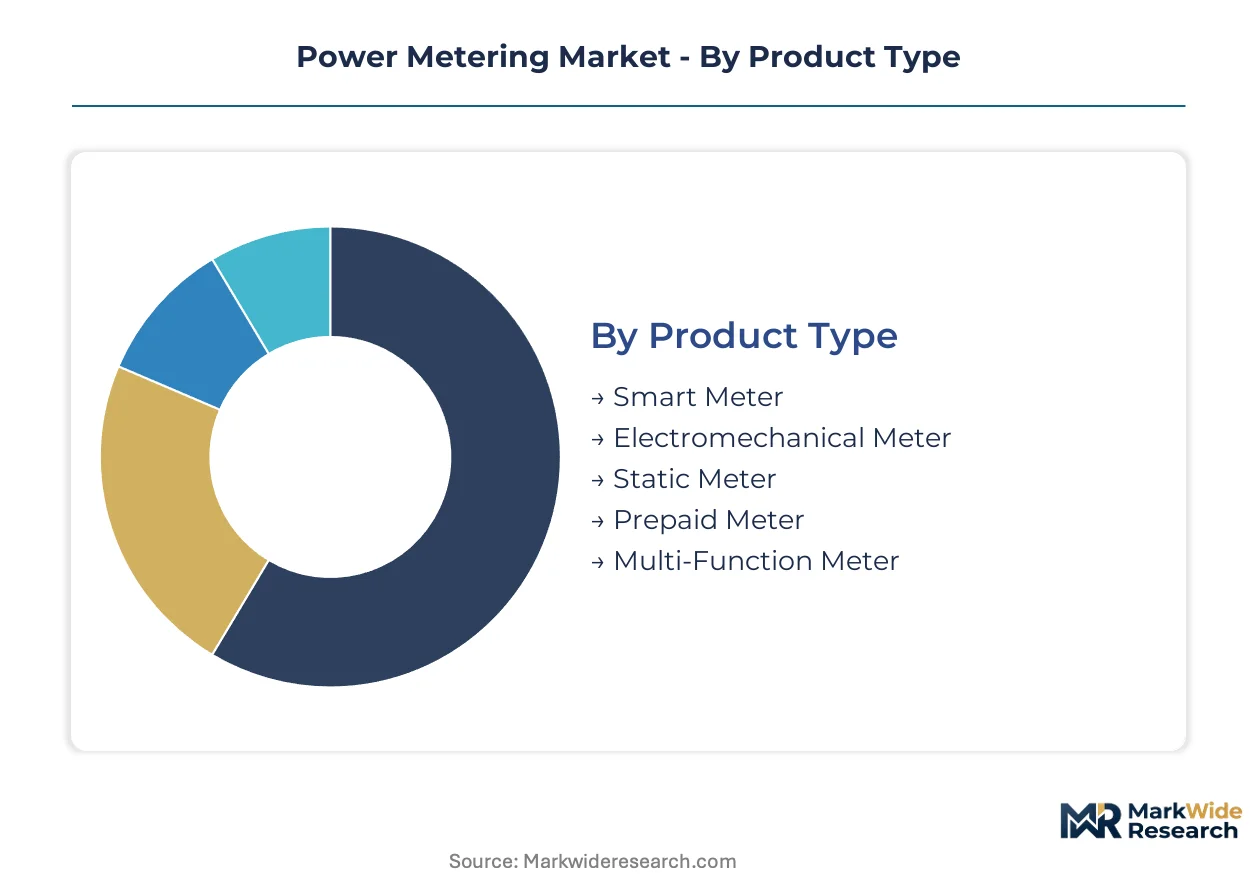
Power metering segmentation reflects divergent investment cycles across utility infrastructure, communication protocols, and customer-facing applications. Each dimension carries distinct margin structures and certification requirements that shape procurement patterns.
Product Type:
Standardization dominates at the residential tier while customization intensifies toward industrial-grade multi-function units.
- Smart Meter:Solid-state devices integrate RF Mesh or cellular modules for 15-minute interval data transmission and remote disconnect capability. Demand concentrates in US investor-owned utilities replacing electromechanical infrastructure under FERC demand response mandates.
- Multi-Function Meter:Embedded power quality analytics including harmonic monitoring and voltage sag detection serve manufacturing and data center applications. Premium pricing applies where IEC 62052-11 0.2S accuracy class certification is mandatory.
- Electromechanical Meter:Induction-disk designs persist in emerging markets as lowest-first-cost procurement options.
- Static Meter:Solid-state measurement cores with Hall-effect sensors displace electromechanical units in European residential deployments.
- Prepaid Meter:Token-based or STS-compliant units address revenue protection in utilities with high collection risk exposure.
Most installed capacity flows through Smart Meter. Expansion is steepest in Multi-Function Meter.
Technology:
Communication architecture selection hinges on population density and existing utility fiber investment.
- AMI:Two-way advanced metering infrastructure enables real-time pricing, remote disconnect, and distributed solar integration. China's State Grid Corporation prioritizes bidirectional protocols for EV load management programs.
- RF Mesh:Self-healing neighborhood area networks reduce infrastructure deployment costs in suburban US service territories. Siemens AG and Landis+Gyr Group AG dominate integrated substation-to-meter RF deployments.
- AMR:Drive-by or walk-by automated meter reading persists in rural territories where AMI capital investment cannot be recovered.
- PLC:Power line carrier communication leverages existing distribution conductors in dense European urban networks.
- Cellular Communication:LTE-M and NB-IoT modules gain traction where RF Mesh density is uneconomical.
AMI claims the dominant share of new capital allocation. Cellular Communication is climbing the fastest as utilities evaluate hybrid architectures.
Application:
Revenue per endpoint varies by order of magnitude from basic residential billing to grid stability orchestration.
- Grid Automation:Substation-grade meters with synchronized phasor measurement enable real-time voltage control and fault location. German distribution networks under EU Green Deal targets require full AMI architecture for renewable integration.
- Industrial Energy Management:Sub-metering deployments in manufacturing facilities track consumption by production line for carbon accounting and demand charge optimization.
- Residential Monitoring:Basic billing-grade meters with optional in-home displays serve time-of-use rate participation.
- Commercial Billing:Mid-tier accuracy class meters address multi-tenant buildings and small retail.
- Demand Response:Direct load control signal reception enables air conditioner and water heater cycling programs.
Residential Monitoring accounts for the largest unit volume. Grid Automation is gaining share fastest as distribution operators modernize.
End User:
Procurement sophistication separates regulated utilities from facility management outsourcing arrangements.
- Electric Utilities:Investor-owned and municipal utilities issue long-term supply agreements with accuracy class and cybersecurity certification requirements. India's Central Electricity Authority directives create volume for prepaid and remote-capable meters.
- Facility Management Firms:Third-party energy service contracts drive sub-metering installation in commercial real estate portfolios.
- Energy Service Companies:Performance contracting models require granular consumption data for guaranteed savings verification.
- Meter Manufacturers:Component and module suppliers serve integrated solution providers and private-label arrangements.
Electric Utilities command the dominant procurement volume. Facility Management Firms are expanding most quickly as building owners outsource energy operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The power metering industry traces its modern scaling to electromechanical meter manufacturing clusters in Germany and the United States during the mid-20th century, with subsequent technology transitions concentrating digital meter production in East Asian electronics corridors.
United States
Investor-owned utilities across California, Texas, and the Northeast are replacing aging electromechanical infrastructure under FERC and state public utility commission mandates for demand response participation. The Federal Energy Regulatory Commission requires advanced metering infrastructure for grid-connected distributed solar and EV load management programs. Texas utilities in the ERCOT footprint prioritize bidirectional communication capabilities for real-time pricing orchestration.
China
State Grid Corporation modernization programs prioritize AMI-enabled meters with embedded power quality monitoring for distributed solar integration and electric vehicle charging load management. The National Energy Administration enforces GB standards for meter communication protocols, creating compliance barriers for non-domestic suppliers. Meter manufacturing concentrates in the Yangtze River Delta corridor serving domestic grid investment cycles.
Germany
Distribution network operators under EU Green Deal energy efficiency targets are compelling upgrades from AMR to full AMI architectures across Bavaria and North Rhine-Westphalia. The EU F-Gas Regulation reshapes meter enclosure specifications and communication module thermal design through sealed housing requirements. Siemens AG anchors integrated substation-to-meter deployments across German distribution networks.
India
Central Electricity Authority directives for smart city and rural electrification initiatives create procurement volume for prepaid metering and remote disconnect capabilities. State-level distribution companies in Maharashtra, Gujarat, and Karnataka issue tenders for AMI-enabled meters with STS-compliant payment systems. Meter deployment accelerates in urban clusters addressing revenue protection and theft reduction.
Italy
Enel's Telegestore program established early large-scale AMI deployment, with ongoing replacement cycles prioritizing cellular LPWAN communication modules for remote meter management. The EU Green Deal accelerates digital metering deployment across the Po Valley industrial corridor and southern distribution territories. Italian utilities revised procurement specifications under F-Gas Regulation compliance timelines.
Power Metering Market Key Industry Players
Capital-heavy producers with captive semiconductor packaging and RF module fabrication compete with asset-light designers outsourcing communication core production to specialized foundries. The market structure shows moderate consolidation at the integrated solution tier with fragmentation among component and regional meter suppliers. Three strategic archetypes dominate: European industrial conglomerates with automation-to-meter vertical portfolios, North American communication specialists with utility software integration capabilities, and Chinese state-aligned manufacturers serving domestic grid procurement. Competitive moves concentrate on strategic partnerships for head-end system integration and geographic licensing agreements to bypass IEC 62351 cybersecurity certification barriers.
Among European industrial conglomerates, Siemens AG and ABB Ltd. exemplify the integrated automation-to-meter archetype with substation-grade portfolio breadth. Landis+Gyr Group AG occupies a position within the North American communication specialist tier, anchoring long-term supply relationships with major investor-owned utilities. Wasion Group represents the state-aligned Chinese manufacturer archetype, serving State Grid Corporation procurement cycles through multi-function meter specialization.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Itron Inc. |
| Aclara Technologies LLC |
| Kamstrup |
| Landis+Gyr Group AG |
| Honeywell International Inc. |
| Wasion Group |
| Schneider Electric |
| Others |
Cost & Logistics Intelligence
Captive semiconductor packaging and RF module fabrication anchor supply positions for capital-heavy producers while compressing margin pools for asset-light designers dependent on East Asian foundries. Siemens AG and Wasion Group leverage in-house production of communication cores to command pricing power in German and Chinese procurement cycles respectively, whereas specialists outsourcing Hall-effect sensor assembly face cost compression from concentrated foundry pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IEC 62052-11 0.2S accuracy class meters from 0.5S commercial-grade units and basic electromechanical induction-disk designs. Certification tier and volume scale drive price differentiation, with multi-function meters embedding harmonic monitoring commanding substantial premiums over billing-grade residential units. Pricing pressure stems from electromechanical meter substitution in emerging markets where lowest-first-cost procurement dominates. Electric utilities exhibit lowest price sensitivity due to long-term supply agreement structures, while state-level distribution companies in India demonstrate highest sensitivity through competitive tender processes.
Supply Chain Analysis
IEC 62351 cybersecurity certification complexity gates supplier participation across European and North American procurement channels, extending qualification timelines for non-domestic vendors. RF Mesh and cellular communication module production concentrates in China, South Korea, and Taiwan, drawing from silicon wafer and semiconductor packaging inputs. Single-source vulnerability in East Asian foundry capacity creates exposure to geopolitical disruption. Distribution runs through direct long-term supply agreements with investor-owned utilities alongside tender-based procurement for state-level distribution companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power metering market functions as a regulatory compounder where FERC demand response mandates and EU Green Deal energy efficiency targets generate sustained replacement demand across multiple procurement cycles.
For Market Incumbents: Acquire captive RF module fabrication capacity to defend against semiconductor supply concentration risks while securing margin pools in AMI-enabled smart meter deployments. Siemens AG anchors integrated substation-to-meter solutions through backward integration into communication core production. Invest in IEC 62351 cybersecurity certification infrastructure to extend procurement timeline advantages against emerging entrants lacking compliance capabilities.
For New Entrants and Emerging Players: Begin with India's smart city and rural electrification initiatives where Central Electricity Authority directives create volume for prepaid metering with lower certification barriers than European or North American markets. Target STS-compliant payment system integration as the most penetrable application segment. Pursue partnership-based go-to-market models with established head-end system providers to bypass proprietary protocol integration complexity.
For Investors and Strategic Acquirers: Roll-up economics work for regional meter suppliers with captive GB standards compliance because China's National Energy Administration procurement cycles favor domestic vendors with established State Grid Corporation relationships. Platform consolidation targets manufacturers with solid-state measurement core capabilities and existing power quality analytics portfolios. Watch cellular LPWAN convergence with RF Mesh as the inflection indicator for hybrid communication architecture adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | IEC 62351 compliance hardens procurement specifications against network intrusion risks in German distribution networks. |
| Backward Integration into RF Modules | In-house semiconductor packaging reduces dependency on East Asian foundry concentration for cellular communication components. |
| Geographic Licensing Agreements | Partnerships with domestic vendors bypass GB standards compliance barriers in China's State Grid Corporation procurement cycles. |
| Power Quality Analytics Development | Embedded harmonic monitoring capabilities capture premium pricing in manufacturing and data center multi-function meter applications. |
| Hybrid Communication Architecture Launch | Cellular LPWAN and RF Mesh convergence reduces infrastructure deployment costs in low-density US service territories. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, meter manufacturer procurement leads, RF network commissioning technicians, and head-end system integration specialists with secondary validation from FERC filings, EIA demand response program databases, EU Green Deal implementation progress reports, and State Grid Corporation tender announcements. Bottom-up endpoint deployment tracking and top-down grid investment flow analysis provided triangulation across measurement approaches.
Segment-weighting across product type, technology protocol, application tier, and end-user procurement sophistication shaped the analytical framework across the projection horizon. CAGRs derived from utility capital expenditure cycle analysis and regulatory mandate timeline modeling incorporated AMI replacement rate assumptions, electromechanical meter residual stock depreciation curves, and distributed solar integration communication requirements as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including extreme semiconductor supply disruption scenarios, cybersecurity certification standard revision timelines, and utility bankruptcy restructuring impacts on long-term supply agreement enforceability. Forecasts reflect documented assumptions regarding state-level mandate adoption rates and technology transition pacing. A model refresh is warranted upon material change in FERC demand response participation requirements or EU Green Deal enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Smart Metering Systems Market
Smart Meters
Solar Meter Market
Smart Meters
Smart Gas Metering Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Global Smart Energy Meters Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
Middle East and Africa Smart Meters Market
Smart Meters
Home Energy Monitor Market
Smart Meters
Europe Water Meter Market
Smart Meters
Smart Electric Meter Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
United States Smart Meter Market