
 Solar Meter Market | 2026-2036
Solar Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Meter Market Insights
Silicon carbide circuitry is pivoting into solar meter architectures, displacing traditional silicon-based components in high-temperature, high-efficiency measurement environments. FLIR Systems leverages its thermal imaging heritage to anchor premium positioning in utility-scale irradiance monitoring. Megger competes through specialized insulation resistance testing protocols that differentiate its meters in European certification regimes. Campbell Scientific sustains R&D intensity in datalogger-integrated meters, occupying the precision agriculture and research station segments where accuracy tolerances tighten annually.
A solar meter is an electromechanical or solid-state instrument engineered to quantify irradiance, photovoltaic output, or thermal collector performance, typically resolving to watts per square meter or cumulative kilowatt-hours with sampling intervals under one second for grid-tied applications. Its primary commercial purpose is to validate energy yield, detect system degradation, and reconcile production against forecast models for asset financiers and operators. Smart meters and digital meters together capture the dominant margin pools, as remote telemetry and revenue-grade accuracy command pricing premiums over analog alternatives. Photovoltaic technology leads installation volumes, though hybrid system meters are gaining fastest as bifacial panels and storage co-location complicate measurement protocols.
The US Federal Energy Regulatory Commission and the EPA jointly shape meter requirements through interconnection standards and environmental compliance reporting for utility-scale assets. India's Central Electricity Authority mandates metering specifications under its technical standards for connectivity, while the Bureau of Indian Standards certifies equipment for domestic procurement under the Production Linked Incentive scheme. Stakeholders must monitor whether emerging grid codes in high-penetration solar territories will force retrofits of existing meter fleets or open replacement cycles for next-generation measurement hardware.
Market Dynamics
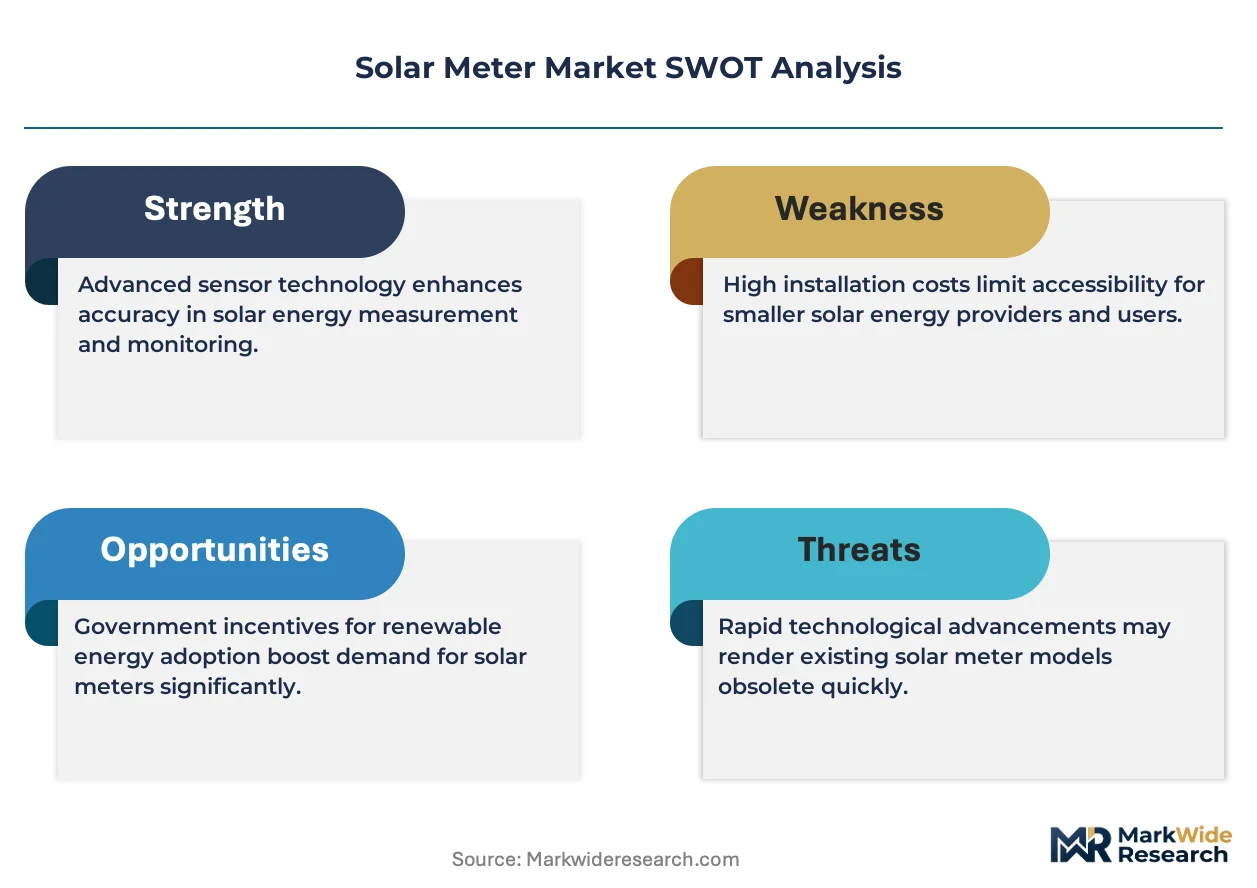
Silicon carbide power electronics are forcing a component-level redesign across solar meter architectures, as thermal tolerance requirements intensify under utility-scale bifacial deployment scenarios.
Growth Catalysts
- US Inflation Reduction Act:Domestic manufacturing incentives for solar monitoring equipment are accelerating capital commitments to meter production facilities across Texas and Arizona.
- India's rural electrification programs:State-level renewable purchase obligations are mandating distributed solar networks with revenue-grade metering in Maharashtra, Gujarat, and Rajasthan.
- Silicon carbide semiconductors:Wide-bandgap materials are enabling 150°C operating temperatures that legacy silicon cannot sustain in desert solar installations.
Market Restraints
- Neodymium supply concentration:Rare earth magnet dependency for solid-state meter components concentrates sourcing risk within China's processing infrastructure.
- Revenue-grade certification timelines:FERC and state-level public utility commission testing protocols extend product launch cycles by 14-22 months for new meter entrants.
- Analog meter substitution:Low-cost electromechanical alternatives persist in off-grid and micro-utility segments where telemetry integration remains uneconomical.
Strategic Opportunities
- Hybrid system meters:Bifacial panel and battery storage co-location is creating measurement complexity that next-generation datalogger-integrated meters can monetize.
- India's Production Linked Incentive scheme:BIS certification requirements for domestic procurement are opening captive demand for locally manufactured smart meters.
- Edge computing convergence:On-device analytics and cellular telemetry are merging to enable sub-second grid response without cloud dependency.
Industry Challenges
- Embedded firmware talent scarcity:Meter OEMs face acute shortages of engineers proficient in IEC 62056 DLMS/COSEM protocol implementation and security hardening.
- Legacy SCADA integration friction:Utility IT departments struggle to reconcile Modbus and DNP3 data streams from new meters with decades-old control system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Meter Market |
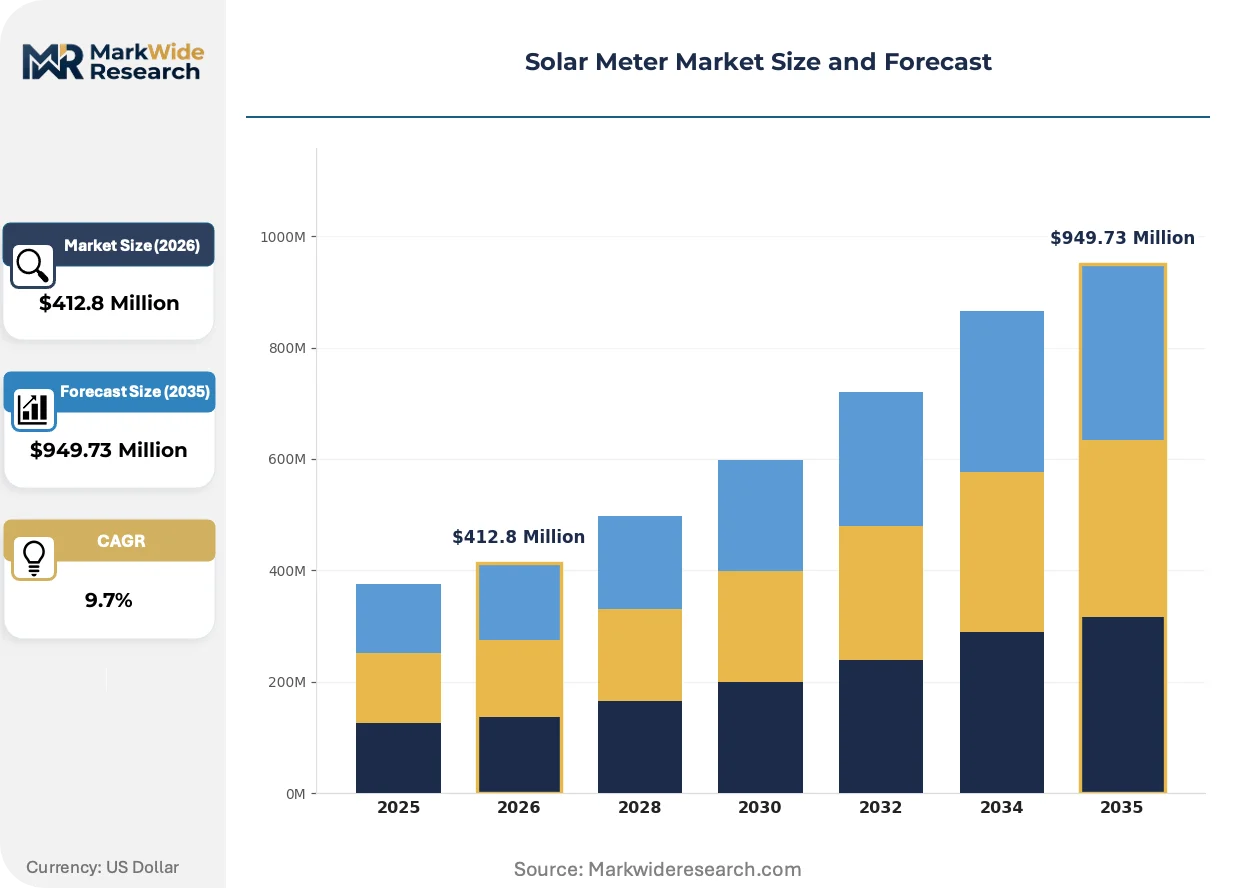
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $949.73 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Meters, Analog Meters, Smart Meters, Multimeters Technology: Photovoltaic, Thermal, Concentrated Solar Power, Hybrid Systems End User: Residential, Commercial, Industrial, Utility Installation: Standalone, Integrated, Portable, Fixed |
| Companies Covered | FLIR Systems, Fluke Corporation, Amprobe, Campbell Scientific, Inc., Megger, Apogee Instruments, Inc., EKO Instruments Co., Ltd., Solar Light Company, Inc., General Tools & Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Meter Market Trends and Innovations
Measurement architectures are fragmenting into specialized tiers as bifacial panels, floating solar, and agrivoltaic installations each demand distinct irradiance validation protocols.
Silicon carbide circuitry is modularizing solar meter power stages into swappable thermal management units that field technicians can replace without full device decommissioning. Utility-scale operators in Nevada and Saudi Arabia are piloting these architectures to reduce mean-time-to-repair in 55°C ambient conditions. This modularity is compressing total cost of ownership calculations for asset financiers underwriting 25-year solar project debt.
India's Central Electricity Authority technical standards for connectivity are mandating time-synchronized phasor measurement capabilities in all new utility-scale interconnections. This regulatory compression is forcing firmware retrofits across existing smart meter fleets deployed under earlier grid codes. Meter OEMs are responding with over-the-air upgrade capabilities that avoid physical site visits.
Buyer concentration among independent power producers is unbundling after-sales service contracts from hardware procurement, creating recurring revenue pools separate from meter shipments. Third-party asset managers like Brookfield and Macquarie now specify 10-year calibration and remote diagnostics as standalone line items in RFPs. This service separation is most advanced in North American utility-scale procurement, where power purchase agreement durations exceed equipment depreciation schedules.
Solar Meter Market Segmentation
Solar meter procurement decisions pivot on certification grade, telemetry requirements, and environmental tolerance specifications. Each segment carries distinct regulatory burdens and margin profiles that reshape vendor positioning across utility-scale and distributed generation deployments.
Product Type:
FERC revenue-grade certification applies selectively across this category, with smart meters and digital meters facing the most stringent testing protocols while analog alternatives operate under relaxed accuracy thresholds.
- Smart Meters:IEC 62056 DLMS/COSEM protocol-enabled devices with cellular or mesh telemetry for real-time grid integration. Demand concentrates among independent power producers in Texas and Arizona where FERC Order 2222 compliance mandates sub-second data granularity for aggregated distributed energy resources.
- Digital Meters:Solid-state instruments with LCD displays and pulse outputs, typically achieving Class 0.5S accuracy for commercial revenue settlement. Procurement is accelerating across Maharashtra and Gujarat as India's CEA technical standards phase out electromechanical alternatives from new interconnections.
- Analog Meters:Electromechanical induction-type instruments with rotating disk displays, requiring no firmware certification. Persist in off-grid rural electrification programs where telemetry infrastructure remains uneconomical.
- Multimeters:Handheld diagnostic instruments combining voltage, current, and resistance measurement for installation commissioning and troubleshooting. Field technicians in Nevada and Saudi Arabia deploy these for rapid irradiance validation in 55°C ambient conditions.
Leading the category by volume: Digital Meters. Growing fastest: Smart Meters.
Technology:
Measurement protocols diverge sharply across this dimension, with bifacial and hybrid configurations demanding multi-plane irradiance sensors that single-sided photovoltaic meters cannot accommodate.
- Photovoltaic:Pyranometer-based meters measuring plane-of-array irradiance for crystalline silicon and thin-film installations. Dominates installation volumes across utility-scale single-axis tracker deployments in the US Southwest and Rajasthan.
- Hybrid Systems:Integrated meters synchronizing photovoltaic output, battery state-of-charge, and thermal collector performance through unified dataloggers. Expanding most quickly as bifacial panel and storage co-location complicates legacy measurement architectures.
- Thermal:Pyrheliometer instruments tracking direct normal irradiance for concentrated solar trough and tower applications. Concentrated in Spain's Extremadura region and Morocco's Noor Ouarzazate complex where parabolic trough technology prevails.
- Concentrated Solar Power:Specialized heliostat field monitoring systems with high-temperature radiometers. Limited to utility-scale molten salt installations requiring precision tracking accuracy verification.
Dominant by installed base: Photovoltaic. Steepest expansion trajectory: Hybrid Systems.
End User:
Procurement authority and accuracy requirements stratify sharply, with utility buyers mandating revenue-grade certification while residential segments prioritize cost minimization over telemetry sophistication.
- Utility:Grid-scale operators specifying IEC 61850-compliant meters with phasor measurement unit capabilities for transmission interconnection. India's CEA mandates time-synchronized reporting for all new renewable capacity additions.
- Industrial:C&I facilities with behind-the-meter solar plus storage seeking interval data for demand charge optimization. Expanding in Germany's Baden-Württemberg manufacturing corridor under EU Green Deal decarbonization mandates.
- Commercial:Retail and office buildings with rooftop installations requiring production monitoring for renewable energy certificate generation. Procurement concentrates in California's SGIP incentive program territories.
- Residential:Single-family and small multi-family dwellings with net metering agreements, typically served by basic production meters without revenue-grade certification. India's rural electrification programs in Uttar Pradesh and Bihar drive volume here.
Highest revenue per unit: Utility. Fastest volume growth: Industrial.
Installation:
Form factor selection tracks deployment mobility requirements and integration depth with existing balance-of-system architectures.
- Fixed:Permanently mounted meters integrated into combiner boxes or inverter enclosures for utility-scale and commercial rooftops. Standard across Nevada and Arizona utility-scale procurement where 25-year asset lifecycles dominate.
- Portable:Handheld or tripod-mounted instruments for temporary irradiance mapping and commissioning validation. Research stations and precision agriculture operators in California's Central Valley deploy these for crop yield correlation studies.
- Integrated:Factory-installed meters within inverter or energy management system enclosures, reducing field wiring complexity. Preferred by European EPC contractors under CE marking streamlined conformity assessment routes.
- Standalone:Self-enclosed meters with independent power supply and weatherproofing for retrofit applications. Common in India's distributed solar networks where legacy inverters lack monitoring capabilities.
Highest shipment volumes: Fixed. Fastest adoption: Integrated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates solar meter procurement through state-level renewable mandates and rural electrification programs. The United States channels demand through utility-scale deployment and domestic manufacturing incentives. Germany, Spain, and Saudi Arabia each anchor distinct technology applications across distributed generation and concentrated solar power.
United States
Utility-scale solar farms in Texas and Arizona are expanding procurement of smart metering infrastructure to optimize grid integration. The Federal Energy Regulatory Commission shapes meter requirements through interconnection standards under FERC Order 2222. Independent power producers in Nevada are piloting silicon carbide modular architectures to reduce mean-time-to-repair in desert conditions.
India
State-level renewable purchase obligations are mandating distributed solar networks with revenue-grade metering in Maharashtra, Gujarat, and Rajasthan. The Central Electricity Authority mandates metering specifications under its technical standards for connectivity, while the Bureau of Indian Standards certifies equipment for domestic procurement. Meter deployment is accelerating across Uttar Pradesh and Bihar under rural electrification programs.
Germany
Commercial and industrial facilities with behind-the-meter solar plus storage are seeking interval data for demand charge optimization. EU Green Deal decarbonization mandates are tightening accuracy tolerances in the Baden-Württemberg manufacturing corridor. European EPC contractors prefer integrated meters under CE marking streamlined conformity assessment routes.
Spain
Concentrated solar power installations in Extremadura are driving demand for pyrheliometer instruments tracking direct normal irradiance. The country's renewable energy auctions are mandating time-synchronized reporting for new capacity additions. Parabolic trough technology deployments are concentrating procurement among utility-scale operators.
Saudi Arabia
Utility-scale operators are deploying meters in 55°C ambient conditions across desert solar installations. The kingdom's renewable energy targets are accelerating procurement of high-temperature-tolerant measurement hardware. Noor Ouarzazate complex operators are validating precision tracking accuracy for molten salt installations.
Solar Meter Market Competitive Landscape
Capacity expansion dominates the current landscape as meter OEMs respond to procurement surges in India and the United States. The vendor base stratifies across three tiers: diversified instrumentation conglomerates with thermal imaging heritage, specialized electrical testing firms with insulation resistance protocols, and precision datalogger manufacturers serving research applications. Two strategic archetypes are consolidating position: component-level innovators in wide-bandgap semiconductors and service-unbundled asset managers specifying long-term calibration contracts. Geographic expansion and technology licensing represent the dominant competitive moves, with firmware upgrade capabilities and over-the-air deployment emerging as differentiation vectors.
Among diversified instrumentation specialists, FLIR Systems and Fluke Corporation exemplify the premium-tier positioning anchored in thermal imaging and electrical measurement heritage. Campbell Scientific, Inc. occupies a distinct archetype within the precision agriculture and research station segments where accuracy tolerances tighten annually. Megger represents the specialized electrical testing tier competing through certification-focused protocols in European regulatory regimes.
| Leading Market Players |
|---|
| FLIR Systems |
| Fluke Corporation |
| Amprobe |
| Campbell Scientific, Inc. |
| Megger |
| Apogee Instruments, Inc. |
| EKO Instruments Co., Ltd. |
| Solar Light Company, Inc. |
| General Tools & Instruments |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide semiconductor transitions are simultaneously compressing bill-of-materials costs for high-temperature meters and concentrating power electronics sourcing among wide-bandgap foundries in Texas and Arizona. This dual effect grants meter OEMs with captive SiC supply arrangements measurable pricing leverage over competitors dependent on merchant silicon components.
Pricing Analysis
Volume shipments concentrate in digital meters while margin pools accrue to smart meters with cellular telemetry and FERC revenue-grade certification. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61850-compliant utility meters from commercial Class 0.5S instruments and basic analog alternatives. Pricing pressure stems from India's PLI scheme driving local manufacturing scale in Maharashtra and Gujarat. Residential rural electrification programs exhibit highest price sensitivity; utility-scale IPPs in Nevada and Arizona demonstrate lowest.
Supply Chain Analysis
Embedded firmware engineering shortages in Texas and Arizona manufacturing corridors are constraining production ramp rates for DLMS/COSEM protocol-compliant meters. Component sourcing draws from China for rare earth magnet processing, Taiwan for precision analog semiconductors, and domestic US foundries for silicon carbide substrates. Single-source vulnerability concentrates in neodymium magnet supply chains. Distribution runs through EPC contractor procurement channels and direct utility RFP processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide wafer capacity constraints are propping pricing premiums for high-temperature solar meters, creating a supply-constrained market structure where foundry relationships determine competitive position.
For Market Incumbents: Lock in multi-year silicon carbide wafer offtake agreements with domestic foundries before capacity commitments exhaust. Secure BIS certification for India's PLI scheme ahead of competitor filings. Vertical integration into firmware development teams mitigates the acute DLMS/COSEM protocol engineering scarcity threatening production timelines. For New Entrants and Emerging Players: Capture the standalone meter retrofit segment across India's distributed solar networks where legacy inverters lack monitoring capabilities. Target precision agriculture applications in California's Central Valley where Campbell Scientific's research-grade positioning leaves mid-tier price-performance gaps. Lead with integrated datalogger capabilities that simplify field wiring for European EPC contractors. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified instrumentation conglomerates seeking thermal imaging and electrical measurement synergies. Five-to-ten year viability favors vendors with revenue-grade certification portfolios and over-the-air firmware upgrade architectures. Watch India's CEA technical standards evolution for forced retrofit cycles that would accelerate replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Stage Modularity | Swappable thermal management units reduce mean-time-to-repair in Saudi Arabia's 55°C desert installations. |
| Over-the-Air Firmware Capability | CEA-mandated phasor measurement retrofits in India avoid costly physical site visits for meter OEMs. |
| Production Linked Incentive Localization | BIS certification unlocks captive procurement from Maharashtra and Gujarat state utilities. |
| Service Contract Unbundling | Brookfield and Macquarie now specify 10-year calibration as standalone RFP line items. |
| Edge Computing Convergence | On-device analytics enable sub-second grid response without cloud dependency for Texas IPPs. |
Research Methodology
Independent corroboration across utility procurement officers, EPC contractor project managers, and meter OEM product directors underwrites the qualitative findings. Primary fieldwork encompassed IPP development executives in Nevada and Arizona, grid operators under FERC jurisdiction, and firmware engineering leads at domestic manufacturing facilities. Secondary validation drew from FERC interconnection filings, EIA utility-scale solar databases, India's CEA technical standards documentation, and Bureau of Indian Standards certification registries. Bottom-up segment sizing triangulated against top-down market reconstruction.
Comparable-period anchoring tied projection assumptions to historical deployment trajectories across utility-scale, commercial, and residential installation categories. The analytical framework modeled product type, technology, end user, and installation form factor dimensions throughout the forecast period. CAGRs derived from segment-level growth rate synthesis calibrated to regulatory mandate timelines and manufacturing capacity expansion announcements. Forecast inputs incorporated silicon carbide semiconductor adoption curves and India's rural electrification program execution rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to neodymium supply chain disruptions and FERC grid code revisions. Forecasts reflect documented assumptions around PLI scheme participation rates and state-level renewable purchase obligation enforcement. A small set of triggers warrants ongoing watch: CEA phasor measurement mandate expansion, SiC foundry capacity commissioning delays, and bifacial panel deployment acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Power Monitoring System Market
Smart Meters
Smart Meters Market
Smart Meters
Global Smart Water Meter Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Power Quality Meter Market
Smart Meters
North America Smart Meters Market
Smart Meters
Water Meter Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Plug in Power Meter Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Smart Metering Systems Market
Smart Meters
Asia-Pacific Smart Meter Data Management Market
Smart Meters
Europe Water Meter Market