
 Advanced Metering Infrastructure Market | 2026-2036
Advanced Metering Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Metering Infrastructure Market Analysis
Silicon carbide power electronics is recalibrating AMI hardware economics by enabling higher-efficiency communication modules with lower thermal losses. General Electric leverages its industrial software heritage to anchor utility-scale deployments across North America. Itron Inc. specializes in RF mesh network architectures that dominate residential smart meter installations. Landis+Gyr sustains manufacturing scale through captive European production facilities serving EMEA grid operators.
Advanced Metering Infrastructure comprises integrated systems of smart meters, communication networks, and data management platforms that measure, collect, and analyze energy consumption at 15-minute or shorter intervals using standards such as IEEE 2030.5 for interoperability. These systems enable utilities to implement time-of-use pricing, detect outages automatically, and integrate distributed energy resources into grid operations. Smart meters within the technology segment lead current deployment volumes while communication modules represent the fastest-growing sub-category as cellular LPWAN and RF mesh protocols displace legacy powerline carrier methods. The services component captures expanding margin pools as utilities outsource meter data management and cybersecurity monitoring to third-party providers rather than building internal cloud infrastructure.
The Federal Energy Regulatory Commission shapes AMI demand through Order 2222, which mandates distributed energy resource participation in wholesale markets requiring granular metering capabilities. In Europe, the F-Gas Regulation and EU Green Deal accelerate smart meter rollouts by linking building-level consumption transparency to decarbonization compliance timelines. China's MIIT enforces GB standards for powerline communication that constrain foreign equipment market access while domestic manufacturers scale production. Stakeholders must monitor evolving cybersecurity certification requirements across jurisdictions, as NERC CIP standards in North America and EN 303 645 in Europe diverge on data encryption protocols for edge devices.
Market Dynamics
Silicon carbide power electronics is compressing thermal budgets in AMI communication modules, forcing incumbent meter manufacturers to redesign hardware architectures around wide-bandgap semiconductors or cede efficiency benchmarks to specialized component suppliers.
Growth Catalysts
- FERC Order 2222:The Federal Energy Regulatory Commission's mandate for distributed energy resource participation in wholesale markets requires granular interval metering, compelling utilities across the United States to accelerate smart meter refresh cycles.
- RF mesh protocols:These wireless communication architectures are reducing deployment costs in dense urban environments by eliminating trenching requirements for fiber backhaul, particularly in German municipal utility territories.
- Grid infrastructure replacement:Aging electromechanical meter populations in China and Germany are reaching end-of-life simultaneously, creating concentrated demand windows for AMI vendors with established manufacturing scale.
Market Restraints
- Silicon carbide substrate shortages:Limited wafer fabrication capacity for wide-bandgap semiconductors is constraining communication module production, with lead times extending to 52 weeks for high-efficiency power stages.
- Chinese GB standards:The Ministry of Industry and Information Technology's mandatory powerline communication specifications create technical barriers for foreign equipment manufacturers seeking market access.
- Powerline carrier legacy:Existing deployed bases of narrowband PLC meters resist software-upgrade paths to 15-minute interval reporting, forcing premature hardware retirement in some European territories.
Strategic Opportunities
- India's smart city mandates:The Ministry of Power's urban distribution reform programs are creating tender pipelines for AMI-integrated demand response systems in metropolitan load centers.
- Cellular LPWAN convergence:The intersection of NB-IoT modules with edge computing capabilities enables predictive maintenance applications that command service contract premiums.
- EU Green Deal building retrofits:The linkage of consumption transparency mandates to decarbonization compliance timelines is expanding addressable market for sub-metering solutions in multi-tenant commercial properties.
Industry Challenges
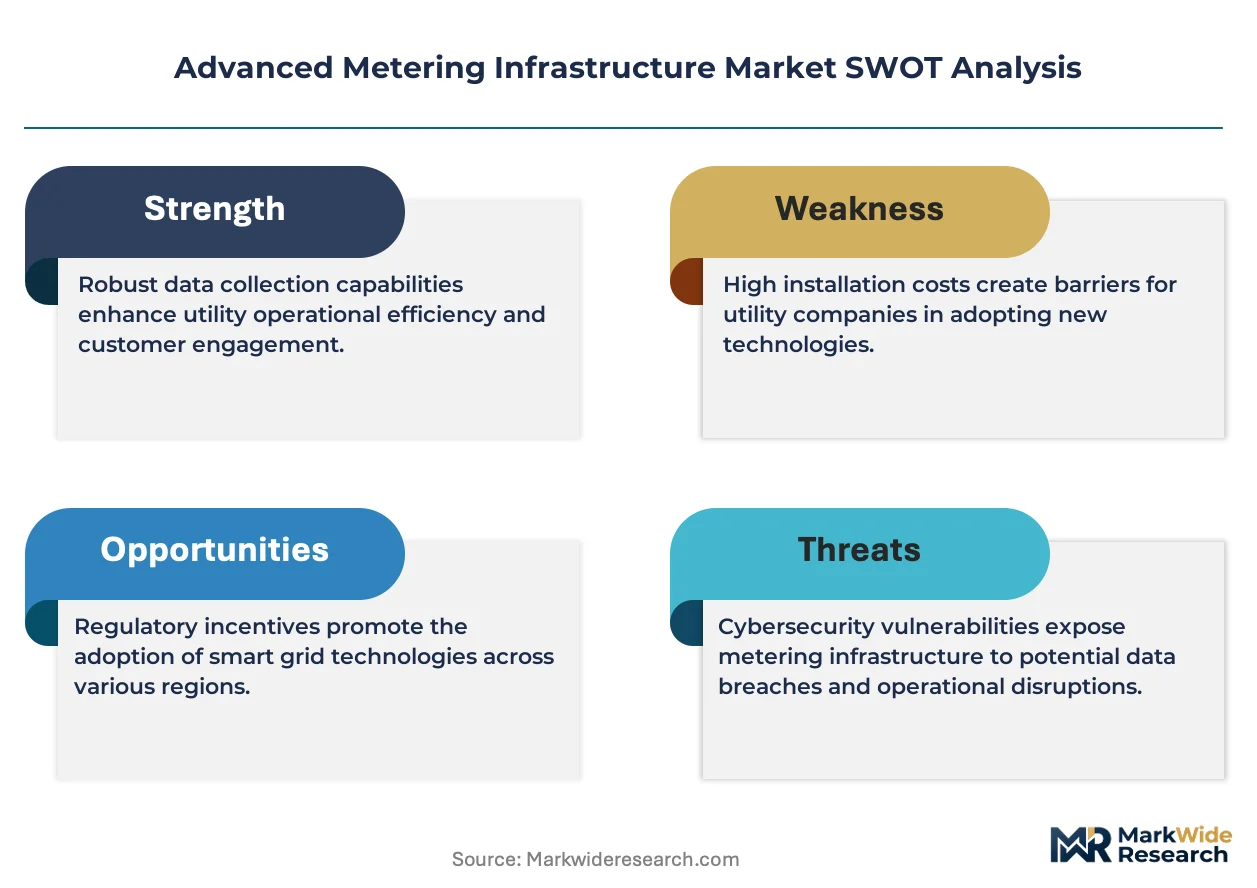
- Cybersecurity certification fragmentation:Divergent encryption requirements between NERC CIP standards in North America and EN 303 645 in Europe force vendors to maintain multiple firmware branches, complicating software release management.
- Legacy head-end integration:Utilities with custom-built meter data management platforms face API incompatibility when deploying next-generation meters, requiring expensive middleware development or system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Metering Infrastructure Market |
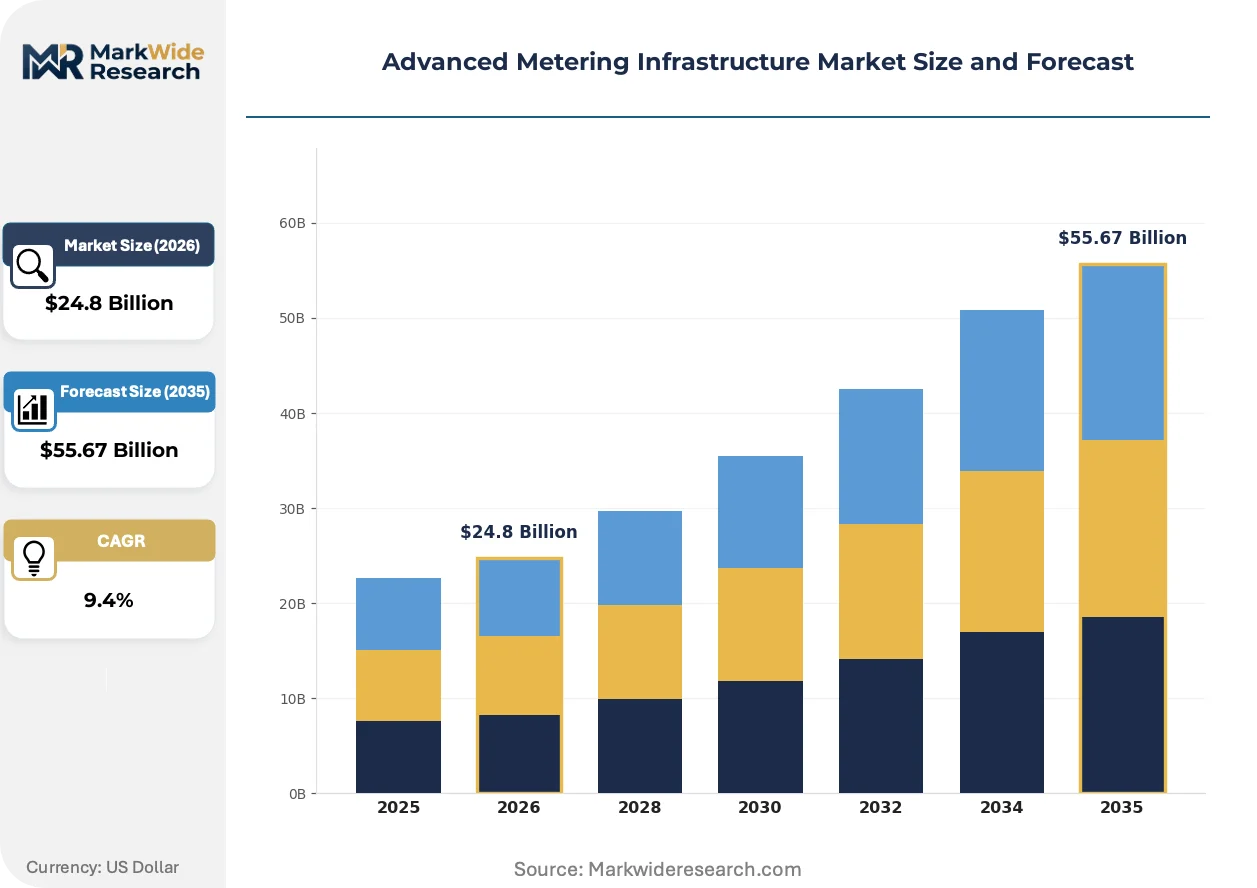
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $55.67 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Meters, Data Concentrators, Communication Modules, Network Gateways End User: Utilities, Commercial, Industrial, Residential Component: Hardware, Software, Services, Cloud Solutions Installation Type: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | General Electric, Cisco Systems Inc., Itron Inc., Capgemini, Siemens, Landis+Gyr, Aclara Technologies, ABB Ltd., Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Metering Infrastructure Market Emerging Trajectories
AMI hardware architectures are bifurcating between high-performance cellular endpoints and cost-optimized RF mesh devices, with software-defined radio platforms emerging as a convergence layer that preserves procurement flexibility for utilities with heterogeneous territory densities.
Silicon carbide MOSFETs are overtaking silicon IGBTs in AMI communication power stages by enabling 40% reduction in switching losses. European meter manufacturers are adopting these devices for solar-integrated smart meters where thermal budgets are constrained. This transition is compressing bill-of-materials differentiation between premium and standard product tiers.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in meter manufacturing processes, forcing suppliers to transition to foam-in-place polyurethane sealing methods. German production facilities are retrofitting assembly lines to accommodate solvent-free potting compounds. This regulatory pressure is accelerating consolidation among smaller enclosure suppliers lacking capital for process requalification.
Utility procurement departments are unbundling meter hardware from data management services, creating separate contract vehicles that favor specialized software vendors over integrated solution providers. This pattern is most pronounced in United States municipal utilities where city councils demand transparent line-item pricing. The shift is compressing vendor margins on hardware while expanding recurring revenue pools for cybersecurity monitoring services.
Advanced Metering Infrastructure Market Segmentation
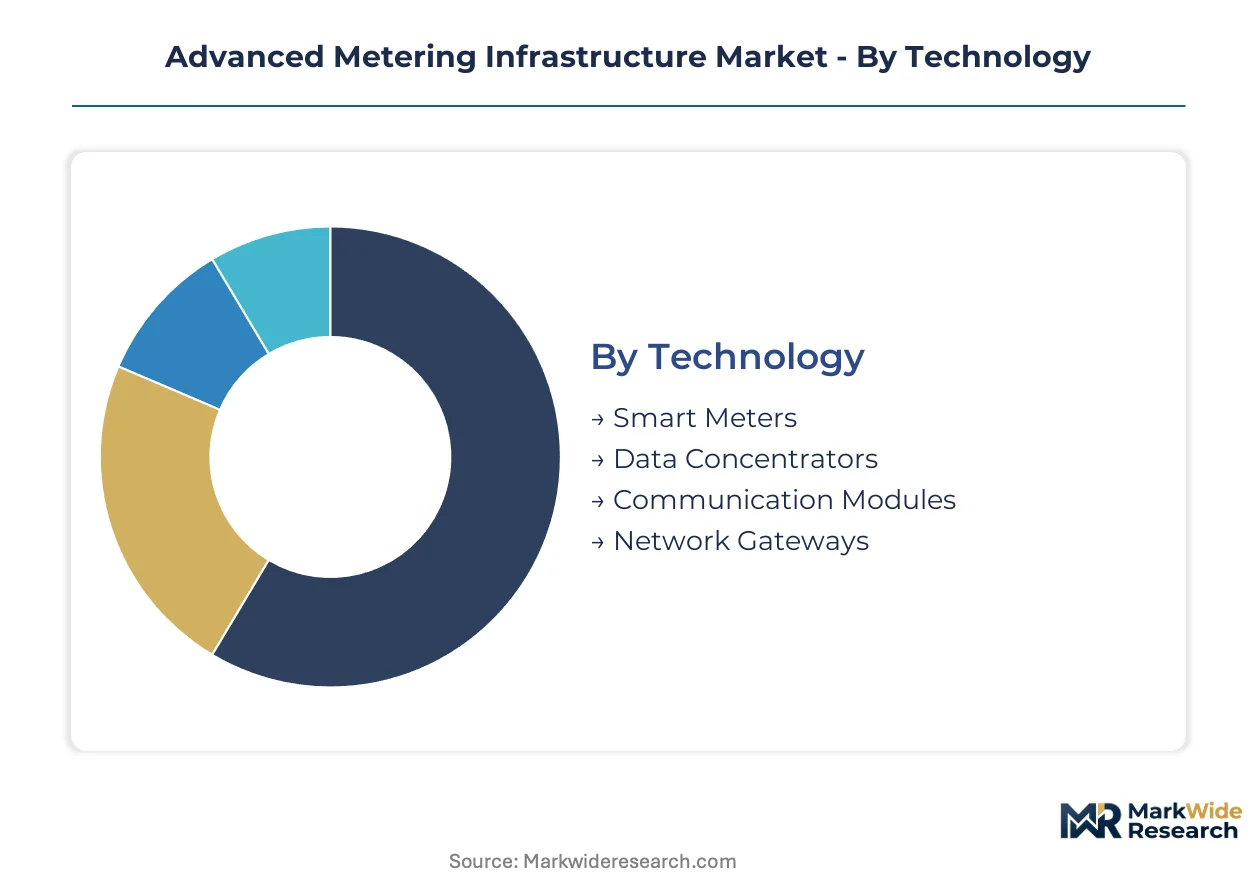
AMI procurement patterns diverge sharply across technology tiers and end-user categories, with utility-scale deployments prioritizing interoperability standards while commercial and industrial segments emphasize sub-metering granularity for demand response participation.
Technology:
Utility procurement departments weigh capital efficiency against functional longevity when selecting device categories, with communication protocol compatibility often overriding upfront hardware cost considerations.
- Smart Meters:These endpoint devices measure consumption at 15-minute intervals using solid-state metrology and embedded RF or cellular transceivers. Demand concentrates in Germany and China, where regulatory mandates for real-time consumption transparency intersect with aging electromechanical meter replacement cycles.
- Communication Modules:Power conversion and wireless transmission subsystems enable mesh networking or cellular backhaul to utility head-end systems. Silicon carbide MOSFETs are displacing silicon IGBTs in these modules, with United States utilities driving procurement for solar-integrated endpoints where thermal budgets are constrained.
- Data Concentrators:Aggregation devices that collect and preprocess meter readings from multiple endpoints before upstream transmission.
- Network Gateways:Protocol translation hardware bridging RF mesh, cellular, and fiber backhaul networks to utility data centers.
Smart meters lead on scale; communication modules lead on momentum.
End User:
Revenue concentration tilts toward entities with balance-sheet capacity for multi-year deployment cycles and regulatory obligations for grid-edge visibility.
- Utilities:Vertically integrated and municipal power companies deploying AMI as core infrastructure for outage management, time-of-use pricing, and distributed energy resource integration. FERC Order 2222 compliance requirements in the United States are accelerating refresh cycles for interval metering capabilities.
- Industrial:Manufacturing facilities and data centers implementing sub-metering for peak demand charge optimization and power quality monitoring. Demand concentrates in China, where MIIT-enforced GB standards for powerline communication constrain foreign equipment while domestic manufacturers scale production.
- Commercial:Multi-tenant office buildings and retail properties requiring consumption transparency for tenant billing and decarbonization reporting under EU Green Deal compliance timelines.
- Residential:Single-family and multi-family dwellings receiving utility-deployed smart meters with limited consumer-facing energy management interfaces.
Utilities command deployment volume; industrial segments capture premium pricing for specialized monitoring functions.
Component:
Margin pools are migrating from capital-intensive hardware toward recurring service revenues as utilities outsource cybersecurity monitoring and meter data management.
- Hardware:Physical meters, concentrators, and communication modules with 15-20 year service life expectations. Procurement is unbundling from software and services, compressing vendor margins on device sales.
- Services:Third-party meter data management, cybersecurity monitoring, and field maintenance contracts. This segment is expanding most quickly as municipal utilities in the United States demand transparent line-item pricing and outsource operational capabilities.
- Software:Head-end systems, analytics platforms, and consumer engagement applications for interval data visualization.
- Cloud Solutions:SaaS-based meter data management and predictive maintenance platforms hosted by specialized vendors rather than utility-owned infrastructure.
Hardware dominates installed base value; services deliver the steepest expansion trajectory.
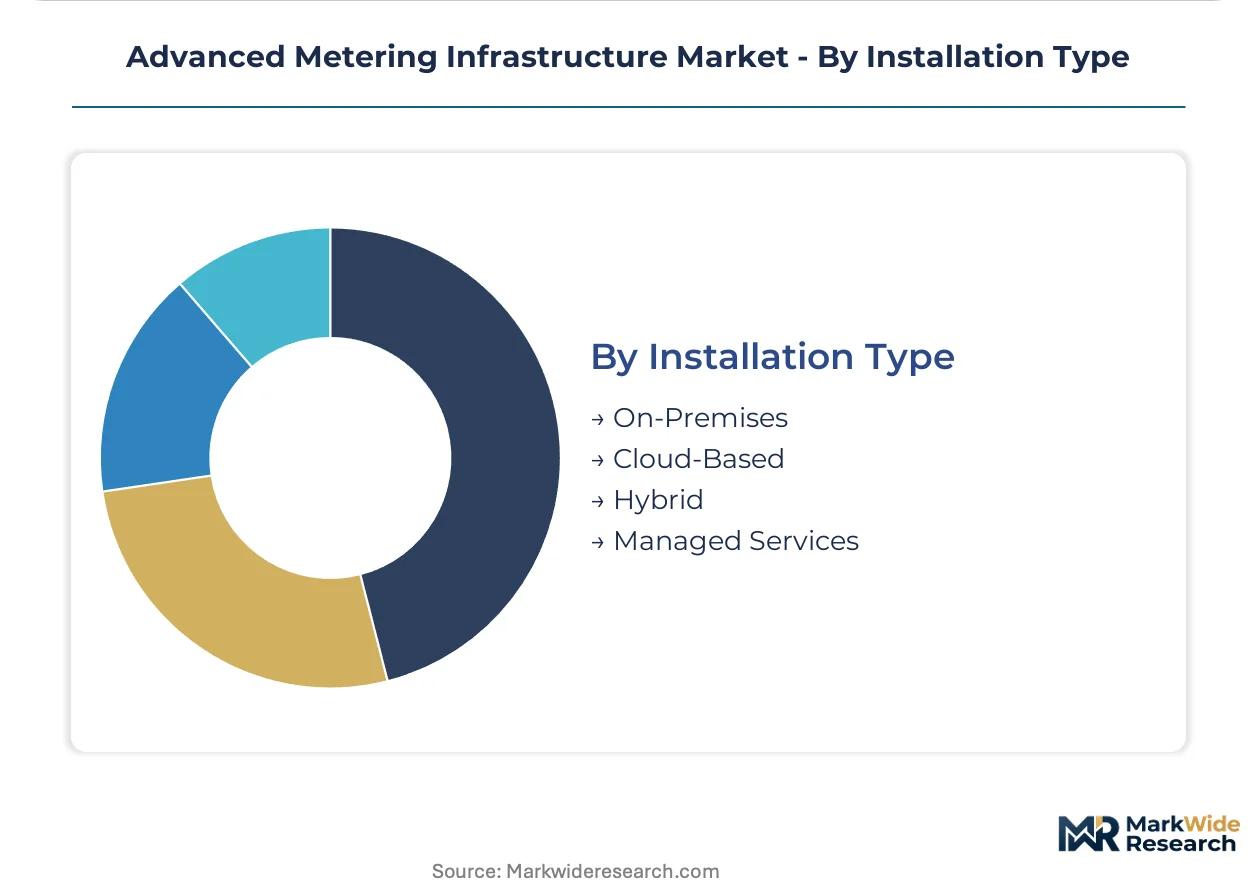
Installation Type:
Deployment architecture decisions hinge on IT security posture, legacy system compatibility, and availability of internal cloud engineering expertise.
- Cloud-Based:Fully hosted meter data management with utility data flowing directly to vendor-operated infrastructure. German municipal utilities favor this model to avoid capital expenditure approval cycles.
- Hybrid:Edge processing at utility data centers combined with cloud analytics for non-critical workloads. This architecture is gaining share fastest among United States investor-owned utilities balancing cybersecurity control with scalability.
- On-Premises:Complete utility ownership of head-end systems and data storage within physical control.
- Managed Services:Outsourced operation of utility-owned infrastructure by specialized vendors.
Cloud-based deployments lead on new contract velocity; hybrid architectures lead on strategic positioning for cybersecurity-sensitive accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal utilities anchor AMI procurement intensity through aggressive smart meter rollout timelines tied to EU decarbonization mandates. FERC Order 2222 compliance requirements in the United States accelerate replacement cycles for interval metering capabilities. China's MIIT enforces domestic GB standards that constrain foreign equipment market access while state-owned grid operators scale deployments.
United States
Investor-owned utilities drive demand for solar-integrated smart meters with constrained thermal budgets. FERC Order 2222 mandates distributed energy resource participation in wholesale markets requiring granular interval metering. Texas and California utilities lead procurement volumes for RF mesh and cellular LPWAN communication modules.
Germany
Municipal utilities favor cloud-based meter data management to bypass capital expenditure approval cycles. The EU F-Gas Regulation phases down hydrofluorocarbon use in meter manufacturing, forcing assembly line retrofits. Bavarian production facilities retrofit solvent-free potting compound processes to maintain EU market access.
China
State Grid Corporation accelerates electromechanical meter replacement across aging infrastructure bases. MIIT-enforced GB standards for powerline communication create technical barriers for foreign equipment manufacturers. Yangtze River Delta manufacturing clusters scale domestic production of communication modules with captive silicon carbide sourcing.
India
Ministry of Power urban distribution reform programs create tender pipelines for AMI-integrated demand response systems. The country's national electricity regulator pushes real-time consumption monitoring mandates for metropolitan load centers. Maharashtra and Gujarat utilities pilot cellular LPWAN deployments for predictive maintenance applications.
United Kingdom
Distribution network operators face regulatory pressure for grid-edge visibility to integrate distributed energy resources. The country's national energy regulator mandates smart meter coverage targets with cybersecurity certification requirements. London and Southeast England concentrate deployment volumes for multi-tenant commercial sub-metering solutions.
Advanced Metering Infrastructure Market Vendor Landscape
Global majors compete with regional champions across communication protocol standards and manufacturing scale. The vendor base stratifies between integrated solution providers and specialized component suppliers. Industrial conglomerates with captive software heritage anchor utility-scale deployments, while RF mesh specialists dominate residential meter architectures. Competitive moves center on silicon carbide power electronics integration and unbundled service contract vehicles.
Within the industrial conglomerate tier, General Electric and Siemens exemplify scale-driven positioning through utility software heritage and European manufacturing footprints. Itron Inc. and Landis+Gyr occupy specialist positions in RF mesh network architectures and captive European production serving EMEA grid operators. These four entities represent the dominant competitive archetypes: integrated industrial platforms, communication protocol specialists, regional manufacturing champions, and utility software anchors.
| Leading Market Players |
|---|
| General Electric |
| Cisco Systems Inc. |
| Itron Inc. |
| Capgemini |
| Siemens |
| Landis+Gyr |
| Aclara Technologies |
| ABB Ltd. |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Captive silicon carbide sourcing from Yangtze River Delta manufacturing clusters anchors both supply security and pricing power for domestic Chinese AMI producers, while foreign vendors absorb margin compression from substrate shortages and extended qualification timelines.
Pricing Analysis
Silicon carbide substrate cost pass-through dominates AMI hardware pricing, with communication module manufacturers absorbing 40% switching-loss reductions into standard-tier products while reserving SiC-enabled thermal performance for premium solar-integrated endpoints. Pricing stratifies across certification-grade tiers, with NERC CIP-compliant firmware commanding service contract premiums versus baseline EN 303 645 configurations. Price erosion runs through standard smart meter tiers as procurement unbundling forces hardware-only bidding wars among municipal utilities. Industrial sub-metering buyers exhibit lowest price sensitivity due to demand response revenue streams, while residential utilities face council-mandated line-item transparency that intensifies cost scrutiny.
Supply Chain Analysis
Dual-sourcing requirements for wide-bandgap semiconductors compel AMI vendors to qualify both domestic Chinese and Japanese SiC substrate suppliers, extending procurement cycles but mitigating single-source vulnerability from Taiwanese wafer fabrication constraints. Raw material dependencies center on silicon carbide wafers, RF transceiver chipsets, and solvent-free polyurethane potting compounds. Supply chain risk concentrates in tariff exposure for European manufacturers importing Chinese-sourced powerline communication ASICs. Distribution runs through utility procurement departments unbundling hardware from managed services, with German municipal utilities favoring cloud-hosted SaaS delivery to bypass capital expenditure approval cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AMI market represents a late-cycle quality story as utility procurement shifts from volume-driven electromechanical replacement toward premium-specification solar-integrated endpoints with edge computing capabilities.
For Market Incumbents: Cement market position through captive silicon carbide sourcing agreements with Yangtze River Delta suppliers and NERC CIP certification investment ahead of diverging global encryption standards. Threat of cellular LPWAN module commoditization from semiconductor specialists demands backward integration into RF mesh protocol stacks to preserve margin differentiation. For New Entrants and Emerging Players: German municipal utilities represent the most penetrable buyer archetype given their cloud-first procurement preference and frustration with legacy vendor integration timelines. White-space targets include sub-metering solutions for EU Green Deal building retrofits and predictive maintenance services for India's cellular LPWAN pilot programs. Go-to-market positioning should emphasize API-native head-end systems that bypass middleware development burdens. For Investors and Strategic Acquirers: Roll-up economics work for specialized cybersecurity monitoring vendors because utility outsourcing of meter data management is accelerating recurring revenue pools faster than hardware replacement cycles. Long-term viability favors platform plays with SaaS delivery models and multi-jurisdiction certification coverage. Watch FERC Order 2222 implementation velocity across Texas and California utilities as inflection indicator for interval metering refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Power Electronics Integration | Silicon carbide MOSFET adoption enables 40% switching loss reduction for solar-integrated endpoints. |
| Unbundled Service Contract Vehicles | Separate hardware and SaaS pricing satisfies municipal utility council transparency mandates. |
| Multi-Jurisdiction Cybersecurity Certification | Dual NERC CIP and EN 303 645 qualification preserves access to US and EU utility procurement. |
| Cloud-Native Head-End Development | API-native platforms eliminate middleware costs for utilities with custom legacy MDM systems. |
| Predictive Maintenance Service Layer | NB-IoT edge computing integration commands premium service contracts for cellular LPWAN deployments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, AMI procurement managers, RF mesh network engineers, and cybersecurity certification specialists with secondary validation from FERC filings, EIA smart meter deployment databases, EU F-Gas Regulation implementation reports, and MIIT GB standard documentation. Bottom-up utility deployment tracking and top-down manufacturing capacity analysis were triangulated against silicon carbide substrate supply chain disclosures.
Comparable historical deployment cycles from German municipal utility rollouts and Chinese State Grid replacement programs anchored the projection horizon across technology tiers, end-user segments, and installation architecture models. CAGRs were derived from segment-level adoption curves incorporating regulatory compliance timelines, equipment replacement age profiles, and communication protocol migration patterns. Forecast inputs included silicon carbide wafer fabrication capacity expansion announcements and utility capital expenditure disclosure trends.
Underlying measurement precision varies by segment; cloud-based deployment and services revenue carry tighter precision than on-premises hardware given vendor SaaS disclosure practices. Forecasts reflect assumptions about FERC Order 2222 implementation pace, EU Green Deal building retrofit funding continuity, and MIIT enforcement consistency for domestic GB standards. Deviation in silicon carbide substrate availability or NERC CIP encryption requirement revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
Watt Meter Market
Smart Meters
Solar Meter Market
Smart Meters
United States (US) Residential Smart Meters Market
Smart Meters
Single-Phase Anti-Theft Meter Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Europe Smart Water Meter Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
US Water Meter Market
Smart Meters
Middle East and Africa Smart Meters Market
Smart Meters
Europe Water Meter Market
Smart Meters
Smart Meter Data Management Market
Smart Meters
Smart Metering Systems Market
Smart Meters
Smart Meter Battery Market