
 United States Smart Meter Market | 2026-2036
United States Smart Meter Market Size, Share, and Industry Trends Forecast 2026-2036
United States Smart Meter Market Analytics
Aftermarket service revenue is reconfiguring competitive economics across the United States Smart Meter Market. Itron Inc. leverages its managed services portfolio to extend customer lifecycles beyond hardware deployment. Landis+Gyr Group AG anchors its position through deep utility partnerships and firmware upgrade pathways. Honeywell International Inc. competes on integrated building-to-grid connectivity, bundling metering with automation software.
A smart meter is a digital device that measures utility consumption in intervals of one hour or less and communicates that data remotely to the utility for monitoring, billing, and system optimization; units typically incorporate solid-state measurement, embedded RF or cellular modems, and meet ANSI C12 accuracy standards for revenue-grade certification. Electric meters dominate installed value given grid modernization urgency, while AMI technology segments command premium positioning over legacy AMR due to two-way command capability and outage management functionality. Water meters represent the fastest-expanding product category as drought-stressed utilities prioritize leak detection and conservation pricing.
FERC Order 2222, state public utility commission mandates, and the EPA's water loss reduction guidance collectively shape procurement specifications and deployment timelines across the country. NIST cybersecurity frameworks and IEEE 2030 interoperability standards further constrain vendor qualification, favoring suppliers with certified encryption stacks and protocol adaptability. Stakeholders must weigh capital allocation between AMI platform consolidation and emerging distributed energy resource integration modules.
Market Dynamics
Federal grid modernization mandates and state renewable portfolio standards are compressing replacement timelines for legacy metering infrastructure, while municipal water utilities in drought-stressed regions accelerate AMI procurement for conservation pricing and leak detection.
Growth Catalysts
- FERC Order 2222:The Federal Energy Regulatory Commission's distributed energy resource aggregation mandate requires two-way communication capability, forcing utilities toward advanced metering infrastructure with command functionality.
- California decarbonization deadlines:Investor-owned utilities in the state face the most aggressive electrification timelines, concentrating demand for revenue-grade meters with ANSI C12 certification and embedded cellular modems.
- EPA water loss reduction guidance:The Environmental Protection Agency's conservation directives are pulling municipal water districts toward interval-measurement devices with remote telemetry for non-revenue water management.
Market Restraints
- Semiconductor supply concentration:RF modem chipsets and solid-state measurement components face sourcing constraints from concentrated Asian foundry capacity, extending lead times for meter manufacturers.
- Cybersecurity certification friction:NIST framework compliance and IEEE 2030 interoperability standards create vendor qualification bottlenecks, favoring incumbents with certified encryption stacks and freezing smaller suppliers.
- Legacy AMR stranded asset risk:Utilities with recent drive-by meter investments face capital efficiency pressures when evaluating full AMI replacement versus incremental upgrade pathways.
Strategic Opportunities
- Texas municipal water expansion:Drought-stressed utilities across the Southwest are prioritizing conservation pricing infrastructure, creating white space for leak-detection-optimized water meter deployments.
- Building-to-grid convergence:Honeywell and automation specialists are bundling metering with HVAC and lighting control systems, opening integrated demand response revenue streams beyond standalone hardware sales.
- Firmware-as-a-service models:Itron's managed services portfolio demonstrates lifecycle extension potential, creating recurring revenue architectures that decouple vendor economics from replacement cycles.
Industry Challenges
- AMI-legacy system integration complexity:Utilities with heterogeneous SCADA and billing platforms face protocol translation burdens when deploying meters with incompatible communication stacks.
- Cybersecurity talent scarcity:NIST framework implementation requires specialized encryption and network segmentation expertise that utilities and vendors struggle to staff at deployment scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Smart Meter Market |
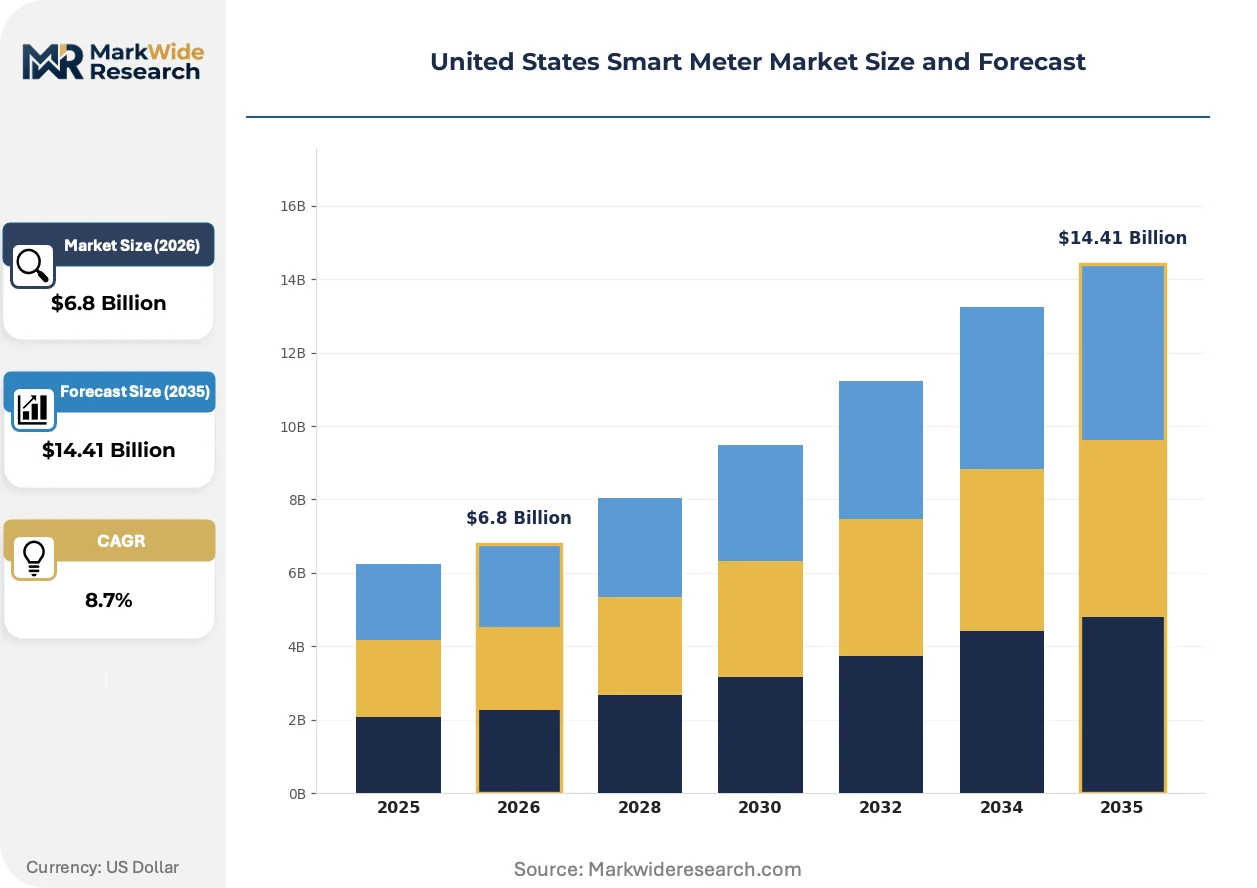
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Meters, Gas Meters, Water Meters, Multi-Utility Meters Technology: AMR, AMI, Wireless Communication, Wired Communication End User: Residential, Commercial, Industrial, Utilities Installation Type: Indoor, Outdoor, Wall-Mounted, Pole-Mounted |
| Companies Covered | Itron Inc., Landis+Gyr Group AG, Honeywell International Inc., Sensus USA Inc. (Xylem Inc.), Siemens AG, General Electric Company, ABB Group, Badger Meter Inc., Kamstrup A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Smart Meter Market Evolving Landscape
Edge computing architectures and cellular LPWAN protocols are reconfiguring how meters process and transmit consumption data, shifting intelligence from centralized utility systems toward distributed device-level analytics.
Cellular LTE-M and NB-IoT modems are replacing proprietary RF mesh networks in new AMI deployments. Municipal utilities in Texas and Arizona are specifying these standards for their extended range and reduced infrastructure requirements. This transition is digitizing last-mile connectivity economics by eliminating repeater dependencies and enabling direct cloud integration.
State public utility commissions in New York and California are mandating interval data access for distributed solar and storage interconnection. These rules force meter specification toward revenue-grade accuracy with sub-hourly measurement capability. Commercial and industrial ratepayers in these states are responding by procuring meters with embedded power quality monitoring for demand charge optimization.
Aftermarket service unbundling is separating hardware procurement from firmware maintenance and data analytics subscriptions. Investor-owned utilities in the Northeast are negotiating multi-year managed service agreements rather than capital purchases. This pattern concentrates most visibly in Con Edison and Eversource territories, where rate-base treatment of operational expenditures creates accounting preference for service-based contracting.
United States Smart Meter Market Segmentation
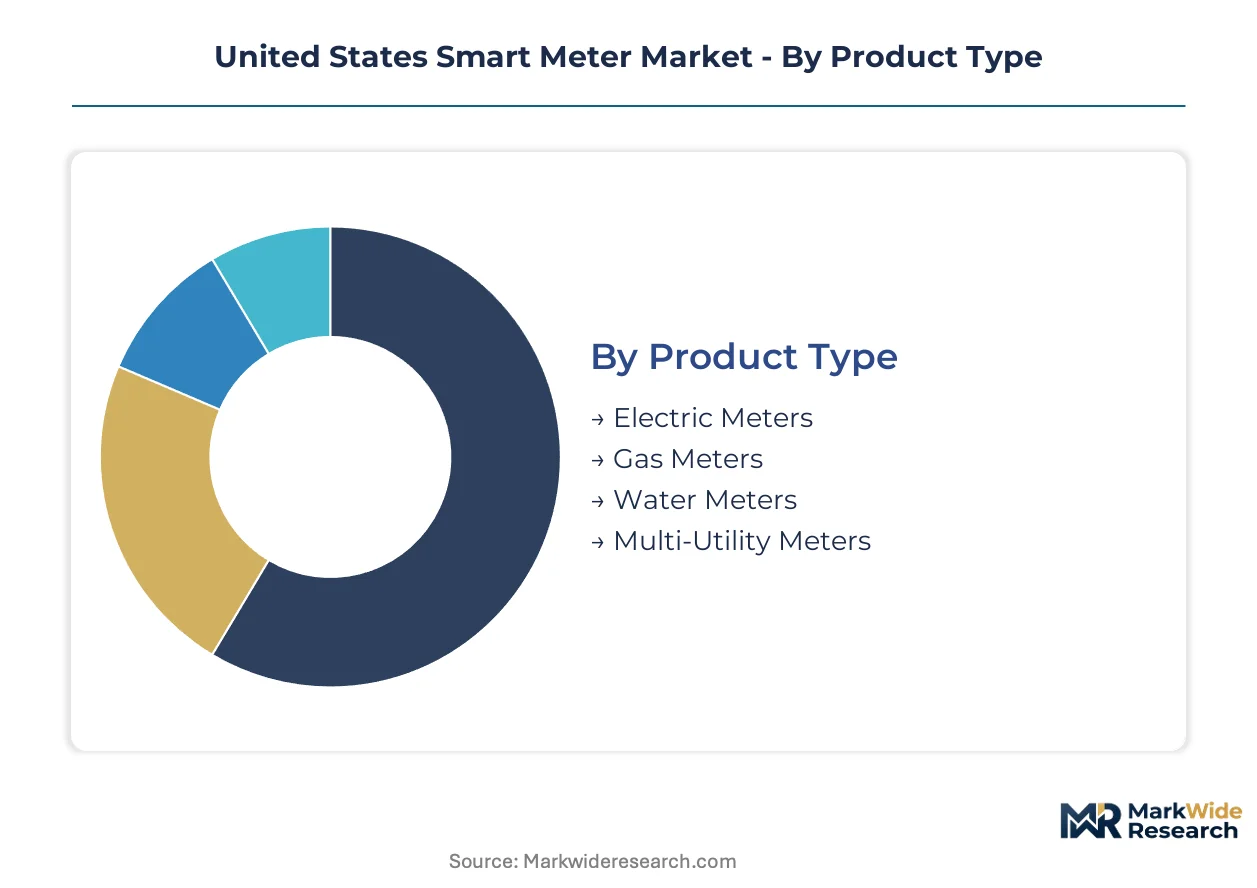
Smart meter procurement patterns diverge sharply across utility types and infrastructure constraints. Product specifications, communication protocols, and deployment environments each create distinct vendor qualification pathways and margin structures.
Product Type:
Mature electric metering dominates installed value while emerging water conservation applications reshape procurement priorities.
- Electric Meters:Solid-state measurement devices with ANSI C12 revenue-grade accuracy and embedded cellular modems. Investor-owned utilities in California and Texas concentrate procurement here due to FERC Order 2222 compliance mandates and aggressive decarbonization timelines.
- Water Meters:Interval-measurement units with remote telemetry for non-revenue water management. Municipal utilities across drought-stressed Southwest states prioritize these for leak detection and conservation pricing infrastructure.
- Gas Meters:Pressure-compensated diaphragm or ultrasonic designs with RF mesh or cellular backhaul for distribution network monitoring.
- Multi-Utility Meters:Consolidated measurement platforms serving electric, gas, and water through unified communication stacks.
Electric meters handle the majority of throughput; water meters are gaining share fastest on conservation mandates.
Technology:
Cost tier separation runs from legacy drive-by systems to premium two-way command infrastructure with cloud-native architectures.
- AMI:Advanced metering infrastructure with two-way communication, outage management, and distributed energy resource command capability. State renewable portfolio standards in New York and California force utilities toward this tier for solar and storage interconnection.
- AMR:Automated meter reading with one-way data transmission via drive-by or fixed network collection. Utilities with recent capital deployments face stranded asset risk when evaluating full replacement versus incremental upgrade pathways.
- Wireless Communication:Cellular LTE-M and NB-IoT protocols replacing proprietary RF mesh in new deployments.
- Wired Communication:Power-line carrier and Ethernet-based connectivity for high-density urban installations.
AMI commands the premium tier on functionality; wireless communication is climbing fastest on infrastructure cost reduction.
End User:
Customer type determines measurement granularity, data access requirements, and integration complexity with building automation systems.
- Utilities:Investor-owned and municipal entities with grid modernization mandates and conservation pricing authority. These customers specify revenue-grade accuracy with sub-hourly intervals and embedded power quality monitoring.
- Residential:Single-family and multi-family dwellings with basic consumption feedback and time-of-use rate exposure.
- Commercial:Office buildings, retail, and hospitality with demand charge optimization and sustainability reporting requirements.
- Industrial:Manufacturing and heavy process facilities with high-voltage metering and power quality analysis for equipment protection.
Utilities drive the largest contract volumes; commercial installations are expanding most quickly on building-to-grid convergence.
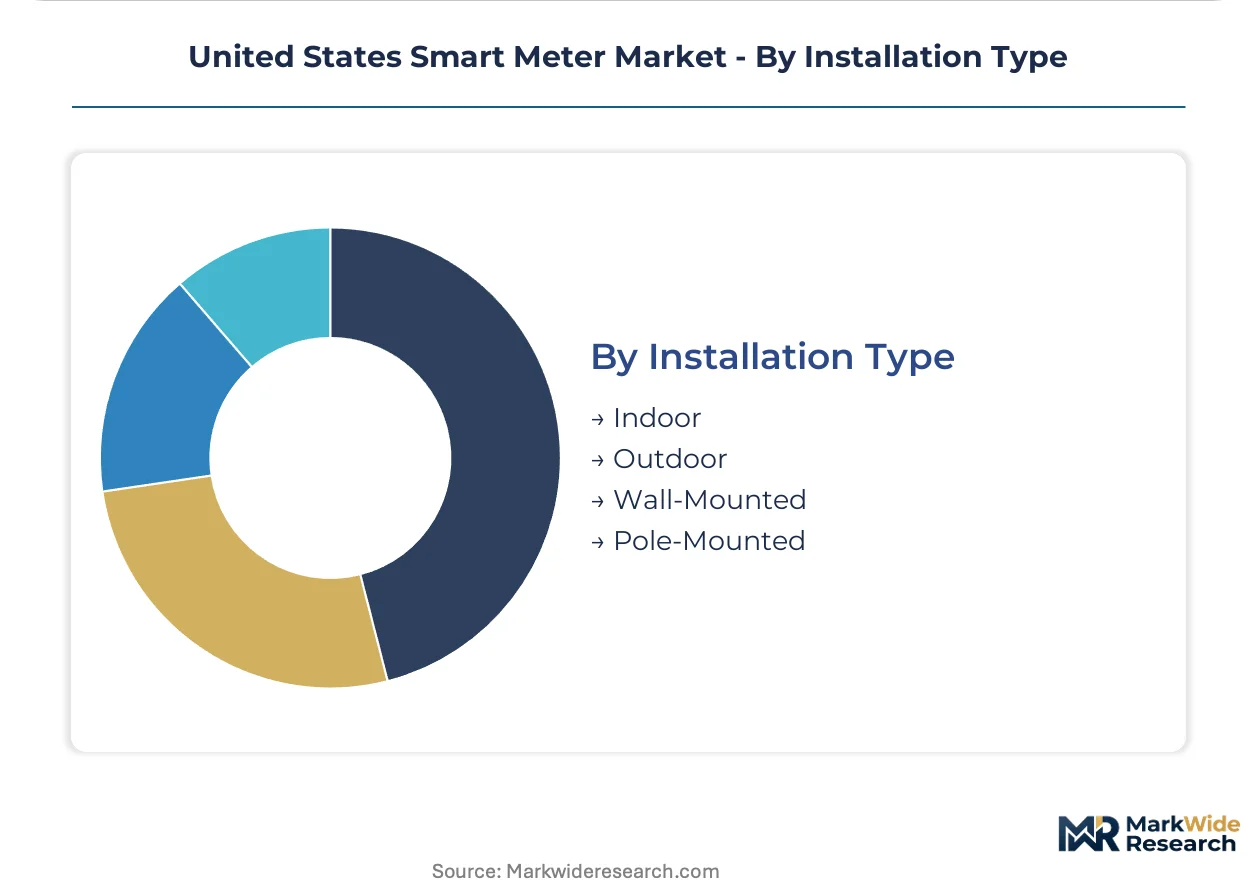
Installation Type:
Deployment environment dictates enclosure ratings, communication range requirements, and physical security specifications.
- Outdoor:NEMA-rated enclosures with extended temperature ranges and tamper-evident sealing for pole-mounted or pedestal installations.
- Indoor:Basement and utility room placements with reduced environmental protection requirements.
- Pole-Mounted:Elevated positioning for electric meters requiring line-of-sight for optical ports and technician access.
- Wall-Mounted:Surface or recessed attachment for water and gas meters in commercial and residential structures.
Outdoor configurations handle the majority of electric utility deployments; wall-mounted water meters are expanding fastest on municipal conservation programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in the Southwest and coastal states where drought stress and decarbonization mandates converge. Texas, California, and New York anchor procurement volume through distinct regulatory pathways and infrastructure investment cycles.
California
Investor-owned utilities face the most aggressive electrification deadlines in the nation. The California Public Utilities Commission mandates interval data access for distributed solar and storage interconnection. Southern California Edison and Pacific Gas & Electric territories concentrate demand for revenue-grade meters with sub-hourly measurement and embedded cellular modems.
Texas
Municipal water utilities across drought-stressed regions prioritize conservation pricing infrastructure. The Texas Commission on Environmental Quality enforces water loss reduction targets that pull districts toward AMI with leak detection analytics. Dallas-Fort Worth and Houston metro utilities are specifying cellular LTE-M protocols for extended range and reduced infrastructure costs.
New York
State renewable portfolio standards force utilities toward two-way command capability for distributed energy resource aggregation. The New York State Public Service Commission mandates advanced metering for grid modernization compliance. Con Edison and National Grid territories in the New York City metro area concentrate commercial and industrial demand for power quality monitoring.
Southwest
Arizona and New Mexico municipal water districts accelerate procurement on EPA conservation directives. State-level drought emergency declarations trigger accelerated replacement timelines for legacy mechanical meters. Phoenix and Tucson utilities are deploying interval-measurement devices with remote telemetry for non-revenue water management.
Pacific Northwest
Regional decarbonization commitments drive electric utility investment in grid-edge intelligence. State clean energy standards in Oregon and Washington require demand response enablement through AMI deployment. Seattle City Light and Portland General Electric territories prioritize meters with embedded power quality monitoring for renewable integration.
United States Smart Meter Market Competitive Landscape
Integrated conglomerates and metering specialists split the market through divergent capability bets. The vendor base clusters around three strategic archetypes: automation-platform bundlers seeking building-to-grid convergence, pure-play meter manufacturers defending hardware margins through firmware services, and industrial conglomerates leveraging utility relationships for cross-selling. Dominant competitive moves include strategic partnerships for protocol certification and portfolio diversification into water conservation applications.
Within the automation-platform tier, Honeywell International Inc. exemplifies building-system integration strategy. Itron Inc. and Landis+Gyr Group AG occupy positions as metering specialists with managed service architectures. These three entities represent contrasting bets on whether vendor economics will decouple from hardware replacement cycles or remain tied to capital deployment timelines.
| Leading Market Players |
|---|
| Itron Inc. |
| Landis+Gyr Group AG |
| Honeywell International Inc. |
| Sensus USA Inc. (Xylem Inc.) |
| Siemens AG |
| General Electric Company |
| ABB Group |
| Badger Meter Inc. |
| Kamstrup A/S |
| Others |
Value Network & Pricing Analysis
Taiwanese foundry clusters in Hsinchu Science Park anchor global RF modem chipset capacity, concentrating upstream leverage among meter manufacturers who must secure solid-state measurement components amid extended allocation cycles. This geographic bottleneck transmits directly into procurement premiums for utilities specifying ANSI C12 revenue-grade certification and embedded cellular connectivity.
Pricing Analysis
FERC Order 2222 dictates the pricing tier structure across the United States Smart Meter Market by mandating two-way command capability as baseline functionality. Three-tier pricing structure across premium AMI, standard cellular-enabled units, and economy AMR legacy replacements separates vendor portfolios. Price differentiation hinges on cybersecurity certification level under NIST frameworks and firmware upgrade pathway guarantees. Cost compression in standard cellular tiers is intensifying because semiconductor sourcing constraints force manufacturers to prioritize high-margin electric utility contracts. Municipal water districts exhibit highest price sensitivity due to ratepayer-funded capital constraints, while investor-owned utilities in California demonstrate lowest sensitivity given rate-base recovery mechanisms.
Supply Chain Analysis
RF modem chipsets and solid-state measurement components draw from concentrated Asian foundry capacity in Taiwan, South Korea, and mainland China. Meter assembly rests on ceramic substrate supply from Japanese specialists, precision current transformers from German manufacturers, and lithium primary cells for gas meter endpoints. Single-source vulnerability in 5G NR modem silicon creates qualification bottlenecks for vendors seeking IEEE 2030 interoperability certification. Distribution runs through direct utility procurement channels with multi-year framework agreements, supplemented by systems integrators serving municipal water districts with bundled AMI deployment services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Smart Meter Market represents early-cycle expansion as federal grid modernization mandates and state renewable portfolio standards force replacement of decades-old mechanical infrastructure. FERC Order 2222 compliance deadlines accelerate penetration curves beyond historical replacement rates.
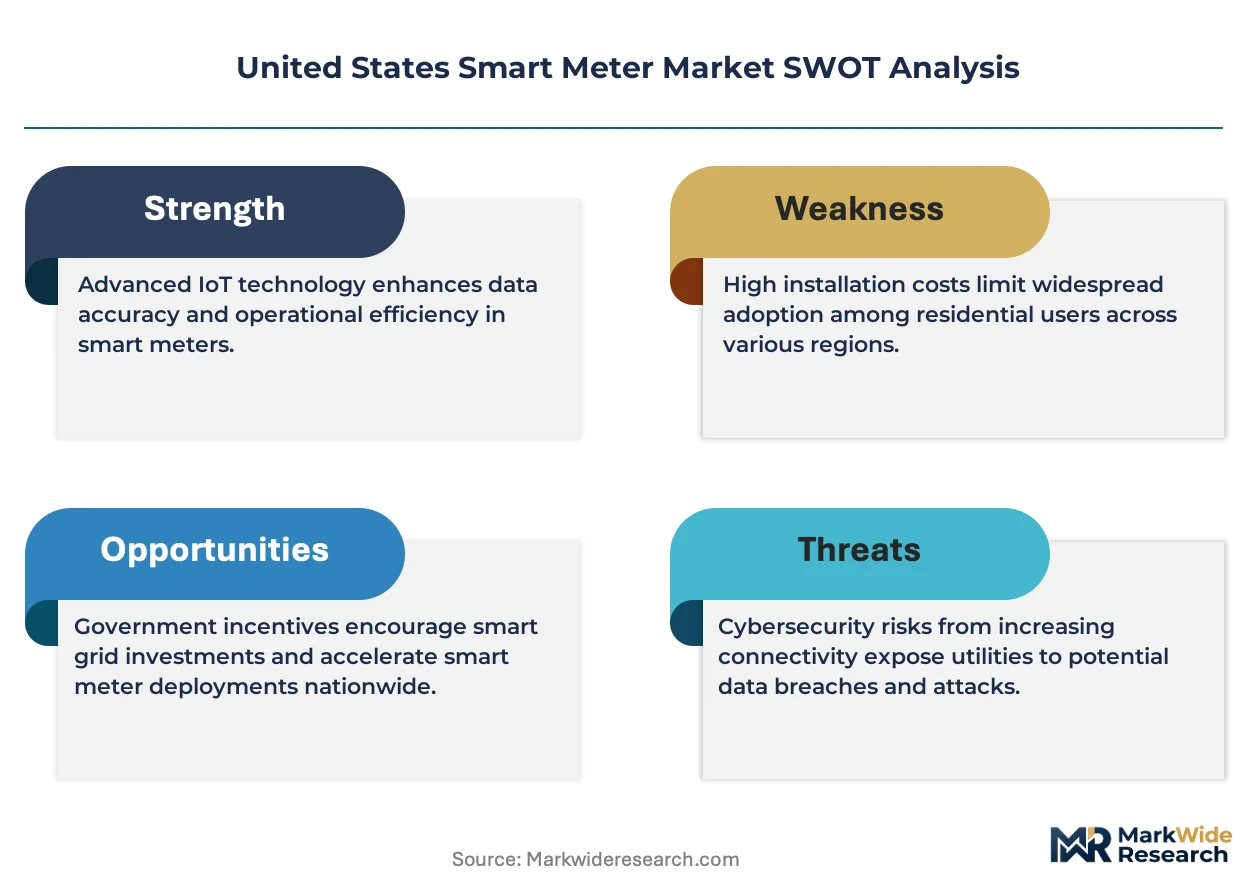
For Market Incumbents: Entrench position through firmware-as-a-service architectures that extend customer lifecycles beyond hardware deployment cycles. Deepen utility partnership structures to capture recurring revenue streams from managed services. Vertical integration into cellular module sourcing mitigates semiconductor allocation risk from concentrated Asian foundry capacity. For New Entrants and Emerging Players: Texas municipal water utilities facing drought-stressed conservation mandates represent the most penetrable entry point for leak-detection-optimized meter portfolios. Southwest states with accelerated EPA water loss reduction timelines offer white-space procurement opportunities outside incumbent electric utility relationships. Direct sales to municipal engineering departments bypasses systems integrator channel control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with certified encryption stacks and protocol adaptability under NIST cybersecurity frameworks. Long-term viability hinges on decoupling economics from hardware replacement through service-based contracting models. Watch for state public utility commission mandate acceleration as inflection indicator for demand pull-forward.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-as-a-Service Transition | Itron's managed services portfolio demonstrates recurring revenue architectures that extend customer lifecycles beyond capital deployment cycles. |
| Cellular LPWAN Protocol Migration | Texas utilities specifying LTE-M and NB-IoT standards eliminate repeater infrastructure costs while enabling direct cloud integration. |
| Water Conservation Application Expansion | Drought-stressed Southwest municipal districts prioritize leak detection analytics, creating fastest-growing product category segmentation. |
| Cybersecurity Certification Investment | NIST framework compliance creates vendor qualification bottlenecks that favor incumbents with certified encryption stacks. |
| Building-to-Grid Convergence Partnerships | Honeywell bundles metering with HVAC automation software, opening integrated demand response revenue streams beyond standalone hardware. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, AMI program managers, municipal engineering directors, and metering systems procurement leads; and secondary validation through FERC filings, EPA water loss reduction guidance documents, state public utility commission mandate records, and investor-owned utility rate case filings. Bottom-up triangulation against top-down market sizing ensured segmentation integrity across product type, technology tier, and end-user categories.
Forecast inputs incorporated utility capital expenditure disclosure patterns, state renewable portfolio standard compliance timelines, and federal grid modernization appropriation flows across the projection horizon. Segmentation modeling captured electric, water, and gas meter categories; AMI versus AMR technology tiers; and investor-owned, municipal, and cooperative utility ownership structures. CAGRs were derived from deployment pipeline analysis and replacement cycle compression factors specific to decarbonization mandate acceleration.
Practitioners should monitor semiconductor allocation cycles and state public utility commission mandate acceleration for early signals of forecast revision. Cross-checking against EIA utility expenditure surveys and EPA water system audit data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Smart Electric Meter Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
Water Meter Market
Smart Meters
Smart Gas Meter Market
Smart Meters
Europe Smart Meters Market
Smart Meters
Smart Meters Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
Middle East and Africa Smart Meters Market
Smart Meters
North America Smart Meters Market
Smart Meters
Plug in Power Meter Market
Smart Meters
Watt Meter Market
Smart Meters
Single-Phase Anti-Theft Meter Market
Smart Meters
Global Smart Water Meter Market
Smart Meters
Europe Smart Water Meter Market