
 Heat Pump Water Heater Market | 2026-2036
Heat Pump Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Pump Water Heater Market Analysis
R-410A refrigerant phaseout is recalibrating compressor design and unit cost structures across the heat pump water heater industry. Daikin Industries Ltd. leverages its captive compressor technology to control supply chain exposure during the transition. Panasonic Holding Corporation anchors its position through deep manufacturing integration in Japan and Southeast Asia. Rheem Manufacturing Company competes aggressively in North American distribution channels with contractor-focused product lines.
Heat pump water heaters transfer thermal energy from ambient air, ground, or water sources to heat domestic or commercial water using vapor-compression refrigeration cycles with coefficients of performance typically ranging from 2.0 to 3.5. These systems serve as primary water heating equipment in residential buildings, hotels, hospitals, and light industrial facilities seeking to displace direct fossil fuel combustion. The residential end user segment commands the largest installed base volume, though commercial applications generate superior margin pools due to scale requirements and service contract attach rates. Air source heat pump configurations dominate unit shipments globally, while split system architectures gain traction in colder climate zones where indoor tank placement prevents freeze risk.
The EU Green Deal and F-Gas Regulation in Europe, alongside NHTSA building efficiency guidelines and EPA refrigerant management rules in the United States, collectively mandate higher seasonal performance factors and lower global warming potential refrigerants. These frameworks compress product development cycles and raise capital barriers for manufacturers lacking in-house testing and certification capabilities. Stakeholders must monitor refrigerant patent landscapes and regional subsidy program continuity to align capacity investments with demand geography.
Market Dynamics
The R-410A refrigerant phaseout is compressing product development cycles and forcing compressor redesigns across the heat pump water heater supply base, with manufacturers racing to certify lower-GWP alternatives before efficiency mandates tighten.
Growth Catalysts
- EU Green Deal building renovation mandates:Germany, France, and the United Kingdom now require heat pump compatibility in residential retrofits, accelerating replacement of conventional electric storage units.
- F-Gas Regulation refrigerant standards:The European framework mandates lower global warming potential alternatives, pulling demand toward heat pump water heaters that displace direct fossil fuel combustion.
- Air source heat pump configurations:These systems dominate unit shipments globally due to simpler installation requirements and broader ambient temperature operating ranges.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger materials face price swings that compress manufacturing margins and destabilize quoted project costs.
- Compressor supply concentration in East Asia:Captive production capabilities at Japanese and South Korean manufacturers limit sourcing flexibility for European and North American assemblers.
- Cold climate performance degradation:Air source units experience coefficient of performance drops below freezing temperatures, restricting addressable markets in Nordic and alpine zones without supplemental heating.
Strategic Opportunities
- Split system architectures in cold climate zones:Indoor tank placement prevents freeze risk and opens Nordic residential markets previously closed to monobloc designs.
- Commercial service contract attach rates:Hotels, hospitals, and light industrial facilities generate superior margin pools through scale requirements and long-term maintenance agreements.
- US Inflation Reduction Act residential incentives:Tax credits for heat pump installations are expanding addressable demand in single-family housing retrofits.
Industry Challenges
- Refrigerant handling certification timelines:Technician licensing requirements for flammable A2L and A3 refrigerants are extending installation workforce deployment.
- Legacy electrical panel capacity constraints:Residential retrofit sites often require service upgrades to accommodate heat pump water heater load profiles, adding project complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Pump Water Heater Market |
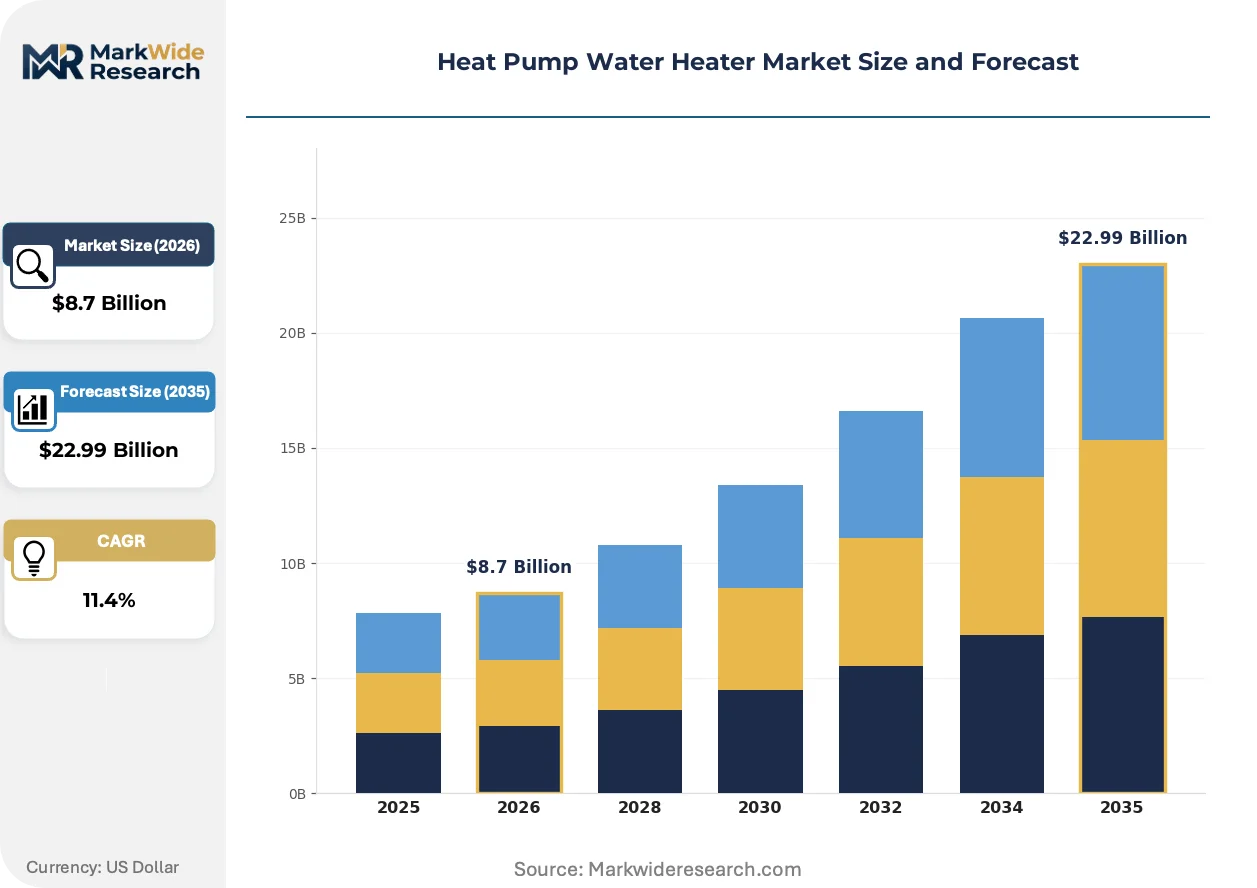
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Heat Pump, Split System, Integrated Heat Pump, Air Source Heat Pump End User: Residential, Commercial, Industrial, Institutional Installation Type: Indoor, Outdoor, Wall-Mounted, Floor-Mounted Energy Source: Electricity, Solar, Natural Gas, Propane |
| Companies Covered | Daikin Industries Ltd., Panasonic Holding Corporation, LG Electronics, STIEBEL ELTRON GmbH & Co., Rheem Manufacturing Company, A. O. Smith, Johnson Controls-Hitachi Air Conditioning, Trane Technologies, Bradford White Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Pump Water Heater Market Emerging Trajectories
Refrigerant chemistry transitions and system architecture evolution are actively reshaping competitive positioning in heat pump water heaters, with efficiency thresholds and climate adaptability becoming primary design constraints.
CO2 transcritical heat pump cycles are consolidating market share in commercial high-temperature applications. These systems deliver water temperatures above 90°C without efficiency collapse, attracting hotels and food processing facilities in Japan and Europe. The technology is consolidating supplier bases as only specialized compressor manufacturers can meet the 10 MPa pressure requirements.
EPA refrigerant management rules and NHTSA building efficiency guidelines in the United States are compressing allowable global warming potential thresholds. Equipment manufacturers must now certify A2L mildly flammable alternatives like R-32 and R-454B, forcing redesign of safety systems and electrical enclosures. The residential replacement segment faces the steepest compliance curve as existing inventory loses regulatory eligibility.
Building renovation procurement is fragmenting across specialized energy service companies and HVAC contractors. Traditional plumbing distributors are losing specification authority to firms bundling heat pump water heaters with envelope upgrades and solar thermal integration. This pattern concentrates in German and French markets where whole-building performance contracting dominates public housing retrofits.
Heat Pump Water Heater Market Segmentation
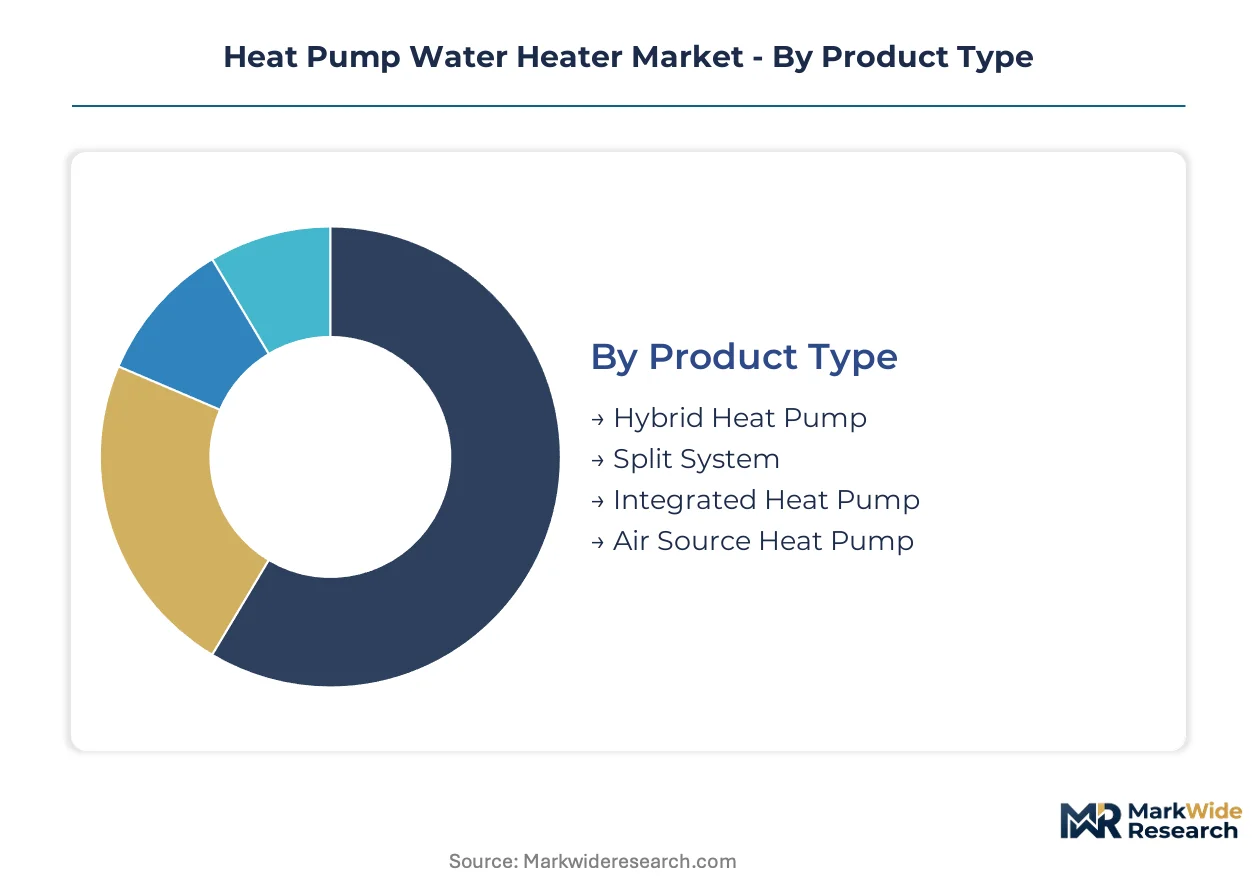
Product architecture and installation constraints shape procurement decisions across the heat pump water heater market. End-use requirements diverge sharply between single-family retrofits and commercial facilities with continuous hot water demand.
Product Type:
Buyer selection hinges on climate exposure and retrofit compatibility rather than upfront cost alone.
- Hybrid Heat Pump:Combines vapor-compression heat pump cycles with electric resistance backup elements to maintain output during peak demand periods. Demand concentrates in North American residential retrofits where existing electrical infrastructure cannot support pure heat pump load profiles during winter months.
- Air Source Heat Pump:Extracts thermal energy from ambient air through finned-tube evaporators, offering the simplest installation topology among heat pump water heater categories. Germany, France, and the United Kingdom now specify these systems in building renovation mandates targeting fossil fuel displacement.
- Split System:Separates compressor/condenser assemblies from storage tanks via refrigerant lines, enabling indoor tank placement in freezing climates.
- Integrated Heat Pump:Houses all components in a single enclosure, minimizing field refrigerant handling and installation labor.
Volume sits with air source configurations; growth tilts toward split system architectures.
End User:
Scale requirements and duty cycle intensity determine margin structure and service contract potential.
- Residential:Single-family and multi-family housing units drive unit shipment volumes through replacement of conventional electric storage tanks. EU Green Deal renovation mandates in Germany and France are accelerating retrofit specifications.
- Commercial:Hotels, hospitals, and food service facilities generate superior margin pools through continuous hot water demand and mandatory service agreements. Japan's commercial sector leads adoption of CO2 transcritical systems for high-temperature applications.
- Industrial:Process hot water requirements in light manufacturing favor larger capacity units with customized control integration.
- Institutional:Schools, government facilities, and military installations prioritize equipment with extended warranty terms and certified maintenance networks.
Residential commands installed base volume; commercial applications are climbing the fastest.
Installation Type:
Site constraints and freeze risk exposure dictate architectural selection across climate zones.
- Indoor:Basement and utility room placements protect components from temperature extremes and precipitation, dominating Northern European markets.
- Outdoor:Sidewall and ground-mounted configurations reduce indoor space requirements but require cold-weather defrost cycles.
- Wall-Mounted:Vertical installations maximize floor space efficiency in compact urban dwellings common in Japanese and South Korean housing stock.
- Floor-Mounted:Traditional tank-on-floor arrangements simplify plumbing connections in North American residential retrofits.
Floor-mounted units retain volume leadership; wall-mounted designs gain share fastest in dense urban markets.
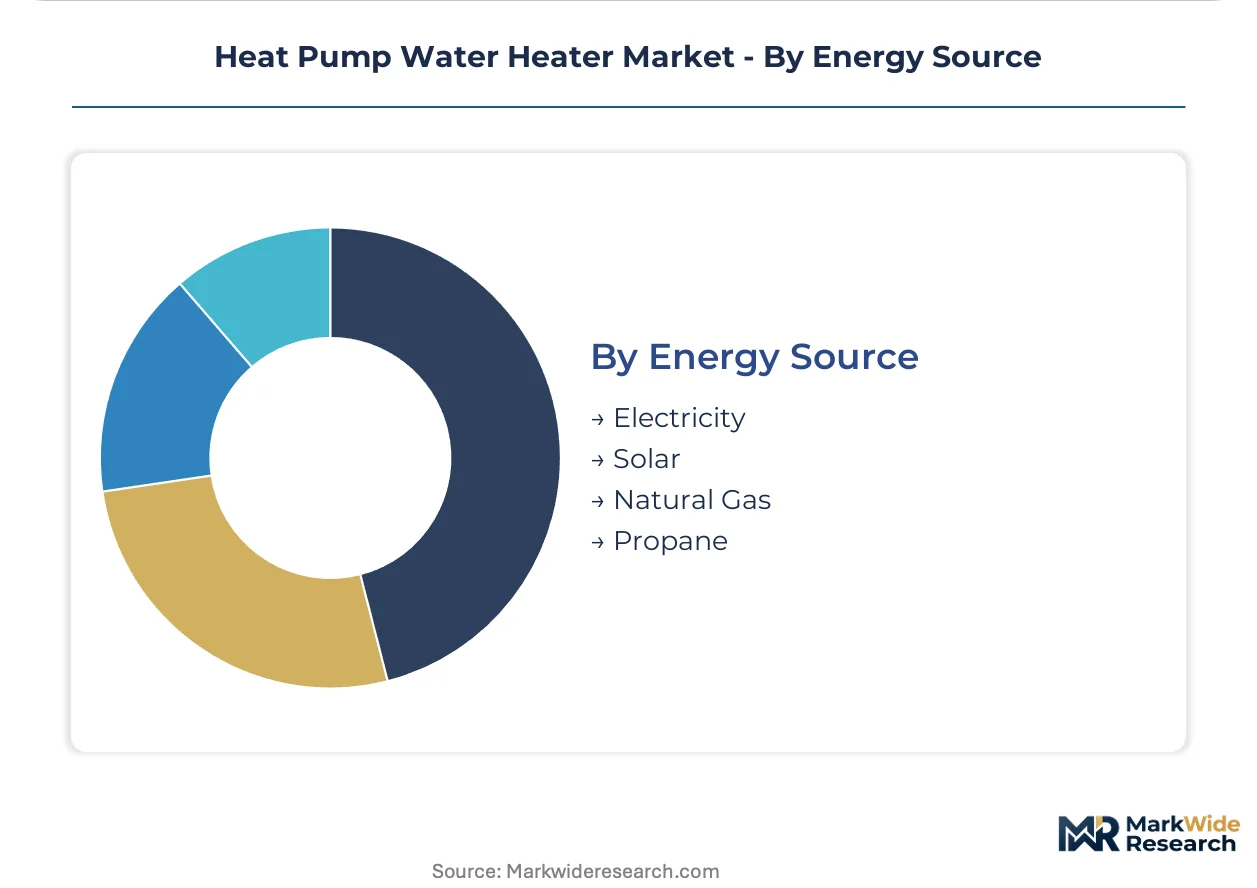
Energy Source:
Grid carbon intensity and behind-the-meter generation capacity reshape operating economics.
- Electricity:Grid-powered compressor operation dominates configurations, with efficiency gains dependent on regional power generation mix.
- Solar:Photovoltaic-to-heat pump coupling reduces effective operating costs where net metering or time-of-use rates apply.
- Natural Gas:Hybrid gas-electric configurations persist in markets with low gas tariffs and limited electrical panel capacity.
- Propane:Rural and off-grid installations in North America utilize propane backup for extreme cold conditions.
Electricity underpins current volume; solar-integrated systems are expanding most quickly in subsidy-rich European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heat pump water heater procurement concentrates in markets where building renovation mandates intersect with fossil fuel displacement targets. Germany, Japan, the United States, France, and the United Kingdom anchor current volume, with regulatory frameworks accelerating replacement cycles for conventional electric storage units.
Germany
The Federal Ministry for Economic Affairs and Climate Action drives heat pump adoption through the Building Energy Act, which mandates renewable heating in new construction and major renovations. The F-Gas Regulation tightens refrigerant standards, pulling specifications toward lower-GWP alternatives. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate manufacturing and installation contractor networks serving residential retrofit demand.
Japan
METI's strategic energy plan prioritizes heat pump electrification in commercial buildings and multi-family housing. CO2 transcritical systems dominate high-temperature applications for hotels and food processing facilities. Manufacturing gravity centers on Osaka-Kobe and Nagoya industrial corridors, where captive compressor production supports domestic and export supply.
United States
The Inflation Reduction Act tax credits expand single-family retrofit eligibility, while EPA refrigerant management rules compress allowable GWP thresholds. NHTSA building efficiency guidelines raise performance factor minimums for federal housing stock. Distribution concentrates in Southeast and Southwest states where heat pump economics outperform resistance heating across wider temperature bands.
France
The National Low Carbon Strategy and MaPrimeRénov subsidy program accelerate residential building envelope upgrades bundled with heat pump water heater installation. ANSM and environmental regulators enforce refrigerant handling certification for flammable A2L alternatives. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate energy service companies delivering whole-building performance contracting.
United Kingdom
The Future Homes Standard and Boiler Upgrade Scheme phase out fossil fuel heating in new construction from 2025. Ofgem regulations and building codes tighten efficiency requirements for replacement installations. Installer networks cluster in Greater London and the Midlands, where housing stock age drives retrofit opportunity density.
Heat Pump Water Heater Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated appliance makers commanding premium positioning and regional assemblers capturing price-sensitive volume. The vendor base organizes around three archetypes: captive compressor specialists with backward integration into refrigeration cycles, heating-equipment diversifiers leveraging distribution scale, and climate-system conglomerates cross-selling from HVAC installed bases. Competitive moves concentrate on refrigerant transition certification racing and cold-climate performance differentiation.
Among Japanese industrial conglomerates, Daikin Industries Ltd. and Panasonic Holding Corporation anchor the captive technology tier, representing compressor-design capabilities that limit supply chain exposure during refrigerant phaseout transitions. Rheem Manufacturing Company exemplifies the North American distribution-focused archetype, occupying a position built on contractor-channel relationships and retrofit-specific product configurations. These three entities illustrate how geographic manufacturing integration and regulatory timing alignment determine competitive position.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Panasonic Holding Corporation |
| LG Electronics |
| STIEBEL ELTRON GmbH & Co. |
| Rheem Manufacturing Company |
| A. O. Smith |
| Johnson Controls-Hitachi Air Conditioning |
| Trane Technologies |
| Bradford White Corporation |
| Others |
Supply Flow & Price Mechanics
Captive compressor production in Japan and South Korea anchors supply chain control for manufacturers navigating refrigerant transitions, simultaneously insulating pricing power for integrated players while exposing non-integrated assemblers to margin compression during input volatility.
Pricing Analysis
Volume concentrates in air source units sold through plumbing distributors, while margin pools accrue to CO2 transcritical systems for commercial high-temperature applications. Price differentiation hinges on seasonal performance factor certification tiers and cold-climate operating ranges, with A2L refrigerant handling requirements adding compliance premiums. Pricing pressure stems from copper and aluminum input volatility destabilizing quoted project costs. Residential retrofits exhibit highest price sensitivity due to electrical panel upgrade burdens, whereas commercial buyers prioritize service contract bundling over upfront equipment cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States manage hub-and-spoke patterns for compressor and heat exchanger components. Manufacturing draws from Japan, South Korea, and China for rotary and scroll compressor technologies, with aluminum fin stock and copper tubing sourced from global metals exchanges. Single-source vulnerability concentrates in specialized CO2 transcritical compressor suppliers capable of 10 MPa pressure ratings. Distribution runs through HVAC wholesalers and energy service companies, with contractor-focused channels dominating North American residential retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressor supply concentration in East Asia props pricing power for integrated manufacturers while constraining capacity expansion for European and North American assemblers racing refrigerant certification deadlines.
For Market Incumbents: Lock in captive compressor supply agreements before A2L refrigerant certification timelines compress sourcing flexibility. Defend margin position through backward integration into heat exchanger manufacturing in Germany and Japan, countering copper price volatility that threatens project quoting stability. Prioritize cold-climate performance differentiation to capture Nordic residential markets opening to split system architectures. For New Entrants and Emerging Players: Launch via direct-to-contractor digital platforms targeting North American residential retrofits underserved by traditional plumbing distributor networks. White-space opportunities concentrate in commercial service contract bundling for hotels and hospitals, where incumbent coverage gaps exist in secondary metropolitan markets. Target solar-integrated system configurations in subsidy-rich European markets where photovoltaic-to-heat pump coupling reduces effective operating costs. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to climate-system conglomerates seeking refrigerant transition capabilities and cold-climate product portfolios. Long-term viability favors manufacturers with in-house testing and certification infrastructure capable of compressing product development cycles under tightening efficiency mandates. Watch F-Gas Regulation enforcement intensity as the inflection indicator for European demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Certification | EPA and EU Green Deal mandates force A2L alternative adoption ahead of R-410A phaseout deadlines. |
| Backward Integration into Compressors | Daikin and Panasonic demonstrate how captive technology limits supply chain exposure during chemistry transitions. |
| Cold-Climate Performance Differentiation | Split system architectures unlock Nordic markets previously closed to monobloc air source designs. |
| Commercial Service Contract Bundling | Hotels and hospitals generate superior margin pools through continuous demand and mandatory maintenance agreements. |
| Solar-Integrated System Development | Photovoltaic coupling reduces operating costs where European net metering or time-of-use rates apply. |
Methodological Framework
Independent corroboration across heat pump equipment manufacturers, HVAC contractor networks, and regulatory affairs specialists underwrites the qualitative findings. Primary interviews engaged product development executives at compressor OEMs, procurement leads at water heater assemblers, installation contractors in Germany and the United States, and energy service company technical directors. Secondary validation drew from EPA refrigerant management filings, EU F-Gas Regulation implementation reports, Building Energy Act documentation, and customs data on compressor trade flows. Bottom-up shipment estimates triangulated against top-down building renovation mandate targets.
Rate-of-change decomposition across product architecture, end-use segment, installation type, and energy source dimensions structured the analytical framework. CAGRs derived from segment-level shipment trajectories weighted by efficiency-tier pricing differentials. Modeled inputs included EU Green Deal renovation mandate implementation schedules, Inflation Reduction Act tax credit uptake curves, and refrigerant handling certification workforce deployment timelines.
Refrigerant chemistry transition delays, subsidy program discontinuities, and copper price volatility spikes are the dominant revision risks. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Efficiency Solutions
Energy Efficiency Gamification Market
Energy Efficiency Solutions
Energy Efficient Warehouse Lighting System Market
Energy Efficiency Solutions
Energy Retrofit Systems Market
Energy Efficiency Solutions
Residential Energy-Efficient Technologies Market
Energy Efficiency Solutions
Energy Efficient Lighting Technology Market
Energy Efficiency Solutions
Energy Efficient Lighting Market
Energy Efficiency Solutions
Residential Air to Water Heat Pump Market
Energy Efficiency Solutions
Energy Efficient Windows Market
Energy Efficiency Solutions
Energy-Saving Constant Humidity Storage Cabinet Market
Energy Efficiency Solutions
Global Energy Efficient Lamps and Ballasts Market
Energy Efficiency Solutions
Waste Heat Recovery System Market
Energy Efficiency Solutions
Economizer Market
Energy Efficiency Solutions
Energy Retrofits Market