
 Nuclear Fuel Fabrication Market | 2026-2036
Nuclear Fuel Fabrication Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Fuel Fabrication Market Outlook
Long-term fuel management contracts is repositioning how vendors capture lifetime value from reactor operators. Westinghouse Electric Company leverages its integrated fuel and services portfolio to lock in decades-long utility relationships. Framatome sustains its European dominance through proprietary MOX fabrication capabilities at its Melox facility. BWXT anchors the North American specialty fuels segment with naval reactor contracts that demand exacting metallurgical standards.
Nuclear fuel fabrication encompasses the conversion of enriched uranium hexafluoride into ceramic uranium dioxide pellets, their loading into zirconium alloy tubes, and assembly into fuel bundles for light water reactors. The process requires sintering temperatures exceeding 1700°C to achieve theoretical densities above 95% for reliable in-reactor performance. Uranium dioxide pellets retain the largest share of product type output, though advanced accident-tolerant fuels with chromium-coated cladding represent the fastest-growing margin pool. Reprocessing technology carries concentrated value due to its capital intensity and regulatory barriers, while direct fabrication dominates volume through its established supply chains serving pressurized water reactors.
The U.S. Nuclear Regulatory Commission enforces 10 CFR Part 50 licensing requirements that govern fuel design approval timelines and manufacturing quality assurance. France's Autorité de Sûreté Nucléaire and the EMA collaborate on cross-border MOX transport and fabrication standards that shape European supply logistics. The IAEA safeguards framework and national export control regimes under the Nuclear Suppliers Group constrain market access for new fabrication entrants. Stakeholders must monitor how Western government fuel security initiatives reshape sourcing mandates for reactor operators.
Market Dynamics
Accident-tolerant fuel qualification timelines are compressing competitive windows as the Department of Energy accelerates doped uranium dioxide pellet testing. Western utilities now demand fuel designs that withstand loss-of-coolant accidents at higher temperatures, forcing fabricators to retool sintering lines and recertify zirconium alloy supply chains before rival designs achieve regulatory approval.
Growth Catalysts
- Operating License Extensions:U.S. utilities under 10 CFR Part 54 are securing 20-year reactor life extensions, locking in replacement fuel assembly demand through mid-century.
- Closed Fuel Cycle Mandates:France's reprocessing infrastructure at La Hague generates plutonium feedstock for MOX fabrication, sustaining domestic load factors and export contracts to Japan and Belgium.
- Chromium-Coated Cladding:Advanced accident-tolerant fuel programs are qualifying coated zirconium tubes that reduce oxidation rates during beyond-design-basis events.
Market Restraints
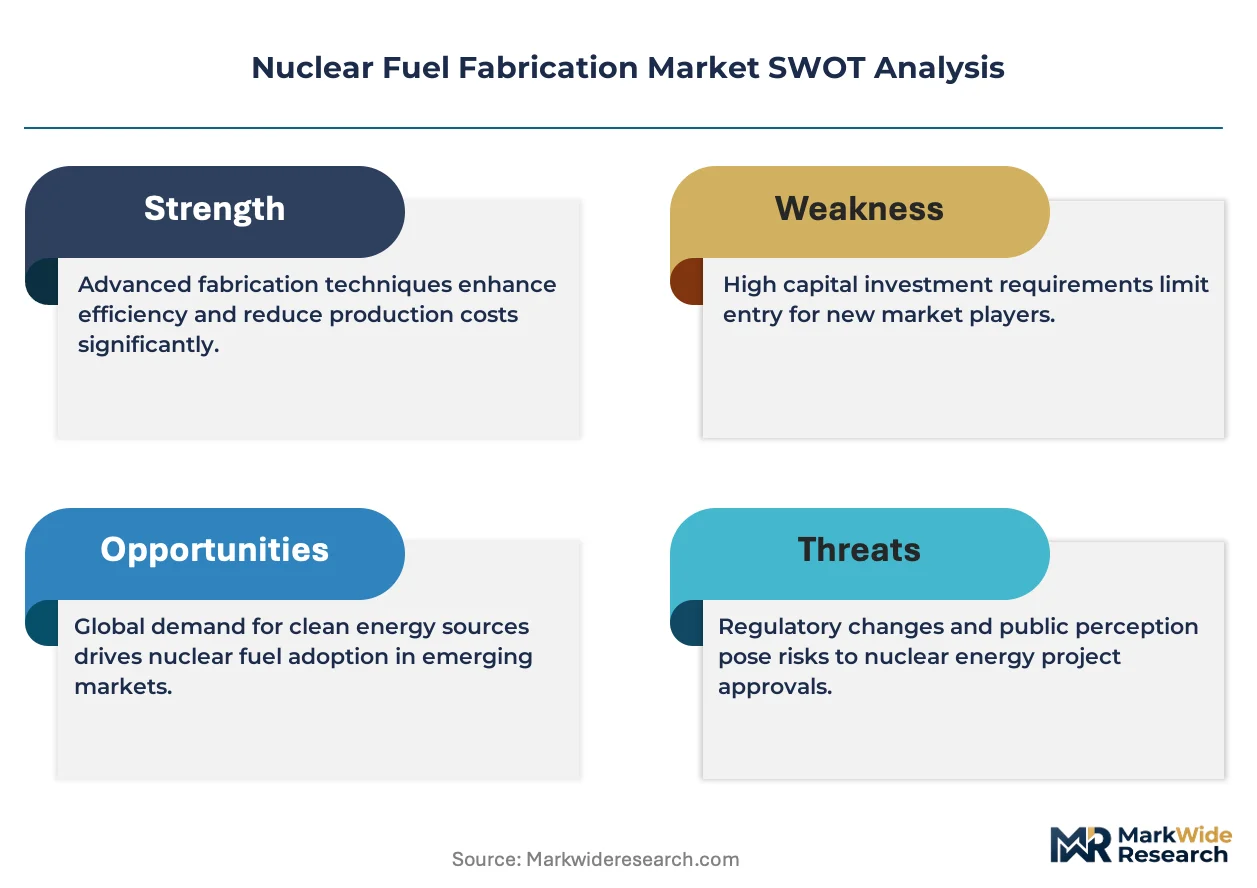
- Enrichment Supply Concentration:Conversion of uranium hexafluoride depends on a handful of Western enrichment facilities, creating chokepoints if geopolitical disruptions affect feedstock flows.
- Sintering Energy Intensity:Achieving 95% theoretical density requires furnace temperatures exceeding 1700°C, exposing fabricators to volatile natural gas and electricity pricing.
- 10 CFR Part 50 Licensing Friction:The U.S. Nuclear Regulatory Commission's design approval timelines extend 18-36 months for novel fuel geometries, delaying revenue recognition.
Strategic Opportunities
- Small Modular Reactor Fuel Formats:Higher-assay low-enriched uranium designs for NuScale and TerraPower reactors require specialized pellet geometries that incumbent vendors can capture first.
- EU Taxonomy Alignment:The European Union's sustainable finance classification is channeling institutional capital toward nuclear fuel projects that meet stringent lifecycle emissions criteria.
- Digital Twin Integration:Fabricators deploying in-reactor performance modeling alongside 10 CFR Part 50 quality assurance are differentiating on predictive fuel reliability metrics.
Industry Challenges
- Metallurgical Talent Scarcity:Zirconium alloy tube drawing and welding require skills concentrated among aging workforces at legacy naval and commercial fuel facilities.
- Dual-Use Export Control Complexity:IAEA safeguards and Nuclear Suppliers Group restrictions complicate cross-border shipment of enriched uranium hexafluoride and fabricated assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Fuel Fabrication Market |
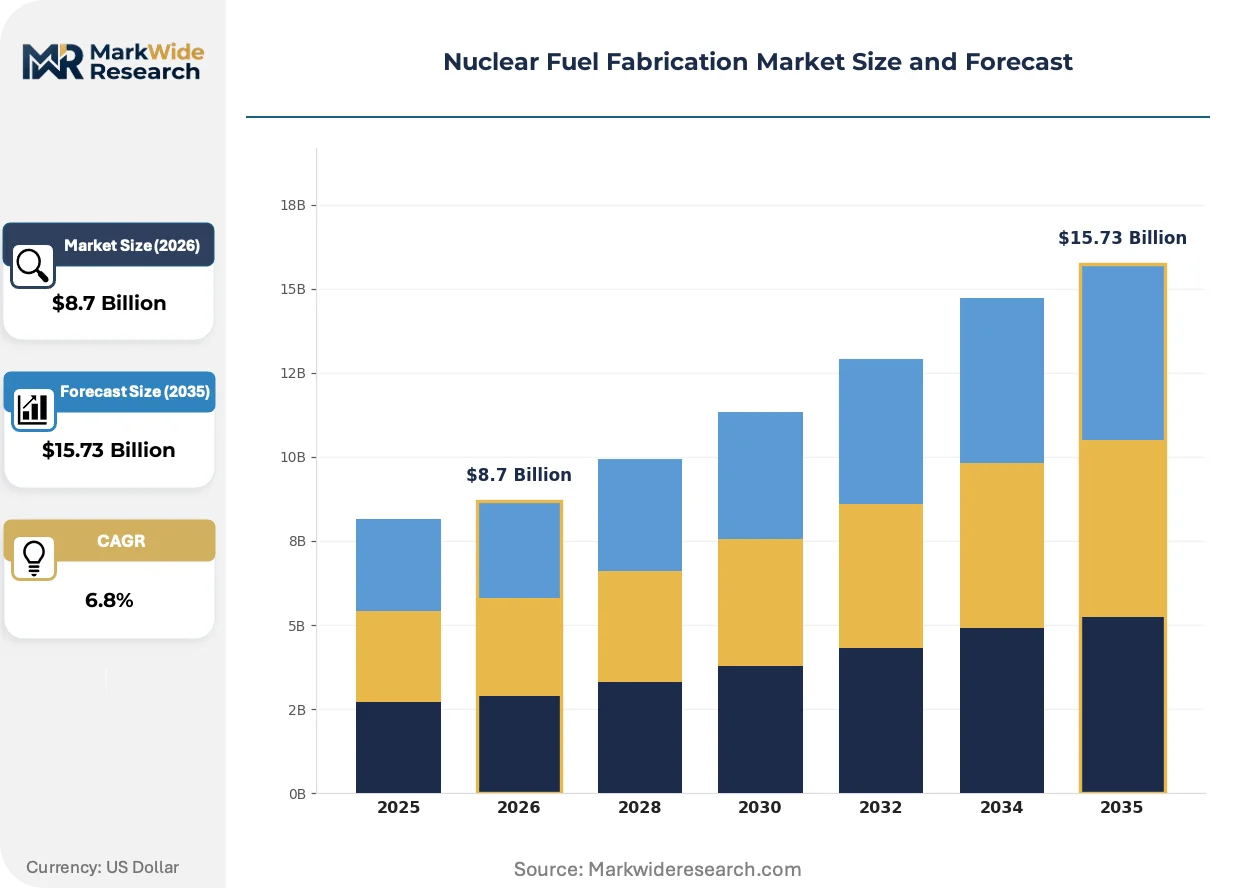
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uranium Dioxide, Mixed Oxide, Thorium Fuel, Other Fuels End User: Nuclear Power Plants, Research Institutions, Defense, Others Technology: Direct Fabrication, Advanced Separation Processes, Reprocessing, Elemental Conversion Form: Pellets, Rods, Assemblies, Other Formats |
| Companies Covered | Westinghouse Electric Company, General Electric, Framatome, GE Vernova, BWXT, TRISO-X, Standard Nuclear, Mitsubishi Heavy Industries, Toshiba Energy System & Solutions Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Fuel Fabrication Market Strategic Shifts
Fabrication technology is pivoting toward materials and processes that extend fuel residence times while satisfying stricter post-Fukushima safety margins. Digital quality assurance and predictive modeling are compressing the gap between laboratory qualification and commercial deployment.
Chromium-coated zirconium cladding is absorbing engineering resources across the accident-tolerant fuel development pipeline. Westinghouse and Framatome are deploying coated tube prototypes in lead test assemblies at operating pressurized water reactors. This material transition is absorbing capital that would otherwise fund incremental uranium dioxide pellet density improvements.
The Department of Energy's Advanced Fuels Campaign is reshaping U.S. regulatory precedent through accelerated timeline waivers for qualifying high-burnup fuel designs. Fabricators responding to this policy shift are pre-positioning manufacturing capacity before 10 CFR Part 50 rulemakings codify new safety criteria. Light water reactor operators in the American Southeast are prioritizing fuel vendors with demonstrated accident-tolerant fuel delivery schedules.
Utility procurement departments are consolidating fuel assembly contracts into multi-cycle agreements that bundle fabrication with core design services. This purchasing consolidation is squeezing independent engineering consultancies that previously supplied reload analysis separately. French and American utilities are leading this bundling shift, locking in decade-long supplier relationships that reduce switching flexibility.
Nuclear Fuel Fabrication Market Segmentation
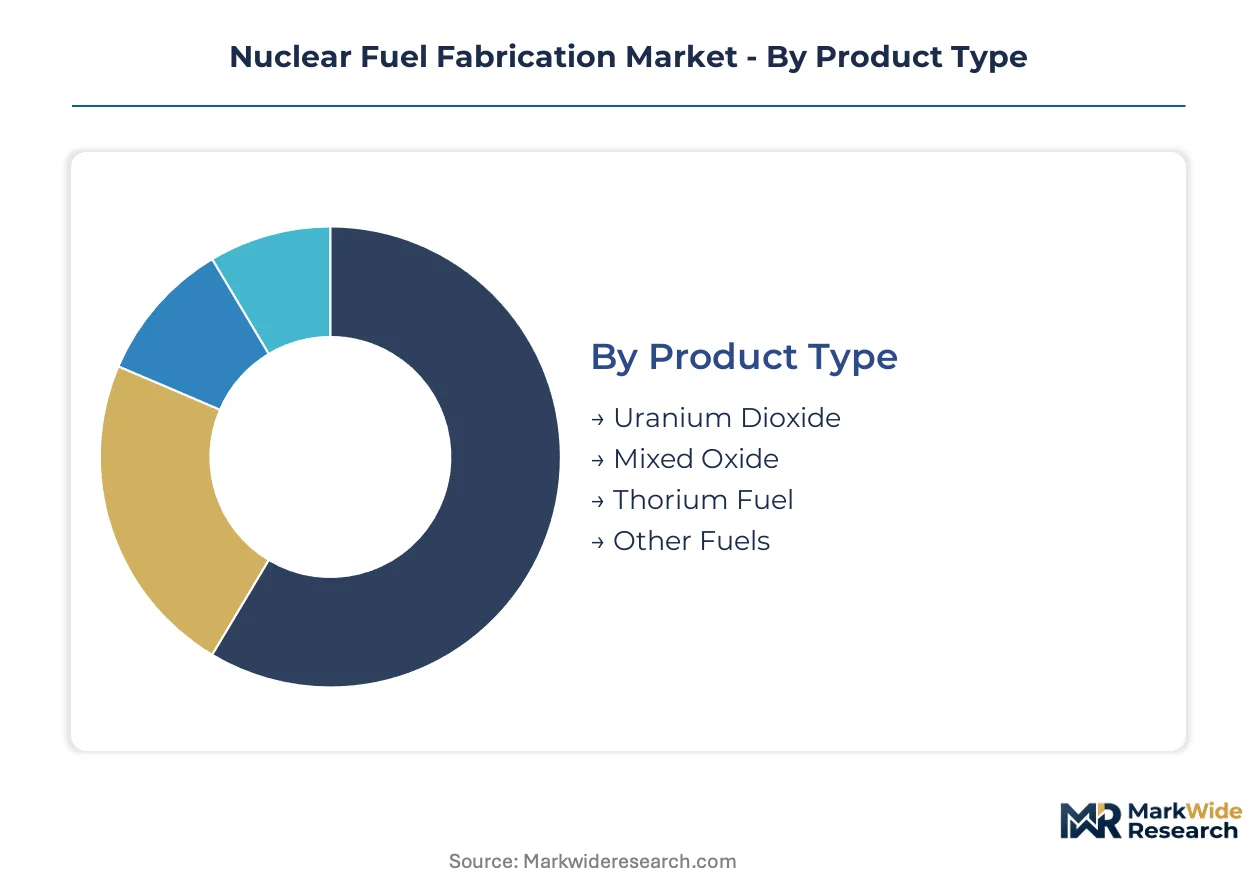
Nuclear fuel fabrication segments diverge sharply between established light water reactor supply chains and emerging advanced reactor formats. Product type and end user categories dominate revenue allocation, while technology and form factors determine capital intensity and regulatory pathway complexity.
Product Type:
Volume concentration sits with uranium dioxide, while premium margins concentrate in reprocessing-derived fuels and accident-tolerant alternatives.
- Uranium Dioxide:Ceramic pellets sintered from enriched uranium hexafluoride feedstock achieve theoretical densities above 95% for reliable in-reactor performance. Pressurized water reactors in France and the United States absorb the majority of fabrication output, driven by license extension programs that lock in replacement fuel assembly demand through mid-century.
- Mixed Oxide:Plutonium-uranium blends fabricated from La Hague reprocessing output serve closed fuel cycle mandates in France and export contracts to Japan. Framatome's Melox facility anchors European supply, though capital intensity and dual-use export controls constrain new market entrants.
- Thorium Fuel:Experimental thorium-uranium matrices remain confined to research reactor qualification programs in India and Norway.
- Other Fuels:High-assay low-enriched uranium and TRISO particle formats target small modular reactor deployments at NuScale and TerraPower.
Today's leader: Uranium Dioxide. Tomorrow's challenger: Mixed Oxide.
End User:
Customer concentration tilts toward utilities with long-term procurement horizons, while research and defense segments command price premiums for small-batch specialty production.
- Nuclear Power Plants:Commercial utilities operating pressurized and boiling water reactors purchase fuel assemblies on multi-cycle contracts bundling fabrication with core design services. American and French operators lead procurement consolidation, reducing supplier switching flexibility.
- Research Institutions:Universities and national laboratories require exotic fuel geometries for materials testing and isotope production. BWXT anchors North American supply with exacting metallurgical standards for naval-derived fabrication expertise.
- Defense:Naval reactor programs demand zirconium alloy tubes with ultra-low hydrogen content and precise dimensional tolerances.
- Others:Medical isotope producers and space power system developers represent fragmented demand with specialized specification requirements.
Commercial utilities capture volume leadership. Defense and research segments define margin benchmarks.
Technology:
Process selection determines regulatory pathway duration and feedstock security exposure.
- Direct Fabrication:Conversion of enriched uranium hexafluoride into ceramic pellets dominates volume through established supply chains serving light water reactors. Sintering furnaces operating above 1700°C expose fabricators to volatile natural gas and electricity pricing.
- Reprocessing:Plutonium recovery from spent fuel generates MOX feedstock with concentrated value due to capital intensity and IAEA safeguards compliance. France's La Hague complex feeds domestic and export fabrication demand.
- Advanced Separation Processes:Electrochemical and fluoride volatility methods remain in pilot-scale demonstration for future closed fuel cycle deployment.
- Elemental Conversion:Reduction of uranium hexafluoride to metal or carbide forms serves research reactor and specialty fuel requirements.
Direct fabrication holds current volume dominance. Reprocessing offers the steepest expansion trajectory under closed fuel cycle policy alignment.
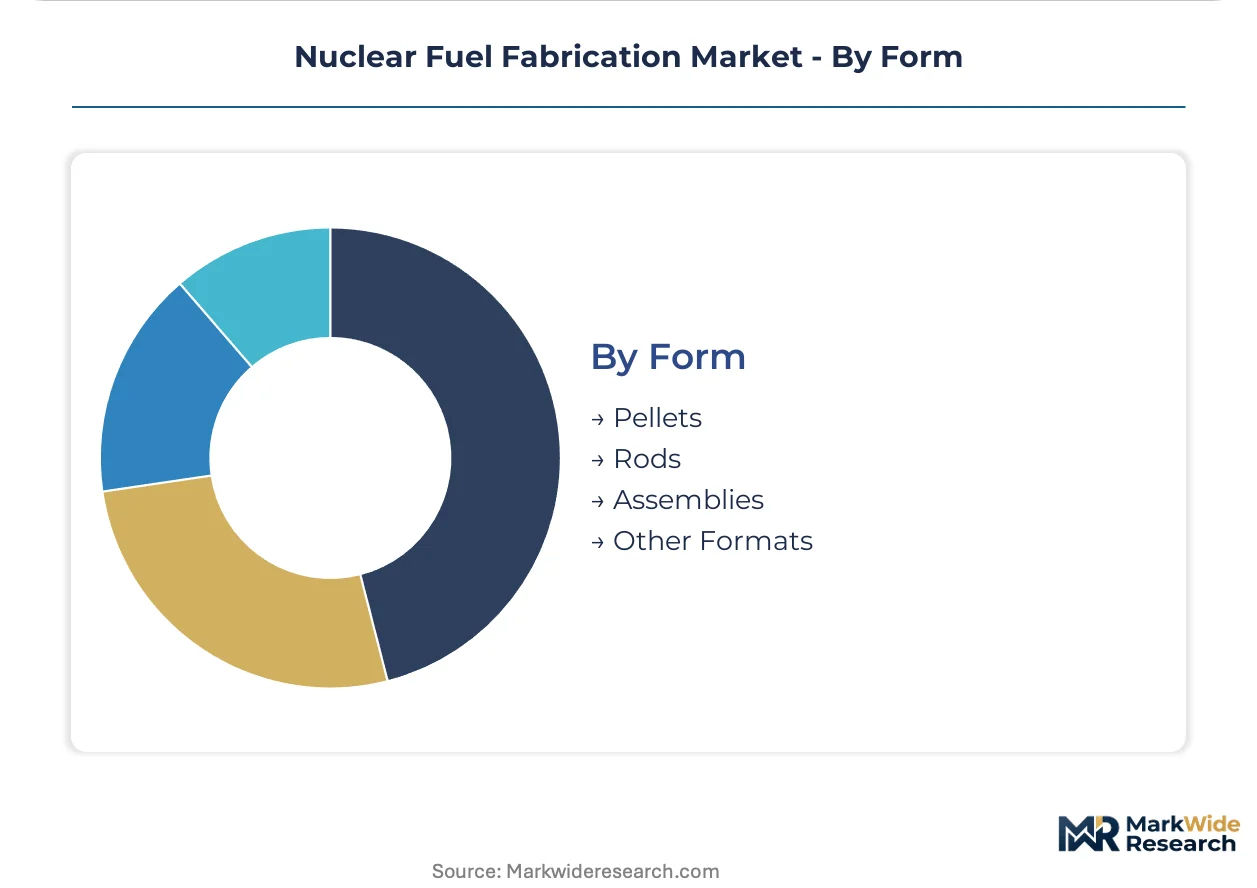
Form:
Physical configuration dictates handling infrastructure and transportation regulatory complexity.
- Pellets:Cylindrical uranium dioxide compacts stack within zirconium cladding tubes. Sintering to 95% theoretical density requires precise temperature control and atmosphere management.
- Rods:Pellet-loaded cladding tubes seal with end plugs through tungsten inert gas welding. Quality assurance under 10 CFR Part 50 governs dimensional and leak-tightness verification.
- Assemblies:Bundled rods arranged in fuel element grids install into reactor cores. Westinghouse and Framatome compete on integrated assembly design and reload optimization services.
- Other Formats:TRISO particles, plate fuels, and sphere-pac configurations serve high-temperature gas-cooled and molten salt reactor designs.
Assemblies generate the highest revenue per unit. Pellet and rod fabrication concentrates supplier margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and France operate divergent fuel security frameworks. American utilities rely on direct fabrication supply chains, while French operators exploit closed fuel cycle infrastructure. Canada and Japan pursue distinct pathways through specialty fuel exports and advanced reactor qualification.
United States
License extensions under 10 CFR Part 54 drive replacement fuel assembly demand through mid-century. The Department of Energy's Advanced Fuels Campaign accelerates accident-tolerant fuel qualification timelines. Fabrication clusters concentrate in South Carolina and Pennsylvania, where Westinghouse and BWXT operate legacy production facilities serving commercial and naval reactor programs.
France
Closed fuel cycle mandates sustain plutonium recovery at the La Hague reprocessing complex for MOX fabrication. The Autorité de Sûreté Nucléaire collaborates with EMA on cross-border transport standards. Framatome's Melox facility in Gard anchors European MOX supply, feeding domestic reactors and export contracts to Japan and Belgium.
Japan
Post-Fukushima safety upgrades prioritize accident-tolerant fuel qualification for existing pressurized water reactor fleets. METI oversees strategic uranium stockpiling and domestic fabrication capacity preservation. Mitsubishi Heavy Industries maintains fabrication expertise in Kobe, though commercial restart schedules remain tied to regulatory consensus at the Nuclear Regulation Authority.
Canada
CANDU heavy water reactor operators demand natural uranium fuel bundles with distinct pellet geometries from light water designs. Canadian Nuclear Safety Commission licensing governs fabrication at BWXT's Toronto-area facility. Ontario's Bruce Power and Ontario Power Generation anchor procurement volumes, with export opportunities to Romania and Argentina.
South Korea
KHNP's reactor fleet drives localization mandates for fuel assembly production. KEPCO Nuclear Fuel operates fabrication capacity under Korea Institute of Nuclear Safety oversight. Busan-Ulsan industrial corridors host zirconium alloy tube drawing capabilities, though enrichment dependence leaves feedstock exposure to Western supply.
Nuclear Fuel Fabrication Market Competitive Environment
Top-tier vendors anchor integrated fuel-service portfolios, while mid-scale specialists concentrate on naval or research reactor niches. The market exhibits tiered concentration with three to four dominant commercial fabricators and a fragmented base of specialty suppliers. Strategic archetypes divide between full-cycle utilities, naval contractors, and advanced reactor fuel pioneers. Competitive moves center on multi-cycle contract bundling and accident-tolerant fuel qualification racing.
Within the integrated commercial tier, Westinghouse Electric Company and Framatome occupy positions defined by geographic licensing heritage and closed fuel cycle capabilities. BWXT exemplifies the naval-specialist archetype through exacting metallurgical standards derived from military reactor programs. TRISO-X represents emerging advanced reactor fuel formats targeting small modular and high-temperature gas-cooled designs.
| Leading Market Players |
|---|
| Westinghouse Electric Company |
| General Electric |
| Framatome |
| GE Vernova |
| BWXT |
| TRISO-X |
| Standard Nuclear |
| Mitsubishi Heavy Industries |
| Toshiba Energy System & Solutions Corporation |
| Others |
Value Chain & Pricing Dynamics
Chromium-coated cladding qualification is compressing fabrication economics while concentrating supplier leverage among vendors with pre-positioned coating capacity. The technology transition demands capital redeployment from incremental pellet density improvements toward coated tube metallurgy, reshaping cost structures and procurement negotiation dynamics across North American and European utilities.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for zirconium alloy tubes. Contract-based long-term offtake agreements dominate commercial utility procurement, with price differentiation driven by burnup performance guarantees and 10 CFR Part 50 certification tier. Cost compression in standard uranium dioxide pellets is intensifying because of sintering energy exposure, while defense and research segments show least price sensitivity due to exacting metallurgical specifications.
Supply Chain Analysis
Domestic-content mandates in France and the United States are reshaping sourcing patterns for enriched uranium hexafluoride. Feedstock concentration centers on the United States, France, and Russia, with fabrication drawing from zirconium sponge, ceramic powder, and specialized welding gases. Single-source vulnerability runs through conversion facilities, while distribution runs through licensed cask transport networks governed by IAEA safeguards and bilateral agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through accident-tolerant fuel premium tiers, justified by chromium-coated cladding qualification timelines that compress competitive windows and reward first-mover fabrication capacity.
For Market Incumbents: To counter emerging advanced reactor fuel specialists, anchor multi-cycle contracts bundling fabrication with core design services and deepen backward integration into zirconium alloy tube drawing. Pre-position coating line capacity ahead of 10 CFR Part 50 rulemakings codifying new safety criteria. For New Entrants and Emerging Players: Launch via research reactor and naval specialty fuel segments where exacting standards create barrier-protected niches. Target medical isotope producers and space power developers with TRISO particle formats, leveraging digital twin integration as a go-to-market differentiator on predictive reliability metrics. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fabrication specialists with captive zirconium metallurgy expertise. Long-term viability favors vendors with demonstrated accident-tolerant fuel delivery schedules and closed fuel cycle licensing heritage. Watch Department of Energy timeline waivers as the inflection signal for accelerated revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Accident-Tolerant Fuel Qualification | Chromium-coated cladding prototypes in lead test assemblies reshape competitive positioning at Westinghouse and Framatome. |
| Multi-Cycle Contract Bundling | Integrated fabrication and reload analysis services lock decade-long utility relationships and reduce supplier switching. |
| Digital Twin Integration | In-reactor performance modeling alongside 10 CFR Part 50 quality assurance differentiates vendors on predictive metrics. |
| Closed Fuel Cycle Expansion | La Hague reprocessing output feeds MOX fabrication growth serving French domestic and Japanese export demand. |
| Small Modular Reactor Fuel Development | Higher-assay low-enriched uranium designs for NuScale and TerraPower require specialized pellet geometries capturing first-mover advantage. |
Study Parameters
Direct dialogue with fuel fabrication executives, utility procurement officers, nuclear regulatory specialists, and zirconium metallurgy engineers grounded qualitative findings. Secondary validation drew from NRC licensing databases, IAEA safeguards documentation, Department of Energy program announcements, and utility 10-K disclosures. Bottom-up and top-down triangulation cross-checked facility capacity data against reactor operator demand forecasts.
Bottom-up modeling aggregated fabrication line throughput by product type and technology, while top-down analysis calibrated against national nuclear generation capacity and fuel cycle policy trajectories. Segmentation dimensions spanned product type, end user, technology, and form factor across the projection horizon. CAGRs derived from regression analysis of historical license extension patterns and announced advanced reactor deployment schedules, incorporating enrichment supply concentration and sintering energy cost volatility as key inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruption to uranium hexafluoride conversion or accelerated small modular reactor deployment. Forecasts reflect documented assumptions regarding regulatory approval timelines, feedstock security frameworks, and technology qualification success rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market
Nuclear Energy
Industrial Radioactive Source Market
Nuclear Energy
Thorium Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Steam Generator Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Decommissioning Services Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market