
 Europe Water Meter Market | 2026-2036
Europe Water Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Water Meter Market Foresight
Software-defined analytics and subscription-based data services is decoupling meter hardware from recurring revenue streams across European utilities. Diehl Stiftung & Co. KG leverages its German manufacturing footprint to anchor supply for AMI deployments in Central Europe. Kamstrup differentiates through ultrasonic technology leadership and high R&D intensity in Denmark-based production. Sensus (Xylem) extends its service portfolio beyond hardware into cloud-based water-loss management platforms.
Europe water meters are precision instruments measuring volumetric flow through potable water distribution networks, typically constructed from brass, polymer, or stainless steel with accuracy classes ranging from R80 to R400 depending on technology. Their primary commercial purpose is enabling accurate billing, leak detection, and network optimization for utility operators. Smart meters represent the fastest-expanding product category as utilities prioritize real-time consumption visibility and remote disconnect capability. AMI technology captures the dominant share of new investment as European operators phase out walk-by AMR systems. Municipal end users command the largest volume pool, though commercial and industrial segments offer higher per-unit margins due to larger pipe diameters and complex data requirements.
The EU Drinking Water Directive mandates stricter monitoring of water quality and quantity, compelling utilities to upgrade legacy analog meters with data-logging capabilities. ECHA REACH compliance shapes material selection for wetted components, restricting certain brass alloys and driving polymer adoption. France's ANSM and Germany's KBA-adjacent metrology frameworks enforce MID certification requirements that govern market access. Stakeholders must monitor how the EU AI Act and Cybersecurity Act will impose algorithmic transparency and network-security standards on IoT-enabled metering infrastructure.
Market Dynamics
AMI infrastructure rollouts across French and German municipal utilities are compressing replacement cycles from fifteen years to eight, creating a sustained equipment refresh window that favors vendors with integrated software stacks over pure hardware suppliers.
Growth Catalysts
- EU Drinking Water Directive revisions:Mandatory data-logging requirements for quality and quantity monitoring compel utilities to retire analog meters. MID-certified smart meters satisfy these obligations while enabling leak detection algorithms.
- F-Gas Regulation phase-down:Restrictions on hydrofluorocarbon use in industrial cooling systems accelerate ultrasonic meter adoption for chilled water billing in commercial buildings, displacing mechanical alternatives.
- Utility consolidation in Central Europe:Aggregated purchasing power of merged German municipal operators drives standardized AMI procurement at scale, reducing per-unit deployment costs.
Market Restraints
- Brass alloy input volatility:ECHA REACH restrictions on lead-containing brass grades force rapid material transitions to polymer or stainless steel wetted components, inflating unit manufacturing costs.
- Danish production concentration:Ultrasonic transducer supply chains cluster around Copenhagen-Odense corridor, exposing buyers to single-source risk for critical sensing elements.
- Mechanical meter residual life:Aging but functional installed base in Eastern European secondary cities delays replacement schedules, stretching payback periods for smart infrastructure investments.
Strategic Opportunities
- Polish municipal underpenetration:AMI deployment rates in Warsaw and Krakow lag Berlin and Paris by seven years, creating first-mover advantage for vendors establishing local service partnerships.
- EU AI Act compliance services:Algorithmic transparency mandates for consumption forecasting models open recurring revenue streams in software auditing and model documentation.
- NB-IoT and LoRa convergence:Hybrid communication architectures blending cellular low-power wide-area with unlicensed spectrum reduce infrastructure capital for rural utility deployments.
Industry Challenges
- Metrology engineer scarcity:MID certification expertise concentrates in Stuttgart and Milan technical institutes, constraining validation throughput for new product introductions.
- Legacy billing system integration:Proprietary protocols from 1990s-era CIS platforms resist API standardization, forcing costly middleware development for AMI data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Water Meter Market |
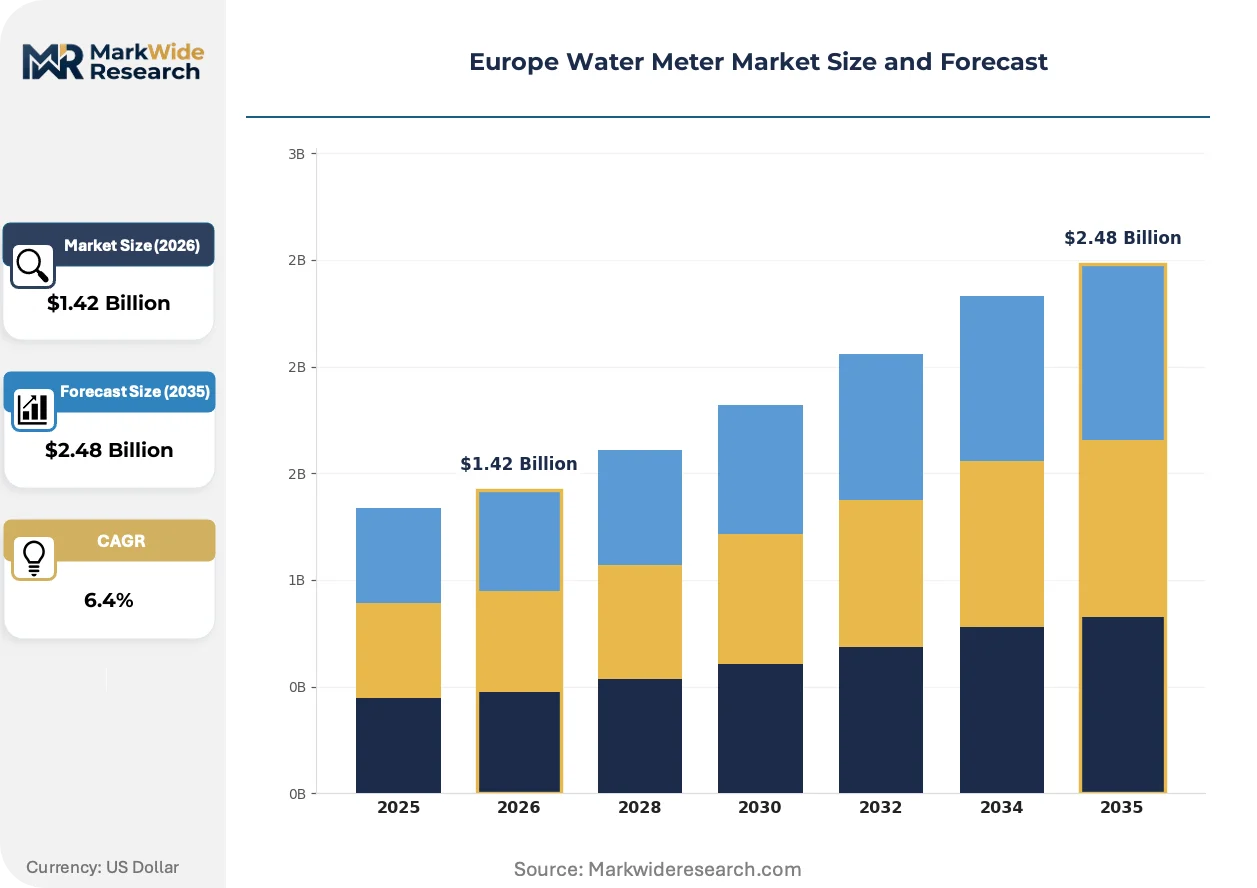
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electromagnetic, Ultrasonic, Smart Technology: AMR, AMI, IoT-enabled, Analog End User: Residential, Commercial, Industrial, Municipal Installation Type: Indoor, Outdoor, Retrofit, New Construction |
| Companies Covered | Sensus (Xylem), Birdz (Veolia), Diehl Stiftung & Co. KG, Landis+Gyr, Apator, Itron, Badger Meter, Maddalena, Kamstrup, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Water Meter Market Shifts & Advancements
Ultrasonic sensing architectures are displacing mechanical measurement cores across European utilities, compressing maintenance intervals while enabling flow-profile diagnostics that mechanical impellers cannot capture.
Ultrasonic transit-time technology measures volumetric flow through ceramic or polymer flow tubes without moving parts, eliminating wear-induced drift. German municipal operators in Bavaria and Baden-Württemberg are adopting these meters at replacement rates exceeding mechanical alternatives by three to one. Diehl and Kamstrup are integrating edge-computing firmware directly into meter housings, enabling leak signature detection at the measurement point rather than in centralized analytics platforms.
The EU Cybersecurity Act imposes Common Criteria certification on network-connected metering infrastructure, mandating hardware security modules and encrypted firmware update channels. Industrial consequence: vendors must redesign radio modules and commissioning tools to satisfy ETSI standards, extending product development timelines. French utilities under ANSM oversight are responding fastest, requiring CC EAL4+ certification as a procurement gate before contract award.
Subscription-based data analytics are unbundling hardware purchases from recurring service revenue, reversing traditional capital-sale economics. European water utilities in the Netherlands and Denmark now procure consumption insights as operational expenditures rather than owning meter assets outright. This shift is most visible in commercial and industrial segments where complex multi-site billing demands real-time dashboard access and automated anomaly alerting.
Europe Water Meter Market Segmentation
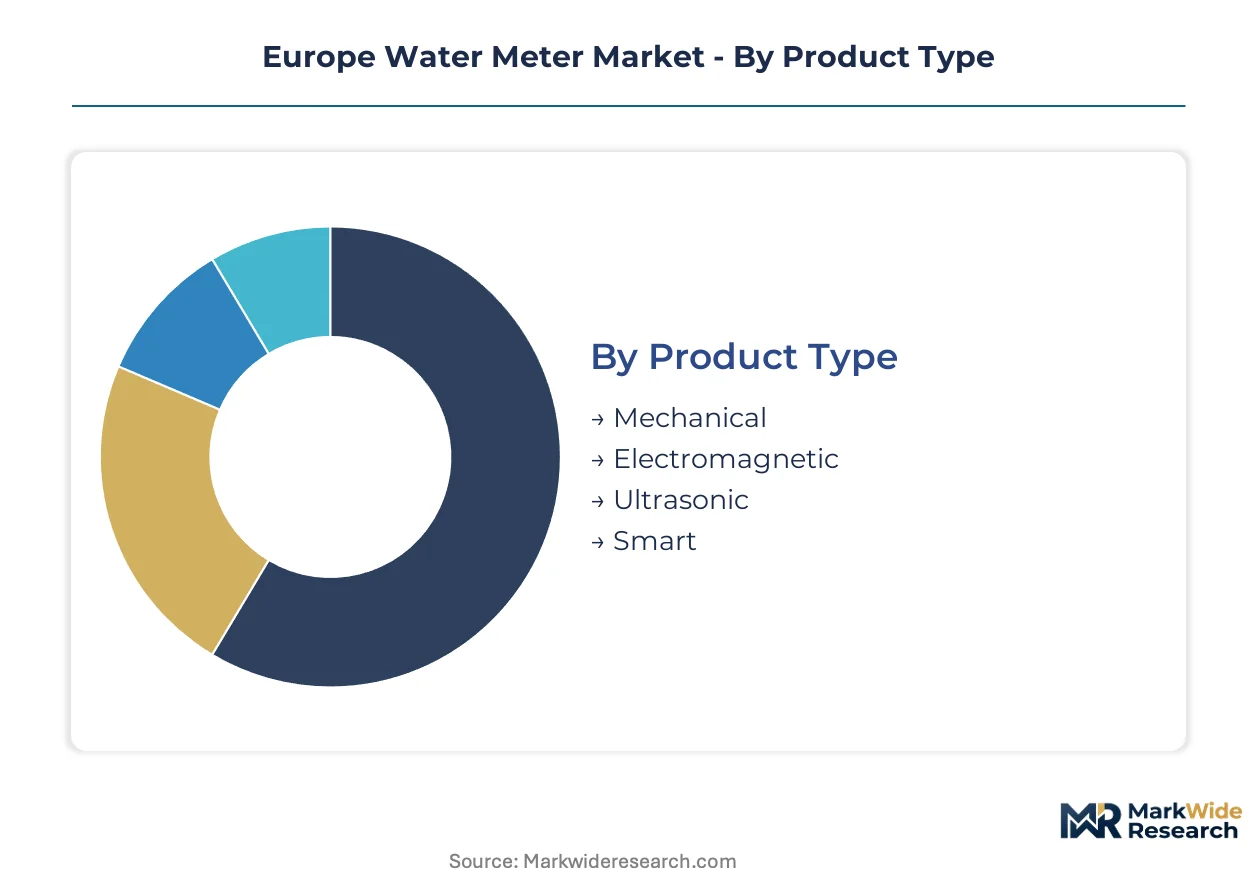
Technology choices in European water metering reflect divergent regulatory pressures, infrastructure ages, and utility digital maturity across national markets. Segment boundaries are blurring as ultrasonic and electromagnetic technologies converge with AMI connectivity, forcing vendors to position across multiple axes simultaneously.
Product Type:
Buyers in this category separate by replacement urgency and total cost of ownership horizons, with German and French utilities prioritizing accuracy longevity over upfront capital outlays.
- Mechanical:Traditional impeller-driven volumetric measurement using brass or polymer wetted components. Demand concentrates in Eastern European secondary cities where municipal budgets delay smart infrastructure cycles and MID recertification extends serviceable life.
- Ultrasonic:Transit-time sensing through ceramic flow tubes eliminates moving parts and enables flow-profile diagnostics. Bavarian and Baden-Württemberg utilities are adopting these at replacement rates exceeding mechanical alternatives, driven by F-Gas Regulation compliance for chilled water billing.
- Electromagnetic:Faraday's law measurement for high-conductivity fluids in large-diameter applications. Industrial end-users in the Netherlands favor these for process water monitoring where mechanical wear is unacceptable.
- Smart:Integrated metrology with embedded communications and edge-computing capability. Danish and Dutch utilities procure these as service subscriptions rather than owned assets, unbundling hardware from data analytics revenue.
Volume sits with Mechanical; growth tilts toward Smart.
Technology:
Deployment economics and cybersecurity posture distinguish procurement patterns, with larger utilities absorbing AMI capital burdens while smaller operators cling to transitional AMR architectures.
- AMR:Drive-by or walk-by radio frequency collection with one-way data transmission. Polish and Romanian utilities retain these for rural coverage where AMI infrastructure density remains uneconomical.
- AMI:Two-way fixed-network communications enabling remote disconnect and real-time leak alerts. Aggregated German municipal operators are driving standardized procurement at scale, compressing replacement cycles from fifteen years to eight.
- IoT-enabled:Cellular LPWAN or unlicensed spectrum connectivity with cloud-native data architectures. French utilities under ANSM oversight require CC EAL4+ certification as a procurement gate, accelerating security-hardened designs.
- Analog:Non-communicating mechanical registers requiring manual reading. Residual demand persists in Italian and Spanish vacation-home markets where connectivity infrastructure is sparse and billing disputes are rare.
AMI commands new investment volumes; IoT-enabled configurations are climbing the fastest as NB-IoT and LoRa hybrid architectures reduce rural deployment capital.
End User:
Data complexity and meter density per account determine margin structures, with multi-site commercial operators demanding API-integrated analytics that residential billing platforms cannot justify.
- Municipal:City-scale distribution network operators managing leak detection and non-revenue water reduction. French and German utilities command the largest volume pools, though per-unit margins compress at procurement scale.
- Commercial:Multi-site retail, hospitality, and office operators with complex sub-metering requirements. These buyers in Belgium and the Netherlands pay premiums for real-time dashboard access and automated anomaly alerting.
- Industrial:Process water and cooling system operators subject to F-Gas Regulation phase-down constraints. German chemical and automotive plants are displacing mechanical meters with ultrasonic alternatives for chilled water billing accuracy.
- Residential:Single-family and multi-unit dwelling billing endpoints. Italian and Eastern European markets retain mechanical dominance where consumer price sensitivity resists smart meter surcharges.
Municipal captures volume concentration; Commercial delivers margin expansion.
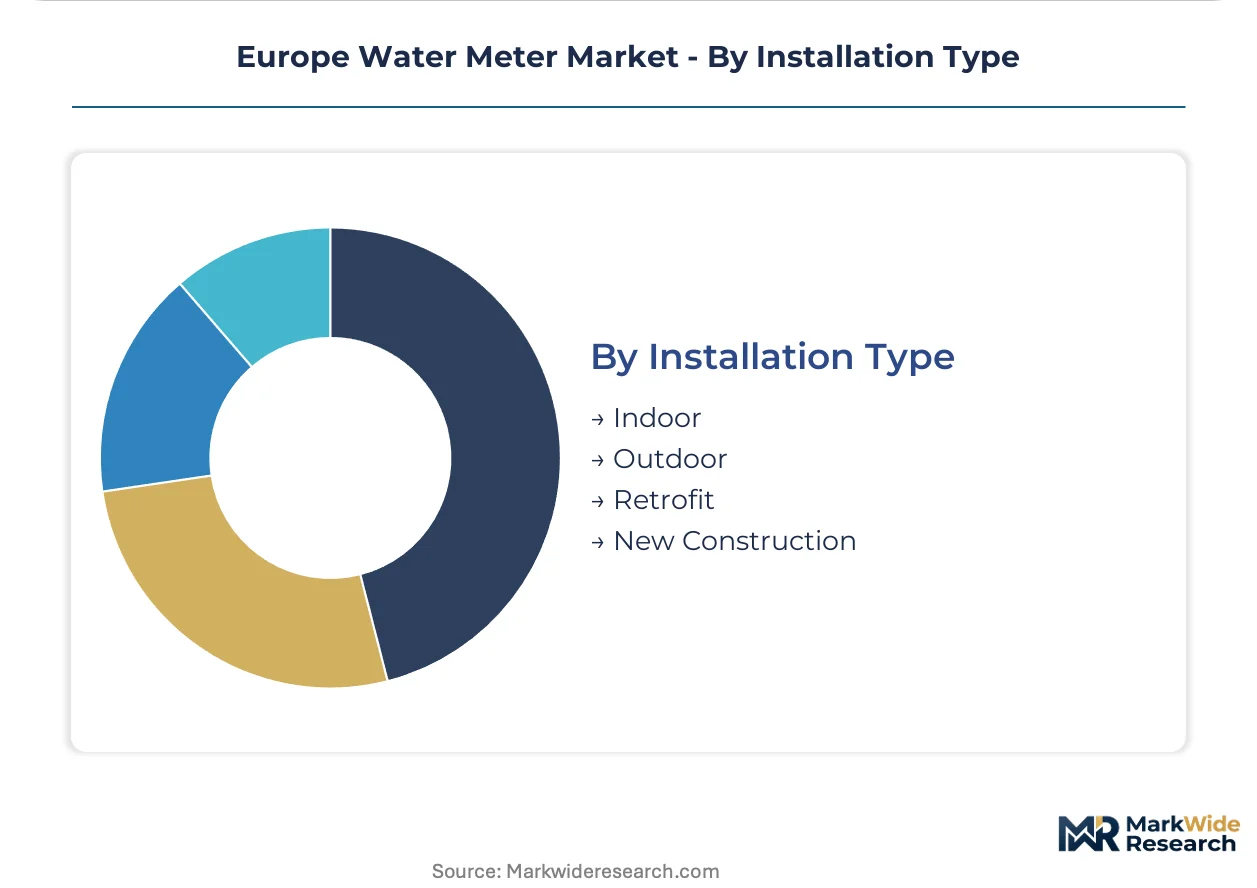
Installation Type:
Physical site constraints and labor cost structures shape procurement, with retrofit deployments dominating aging European urban cores while new construction offers integrated design flexibility.
- Retrofit:Replacement of existing meters within constrained mechanical footprints and legacy piping. Paris and Berlin utility districts generate sustained demand as AMI rollouts compress replacement cycles.
- New Construction:Greenfield deployment with coordinated civil works and smart-ready infrastructure. Dutch residential developments near Amsterdam and Rotterdam specify IoT-enabled meters from project inception.
- Indoor:Protected installation within building envelopes, typical for residential and light commercial endpoints. German KBA-adjacent metrology frameworks govern accuracy certification for these applications.
- Outdoor:Pit or surface-mounted exposure to temperature cycling and flooding risk. British utilities specify polymer housings and IP68 ratings for these demanding environments.
Retrofit dominates current volumes; New Construction offers the steepest expansion trajectory as EU building codes mandate smart-readiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr corridor anchors European water meter procurement, with German municipal utilities driving standardized AMI deployments at scale. French and British operators follow distinct regulatory timelines, while Polish and Italian markets present divergent modernization trajectories.
Germany
Bavarian and Baden-Württemberg utilities compress replacement cycles from fifteen years to eight, prioritizing ultrasonic accuracy for chilled water billing. The KBA-adjacent metrology framework enforces MID certification requirements that govern market access for all wetted components. Stuttgart technical institutes concentrate metrology engineering expertise, constraining validation throughput for new product introductions.
France
ANSM oversight mandates CC EAL4+ certification as a procurement gate before contract award, accelerating security-hardened IoT designs. The EU Drinking Water Directive revisions compel Paris and Lyon municipal operators to retire analog meters with data-logging alternatives. Île-de-France utility districts generate sustained retrofit demand as AMI rollouts expand beyond the capital region.
United Kingdom
British utilities specify polymer housings and IP68 ratings for outdoor pit-mounted installations exposed to temperature cycling and flooding risk. Ofwat regulatory pressure on non-revenue water reduction drives smart meter adoption in Thames Water and Anglian Water territories. London and Southeast England concentrate deployment volumes, though per-unit margins compress at procurement scale.
Poland
Warsaw and Krakow lag Berlin and Paris by seven years in AMI deployment rates, creating first-mover advantage for vendors establishing local service partnerships. Polish municipal budgets retain AMR architectures for rural coverage where fixed-network infrastructure density remains uneconomical. The aggregated purchasing power of merged municipal operators has not yet materialized, delaying standardized procurement.
Italy
Italian vacation-home markets in Tuscany and Lombardy retain analog mechanical registers where connectivity infrastructure is sparse and billing disputes are rare. Hera Group and Acea SpA drive smart meter pilots in Bologna and Rome, though consumer price sensitivity resists surcharges in residential segments. The residual life of aging installed base in secondary cities stretches payback periods for infrastructure investments.
Europe Water Meter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European water meter landscape. The vendor base separates into integrated hardware-software stacks, pure component specialists, and utility-affiliated service platforms. Strategic archetypes include German manufacturing anchors, Danish ultrasonic technology leaders, and French water-utility-captive operators. Competitive moves center on AMI platform consolidation and cybersecurity certification pre-emption.
Among German-based fabricators, Diehl Stiftung & Co. KG occupies a position representing integrated manufacturing depth, while Kamstrup exemplifies ultrasonic technology specialization anchored in Danish production. Sensus, operating under Xylem ownership, represents the utility-captive service platform archetype extending beyond hardware into recurring data revenue streams.
| Leading Market Players |
|---|
| Sensus (Xylem) |
| Birdz (Veolia) |
| Diehl Stiftung & Co. KG |
| Landis+Gyr |
| Apator |
| Itron |
| Badger Meter |
| Maddalena |
| Kamstrup |
| Others |
Supply & Pricing Matrix
Family-owned German mid-caps anchor manufacturing capacity in Baden-Württemberg and Bavaria, translating regional production density into pricing discipline through captive metrology expertise and MID certification control. Their ownership structure resists short-term margin compression, sustaining premium positioning for ultrasonic and AMI-enabled meters while forcing price competition into mechanical tiers where Eastern European assemblers operate.
Pricing Analysis
Value-based pricing anchored to non-revenue water reduction outcomes dominates municipal procurement in France and Germany, with utilities paying premiums for meters demonstrating leak-detection accuracy rather than hardware specifications alone. Price differentiation separates CC EAL4+ certified IoT configurations from standard AMI tiers, with cybersecurity compliance adding substantial cost to French deployments under ANSM oversight. Pricing pressure stems from polymer substitution for REACH-restricted brass alloys, inflating unit manufacturing costs across all accuracy classes. Residential segments in Italy and Poland exhibit highest price sensitivity, resisting smart meter surcharges, while Dutch commercial operators accept subscription-based data services with minimal capital outlay.
Supply Chain Analysis
Ultrasonic transducer supply rests on Danish specialty producers concentrated around the Copenhagen-Odense corridor, creating single-source dependency for critical sensing elements. Ceramic flow tubes and polymer wetted components draw from German and Austrian material processors, while semiconductor content for radio modules sources from Taiwan and South Korea. Supply chain risk centers on Danish production concentration exposing buyers to geographic disruption without qualified secondary sources. Distribution runs through utility-affiliated service platforms and direct municipal procurement channels, with consolidated German operators driving standardized AMI procurement at scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with integrated software-hardware stacks, as EU Cybersecurity Act compliance costs and MID certification bottlenecks force pure hardware specialists toward acquisition or exit.
For Market Incumbents: Lock in AMI platform consolidation through backward integration into ultrasonic transducer supply, reducing exposure to Danish single-source risk. Prioritize CC EAL4+ certification pre-emption for French ANSM procurement gates, creating exclusionary barriers against uncertified competitors. Defend against emerging utility-captive service platforms by unbundling hardware from subscription analytics, matching Sensus-style recurring revenue models. For New Entrants and Emerging Players: Launch via local service partnerships in Polish municipal markets where Warsaw and Krakow lag Berlin and Paris by seven years in AMI deployment. Target AMR-to-AMI transition opportunities in Romanian rural utilities where fixed-network infrastructure density remains uneconomical. Lead with NB-IoT and LoRa hybrid communication architectures that reduce rural deployment capital versus cellular-only alternatives. For Investors and Strategic Acquirers: French utilities requiring CC EAL4+ certification as a procurement gate before contract award is the leading indicator that cybersecurity-hardened vendors will capture disproportionate share in adjacent EU markets. The five-to-ten year viability window favors asset-light designers with cloud-native data architectures over capital-heavy mechanical producers. Acquisition targets should display MID certification expertise and established ANSM or KBA regulatory relationships. Watch for Polish municipal consolidation triggering standardized procurement as the inflection signal for Central European market entry.| Strategic Initiative | Industry Significance |
|---|---|
| AMI Platform Consolidation | Aggregated German municipal purchasing power compresses replacement cycles from fifteen years to eight. |
| Ultrasonic Technology Migration | F-Gas Regulation compliance accelerates displacement of mechanical meters in chilled water billing applications. |
| Cybersecurity Certification Pre-emption | ANSM-mandated CC EAL4+ certification gates French procurement, excluding unprepared vendors. |
| Subscription-Based Data Services | Dutch and Danish utilities now procure consumption insights as operational expenditures rather than capital assets. |
| Local Service Partnership Establishment | Seven-year deployment lag in Polish cities creates first-mover advantage for vendors with Warsaw presence. |
Research Methodology
Independent corroboration across utility planning officers, AMI procurement managers, and metrology engineering directors underwrites the qualitative findings on replacement cycle compression and certification bottlenecks. Secondary validation drew from EU Drinking Water Directive implementation reports, ECHA REACH restriction updates, ANSM cybersecurity guidance documents, and German KBA metrology framework disclosures. Bottom-up meter deployment estimates triangulated against top-down utility capital expenditure disclosures.
Rate-of-change decomposition across the analysis window separates volume growth from value expansion, modeling technology substitution effects as ultrasonic and smart configurations displace mechanical alternatives. Segmentation dimensions include product type, communication technology, end-user category, and installation context. CAGRs derive from utility replacement schedules, regulatory compliance deadlines, and infrastructure investment trajectories. Forecast inputs incorporate F-Gas Regulation phase-down timelines and EU AI Act algorithmic transparency mandates affecting consumption forecasting models.
Regulatory implementation delays, raw material substitution cost volatility, and utility consolidation timing are the dominant revision risks to deployment assumptions. Forecasts reflect documented assumptions about municipal budget availability and certification throughput capacity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Europe Smart Water Meter Market
Smart Meters
Digital Water Meters Market
Smart Meters
North America Gas Meter Market
Smart Meters
North America Smart Meters Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Home Energy Monitor Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Smart Gas Metering Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Asia-Pacific Smart Meter Data Management Market
Smart Meters
United States (US) Water Meter Market
Smart Meters
Power Quality Meter Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
Global Smart Electricity Meter Market