
 North America EV Charging Stations Market | 2026-2036
North America EV Charging Stations Market Size, Share, and Industry Trends Forecast 2026-2036
North America EV Charging Stations Market Intelligence
The focus on workplace facilities and commercial establishments as key installation sites is expanding the market beyond its initial residential base. ChargePoint leverages its extensive network across various site types, from residential complexes to public lots. Tesla operates a proprietary Supercharger network that remains a significant factor for its vehicle owners. Electrify America specializes in high-power DC fast charging corridors, crucial for enabling long-distance EV travel in the United States and Canada.
North American EV charging stations are infrastructure devices that supply electric energy for recharging electric vehicles. They range from low-power Level 1 units using standard outlets to high-power DC Fast Chargers capable of delivering over 350 kW. Their primary purpose is to provide reliable and accessible refueling for a growing fleet of battery electric vehicles. While Level 2 chargers dominate residential and workplace installations, DC Fast Charger deployments represent the fastest-growing segment. The market is also seeing a connector standard consolidation, with the Tesla-developed standard gaining broad automaker support over CCS and CHAdeMO.
Regulations from the US Environmental Protection Agency (EPA) on vehicle emissions directly stimulate EV adoption and subsequent charger demand. The National Electric Vehicle Infrastructure (NEVI) program, overseen by federal agencies, sets standards for reliability and interoperability for publicly funded chargers in the US. These frameworks ensure a consistent user experience and accelerate network buildout. Stakeholder success depends on navigating the complex interplay of hardware standards, software interoperability, and grid capacity constraints.
Market Dynamics
The convergence of charging connector standardization and large-scale public funding is the central force shaping the North American market. The widespread adoption of the NACS standard simplifies hardware design, while federal programs like NEVI in the US accelerate network density and enforce reliability.
Growth Catalysts
- Favorable Regulations:Emissions standards from the US Environmental Protection Agency (EPA) and similar Canadian mandates directly compel automakers to produce more EVs, creating a foundational demand for charging infrastructure buildout.
- Commercial Site Deployment:The expansion of charging installations at workplace campuses, retail centers, and multi-unit residential buildings provides consistent, high-utilization demand beyond single-family homes and public highway corridors.
- Policy-Driven Regional Demand:States like California and provinces such as Quebec, with aggressive zero-emission vehicle (ZEV) mandates and consumer incentives, create concentrated geographic markets for all types of charging equipment.
Market Restraints
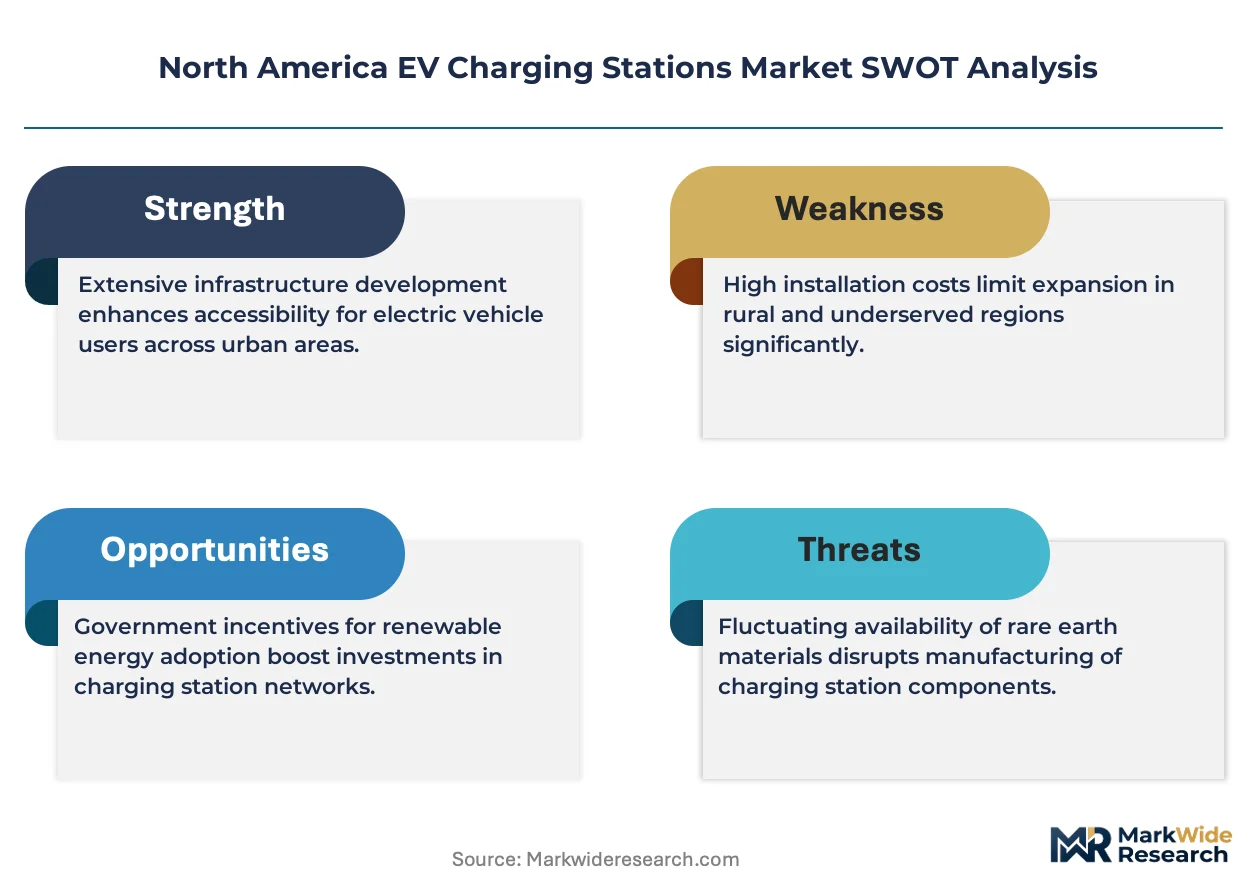
- Grid Infrastructure Limitations:The deployment of multiple high-power DC fast chargers at a single site often requires costly and time-consuming electrical service and substation upgrades, constraining the pace of network expansion.
- High Capital Expenditure:The significant upfront cost for DC fast charging hardware, coupled with complex installation and site preparation expenses, acts as a substantial barrier to entry for smaller operators and site hosts.
- Inconsistent Permitting Processes:Varying and often lengthy permitting and approval timelines across different municipalities and jurisdictions in the US and Canada create significant delays and uncertainty for network developers.
Strategic Opportunities
- Medium and Heavy-Duty Vehicle Electrification:Developing high-power charging solutions tailored for electric trucks and buses represents a significant opportunity, addressing the emerging needs of commercial fleet and logistics electrification.
- Vehicle-to-Grid Integration:The integration of bi-directional charging capabilities allows EVs to provide grid stabilization services, creating new revenue streams for charger owners and fleet operators through energy market participation.
- Rural and Underserved Corridor Expansion:Building out charging infrastructure in rural areas and along less-traveled transportation corridors in the US and Canada addresses critical gaps in network coverage, supported by government funding programs.
Industry Challenges
- Skilled Labor Scarcity:A shortage of electricians and technicians certified to install, commission, and maintain high-voltage DC fast charging systems creates bottlenecks and increases operational costs for network providers.
- Charger Reliability and Uptime:Meeting the stringent uptime and reliability requirements mandated by programs like NEVI is a major operational challenge, requiring robust remote monitoring and rapid field service response.
- Software and Payment Interoperability:Ensuring seamless communication and payment processing between different charging networks, vehicles, and payment platforms remains a persistent technical hurdle for achieving a frictionless user experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America EV Charging Stations Market |
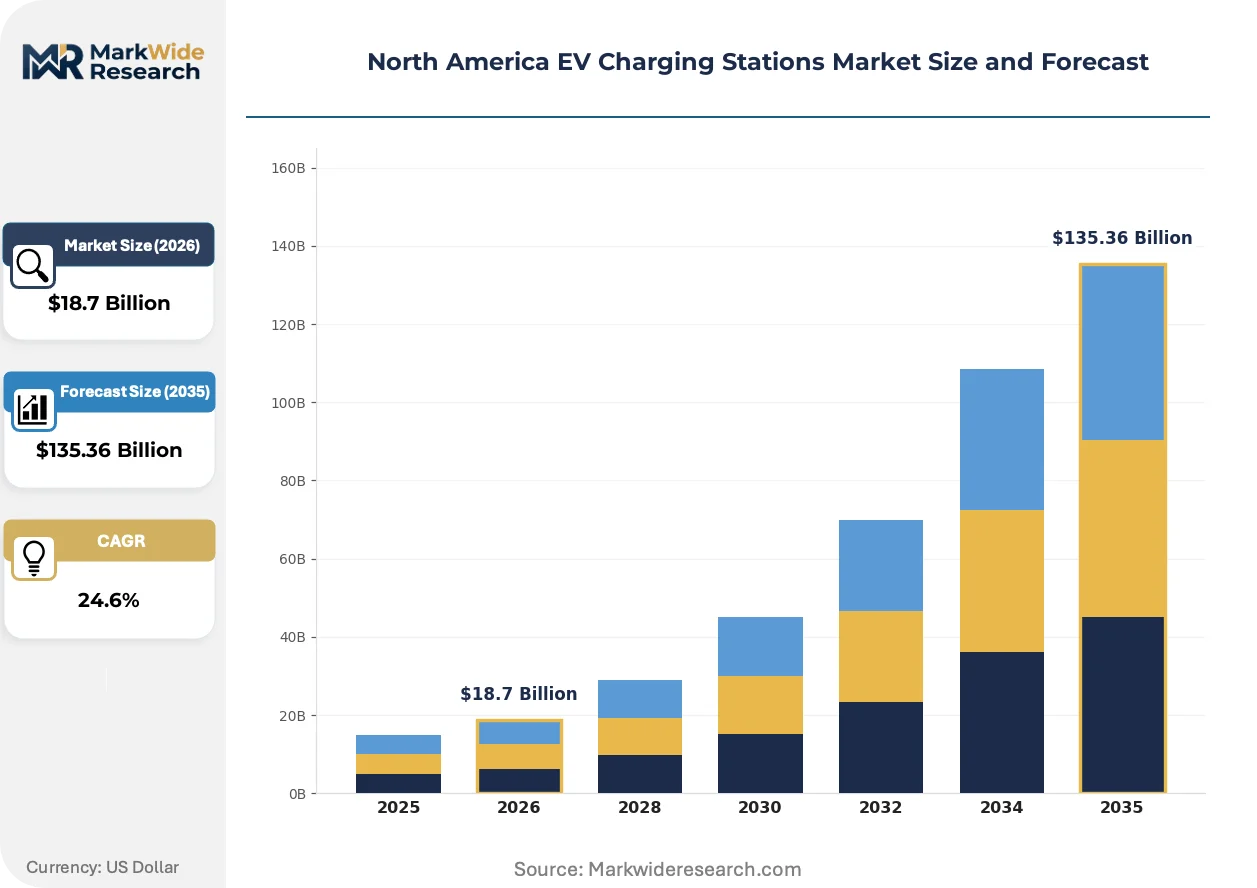
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $135.36 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charger Type: Level 1, Level 2, DC Fast Charger, Wireless Charger Installation Site: Residential Complexes, Commercial Establishments, Public Parking, Workplace Facilities Connector Type: Type 1, Type 2, CHAdeMO, CCS, Tesla Charging Network: Pay-as-you-go, Subscription-based, Free Access, Membership Access |
| Companies Covered | Electrify America, EV Connect, ChargePoint, AmpUp, Shell Recharge, Blink Charging, EVgo, FLO, Tesla, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America EV Charging Stations Market Strategic Shifts & Innovations
Software-defined functionality and grid intelligence are transforming the EV charging station from a simple power dispenser into a connected energy asset. The emphasis is shifting from hardware deployment alone to sophisticated network management, energy optimization, and integration with the broader electrical grid.
Bi-directional charging technology enables power to flow from a vehicle's battery back to a building or the electrical grid. Fleet operators and residential property owners are the primary early adopters, exploring its utility for reducing peak energy costs. This capability is converging with distributed energy resource management software, transforming EV fleets into controllable assets for grid services.
The US National Electric Vehicle Infrastructure (NEVI) program sets strict standards for federally funded charging projects. These rules mandate minimum uptime percentages, open access to multiple payment methods, and transparent pricing to ensure a reliable public network. This directly impacts charger manufacturers and network operators, who must engineer their systems for compliance to participate in the publicly funded buildout.
A shift from one-time hardware sales toward subscription-based Charging-as-a-Service (CaaS) models is gaining traction. This approach bundles the charger, installation, software, ongoing maintenance, and energy management into a recurring operational fee for site hosts. This model is most visible within commercial fleet depots and multi-unit residential properties across the United States and Canada, lowering the initial capital barrier for adoption.
North America EV Charging Stations Market Segmentation
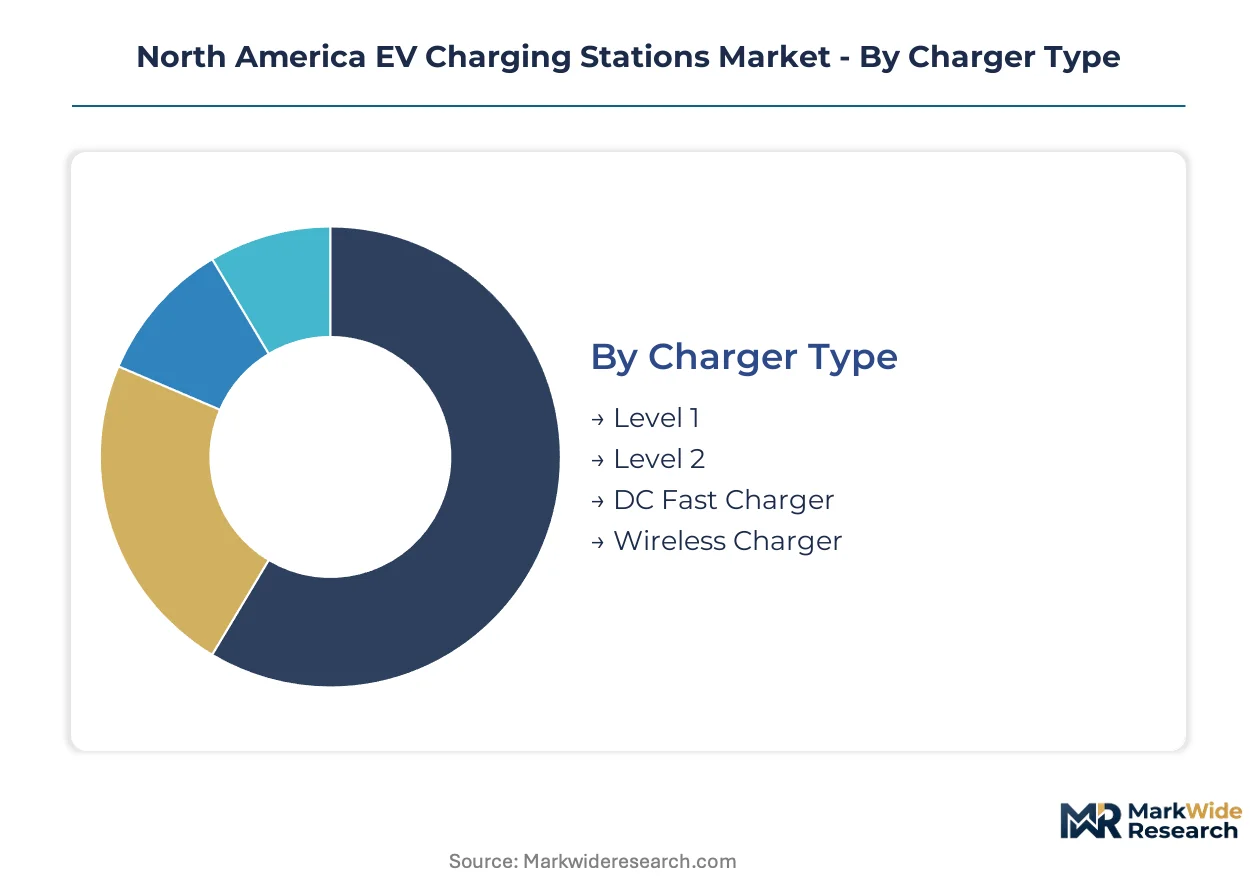
Understanding the North America EV charging stations market through detailed segmentation reveals distinct user needs and infrastructure demands. This categorization helps stakeholders identify key growth areas and tailor solutions for different charging scenarios across the United States and Canada. Analyzing these segments provides clarity on technological preferences and deployment strategies.
Charger Type:
Charging solutions across North America vary by integration depth, from basic embedded power delivery to sophisticated standalone units.
- DC Fast Charger:These high-power units deliver over 50 kW, enabling rapid recharging for long-distance travel and commercial fleet operations. Demand concentrates along major transportation corridors in the United States and Canada, driven by federal funding programs like NEVI.
- Level 2:Operating at 240V, these chargers are prevalent in residential, workplace, and public destinations, offering a balance of speed and cost-effectiveness. Their deployment expands rapidly in commercial establishments and multi-unit dwellings across urban centers.
- Level 1:Utilizing standard 120V household outlets, Level 1 chargers provide basic overnight charging primarily for residential users.
- Wireless Charger:This emerging technology allows inductive power transfer without physical connection, targeting convenience for future vehicle models.
Level 2 chargers lead volumes today; DC Fast Chargers are gaining share fastest.
Installation Site:
EV charging infrastructure applications span diverse environments, catering to both private and communal vehicle needs.
- Commercial Establishments:These sites include retail centers, hotels, and entertainment venues, attracting customers with convenient charging options. Their deployment is driven by consumer demand for amenities and local incentives in states like California.
- Workplace Facilities:Employers provide charging at office campuses and industrial sites, supporting employee EV adoption and fleet electrification. This segment sees high utilization during business hours, particularly in urban areas.
- Residential Complexes:Multi-unit dwellings and single-family homes constitute a foundational segment for Level 1 and Level 2 charger installations.
- Public Parking:Government-owned lots and municipal garages offer charging access for urban residents and visitors, often supported by federal grants.
Commercial Establishments and Workplace Facilities show the steepest expansion trajectory for new charging deployments.
Connector Type:
Connector standard supply concentration critically influences interoperability and hardware design across the North American market.
- Tesla:The North American Charging Standard (NACS), originally proprietary to Tesla, is now gaining broad support from major automakers in the United States and Canada. This standardization simplifies infrastructure development.
- CCS:The Combined Charging System (CCS) has historically been a dominant standard for non-Tesla EVs, offering both AC and DC charging capabilities. Its widespread use continues across public and private networks.
- Type 1:Also known as J1772, this connector is the standard for Level 1 and Level 2 AC charging in North America.
- Type 2:Predominantly used in Europe, this AC connector has limited presence in North America but supports higher power levels.
- CHAdeMO:This DC fast charging standard, primarily from Japanese automakers, is seeing declining adoption rates in North America.
The Tesla connector standard is rapidly consolidating market share, while CCS maintains a significant installed base.
Charging Network:
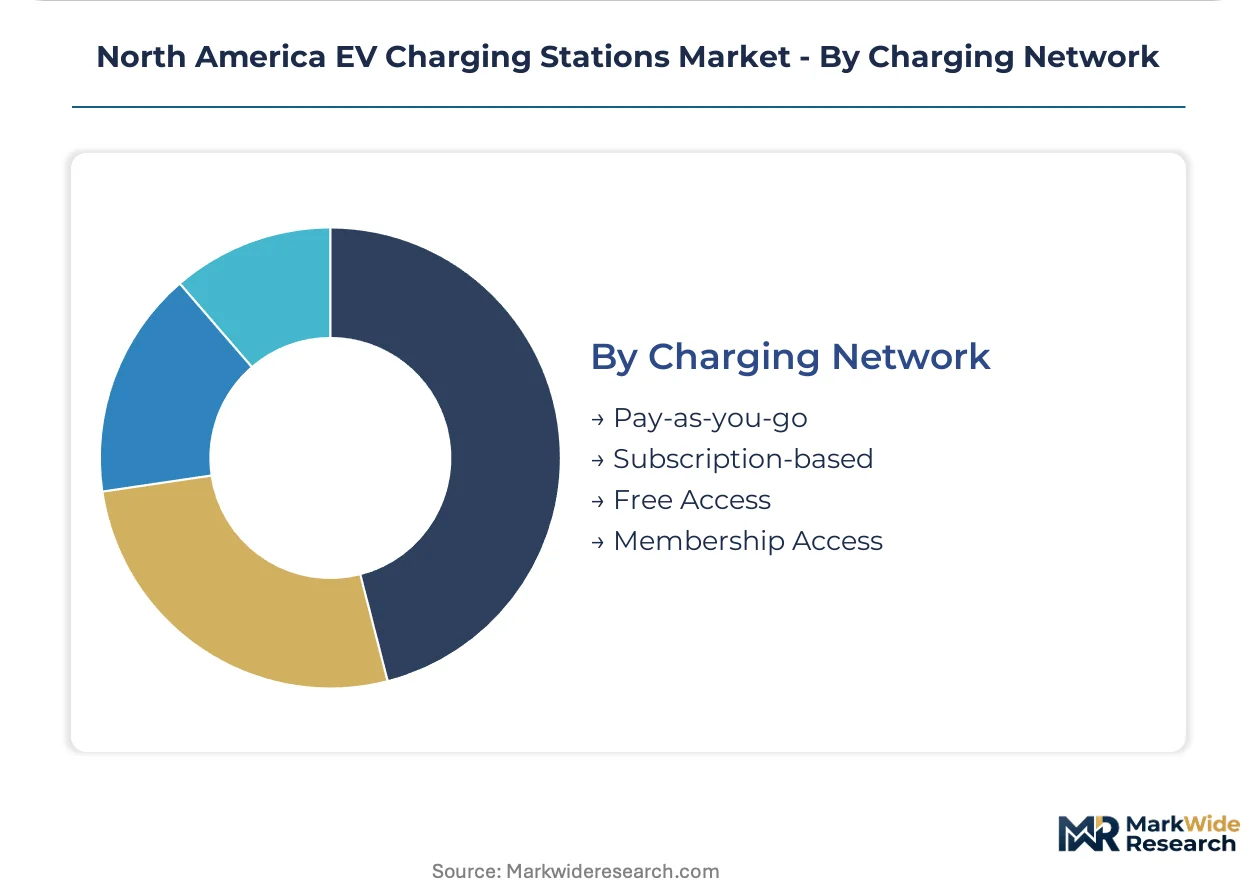
Charging network customer engagement models delineate distinct revenue streams and user experiences across North America.
- Pay-as-you-go:Users pay for charging sessions on an ad-hoc basis, typically via credit card or mobile app, offering flexibility for occasional users across public networks. This model dominates casual public charging.
- Subscription-based:This model provides users with discounted rates or unlimited charging for a recurring fee, appealing to frequent EV drivers and fleet operators. Charging-as-a-Service (CaaS) offerings often utilize this structure.
- Free Access:Some commercial establishments or workplaces offer complimentary charging as a customer amenity or employee benefit.
- Membership Access:Specific networks require a membership for charging, often providing exclusive benefits or lower per-kilowatt-hour rates.
Pay-as-you-go remains the most common model, but subscription services are steadily expanding their user base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American EV charging market sees significant investment driven by favorable policy environments. States and provinces with ambitious decarbonization goals create concentrated demand for infrastructure. This regional focus allows for targeted deployment strategies and regulatory alignment, accelerating network expansion across key areas.
United States
Demand for EV charging in the United States is fueled by increasing EV sales and federal initiatives. The National Electric Vehicle Infrastructure (NEVI) program provides substantial funding for public charger buildout, emphasizing reliability standards. Major urban centers like Los Angeles and New York City are seeing dense deployments, supporting both residential and commercial EV users.
Canada
Canadian EV adoption policies drive charger demand, particularly in densely populated corridors. Health Canada regulations and provincial mandates encourage zero-emission vehicle sales, necessitating robust charging networks. Metropolitan areas such as Toronto and Vancouver are focal points for new installations, integrating workplace and public charging solutions.
California
California's aggressive zero-emission vehicle (ZEV) mandates and consumer incentives create a concentrated market. The California Air Resources Board (CARB) regulations directly stimulate EV sales and infrastructure investment. Silicon Valley and the greater Bay Area lead in innovative charging deployments, including advanced Level 2 and DC fast charging solutions.
Quebec
Quebec's strong EV adoption policies, including significant provincial rebates, foster a dedicated charging ecosystem. Hydro-Québec supports the expansion of public charging networks, leveraging the province's abundant renewable energy. Montreal and Quebec City are experiencing substantial growth in charging station density, catering to a rapidly growing EV fleet.
North America EV Charging Stations Market Key Industry Players
Network expansion and standardization efforts dominate the current North American EV charging landscape. The market exhibits an evolving structure, with dedicated charging network operators competing alongside automotive manufacturers. Strategic archetypes include proprietary network providers, public charging specialists, and integrated hardware/software solution vendors. Geographic expansion and technology integration are primary competitive moves driving market evolution.
Public charging specialists and proprietary network providers exemplify the market's diverse approaches. ChargePoint, for instance, represents a broad-based network operator with installations across various site types in North America. Tesla, meanwhile, anchors the proprietary network model, leveraging its Supercharger infrastructure for its vehicle owners. Electrify America occupies a position as a key player in high-power DC fast charging corridors across the United States and Canada.
| Leading Market Players |
|---|
| Electrify America |
| EV Connect |
| ChargePoint |
| AmpUp |
| Shell Recharge |
| Blink Charging |
| EVgo |
| FLO |
| Tesla |
| Others |
Cost & Logistics Intelligence
NACS standardization, while simplifying hardware design, simultaneously reshapes cost economics for manufacturers and concentrates supply chain power towards a unified connector ecosystem. This shift impacts component sourcing and pricing dynamics across the North American market.
Pricing Analysis
Network operator markups often reflect the level of service and convenience offered, influencing pay-as-you-go and subscription-based models. Price differentiation stems from charging speed, with DC Fast Chargers commanding higher rates, and bundled software services. Pricing pressure stems from stringent NEVI program requirements for transparent pricing and reliability, driving down per-kilowatt-hour costs for public charging. Commercial fleet operators exhibit the highest price sensitivity, seeking cost-effective bulk charging solutions.
Supply Chain Analysis
Skilled labor scarcity in North American manufacturing hubs for power electronics and high-voltage components presents a key supply chain constraint. Supply concentration for critical components like power semiconductors and battery management systems draws heavily from China and Mexico. Raw material dependencies include lithium, copper, and rare earth elements for charger components. Single-source vulnerability for advanced power electronics poses a structural risk. Distribution runs through a mix of direct sales to large network operators and indirect channels via electrical equipment distributors across the United States and Canada.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American EV charging market represents a geographic-arbitrage play, as favorable regulatory environments and public funding in the United States offer different investment profiles compared to Canada's robust provincial incentives.
For Market Incumbents: Anchor existing network reliability and software integration to meet stringent NEVI uptime requirements and maintain user trust. Consolidate market share through strategic acquisitions of smaller regional networks, particularly in areas with high EV adoption. The threat of inconsistent permitting processes across jurisdictions requires proactive engagement with local authorities. Certification investment in new hardware for NACS compatibility serves as a critical lever for future growth.
For New Entrants and Emerging Players: Begin with targeted deployment in underserved rural areas and commercial fleet depots, where competition remains lower. The medium and heavy-duty vehicle charging segment represents the most penetrable market due to its emerging infrastructure needs. A go-to-market angle focused on Charging-as-a-Service (CaaS) models can lower upfront costs for site hosts and accelerate adoption in multi-unit dwellings. Focus on interoperable software solutions to attract a broader user base.
For Investors and Strategic Acquirers: Valuations sit cheapest among hardware manufacturers with proprietary power management technologies and smaller regional network operators. Long-term viability over a 5-10 year window hinges on successful grid integration capabilities and Vehicle-to-Grid (V2G) technology. Acquisition targets should include companies specializing in advanced software platforms for energy management and grid services. Practitioners should monitor NACS adoption rates across major automakers for early signals of market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Standardize NACS across product lines | Simplifies user experience across North America, accelerating EV adoption rates. |
| Invest in V2G-enabled charger development | Creates new revenue streams for fleet operators through energy market participation. |
| Expand DC Fast Charger network in underserved corridors | Addresses critical gaps in transportation infrastructure, supported by federal funding. |
| Implement CaaS models for commercial fleets | Lowers upfront capital barriers for businesses adopting electric vehicles. |
| Enhance remote diagnostic and repair capabilities | Improves charger uptime and reliability, meeting NEVI program requirements. |
Research Approach
Coverage spans the United States and Canada, with primary inputs from each region informing market dynamics and forecast assumptions. The analysis combines in-depth primary interviews with EV network operators, utility planning engineers, automotive OEMs, and commercial property developers. Secondary validation draws from NEVI program guidelines, EPA emissions data, state and provincial EV mandates, and industry association reports. A robust bottom-up and top-down triangulation approach ensures data consistency.
Rate-of-change decomposition quantifies market shifts across the analysis window by segmenting demand drivers and supply-side capabilities. The analytical framework models market dimensions including charger type, installation site, connector standard, charging network, and regional EV adoption rates. Compound annual growth rates were derived from historical data analysis and projected infrastructure buildout. Key forecast inputs include national EV sales forecasts and government incentive programs.
Several conditions sit outside the modeled scope, including unforeseen global economic downturns or rapid shifts in energy policy. Forecasts reflect assumptions regarding regulatory stability and technological progression. Grid capacity constraints and raw material price volatility represent specific risk factors that could revise future projections. Practitioners should monitor major automaker commitments to NACS and significant utility infrastructure investments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
United States Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Smart EV Charger Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Solar-Based Electronic Vehicle Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Global EV Charging Piles Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
Electric Vehicle Battery Charger Market
Electric Vehicle Charging
Global Automotive Charging System Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
Battery Swap Station Market