
 Global Smart Energy Meters Market | 2026-2036
Global Smart Energy Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Energy Meters Market Outlook
Chinese meter manufacturing is consolidating as domestic producers scale automated assembly lines for IoT-enabled units. Landis+Gyr leverages its Swiss engineering heritage to dominate European utility tenders with precision metering platforms. Itron Inc. sustains North American market presence through deep utility software integration alongside hardware supply.
Smart energy meters are precision measurement devices that record electricity, gas, or water consumption at intervals of one hour or less and communicate data via embedded RF or power-line carrier modules to central systems for billing and grid management. These instruments enable demand-response programs, outage detection, and real-time load balancing across distribution networks. IoT-enabled product types command expanding share as utilities prioritize two-way communication and remote disconnect capabilities over basic digital registers. Residential end users anchor volume demand, though industrial installations generate disproportionate margin pools due to complex multi-tariff configurations and power quality monitoring requirements.
The EU Green Deal and F-Gas Regulation shape product design mandates across Europe, while the EPA and state-level public utility commissions in the United States enforce interoperability standards and data privacy protocols for AMI deployments. China's GB standards and MIIT directives accelerate domestic substitution of foreign meter platforms while prescribing communication protocol compatibility. Stakeholders must monitor evolving cybersecurity certification requirements as grid-edge device attack surfaces expand alongside connected meter penetration.
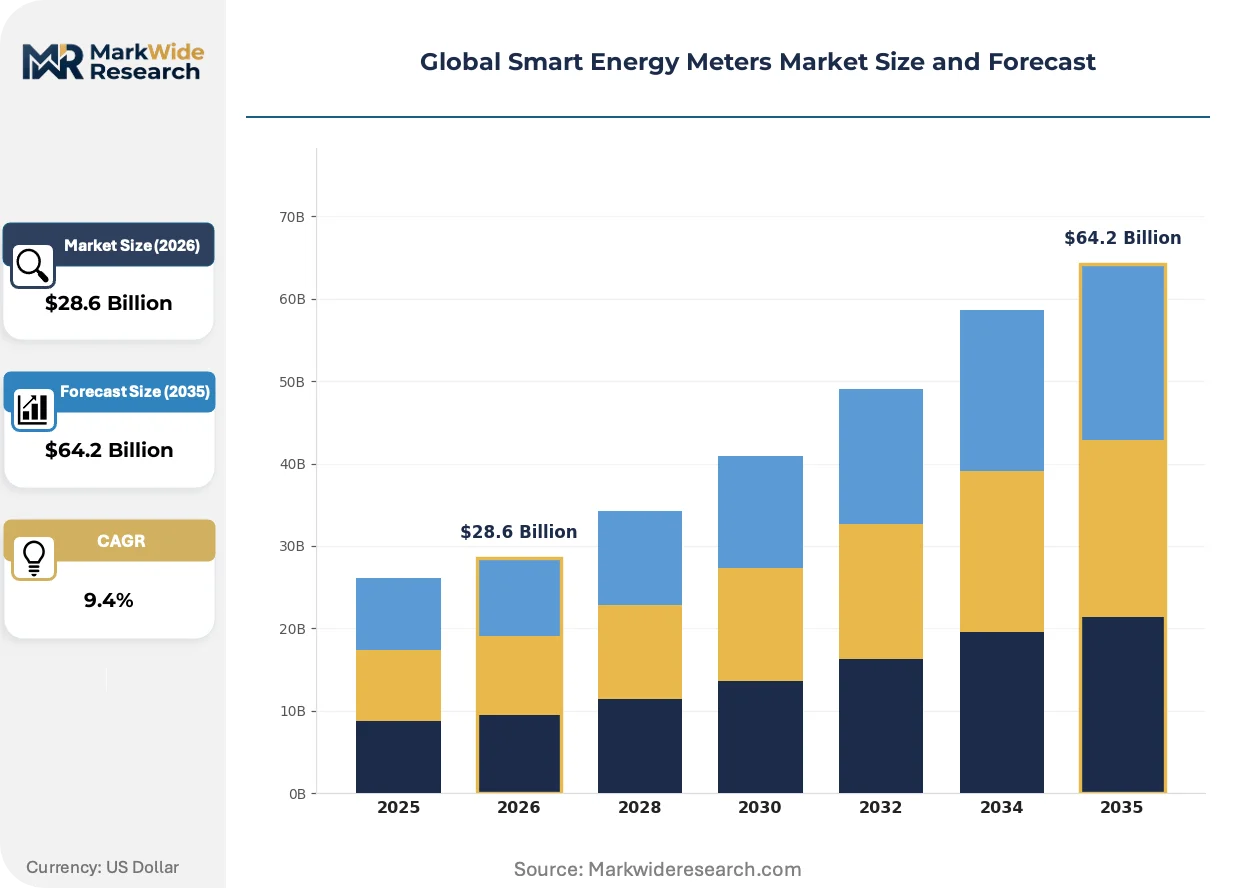
Market Dynamics
AMI deployment timelines are compressing as utilities face simultaneous pressure from decarbonization mandates and grid-edge electrification loads, forcing capital allocation trade-offs between meter hardware and software platforms.
Growth Catalysts
- EU Green Deal mandates:Member states must install smart meters covering 80% of consumers by 2027, creating regulatory pull for two-way communication devices.
- Industrial microgrids:Manufacturing clusters in Germany and India deploy sub-metering networks to isolate power quality disturbances and optimize demand charges.
- NB-IoT protocol adoption:Cellular LPWAN modules are displacing proprietary RF mesh networks in urban density zones, reducing infrastructure capital intensity.
Market Restraints
- Semiconductor supply concentration:RF transceiver and metrology chip fabrication concentrates in Taiwan and South Korea, exposing meter OEMs to allocation volatility.
- F-Gas Regulation compliance costs:EU-mandated phase-down of SF6 in switchgear adjacent to metering points requires design requalification and material substitution.
- AMI capital intensity:Full-stack deployments demand simultaneous investment in head-end systems, communication infrastructure, and meter hardware, stretching utility balance sheets.
Strategic Opportunities
- India's RDSS scheme:The central government's results-linked distribution reform program unlocks smart metering tenders across 27 states with pre-qualified vendor pools.
- EV load disaggregation:Residential meters with embedded NILM algorithms capture emerging revenue streams from vehicle-to-grid participation and time-of-use arbitrage.
- Cloud-native MDM platforms:Software-as-a-service meter data management displaces on-premise legacy systems, opening subscription revenue models for hardware suppliers.
Industry Challenges
- Cybersecurity certification timelines:IEC 62351 and regional grid code security audits extend product launch cycles by 8-14 months for new platform introductions.
- Interoperability testing complexity:Multi-vendor AMI ecosystems require protocol conformance validation across DLMS/COSEM, IEEE 2030.5, and utility-specific extensions.
- Workforce transition gaps:Field technician pools trained on electromechanical meter replacement lack competencies for RF commissioning and firmware-over-the-air troubleshooting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Energy Meters Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Digital, IoT-enabled, Smart Communication End User: Residential, Commercial, Industrial, Utilities Technology: RFID, Zigbee, GPRS, PLC Installation Type: New Installation, Replacement, Upgrade, Retrofit |
| Companies Covered | Landis+Gyr, Itron Inc., Siemens AG, Schneider Electric SE, Honeywell International Inc., Sagemcom, ABB Ltd., Kamstrup A/S, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Energy Meters Market Strategic Shifts
Edge intelligence migration is redistributing computational load from centralized data centers to meter-class devices, enabling real-time grid services that were previously latency-constrained by backhaul networks.
AI-driven anomaly detection is absorbing pattern recognition workloads previously executed in cloud-based meter data management systems. German distribution system operators deploy these capabilities to identify transformer overload risks before SCADA alerts trigger. The shift is compressing response windows for demand-response events from fifteen-minute settlement intervals to sub-minute dispatch signals.
CSRD disclosure requirements are mandating granular energy traceability for Scope 2 emissions accounting. Large industrial consumers in France and the Netherlands now require meter-level timestamped certificates to validate renewable energy procurement claims. This regulatory layer is forcing AMI vendors to embed cryptographic verification modules and immutable audit logs.
Integrated energy service bundling is displacing standalone meter procurement. Spanish and Italian utilities now contract hardware, installation, and analytics as unified outcomes rather than capital purchases. The model concentrates vendor selection authority within procurement functions that previously separated meter buying from software licensing.
Global Smart Energy Meters Market Segmentation
Smart energy meter segmentation reveals distinct technology maturity curves and capital deployment patterns across utility infrastructure cycles. Product specifications, communication protocols, and installation contexts determine procurement economics and vendor selection criteria.
Product Type:
Communication capability and embedded processing power define the product hierarchy, separating legacy registers from grid-edge intelligence platforms.
- IoT-enabled:Two-way communication modules with remote disconnect and firmware-over-the-air capabilities dominate tender specifications. German distribution operators and Indian state discoms prioritize these units for demand-response integration and outage management.
- Smart Communication:Advanced metering infrastructure endpoints with DLMS/COSEM protocol stacks and cellular LPWAN connectivity command premium positioning. Chinese utilities deploy these at scale for real-time load balancing across provincial grids.
- Digital:Basic electronic registers without networked telemetry serve residual replacement cycles and budget-constrained deployments in secondary cities.
- Electromechanical:Rotating disk technology persists only in legacy asset bases awaiting full AMI conversion, with manufacturing volumes concentrated in price-sensitive procurement corridors.
Mature deployment sits with Digital meters in legacy replacement programs. Newer deployment is concentrated in IoT-enabled units with embedded cybersecurity modules.
End User:
Consumption scale and tariff complexity create divergent technical requirements across customer classes.
- Utilities:Bulk procurement of AMI endpoints for system-wide deployment drives volume economics. State-owned discoms in India and municipal operators in Germany negotiate multi-year framework agreements with integrated software provisioning.
- Industrial:Multi-tariff configurations with power quality monitoring and sub-metering for microgrid isolation generate disproportionate margin contribution. Manufacturing clusters in Gujarat and Bavaria deploy these for demand charge optimization.
- Residential:Single-phase units with NILM capability for EV load disaggregation represent the volume anchor, with Chinese meter OEMs scaling automated assembly for cost compression.
- Commercial:Mid-scale three-phase installations with time-of-use billing and tenant sub-allocation serve retail and office building portfolios.
Margin concentration sits with Industrial configurations. Volume expansion is climbing the fastest in Residential segments under EU Green Deal mandates and India's RDSS scheme.
Technology:
Communication protocol selection determines infrastructure capital intensity and geographic suitability for meter networks.
- PLC:Power-line carrier transmission leverages existing distribution wiring, reducing dedicated communication infrastructure spend. Dense urban deployments in Chinese tier-1 cities exploit this for rapid AMI rollout without RF spectrum coordination.
- Zigbee:Mesh networking protocols with IEEE 802.15.4 physical layer enable neighborhood area network formation for localized data concentration. European utilities favor these for interoperability with home area network devices.
- GPRS:Cellular backhaul via legacy 2G/3G networks persists in rural coverage zones where mesh density proves uneconomical.
- RFID:Passive identification for asset tracking and field inventory management rather than continuous telemetry, serving supplementary utility workflows.
Protocol standardization sits with PLC deployments. Cellular migration is expanding most quickly as NB-IoT modules displace proprietary RF mesh in urban density zones.
Installation Type:
Deployment context shapes procurement bundling and vendor service obligations across meter lifecycle stages.
- New Installation:Greenfield AMI deployment with integrated head-end systems and communication infrastructure accompanies grid extension in rapidly urbanizing districts. Chinese smart city initiatives and Indian rural electrification programs drive tender volume.
- Replacement:Electromechanical-to-digital conversion cycles in mature European markets create predictable hardware refresh demand with standardized technical specifications.
- Upgrade:Communication module retrofits and firmware enhancements extend functional life of existing digital registers, stretching utility capital planning horizons.
- Retrofit:Adapter kits and enclosure modifications enable communication capability addition to legacy meter bases with minimal field labor.
Procurement scale sits with New Installation programs. Upgrade activity is gaining share fastest as utilities prioritize software-defined functionality over hardware replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polycrystalline silicon feedstock from Xinjiang and Inner Mongolia underpins Chinese meter manufacturing scale. German precision engineering clusters supply metrology components for European AMI rollouts. Taiwanese semiconductor fabrication concentrates RF transceiver supply for cellular-enabled units.
China
State Grid Corporation procures 50 million smart meters annually through centralized tenders. MIIT directives mandate domestic substitution of foreign communication modules by 2026. Shenzhen and Hangzhou host automated assembly lines scaling IoT-enabled unit production for provincial grid operators.
Germany
Distribution system operators face 80% smart meter coverage deadlines under EU Green Deal mandates. F-Gas Regulation compliance drives SF6 phase-down in switchgear adjacent to metering points. Bavarian industrial clusters deploy sub-metering networks for manufacturing power quality isolation.
United States
Investor-owned utilities balance AMI capital allocation between meter hardware and grid-edge software platforms. EPA and state public utility commissions enforce interoperability standards and data privacy protocols. Texas and California lead deployment volume through municipal operator frameworks and IOU consolidation programs.
India
State discoms tender 25 million smart meters under the RDSS results-linked reform scheme. CEA technical standards prescribe DLMS/COSEM protocol compatibility for national interoperability. Gujarat and Maharashtra manufacturing clusters assemble units for 27-state deployment programs.
Japan
TEPCO and regional utilities accelerate AMI replacement of legacy electromechanical registers. METI efficiency targets drive demand-response integration for commercial building portfolios. Kanto and Kansai metropolitan areas concentrate deployment density for time-of-use tariff pilots.
Global Smart Energy Meters Market Competitive Environment
Global majors compete with regional champions across software-hardware integration depth and utility relationship tenure. Market structure tilts toward consolidated procurement authority as state-owned discoms and municipal operators consolidate vendor selection through multi-year framework agreements. Three archetypes dominate: Swiss-German precision engineering houses, North American software-integrated hardware suppliers, and Chinese state-linked volume manufacturers. Competitive moves concentrate on cloud-native MDM platform partnerships and automated assembly line scaling for cost compression.
Within the precision engineering tier, Landis+Gyr and Kamstrup A/S exemplify European heritage positioning for utility tender dominance. Among diversified industrial conglomerates, Siemens AG and ABB Ltd. occupy positions spanning metering hardware through grid automation portfolios. Honeywell International Inc. represents the building-to-grid integration archetype, leveraging HVAC and energy management adjacencies for commercial segment penetration.
| Leading Market Players |
|---|
| Landis+Gyr |
| Itron Inc. |
| Siemens AG |
| Schneider Electric SE |
| Honeywell International Inc. |
| Sagemcom |
| ABB Ltd. |
| Kamstrup A/S |
| General Electric |
| Others |
Value Chain & Pricing Dynamics
RF commissioning specialists concentrated in Shenzhen and Hangzhou compress labor-cost differentials between premium Swiss-engineered units and economy-tier Chinese assemblies. This workforce geography widens pricing spreads as European utilities absorb premium service bundles while Indian state discoms strip out installation support for bare-hardware tenders.
Pricing Analysis
Warranty and firmware-over-the-air maintenance bundling separates premium-tier European tenders from unbundled hardware procurement in cost-sensitive corridors. Three-tier pricing structure across premium, standard, and economy levels reflects DLMS/COSEM certification depth and cybersecurity module inclusion. Cost compression in economy tiers is intensifying because Indian RDSS scheme vendors compete on stripped-down specifications. Residential utilities in South Asia exhibit highest price sensitivity; German distribution system operators show least sensitivity given EU Green Deal compliance deadlines.
Supply Chain Analysis
Container freight volatility from Shanghai to Hamburg and Los Angeles strains working capital cycles for meter OEMs sourcing metrology chips. RF transceiver fabrication concentrates in Taiwan and South Korea; polycrystalline silicon feedstock draws from Xinjiang and Inner Mongolia. Single-source vulnerability in 40nm semiconductor node supply exposes deployment timelines to foundry allocation decisions. Distribution runs through state-owned discom framework agreements and municipal operator consolidated procurement windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart energy meter sector occupies a technology-transition phase as NB-IoT cellular modules displace proprietary RF mesh networks. Legacy power-line carrier deployments face accelerated obsolescence from LPWAN protocol standardization.
For Market Incumbents: Cement software-hardware integration depth through cloud-native MDM platform partnerships that lock utility customers into subscription revenue streams. Defend against Chinese state-linked volume manufacturers by embedding IEC 62351 cybersecurity certification as a non-negotiable tender requirement. Prioritize automated assembly line scaling in Eastern European manufacturing clusters to match Chinese unit economics.
For New Entrants and Emerging Players: The 40-60% price-point gap between premium Swiss-German and economy Chinese tiers opens white-space targeting for mid-market cellular-enabled units. India's 27-state RDSS tender pipeline represents the most penetrable geography given pre-qualified vendor pool turnover and interoperability mandate enforcement gaps. Pursue EV load disaggregation software licensing as a service-layer wedge rather than competing on meter hardware margins.
For Investors and Strategic Acquirers: Re-rating potential sits with software-integrated hardware suppliers given cloud-native MDM platform adoption curves and recurring revenue multiple expansion. Long-term viability favors vendors with backward integration into metrology semiconductor sourcing and firmware development capabilities. Watch NB-IoT module cost curves as the inflection signal for cellular-native meter penetration tipping points.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native MDM Platform Deployment | Utility software procurement shifts from perpetual licenses to SaaS subscriptions, concentrating vendor selection authority. |
| NB-IoT Communication Module Integration | Cellular LPWAN protocols displace proprietary RF mesh in urban density zones, reducing infrastructure capital intensity. |
| IEC 62351 Cybersecurity Certification Investment | Grid-edge device security audits extend product launch cycles but create tender barriers for uncertified competitors. |
| Automated Assembly Line Scaling | Chinese OEMs compress unit economics through robotic meter production, forcing European precision engineering houses to match. |
| EV Load Disaggregation Algorithm Development | NILM-enabled meters capture vehicle-to-grid revenue streams from time-of-use arbitrage and demand-response participation. |
Study Parameters
Document review covered utility tender databases, regulatory filings with FERC and state public utility commissions, and CEA technical standards, complemented by interviews with utility planning officers, AMI procurement leads at state-owned discoms, smart meter OEM product managers, and grid operators. Secondary validation drew from EIA deployment data, IEA smart grid investment trackers, and SEC filings of publicly traded meter manufacturers. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment forecasts.
Segmented outputs across product type, end user, communication technology, and installation context were generated through the projection horizon. CAGRs were derived from regression analysis against AMI capital expenditure cycles and regulatory mandate timelines. Forecast inputs incorporated NB-IoT module cost trajectories, EU Green Deal compliance deadlines, and India's RDSS scheme disbursement velocity.
Inputs from utility procurement officers and discom planning departments were available through the study window; gaps in real-time tender award disclosure introduce uncertainty bands around deployment timing assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Residential Water Submetering Market
Smart Meters
Smart Meters Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
Gas Meters Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
Solar Meter Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
Europe Smart Meter Data Management Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Smart Electric Meter Market
Smart Meters
Single-Phase Anti-Theft Meter Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Watt Meter Market
Smart Meters
North America Gas Meter Market
Smart Meters
Digital Gas Meter Market